
 North America Metal Finishing Market | 2026-2036
North America Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Finishing Market Analytics
Aftermarket service revenue is tilting toward specialized refurbishment and recoating of industrial components rather than one-time transactional finishing. OC Oerlikon Management AG leverages its thermal spraying technology portfolio to anchor long-term service contracts with aerospace OEMs. Techmetals, Inc. competes through its specialization in precision electroplating for medical and electronics applications. C. Uyemura & Co. Ltd extends its position in electroless nickel chemistry across the automotive supply chain.
North America metal finishing encompasses chemical and physical surface modification processes applied to metallic substrates to enhance corrosion resistance, wear properties, electrical conductivity, or aesthetic appearance, typically operating within thickness tolerances of 0.1 to 50 microns depending on the deposition method. Electroplating remains the dominant product category by volume, though powder coating captures expanding share in automotive styling and architectural applications where volatile organic compound restrictions limit liquid coating options. Physical vapor deposition represents the fastest-growing technology segment, driven by electronics miniaturization and aerospace demand for high-performance thermal barrier coatings. Protective applications command the largest share of end-use value, while functional coatings for electronics and semiconductor fabrication equipment represent the highest-margin application area.
The EPA enforces hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants that directly constrain hexavalent chromium plating operations, while OSHA mandates worker exposure limits that increase compliance costs for traditional electroplating shops. The Canadian Environmental Protection Act and corresponding provincial regulations in Ontario and Quebec impose parallel restrictions on heavy metal discharges, creating cross-border harmonization pressure on process chemistry suppliers. Stakeholders must monitor the trajectory of trivalent chromium substitution economics and the emerging commercial viability of atomic layer deposition for next-generation electronics substrates.
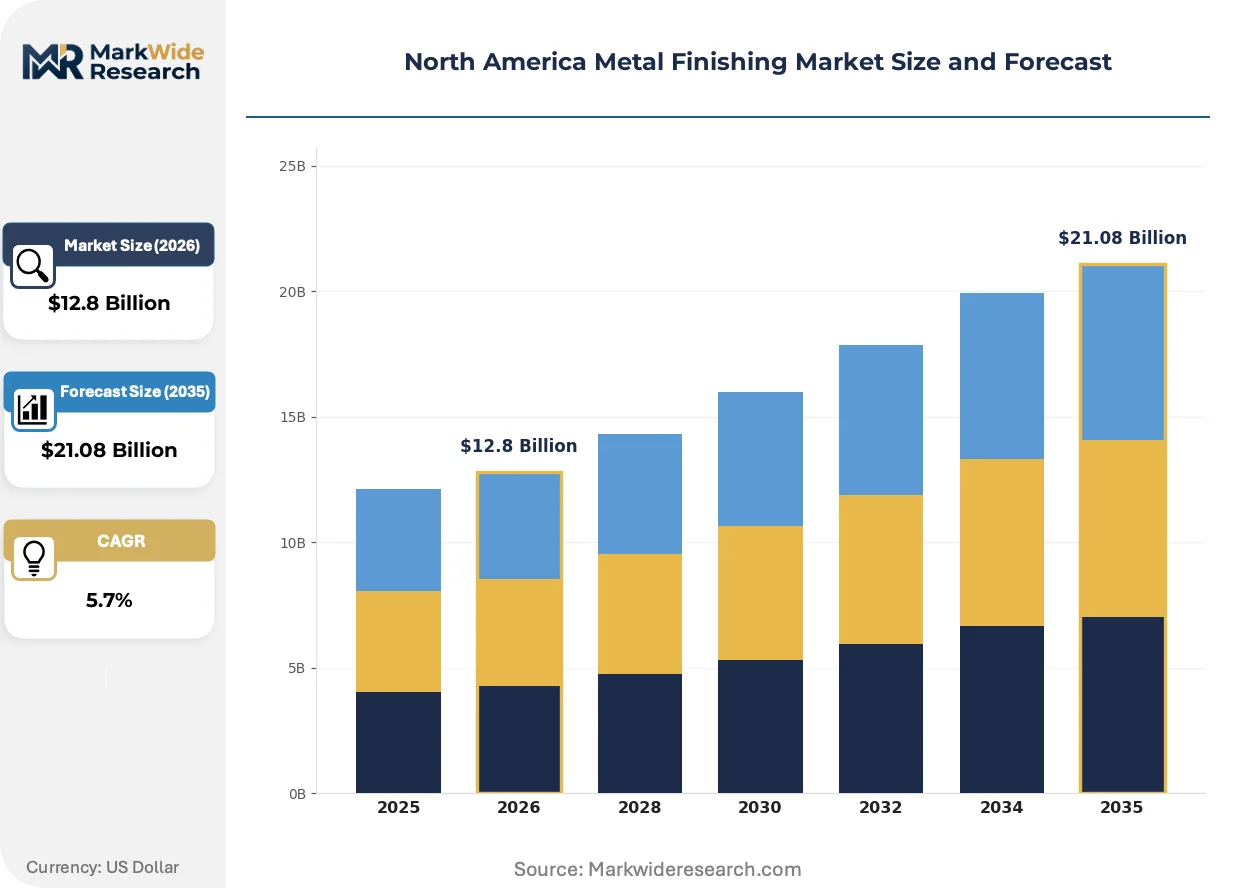
Market Dynamics
The EPA's National Emission Standards for Hazardous Air Pollutants is compressing hexavalent chromium capacity across the Great Lakes manufacturing corridor, forcing a rapid chemistry transition that is reshaping capital allocation and supplier qualification timelines for aerospace and automotive finishers.
Growth Catalysts
- Trivalent chromium chemistry:Ohio and Michigan plating shops are retooling lines to meet EPA hazardous air pollutant mandates, creating replacement demand for process equipment and chemical formulations.
- Physical vapor deposition:Aerospace OEMs in the United States and Canada are qualifying thermal barrier coatings for turbine blades, expanding high-margin functional coating volumes.
- Electronics miniaturization:Semiconductor fabrication equipment manufacturers are specifying atomic layer deposition for wafer handling components, opening precision finishing applications.
Market Restraints
- Specialized chemical supply concentration:Electroless nickel chemistry production concentrates among Japanese and German formulators, exposing North American finishers to transoceanic logistics volatility.
- Hexavalent chromium conversion capex:Small and mid-size electroplating shops in Ontario and Quebec face six-figure line retrofits to achieve OSHA worker exposure compliance.
- Powder coating technical ceiling:Thickness uniformity limitations below 25 microns restrict powder coating penetration into precision electronics applications.
Strategic Opportunities
- Mexico automotive supplier base:Underpenetrated metal finishing capacity in Guanajuato and Querétaro creates geographic expansion potential for US-based thermal spray and electroless nickel specialists.
- IRA clean manufacturing incentives:US Department of Energy funding for industrial decarbonization supports trivalent chromium and water-based coating process investments.
- Medical device coating convergence:Combination antimicrobial and lubricious coating specifications for surgical instruments are converging biocompatible polymer and electroless nickel technologies.
Industry Challenges
- Hexavalent chromium process expertise attrition:Veteran platers with deep tank chemistry knowledge are retiring faster than trivalent chromium training programs can replenish qualified technicians.
- NADCAP accreditation timelines:Aerospace finishing suppliers face 12-to-18-month audit cycles to achieve or renew special process certifications, constraining new entrant qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Finishing Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroplating, Anodizing, Powder Coating, Plating Technology: Chemical, Physical Vapor Deposition, Thermal Spraying, Electroless End User: Aerospace, Automotive Components, Electronics, Industrial Machinery Application: Decorative, Protective, Functional, Automotive Styling |
| Companies Covered | OC Oerlikon Management AG, Techmetals, Inc., C. Uyemura & Co. Ltd, American Tinning & Galvanizing Co., LEC Metal Finishing, Honeywell International Inc., Sequa, Modern Industries, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Finishing Market Evolving Landscape
Process chemistry innovation and regulatory chemistry mandates are compressing traditional finishing technology lifecycles, while buyer consolidation in aerospace and automotive is forcing service model reinvention across the value chain.
Atomic layer deposition for electronics substrates is hybridizing semiconductor and metal finishing process knowledge. Equipment suppliers are integrating precursor delivery systems with traditional plating line controls. Michigan and California electronics manufacturers are piloting these systems for copper seed layer applications, compressing the boundary between wafer fabrication and component finishing.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is accelerating hexavalent chromium phaseouts in the United States. Chrome plating shops in Ohio and Pennsylvania are exhausting their compliance timelines. Aerospace OEMs are dual-qualifying trivalent chromium and electroless nickel alternatives for landing gear and fastener specifications, shifting specification authority from platers to prime contractors.
Aftermarket service contracts are displacing transactional job shop relationships in aerospace and power generation. OC Oerlikon Management AG and similar thermal spray specialists are capturing ten-year refurbishment agreements for turbine components. This bundling concentrates volume with qualified suppliers and marginalizes small platers without NADCAP accreditation, with the shift most visible in the Great Lakes aerospace corridor spanning Ontario, Michigan, and Ohio.
North America Metal Finishing Market Segmentation
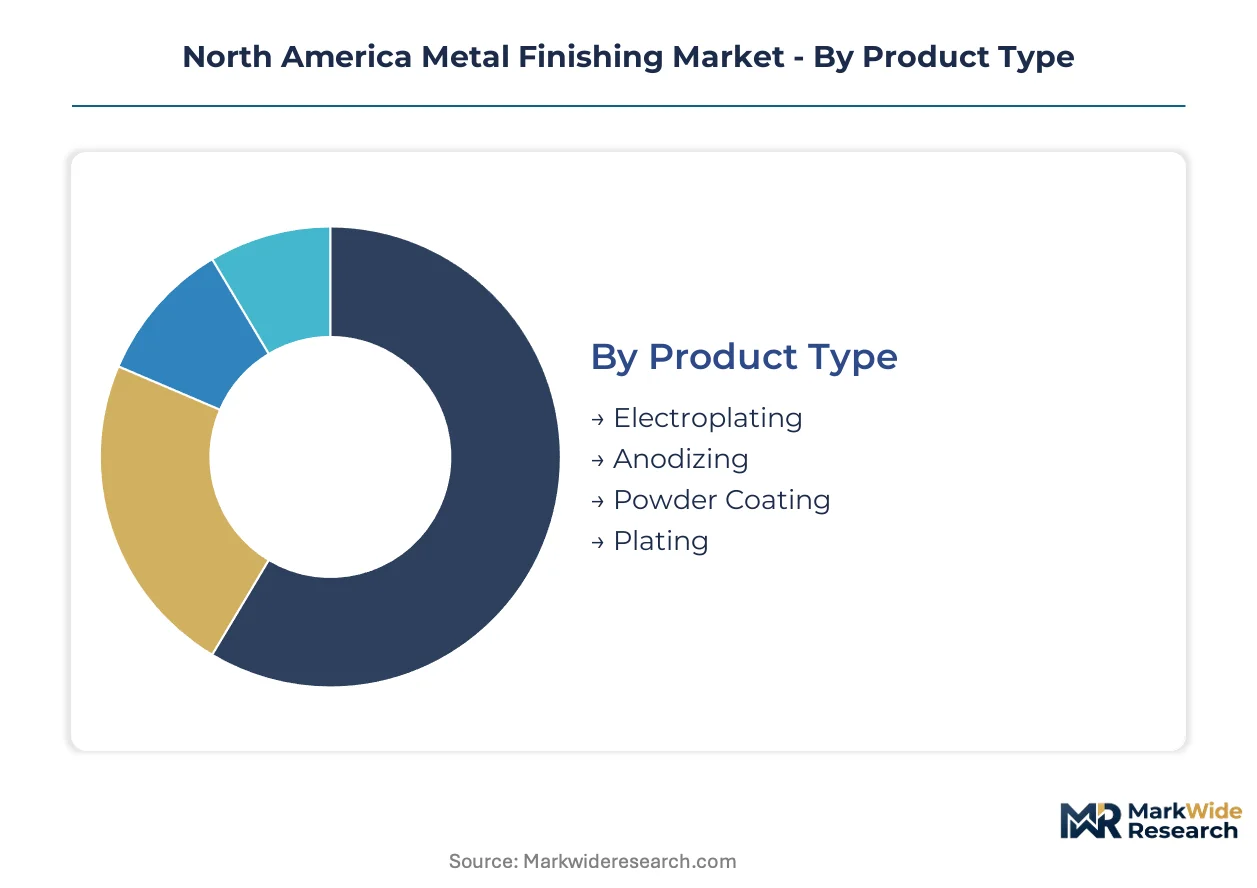
North American metal finishing segments diverge sharply by capital intensity and regulatory exposure. Product type and technology choices determine compliance burden, while end-user concentration in Great Lakes aerospace and Mexican automotive assembly shapes geographic deployment.
Product Type:
Mature processes dominate installed base volume, though emerging alternatives capture specification shifts driven by EPA mandates.
- Electroplating:Tank-based electrodeposition of metals onto conductive substrates achieves thickness control within 0.1 to 50 microns. Demand concentrates across Ohio and Michigan job shops serving automotive fastener and connector specifications, with trivalent chromium conversion now mandatory for hexavalent chromium lines.
- Powder Coating:Thermoset or thermoplastic powders applied electrostatically and cured thermally eliminate volatile organic compound emissions. Automotive styling applications in Michigan and Ontario assembly plants are expanding share as liquid coating restrictions tighten, though thickness uniformity below 25 microns limits electronics penetration.
- Anodizing:Electrochemical oxide layer formation on aluminum substrates enhances corrosion and wear resistance.
- Plating:General category encompassing barrel, rack, and continuous reel-to-reel deposition methods.
Electroplating retains volume leadership; powder coating holds the steepest expansion curve.
Technology:
Cost tier stratification separates commodity chemical processes from capital-intensive physical deposition systems.
- Physical Vapor Deposition:Vacuum-based evaporation or sputtering of target materials produces dense, adherent coatings with exceptional thickness uniformity. Aerospace OEMs in the United States and Canada are qualifying thermal barrier coatings for turbine blades, expanding high-margin functional volumes beyond traditional plating economics.
- Electroless:Autocatalytic reduction deposits uniform metal layers without external electrical current, critical for complex geometries. Semiconductor fabrication equipment manufacturers in California and Texas are specifying electroless nickel for wafer handling components, opening precision finishing applications.
- Chemical:Conversion coating and passivation processes modify surface chemistry without metallic deposition.
- Thermal Spraying:Molten or semi-molten material projection builds thick protective coatings for wear and corrosion resistance.
Chemical processes retain volume leadership; physical vapor deposition holds the steepest expansion curve.
End User:
Customer type concentration creates divergent margin profiles, with aerospace and electronics commanding qualification premiums over automotive commodity work.
- Aerospace:NADCAP-accredited finishing for turbine components, landing gear, and airframe structures demands traceable process control. Manufacturers in the Great Lakes corridor spanning Ontario, Michigan, and Ohio are expanding procurement of protective surface treatments, with dual-qualification of trivalent chromium and electroless nickel alternatives accelerating.
- Electronics:Miniaturization trends drive atomic layer deposition and precision electroless applications for semiconductor fabrication equipment. Michigan and California manufacturers are piloting copper seed layer systems, compressing boundaries between wafer fabrication and component finishing.
- Automotive Components:High-volume plating and coating for powertrain, chassis, and exterior trim applications.
- Industrial Machinery:Protective and repair coatings for heavy equipment, pumps, and valves.
Automotive components retain volume leadership; electronics holds the steepest expansion curve.
Application:
Margin structure separates specification-driven functional work from price-sensitive decorative finishing.
- Protective:Corrosion and wear resistance coatings dominate end-use value across aerospace, automotive, and industrial machinery. EPA enforcement of National Emission Standards for Hazardous Air Pollutants is compressing hexavalent chromium capacity across the Great Lakes manufacturing corridor, forcing chemistry transitions that reshape capital allocation.
- Functional:Electrical conductivity, thermal management, and tribological properties command highest-margin positioning. Electronics and semiconductor fabrication equipment specifications for atomic layer deposition and precision electroless nickel concentrate in California and Texas technology corridors.
- Decorative:Aesthetic finishing for consumer goods, architectural elements, and automotive trim.
- Automotive Styling:Exterior and interior appearance treatments with specific color and gloss requirements.
Protective applications retain volume leadership; functional coatings hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive finishers in Mexico operate on thin margins where powder coating volumes drive price competition, while aerospace suppliers in the Great Lakes corridor command qualification premiums that insulate them from commodity pressure.
United States
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is forcing hexavalent chromium conversions across Ohio and Michigan plating shops. The Department of Energy's IRA clean manufacturing incentives are accelerating trivalent chromium and water-based coating investments. The Great Lakes manufacturing corridor spanning Ohio, Michigan, and Illinois concentrates aerospace and automotive finishing demand.
Canada
The Canadian Environmental Protection Act imposes parallel heavy metal discharge restrictions that harmonize cross-border process chemistry standards. Ontario's provincial regulations in Toronto-Windsor corridor job shops are accelerating electroless nickel substitution timelines. NADCAP-accredited finishers in Ontario are capturing expanded procurement from US aerospace OEMs seeking dual-qualified suppliers.
Mexico
Automotive assembly expansion in Guanajuato and Querétaro is outpacing local metal finishing capacity, creating supply gaps for thermal spray and electroless nickel services. Mexican environmental regulations under SEMARNAT are tightening effluent standards for plating operations near industrial zones. US-based specialists are establishing satellite operations in the Bajío Region to serve tier-one automotive suppliers.
North America Metal Finishing Market Competitive Landscape
Capability concentration sits with NADCAP-accredited specialists serving aerospace primes; scale advantage sits with diversified chemical and equipment suppliers serving cross-industry volumes. The market structures around three tiers: integrated thermal spray specialists with long-term service contracts, precision electroplating job shops with medical and electronics qualifications, and commodity powder coating operators serving automotive styling. Dominant competitive moves include geographic expansion into underpenetrated Mexican automotive corridors and chemistry portfolio diversification away from hexavalent chromium.
Within the integrated thermal spray tier, OC Oerlikon Management AG exemplifies the long-term contract model anchoring aerospace refurbishment relationships. Among precision electroplating specialists, Techmetals, Inc. occupies a position representing medical and electronics qualification depth. Japanese chemical formulators including C. Uyemura & Co. Ltd anchor the electroless nickel supply tier serving semiconductor fabrication equipment specifications.
| Leading Market Players |
|---|
| OC Oerlikon Management AG |
| Techmetals, Inc. |
| C. Uyemura & Co. Ltd |
| American Tinning & Galvanizing Co. |
| LEC Metal Finishing |
| Honeywell International Inc. |
| Sequa |
| Modern Industries |
| Linde plc |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Japanese and German electroless nickel chemistry imports compresses margin structures for Ohio and Michigan plating shops while simultaneously forcing geographic diversification of chemical sourcing. This dual pressure widens pricing spreads between NADCAP-accredited aerospace finishers and commodity automotive job shops, reshaping procurement patterns across the Great Lakes manufacturing corridor.
Pricing Analysis
Aftermarket service contracts now anchor lifetime value capture for thermal spray specialists serving aerospace refurbishment cycles. Pricing stratifies across premium, standard, and economy tiers based on NADCAP accreditation status and chemistry portfolio breadth, with trivalent chromium conversion costs intensifying margin pressure on small electroplating operators. Aerospace OEMs exhibit lowest price sensitivity due to specification lock-in, while Mexican automotive suppliers face acute cost compression from liquid coating restrictions.
Supply Chain Analysis
Upstream feedstock concentration in Japan and Germany for electroless nickel chemistry creates transoceanic dependency for North American finishers. Specialty chemical formulators, nickel salts, and chromium compounds feed from concentrated Asian and European production hubs, exposing the supply chain to single-source vulnerability on critical process inputs. Distribution runs through regional chemical distributors and direct OEM relationships, with qualified supplier lists tightening under EPA hazardous air pollutant enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American metal finishing sits at an early-cycle expansion inflection, with EPA-mandated hexavalent chromium phaseouts creating replacement demand for trivalent chemistry and electroless nickel alternatives. This regulatory tailwind accelerates specification authority shifts from job shops to prime contractors, opening consolidation opportunities for qualified specialists.
For Market Incumbents: Pre-empt chemistry transition bottlenecks by securing long-term electroless nickel supply agreements with Japanese formulators before competitor qualification timelines compress. Invest in NADCAP accreditation expansion into underpenetrated Mexican automotive corridors to defend against emerging thermal spray specialists. Vertical integration into precursor chemistry blending insulates margin pressure from transoceanic logistics volatility. For New Entrants and Emerging Players: Build out electroless nickel capacity in Guanajuato and Querétaro to capture supply gaps in Mexico's expanding automotive assembly base. Target medical device coating convergence opportunities where antimicrobial polymer and lubricious electroless specifications remain undersupplied. Lead with combination technology offerings rather than single-process commodity positioning to bypass entrenched supplier relationships. For Investors and Strategic Acquirers: EPA's National Emission Standards for Hazardous Air Pollutants enforcement reshapes the acquisition landscape by stranding hexavalent chromium-dependent assets and elevating trivalent-qualified operations. Long-term viability centers on chemistry portfolio diversification and aerospace certification depth rather than scale alone. Watch NADCAP audit queue lengths as the inflection signal—backlogs exceeding 18 months indicate severe supply constraint and pricing power accumulation for accredited finishers.| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chromium Line Conversion | EPA hazardous air pollutant compliance secures operational continuity for Ohio and Michigan plating shops. |
| Mexico Geographic Expansion | Guanajuato satellite operations capture automotive supplier base growth outpacing local finishing capacity. |
| Long-term Service Contract Anchoring | Ten-year turbine component refurbishment agreements concentrate volume with qualified thermal spray specialists. |
| Electroless Nickel Chemistry Backward Integration | In-house precursor blending reduces dependency on Japanese and German formulator supply chains. |
| NADCAP Accreditation Investment | Special process certification opens procurement channels to US and Canadian aerospace OEM dual-qualification programs. |
Research Methodology
A spread of perspectives from plating shop operators, aerospace procurement managers, chemical formulator technical directors, and EPA compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews across the Great Lakes manufacturing corridor with secondary validation from SEC filings of publicly traded finishing specialists, customs data on electroless nickel chemistry imports, and OSHA enforcement records. Bottom-up capacity modeling triangulated against top-down aerospace and automotive production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, technology tier, end-use industry, and geographic production cluster. CAGRs were derived from installed base replacement cycles, regulatory compliance timelines, and specification shift elasticity in aerospace procurement. Industry-specific inputs incorporated EPA enforcement trajectory modeling and NADCAP accreditation pipeline data.
Stress conditions across trivalent chromium conversion capex requirements, electroless nickel supply disruption scenarios, and Mexican environmental regulation tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on chemistry substitution economics and prime contractor qualification behavior. Cross-checking against Department of Energy industrial decarbonization grant disbursement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper Wire Market
Metals
Ferrosilicon Magnesium Market
Metals
Lithium Tungstate Market
Metals
Steel Salvage Drums Market
Metals
Nickel Sulfate Market
Metals
Ferro Vanadium Market
Metals
High Purity Lead Market
Metals
Rare Earth Metals Market
Metals
Global Wire Rods Market
Metals
Precious Metals Wire Market
Metals
Platinum Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
TMCP Steel Market
Metals
Amorphous Metal Cores Market
Metals
Stainless Steel Round Bar Market
Metals
Silver Enamel Market