
 Russia Metal Fabrication Market | 2026-2036
Russia Metal Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Metal Fabrication Market Outlook
Aluminum is decoupling from traditional steel specifications in Russian structural applications as lightweighting pressures reshape product economics. Severstal-Metiz leverages captive wire-drawing capacity to dominate welding consumables for Arctic infrastructure. NLMK sustains flat-rolled dominance through continuous annealing investments at its Lipetsk complex. Magnitogorsk Iron and Steel Works anchors heavy-gauge fabrication for railcar and boiler segments through integrated slab-to-coil conversion.
Metal fabrication encompasses the cutting, bending, welding, machining, and assembling of raw metal materials into finished components or structures, typically operating with tolerances between 0.1 mm and 2 mm depending on the process and end-use specification. The discipline serves as the physical backbone of industrial manufacturing, converting sheet, plate, tube, and structural sections into capital equipment, vehicles, vessels, and built infrastructure. Welding equipment and cutting tools together command the largest product-type revenue pools, reflecting Russia's sustained investment in pipeline construction and heavy machinery refurbishment. Robotics adoption within fabrication technology segments accelerates fastest among technology categories, though plasma cutting retains installed-base dominance across shipyards in the Baltic and Black Sea basins. Construction and automotive manufacturing applications absorb the majority of output volume, with aerospace engineering representing a higher-margin but smaller-scale demand pocket.
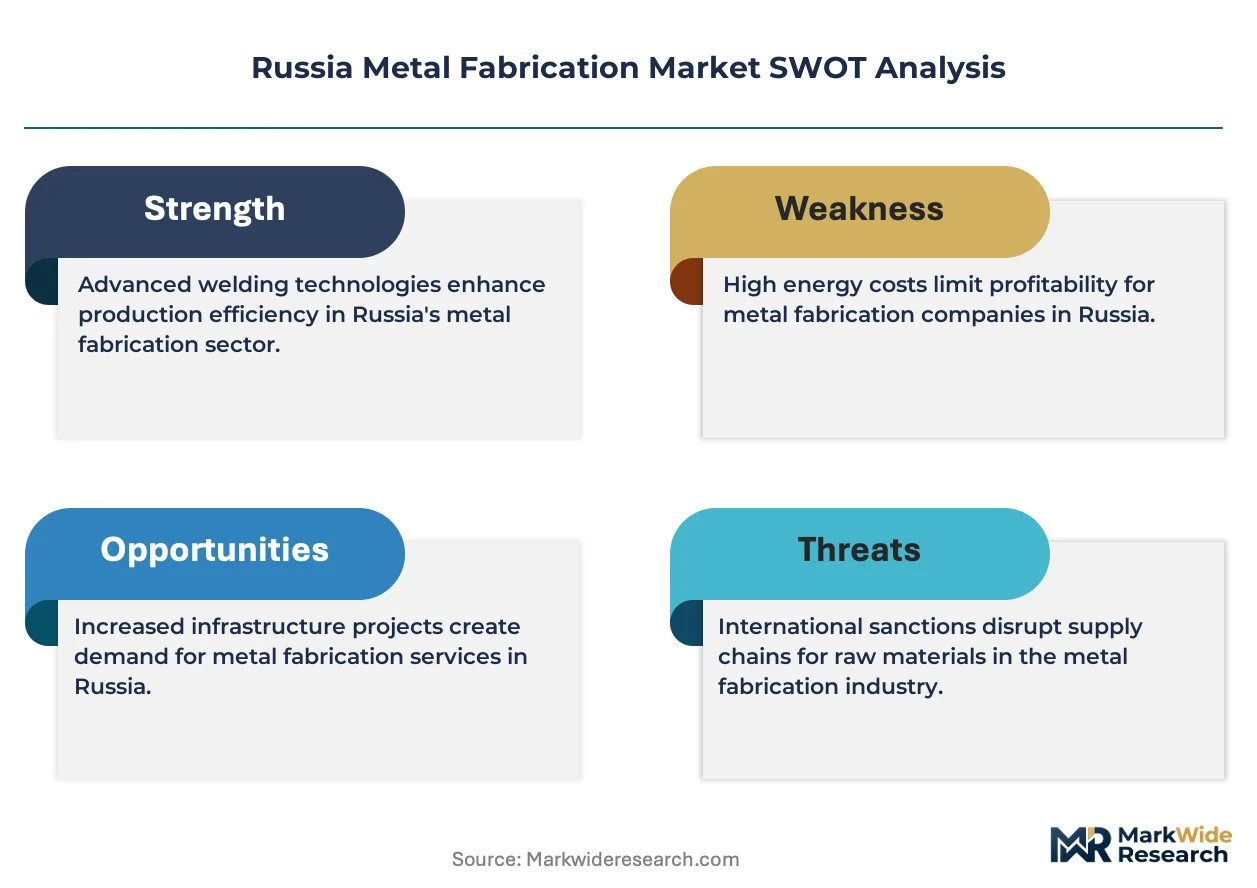
Russia's Technical Regulation on Safety of Machinery (TR CU 010/2011) and GOST-R certification requirements govern product-market access for imported fabrication equipment, while Rostekhnadzor oversees pressure-vessel welding qualifications that directly shape contractor eligibility. The country's import-substitution regime, reinforced by Central Bank of Russia financing directives for domestic capital goods procurement, redirects demand toward local equipment builders and service networks. Stakeholders must monitor how sanctions-driven supply chain reconfiguration affects spare-part availability for European and Asian machine tools already deployed across Russian fabrication floors.
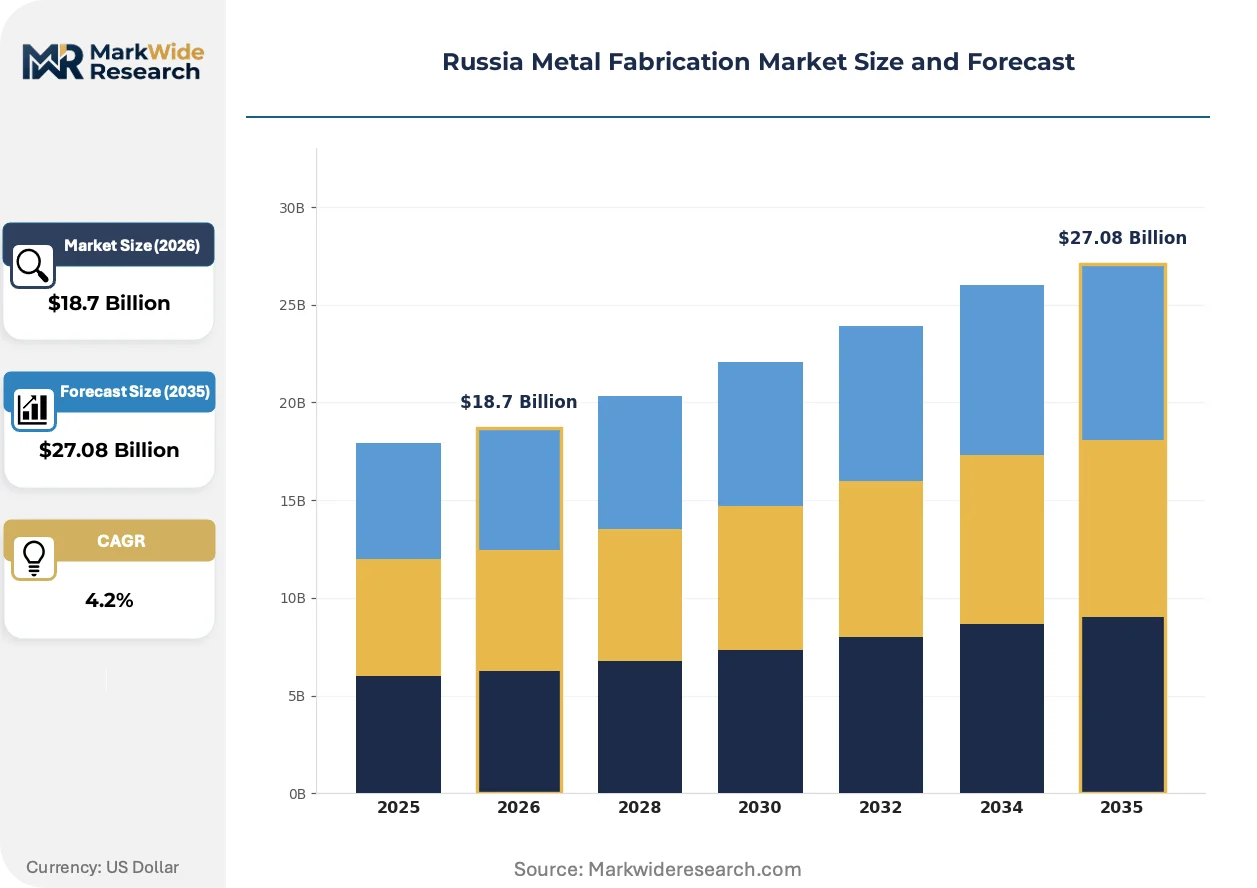
Market Dynamics
Import-substitution mandates under sanctions have restructured procurement rules across Russian fabrication floors, redirecting capital flows toward domestic equipment builders and fragmenting established supply relationships with European and Asian machine-tool suppliers.
Growth Catalysts
- Arctic infrastructure buildout:Pipeline and port construction in the Far East drives demand for heavy-gauge welding systems and cryogenic-grade consumables. Shipbuilders in Vladivostok and Murmansk anchor this expansion.
- TR CU 010/2011 machinery safety framework:Technical regulations governing product-market access create compliance-based demand for certified domestic fabrication equipment, favoring local assembly over imports.
- Continuous annealing investments:Flat-rolled steel producers are upgrading coil processing lines to capture higher-margin automotive and appliance specifications previously served by imports.
Market Restraints
- Alloy input cost volatility:Nickel and molybdenum price swings compress margins for stainless and specialty steel fabricators serving chemical processing equipment.
- Spare-part supply concentration:European machine-tool components face sanctions-driven availability constraints, forcing extended maintenance cycles and cannibalization of existing assets.
- Plasma cutting technical ceiling:Thick-plate precision above 50 mm remains limited compared to laser-hybrid alternatives, constraining nuclear and pressure-vessel contractor eligibility.
Strategic Opportunities
- Chelyabinsk pipe-rolling cluster expansion:Underpenetrated capacity for large-diameter line pipe serving Central Asian export corridors offers white-space growth.
- Robotics-welding convergence:Articulated arm systems integrated with seam-tracking vision are opening automated fabrication in railcar and boiler segments previously resistant to capital investment.
- Central Bank of Russia financing directives:Preferential lending terms for domestic capital goods procurement create a structural tailwind for local equipment manufacturers.
Industry Challenges
- Welding engineer certification backlog:Rostekhnadzor qualification timelines for pressure-vessel contractors extend project mobilization by 4-8 months, constraining contractor pool elasticity.
- Legacy control system integration:Soviet-era machine tools with proprietary PLC architectures resist retrofit with modern MES and predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Metal Fabrication Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Equipment, Cutting Tools, Forming Machines, Finishing Tools Application: Construction, Automotive Manufacturing, Aerospace Engineering, Shipbuilding End User: Manufacturers, Contractors, Distributors, Service Providers Technology: Laser Cutting, Plasma Cutting, Waterjet Cutting, Robotics |
| Companies Covered | Severstal-Metiz, Novolipetsk Steel (NLMK), Magnitogorsk Iron and Steel Works, Lenmontag, Metalloinvest Management Company LLC, Mechel, Ruspolimet, Evraz Group, Public Joint Stock Company "Chelyabinsk Pipe-Rolling Plant", Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Metal Fabrication Market Strategic Shifts
Digital thread technologies and automated quality assurance are compressing fabrication tolerances while reshaping how Russian producers compete for sanctioned-market export opportunities.
Hybrid laser-arc welding is decentralizing thick-plate production from concentrated shipyard facilities to distributed mid-cap fabricators. Boiler and railcar manufacturers in the Ural industrial belt are piloting these systems at half the capital intensity of traditional submerged-arc lines. The technology is decentralizing geographic production gravity and enabling smaller shops to bid on pressure-vessel contracts previously reserved for integrated yards.
Russia's import-substitution regime, reinforced by Central Bank financing directives, now mandates domestic-content thresholds for state-funded fabrication projects. Industrial consequence includes forced localization of welding consumables and cutting-tool supply chains. Arctic infrastructure contractors face the steepest compliance burden, accelerating partnerships with captive wire-drawing and electrode manufacturers.
Buyer concentration among state-linked EPC firms is compressing supplier negotiation cycles and unbundling after-sales service from equipment contracts. Fabrication shops now procure maintenance parts through separate tender processes, fragmenting vendor relationships. This pattern is most visible in pipeline construction, where Transneft-linked contractors disaggregate capital expenditure from operational support agreements.
Russia Metal Fabrication Market Segmentation
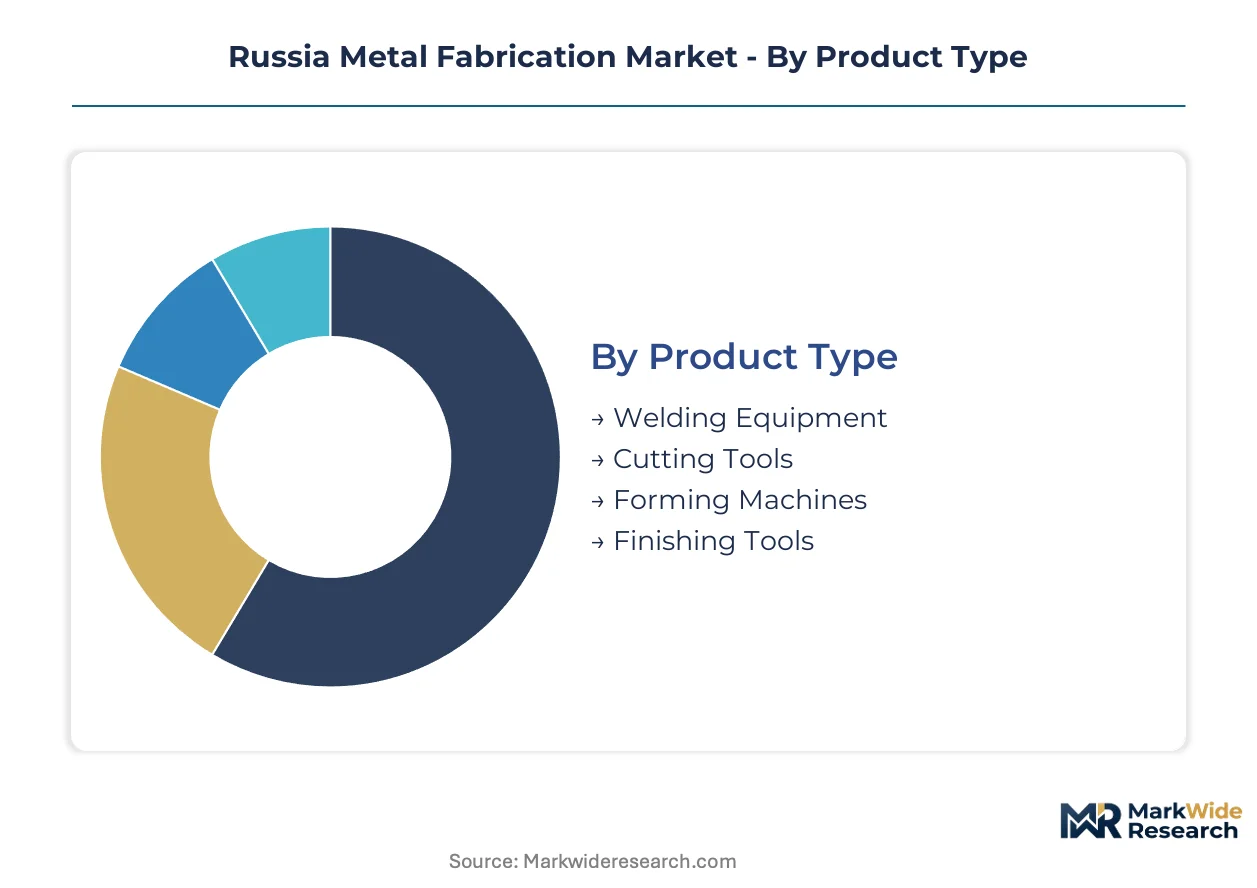
Segmentation in Russian metal fabrication reveals how sanctions-driven procurement rules fragment demand across equipment categories and user types. Each dimension carries distinct compliance burdens and localization requirements under the import-substitution regime.
Product Type:
Customization intensity varies sharply across this category, from standardized consumables to project-engineered forming lines.
- Welding Equipment:Systems span manual arc units through automated seam-tracking installations. Demand concentrates in Far East shipyards for cryogenic-grade pipeline construction, driven by Arctic infrastructure buildout and Rostekhnadzor certification requirements for pressure-vessel contractors.
- Cutting Tools:Plasma and oxy-fuel consumables dominate installed bases, though laser-hybrid systems gain traction for thick-plate precision. Chelyabinsk pipe-rolling clusters absorb high-volume plasma torch shipments for large-diameter line pipe production.
- Forming Machines:Press brakes and roll-forming lines serve railcar and boiler manufacturers in the Ural industrial belt.
- Finishing Tools:Grinding and surface preparation equipment support refurbishment cycles for Soviet-era machine tool fleets.
Leading the category by volume: Welding Equipment. Growing fastest: Cutting Tools.
Application:
Margin structures diverge across this category, from cost-competitive construction contracts to aerospace engineering premiums.
- Construction:Structural steel fabrication for commercial and residential buildings demands high-throughput cutting and welding systems. State-funded infrastructure projects in Moscow and St. Petersburg drive equipment procurement under domestic-content mandates.
- Automotive Manufacturing:Continuous annealing investments at Lipetsk and other flat-rolled complexes feed stamping and body-in-white fabrication. Lightweighting pressures accelerate aluminum-to-steel substitution in structural applications.
- Aerospace Engineering:Titanium and high-strength alloy fabrication for airframe and engine components operates at tighter tolerances than commercial segments.
- Shipbuilding:Baltic and Black Sea yards anchor plasma cutting demand, while Vladivostok facilities adopt advanced welding systems for ice-class vessel construction.
Construction claims the largest revenue pool. Aerospace engineering expands most quickly on a percentage basis.
End User:
Procurement authority concentrates differently across this category, from integrated manufacturers to fragmented contractor networks.
- Manufacturers:Steel mills and OEM fabricators with captive maintenance shops drive capital equipment purchases. NLMK and Severstal-Metiz anchor demand for high-volume welding consumables through backward-integrated supply chains.
- Contractors:State-linked EPC firms and Transneft-aligned pipeline builders disaggregate equipment from service contracts. Tender fragmentation forces separate procurement for spare parts and maintenance.
- Distributors:Regional equipment dealers face margin compression as manufacturers direct-sell to large accounts.
- Service Providers:Independent maintenance shops cannibalize European machine-tool assets for spare-part availability.
Manufacturers dominate capital expenditure. Contractors represent the fastest-expanding service revenue opportunity.
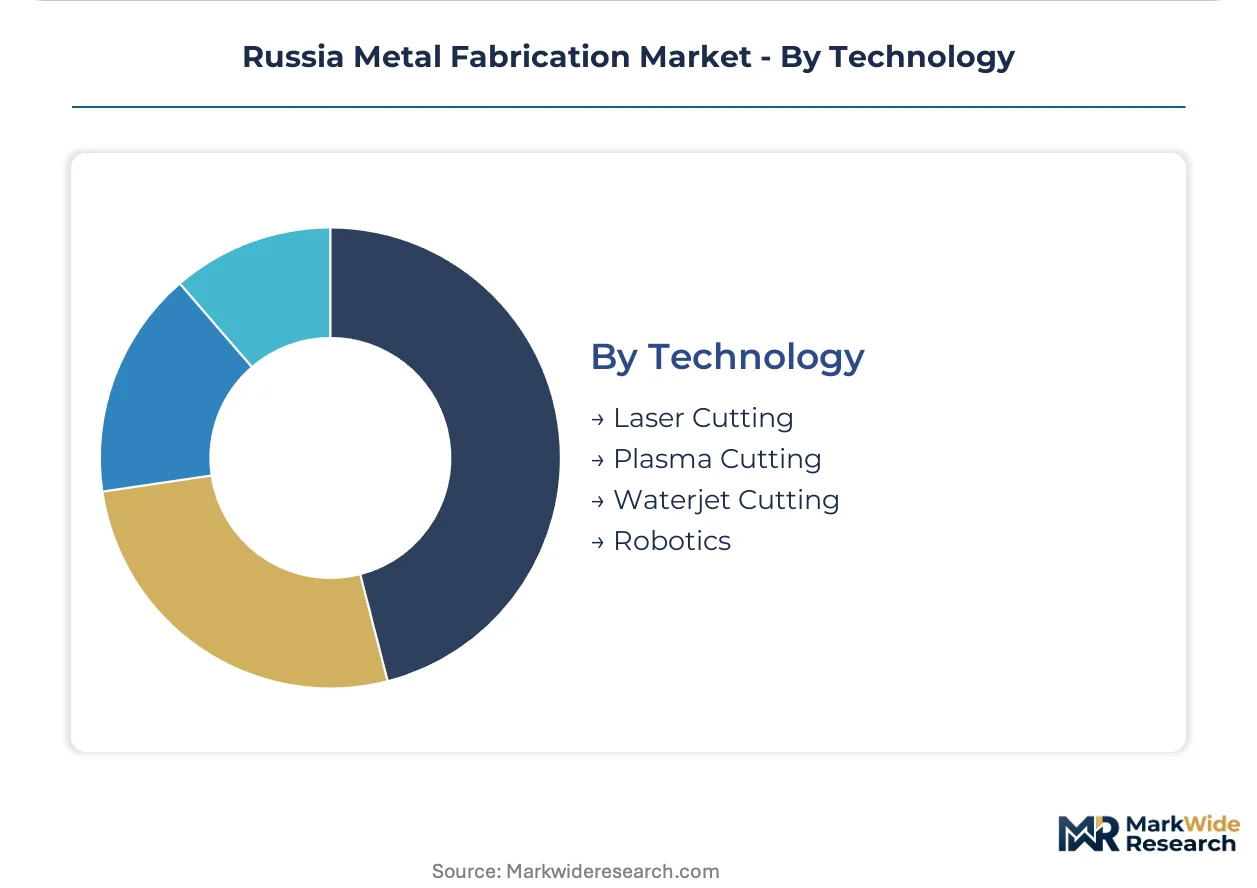
Technology:
Maturity gradients separate established plasma installations from emerging robotics adoption across Russian fabrication floors.
- Laser Cutting:Fiber and CO2 systems penetrate automotive and appliance specifications previously served by imports. Lipetsk flat-rolled investments integrate laser blanking for higher-margin coil processing.
- Plasma Cutting:Thick-plate dominance persists in shipyards despite technical ceilings above 50mm. Baltic and Black Sea basins retain installed-base concentration.
- Waterjet Cutting:Abrasive and pure-water systems serve specialty applications in aerospace and composite fabrication.
- Robotics:Articulated arm welding systems with seam-tracking vision automate railcar and boiler segments. Ural industrial belt pilot programs demonstrate half the capital intensity of submerged-arc lines.
Plasma Cutting maintains installed-base leadership. Robotics gains share fastest among technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for metal fabrication equipment concentrates in Russia's industrial belt regions, where state-funded infrastructure and import-substitution mandates redirect capital toward domestic supply chains. Chelyabinsk and the Ural Mountains anchor heavy-gauge production, while Far East shipyards drive advanced welding adoption for Arctic projects.
Central Russia
Lipetsk's flat-rolled steel complex sustains continuous annealing investments for automotive and appliance specifications. The Central Bank of Russia's financing directives for domestic capital goods procurement favor local equipment builders over imports. Moscow and St. Petersburg construction markets absorb structural steel fabrication under domestic-content mandates for state-funded projects.
Ural Federal District
Magnitogorsk anchors heavy-gauge fabrication for railcar and boiler segments through integrated slab-to-coil conversion. Rostekhnadzor oversees pressure-vessel welding qualifications that shape contractor eligibility across the region. Chelyabinsk's pipe-rolling cluster expands capacity for large-diameter line pipe serving Central Asian export corridors.
Far East
Vladivostok and Murmansk shipbuilders drive demand for cryogenic-grade welding systems and advanced consumables. Arctic infrastructure buildout for pipelines and ports requires heavy-gauge fabrication equipment with ice-class certifications. The region faces the steepest compliance burden for domestic-content thresholds under import-substitution rules.
Northwestern Federal District
Baltic Sea shipyards retain plasma cutting installed-base dominance despite technical ceilings above 50mm. St. Petersburg's industrial base supports refurbishment cycles for Soviet-era machine tool fleets. The region's fabrication shops cannibalize European assets for spare-part availability under sanctions-driven supply constraints.
Siberian Federal District
Krasnoyarsk and Irkutsk manufacturing centers serve resource extraction equipment markets with heavy fabrication capabilities. Legacy control systems with proprietary PLC architectures resist retrofit with modern MES platforms. Regional producers pilot robotics-welding convergence at capital intensities below traditional submerged-arc lines.
Russia Metal Fabrication Market Competitive Environment
Backward integration into welding consumables dominates the current landscape, with steel producers capturing margin pools previously held by independent suppliers. The market structure consolidates around integrated metals conglomerates with captive fabrication equipment divisions, mid-scale regional specialists serving state-linked EPC contractors, and emerging domestic equipment builders financed by preferential lending programs. Strategic archetypes include vertical metals-to-consumables integrators, geography-bound fabrication contractors, and state-supported capital goods assemblers. Capacity expansion and import-substitution partnerships represent the dominant competitive moves.
Among Russia-based metals conglomerates, Severstal-Metiz and Novolipetsk Steel occupy positions exemplifying the vertical integration archetype, while Magnitogorsk Iron and Steel Works anchors the heavy-gauge fabrication tier. These entities represent how captive wire-drawing and electrode manufacturing capabilities reshape competitive positioning under sanctions-driven procurement rules.
| Leading Market Players |
|---|
| Severstal-Metiz |
| Novolipetsk Steel (NLMK) |
| Magnitogorsk Iron and Steel Works |
| Lenmontag |
| Metalloinvest Management Company LLC |
| Mechel |
| Ruspolimet |
| Evraz Group |
| Public Joint Stock Company "Chelyabinsk Pipe-Rolling Plant" |
| Others |
Value Chain & Pricing Dynamics
State-linked EPC contractors and Transneft-aligned pipeline builders concentrate procurement authority, forcing equipment vendors toward project-based pricing with unbundled after-sales service. This buyer concentration compresses negotiation cycles and fragments vendor relationships across Russian fabrication floors.
Pricing Analysis
Volume-driven welding consumables trade at thin margins against premium-priced automated seam-tracking systems for cryogenic-grade applications. Price differentiation separates Rostekhnadzor-certified equipment from uncertified alternatives, with Arctic infrastructure contractors paying compliance premiums. Pricing pressure stems from alloy input cost volatility, particularly nickel and molybdenum swings in stainless fabrication. State-funded construction projects exhibit lowest price sensitivity, while independent regional distributors face margin compression from manufacturer direct-selling.
Supply Chain Analysis
Rostekhnadzor welding qualifications and TR CU 010/2011 certification requirements gate supply eligibility for pressure-vessel contractors. Equipment sourcing draws from domestic assembly plants in Central Russia, residual European component flows through third-country channels, and Asian machine-tool suppliers in China and South Korea. Spare-part availability constraints from sanctions-driven restrictions create single-source vulnerability for legacy European assets. Distribution runs through state-linked EPC tender processes that disaggregate capital expenditure from operational support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rostekhnadzor certification backlogs and welding engineer qualification timelines constrain contractor pool elasticity, propping pricing power for certified domestic equipment builders. Supply scarcity around qualified fabrication capacity sustains margin premiums across the analysis window.
For Market Incumbents: Cement backward integration into welding consumables and electrode manufacturing to capture margin pools from independent suppliers. Expand captive wire-drawing capacity at Far East facilities to serve Arctic infrastructure demand. Deepen Rostekhnadzor certification investment to defend against emerging domestic equipment assemblers financed by Central Bank preferential lending.
For New Entrants and Emerging Players: Enter via Chelyabinsk pipe-rolling cluster expansion for large-diameter line pipe capacity serving Central Asian export corridors. Target robotics-welding convergence in Ural railcar and boiler segments where capital intensity requirements sit below traditional submerged-arc lines. Pursue joint venture structures with state-linked EPC firms to secure procurement access under domestic-content mandates.
For Investors and Strategic Acquirers: The window for entry favors mid-scale regional specialists with established Rostekhnadzor contractor relationships and captive maintenance service networks. Acquisition targets should demonstrate backward-integrated consumables supply and proven execution on state-funded infrastructure projects. Watch for inflection in Central Bank financing directive enforcement intensity as signal for domestic equipment builder valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Welding Consumables | Captures margin pools from independent electrode suppliers under import-substitution procurement rules. |
| Rostekhnadzor Certification Investment | Unlocks pressure-vessel contractor eligibility and Arctic infrastructure project access. |
| Robotics-Welding Convergence Pilot | Halves capital intensity for railcar and boiler automation versus submerged-arc alternatives. |
| Far East Capacity Expansion | Positions for cryogenic-grade pipeline demand from Vladivostok and Murmansk shipbuilders. |
| Joint Venture with State-Linked EPC | Secures procurement channel access under fragmented tender processes separating capex from service. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Russia metal fabrication assessment. Primary interviews with plant engineers at steel mills, procurement leads at state-linked EPC contractors, maintenance directors at shipyards, and aftermarket service heads validated demand patterns. Bottom-up equipment shipment tracking and top-down steel consumption modeling were triangulated against Rostekhnadzor certification database trends.
Data-stream reconciliation across product type, application, technology, and end-user dimensions shaped the analytical framework. CAGRs were derived from equipment replacement cycles, continuous annealing investment pipelines, and Arctic infrastructure project announcements. Forecast inputs included welding engineer qualification timelines, Central Bank financing directive enforcement patterns, and plasma-to-laser-hybrid technology substitution curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sanctions escalation or spare-part supply disruption scenarios. Model assumptions reflect import-substitution regime durability and Rostekhnadzor certification capacity constraints. A model refresh is warranted upon material change in Central Bank domestic capital goods procurement financing terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Medical Metal Tubing Market
Metals
Titanium Market
Metals
Global Stretch Spring Wire Market
Metals
Crude Steel Market
Metals
Galvanizing Market
Metals
Titanium Mill Products Market
Metals
Aluminum Welding Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Europe Metal Service Centers Market
Metals
Ferro Aluminum Market
Metals
Trivalent Chromium Finishing Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Refined Nickel Market
Metals
Global Brazing Consumable Market
Metals
Powder Metallurgy Market
Metals
Metallurgical Silicon Market