
 Abrasion-Resistant Rubber Pipe Market | 2026-2036
Abrasion-Resistant Rubber Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasion-Resistant Rubber Pipe Market Analysis
Mining procurement teams are reorganizing vendor selection criteria toward total cost of ownership metrics rather than unit price alone. Trelleborg AB anchors its position through captive polymer compounding facilities in Sweden and Sri Lanka. Parker Hannifin competes by leveraging its distributed service network across Latin American extraction sites. ContiTech AG differentiates through proprietary NR/BR blend formulations optimized for high-solids slurry transport.
Abrasion-resistant rubber pipe consists of elastomeric tubes engineered with reinforced carcass layers, typically achieving Shore A hardness ratings of 60–85 and tensile strength exceeding 15 MPa to withstand particulate erosion in hydraulic conveying systems. Flexible pipes command the largest volume share in mining tailings and dredging operations where routing complexity demands bend radius compliance below 4× diameter. Composite pipes represent the fastest-expanding category as thermoplastic-lined constructions displace pure rubber in oil sands processing where aromatic hydrocarbon exposure degrades standard compounds.
EPA effluent limitations under the Clean Water Act constrain discharge piping specifications in US mining and construction drainage, while REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons reshape compound formulations for European supply chains. China's GB/T standard system mandates pressure testing protocols that exceed legacy ASTM D2230 requirements, creating certification friction for imported assemblies. Stakeholders must monitor evolving MEE enforcement patterns around tailings dam construction standards and assess whether captive compounding investments offset regulatory compliance costs in targeted geographies.
Market Dynamics
Compound reformulation under REACH and EPA emissions rules is forcing rubber processors to rebuild supply chains around low-aromatic feedstocks, fundamentally altering cost structures and supplier qualification timelines across the value chain.
Growth Catalysts
- Ore Processing Intensification:Mining operators in Australia and Chile are expanding procurement of reinforced slurry pipes as extraction volumes rise. This drives replacement cycles and specification upgrades in high-wear applications.
- REACH Annex XVII:Polycyclic aromatic hydrocarbon restrictions in Europe are accelerating compound innovation. Formulators investing in compliant blends capture preferential supplier status with EU-based mining equipment OEMs.
- Hydraulic Conveying Expansion:Tailings dam construction standards under China's MEE enforcement patterns are mandating higher-performance discharge piping. Domestic coal operations in Shanxi Province represent concentrated demand pull.
Market Restraints
- Natural Rubber Price Volatility:NR/BR blend formulations depend on plantation supply concentrated in Southeast Asia. Weather disruptions and labor availability constrain input cost predictability for compounders.
- Captive Compounding Concentration:Vertically integrated polymer facilities in Sweden and Sri Lanka limit third-party compounder access to proprietary formulations. This geographic supply concentration creates qualification bottlenecks for new market entrants.
- Thermoplastic Substitution:Composite pipe constructions with thermoplastic liners are displacing pure rubber in oil sands processing. Aromatic hydrocarbon exposure degrades standard elastomer compounds, compressing addressable market in Canadian extraction.
Strategic Opportunities
- Western Australia Pilbara District:Iron ore expansion in this region outpaces local pipe manufacturing capacity. Import substitution partnerships with established compounders create channel entry points.
- Sensor-Embedded Monitoring:Integration of wear-detection fibers with reinforced carcass layers enables predictive replacement scheduling. Mining operators in Chile are piloting these systems to reduce unplanned downtime.
- US EPA Effluent Limitations:Clean Water Act constraints on mining discharge specifications are tightening. Compounders with pre-qualified low-leach formulations can accelerate vendor approval with US procurement teams.
Industry Challenges
- GB/T Certification Friction:China's pressure testing protocols exceed legacy ASTM D2230 requirements. Foreign manufacturers face extended timeline and documentation burden to qualify imported assemblies.
- Compounder Talent Scarcity:Formulation chemistry expertise for abrasion-resistant blends sits with aging technical workforces in Germany and Japan. Knowledge transfer to emerging production facilities lags capacity expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abrasion-Resistant Rubber Pipe Market |
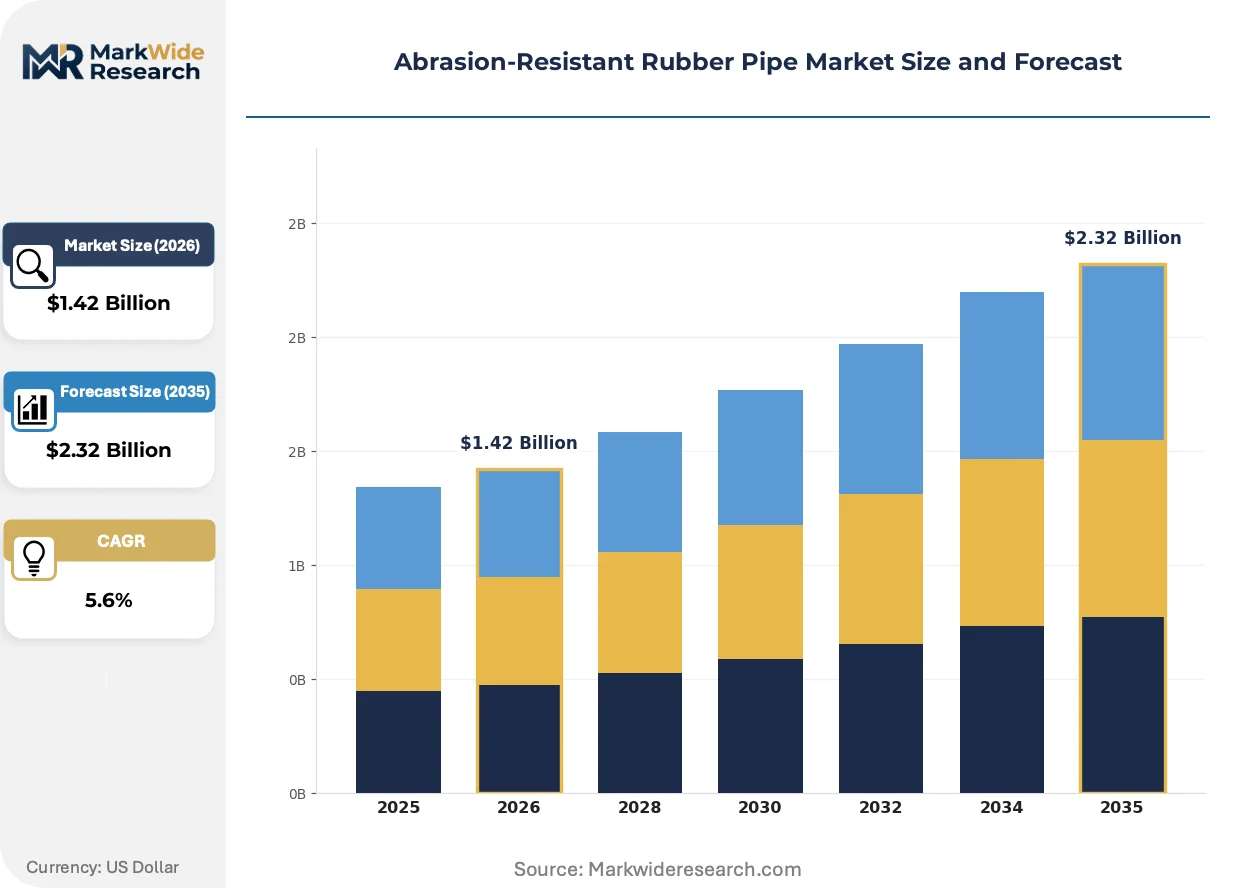
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pipes, Rigid Pipes, Composite Pipes, Reinforced Pipes Application: Mining, Oil & Gas, Construction, Water Management End User: Industrial, Commercial, Agricultural, Municipal Material Grade: High-Grade Rubber, Medium-Grade Rubber, Standard Rubber, Specialty Compounds |
| Companies Covered | Manuli Hydraulics, Trelleborg AB, Parker Hannifin, Bridgestone, ContiTech AG, Gates Corporation, Alfagomma Group, Semperit AG Holding, Eaton Hydraulics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasion-Resistant Rubber Pipe Market Emerging Trajectories
Thermoplastic-lined composite constructions and embedded sensor systems are fragmenting traditional rubber pipe specifications, while procurement teams reorganize vendor selection around total cost metrics rather than unit pricing alone.
Reinforced carcass designs with integrated fiber-optic wear monitoring are bifurcating the flexible pipe segment. Mining operators in Western Australia's Pilbara district are adopting these systems at pilot scale for tailings transport. The technology is bifurcating supplier tiers into sensor-integrated solution providers versus commodity pipe fabricators, compressing margin pools for undifferentiated manufacturers.
EPA effluent limitations under the Clean Water Act are constraining discharge piping specifications in US mining and construction drainage. Compounders must reformulate to meet leachate thresholds while maintaining Shore A hardness ratings of 60–85 for abrasion resistance. US-based procurement teams are consolidating vendor lists around pre-qualified suppliers with established EPA compliance documentation, favoring incumbents with regulatory affairs capabilities.
Vendor selection criteria among mining procurement teams are reorganizing toward total cost of ownership metrics. Unit price alone no longer determines contract awards; lifecycle replacement frequency and installation labor requirements now dominate evaluation frameworks. This behavioral shift is most visible in Chilean copper extraction operations, where procurement departments have established cross-functional committees combining engineering, finance, and supply chain functions for pipe specification decisions.
Abrasion-Resistant Rubber Pipe Market Segmentation
Segmentation in abrasion-resistant rubber pipe markets exposes divergent supply chain configurations across product architectures and end-use requirements. Procurement patterns vary sharply between domestic specification-driven demand and export-oriented volume plays.
Product Type:
Geographic concentration differs markedly across product architectures, with flexible and composite pipes tracking export-led mining demand while rigid variants serve localized infrastructure.
- Flexible Pipes:Elastomeric tubes with reinforced carcass layers achieve Shore A hardness of 60–85 and bend radii below 4× diameter. Demand concentrates in Western Australia's Pilbara iron ore district and Chilean copper extraction, where routing complexity around tailings infrastructure drives specification. Mining operators in these regions are expanding procurement as ore processing intensifies.
- Composite Pipes:Thermoplastic-lined constructions displace pure rubber in oil sands processing where aromatic hydrocarbon exposure degrades standard compounds. Canadian extraction operators are piloting these systems fastest, though supply chains remain concentrated among compounders with captive polymer facilities in Sweden and Sri Lanka.
- Rigid Pipes:Fixed-configuration installations dominate municipal water management and construction drainage within domestic markets.
- Reinforced Pipes:Multi-layer carcass designs serve high-pressure slurry transport in established mining corridors.
Flexible pipes command the established base. The steepest expansion runs through composite constructions.
Application:
Cost tier stratification separates premium-specification mining applications from price-sensitive construction and water management segments.
- Mining:Slurry transport, tailings discharge, and dredging operations demand tensile strength exceeding 15 MPa and specialized NR/BR blend formulations. Australia's Pilbara district and China's Shanxi Province coal belt represent concentrated demand clusters where procurement teams reorganize vendor selection toward total cost of ownership metrics.
- Oil & Gas:Aromatic hydrocarbon exposure in oil sands processing mandates compound reformulation toward low-aromatic blends under EPA emissions rules and REACH Annex XVII restrictions.
- Construction:Drainage and site dewatering applications prioritize unit price over lifecycle performance in fragmented procurement.
- Water Management:Municipal and industrial discharge specifications face tightening EPA effluent limitations under the Clean Water Act.
Mining applications absorb the premium tier. Construction and water management segments compete on delivered cost.
End User:
Customer type determines specification authority, with industrial operators driving compound innovation while municipal buyers follow standardized procurement.
- Industrial:Mining conglomerates and oil sands processors specify custom formulations with integrated wear-monitoring fibers. Chilean copper extraction operations have established cross-functional procurement committees combining engineering, finance, and supply chain functions.
- Commercial:Construction contractors and rental equipment fleets prioritize availability and installation labor efficiency over compound sophistication.
- Agricultural:Irrigation and drainage applications represent dispersed, price-sensitive demand with limited specification leverage.
- Municipal:Water authority procurement follows legacy ASTM D2230 requirements, though China's GB/T standard system mandates pressure testing protocols that exceed these benchmarks.
Industrial end users command formulation development. Municipal and agricultural segments follow standardized specifications.
Material Grade:
Supply concentration around proprietary compounding expertise creates qualification bottlenecks for high-grade and specialty formulations.
- High-Grade Rubber:Optimized NR/BR blends achieve tensile strength exceeding 15 MPa with Shore A hardness precision for severe slurry erosion. Trelleborg AB and ContiTech AG anchor supply through captive facilities, constraining third-party compounder access.
- Specialty Compounds:Low-aromatic formulations compliant with REACH Annex XVII polycyclic aromatic hydrocarbon restrictions and EPA emissions rules require rebuilt supply chains. Formulators investing in compliant blends capture preferential supplier status with EU-based mining equipment OEMs.
- Medium-Grade Rubber:Balanced performance-cost positioning serves construction drainage and secondary mining applications.
- Standard Rubber:Commodity formulations face compression from thermoplastic substitution in oil sands processing.
High-grade rubber maintains the specification anchor. Specialty compounds are climbing the fastest as regulatory compliance reshapes procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish compounders export proprietary NR/BR blends to Australian mining corridors, while Chinese fabricators supply Shanxi Province coal operations through domestic certification channels. Trade flows track ore processing intensity across extraction belts.
Australia
Iron ore expansion in Western Australia's Pilbara district outpaces local manufacturing capacity. The country's national mining safety regulator mandates pressure testing protocols for tailings discharge infrastructure. Mining operators in the Pilbara region are expanding procurement of reinforced slurry pipes as extraction volumes intensify.
China
Domestic coal operations in Shanxi Province drive concentrated demand for high-pressure discharge piping. The Ministry of Ecology and Environment enforces tailings dam construction standards that mandate higher-performance specifications. Fabricators in the Yangtze River Delta supply compound formulations compliant with GB/T pressure testing requirements that exceed legacy benchmarks.
Chile
Copper extraction operations in the Atacama Desert generate replacement cycles for abrasion-resistant transport infrastructure. The country's national mining regulator oversees environmental compliance for slurry discharge systems. Procurement committees in Santiago combine engineering, finance, and supply chain functions for vendor selection decisions.
United States
EPA effluent limitations under the Clean Water Act constrain discharge piping specifications in mining and construction drainage. The Environmental Protection Agency enforces leachate thresholds that compounders must meet while maintaining hardness ratings. Procurement teams in Arizona and Nevada copper belts consolidate vendor lists around pre-qualified suppliers with established compliance documentation.
Canada
Oil sands processing in Alberta mandates compound reformulation toward low-aromatic blends resistant to hydrocarbon degradation. Environment and Climate Change Canada oversees emissions rules affecting elastomer specifications. Operators in the Athabasca region pilot thermoplastic-lined composite constructions as alternatives to pure rubber systems.
Abrasion-Resistant Rubber Pipe Market Vendor Landscape
Player mix skews toward vertically integrated compounders with captive polymer facilities and distributed service networks. Market structure concentrates around proprietary formulation expertise, creating qualification bottlenecks for new entrants. Two strategic archetypes dominate: integrated polymer compounders controlling upstream feedstock access, and service-network players leveraging proximity to extraction sites. Competitive moves center on geographic expansion into mining corridors and portfolio diversification toward sensor-integrated monitoring systems.
Among European integrated compounders, Trelleborg AB and ContiTech AG exemplify the captive-facility archetype, anchoring supply through proprietary NR/BR blend formulations. Parker Hannifin occupies a position within the service-network tier, representing distributed coverage models across Latin American extraction sites. These three names illustrate the bifurcation between formulation-anchored and proximity-driven competitive strategies.
| Leading Market Players |
|---|
| Manuli Hydraulics |
| Trelleborg AB |
| Parker Hannifin |
| Bridgestone |
| ContiTech AG |
| Gates Corporation |
| Alfagomma Group |
| Semperit AG Holding |
| Eaton Hydraulics |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Australian and Chilean mining operators lock in compound supply access while anchoring price visibility against natural rubber volatility. These agreements insulate captive compounders from spot market swings but expose them to volume penalties if ore processing intensity shifts.
Pricing Analysis
Current-generation flexible pipe formulations command premium positioning over prior-generation rigid constructions, while next-generation sensor-embedded systems are resetting price floors. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated solutions from commodity fabricators. Price differentiation rests on certification grade against China's GB/T standards and REACH Annex XVII compliance status. Cost compression in standard rubber tiers is intensifying because thermoplastic-lined composites are displacing pure elastomer in oil sands processing. Construction drainage buyers exhibit highest price sensitivity, while industrial mining operators prioritize lifecycle replacement frequency over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian natural rubber feedstock delivery to compounders in Sweden and Sri Lanka. Supply concentrates in Thailand and Indonesia for plantation latex, with Germany and Japan anchoring formulation chemistry expertise. Raw material dependencies center on natural rubber, synthetic polybutadiene, and carbon black reinforcement. Single-source vulnerability runs through aging technical workforces in European compounding facilities. Distribution runs through OEM procurement committees at mining conglomerates and direct service networks at extraction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining procurement consolidation into cross-functional committees concentrates buyer power, forcing suppliers to reorganize around total cost metrics rather than unit price competition.
For Market Incumbents: Fortify proprietary NR/BR blend formulations through backward integration into captive polymer facilities. Deepen sensor-embedded monitoring capabilities to bifurcate supplier tiers and compress margin pools for undifferentiated fabricators. Anchor regulatory affairs capabilities around EPA effluent documentation and REACH Annex XVII compliance to accelerate vendor approval cycles with consolidated procurement teams. For New Entrants and Emerging Players: Lead with GB/T certification investment to capture import substitution partnerships in Western Australia's Pilbara district, where iron ore expansion outpaces local manufacturing capacity. Target specialty low-aromatic compound segments where REACH and EPA rules are forcing supply chain rebuilds. Pursue joint development agreements with mining operators piloting predictive replacement scheduling systems in Chilean copper extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with long-term offtake agreements and embedded service contracts at tier-one mining corridors. Five-to-ten year viability favors vertically integrated specialists with proprietary formulation libraries and regulatory pre-qualification. Monitor MEE enforcement patterns around tailings dam construction standards as inflection indicator for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of NR/BR blends locks in formulation control against feedstock volatility. |
| Sensor-Embedded Pipe Development | Wear-detection fiber integration enables predictive maintenance contracts with Pilbara operators. |
| REACH Annex XVII Compliance Investment | Low-aromatic compound pre-qualification accelerates vendor status with EU mining equipment OEMs. |
| GB/T Certification Acquisition | Pressure testing protocol alignment opens import substitution channels in Shanxi Province coal belt. |
| Service Network Expansion in Latin America | Proximity to Chilean copper extraction sites reduces unplanned downtime response intervals. |
Methodological Framework
Initial hypotheses were tested against primary input from mining procurement directors, compound formulation chemists, tailings infrastructure engineers, and aftermarket service managers and refined through secondary validation. Mining operator maintenance records, customs trade data for rubber compound imports, SEC filings from diversified industrial conglomerates, and China's MEE enforcement bulletins anchored quantitative baselines. Bottom-up volume modeling across product architectures triangulated with top-down value estimates from ore processing intensity projections.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, application severity tier, material grade certification, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis tied to slurry erosion rates and specification upgrade patterns. Forecast inputs incorporate ore processing intensity indices and tailings dam construction permit issuance rates.
Forecasts assume regulatory continuity in EPA effluent limitations and REACH Annex XVII enforcement; material policy shifts would require re-modeling around accelerated thermoplastic substitution or relaxed hydrocarbon restrictions. Practitioners should keep alternative scenarios live as MEE tailings standards and natural rubber plantation labor availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Color Masterbatch Market
Rubber
Rubber Roller Cleaner Market
Rubber
Reclaimed Rubber Market
Rubber
Rubber Wear Liners Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Industrial Rubber Market
Rubber
Europe Silicone Rubber Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Tire Softener Market
Rubber
Polyacrylate Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Global Chloroprene Rubber Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Acrylic Rubber Market
Rubber
Rubber Bulbs Market