
 Special Graphite Market | 2026-2036
Special Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Special Graphite Market Analytics
A shortage of carbon materials engineers is redrawing competitive boundaries in the special graphite sector. SGL Carbon leverages its European manufacturing heritage to sustain premium electrode output for steelmakers. GrafTech International anchors North American supply through vertical integration into petroleum needle coke. Nippon Kokuen Group competes on ultra-high purity grades for semiconductor thermal management applications.
Special graphite encompasses engineered carbon materials with controlled crystalline structure, typically achieving purity above 99.95% carbon content through graphitization at temperatures exceeding 2,800°C for applications demanding thermal stability and electrical conductivity. Synthetic graphite dominates electrode and battery anode applications due to consistent particle size distribution and low impurity profiles. Natural graphite occupies cost-sensitive lubricant and expandable graphite segments where crystalline flake structure delivers lubricity. Battery anodes represent the fastest-expanding application category as lithium-ion chemistry requirements tighten carbon coating specifications.
China's MIIT enforces GB standards on graphite export classifications while the EU's REACH framework mandates substance registration for imported carbon materials. EPA oversight in the United States governs emissions from graphitization furnaces, raising capital requirements for domestic producers. Stakeholders must monitor evolving battery supply chain due diligence rules across multiple jurisdictions to secure qualified supplier status.
Market Dynamics
Automakers' battery chemistry roadmaps are forcing graphite suppliers to recalibrate purity specifications and coating protocols faster than furnace capacity can expand. This demand acceleration from electric vehicle programs is compressing qualification timelines and concentrating procurement power among vertically integrated cell manufacturers.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content thresholds and carbon footprint declarations are creating certified supply premiums for European-sourced synthetic graphite.
- Silicon-anode blending:Next-generation lithium-ion formulations incorporating silicon require engineered graphite substrates with precisely controlled surface area and porosity profiles.
- China:Dual carbon goals and provincial emissions trading schemes are shuttering inefficient graphitization capacity, tightening supply for compliant exporters.
Market Restraints
- Petroleum needle coke volatility:Feedstock costs for synthetic graphite fluctuate with oil refinery output decisions and decarbonization-driven coker unit retirements.
- Heilongjiang and Shandong concentration:Over 70% of global spherical graphite processing sits in two Chinese provinces, exposing buyers to single-jurisdiction logistics and policy risks.
- Thermal management ceiling:Natural graphite's anisotropic thermal conductivity limits its deployment in high-power semiconductor packaging where isotropic synthetic grades dominate.
Strategic Opportunities
- India:Production-linked incentive schemes for advanced chemistry cell manufacturing are attracting graphite anode investments with domestic coating and spheronization capabilities.
- Solid-state battery interfaces:Pre-lithiated graphite anodes and solid electrolyte compatibility layers represent uncontracted demand from next-generation cell architectures.
- Direct purchasing consortia:Automotive OEMs are forming pooled procurement vehicles to secure qualified anode material volumes outside traditional trader channels.
Industry Challenges
- Carbon materials engineering talent:Universities produce fewer graphitization specialists than furnace expansions require, forcing producers to poach from adjacent ceramics and metallurgy sectors.
- REACH registration timelines:EU substance dossiers for novel coated graphite grades extend 18-24 months, delaying market entry for iterative product improvements.
- Legacy EAF electrode specifications:Steelmaker technical standards written for 1980s graphite grades create friction against adopting higher-purity, lower-resistivity alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Graphite Market |
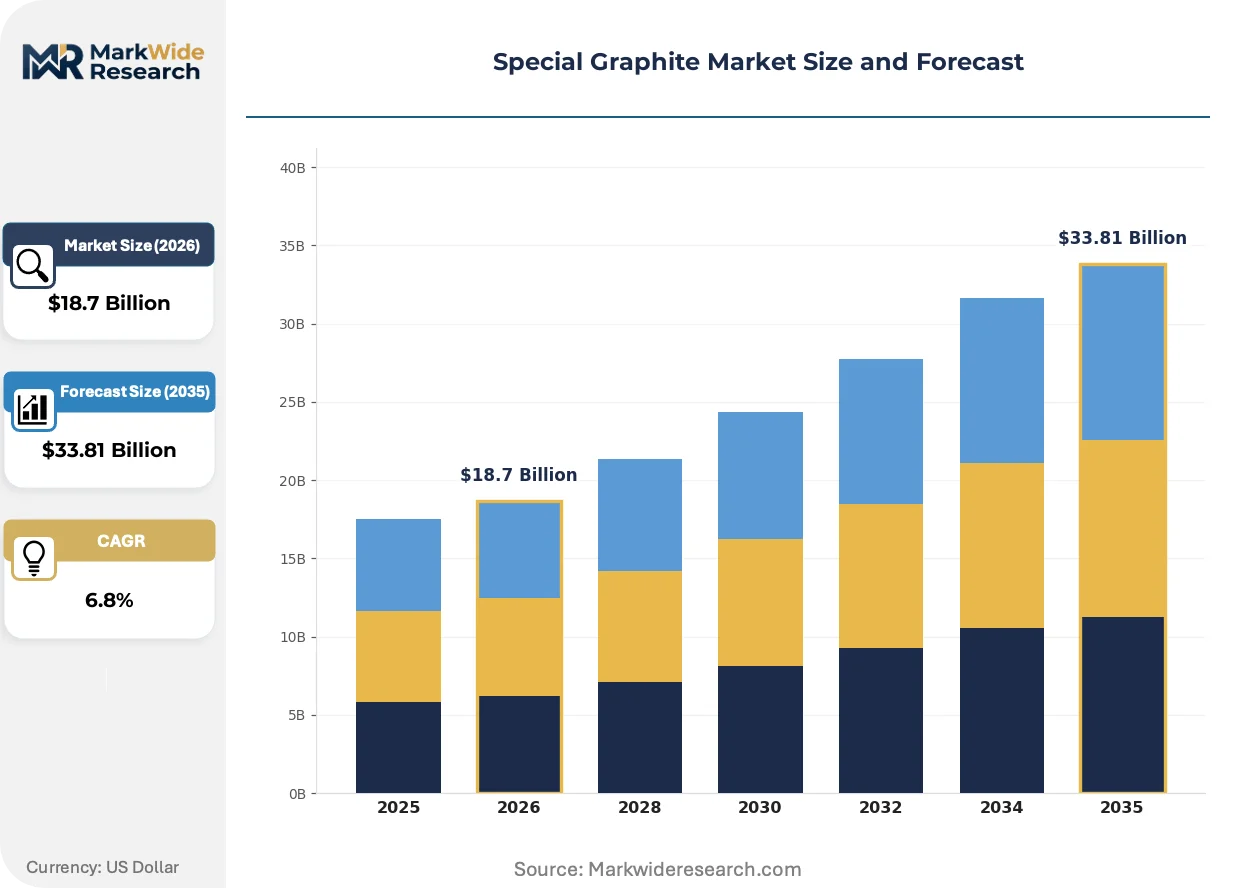
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Graphite, Synthetic Graphite, Expandable Graphite, Graphite Powder End User: Electronics, Automotive Batteries, Steel Production, Lubricants Form: Flake Graphite, Amorphous Graphite, Graphite Nanoparticles, Graphite Pellets Application: Electrodes, Thermal Management, Battery Anodes, Carbon Brushes |
| Companies Covered | Mersen, Nippon Kokuen Group, SGL Carbon, Entegris, Fangda Carbon New Material Co., Ltd., Toyo Tanso Co., Ltd., GrafTech International Ltd., HEG Limited, Tokai Carbon Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Graphite Market Evolving Landscape
Graphite processing is bifurcating into commodity spheronization for automotive volume and precision coating for premium thermal applications. Equipment suppliers and chemical partners are racing to decouple these workflows.
Continuous graphitization technology is decomposing the traditional batch furnace paradigm that has dominated since the 1960s. European furnace builders and Japanese carbon specialists are piloting electrically heated conveyor systems that reduce energy intensity and cycle times. This shift is compressing capital recovery periods and enabling smaller-scale production nodes closer to battery assembly plants.
EPA emissions standards for graphitization furnaces are tightening particulate and sulfur dioxide limits in the United States. Domestic producers face retrofit investments or capacity mothballing decisions. The regulatory pressure is accelerating interest in electrically heated alternatives and imported synthetic graphite from jurisdictions with different emissions accounting frameworks.
Cell manufacturers are consolidating their anode supplier base from twenty-plus qualified vendors to six to eight strategic partners with captive coating capabilities. Long-term offtake agreements with minimum volume guarantees are replacing spot purchasing. This concentration is most visible in European and North American battery plant announcements where single-source qualification timelines dominate supplier selection criteria.
Special Graphite Market Segmentation
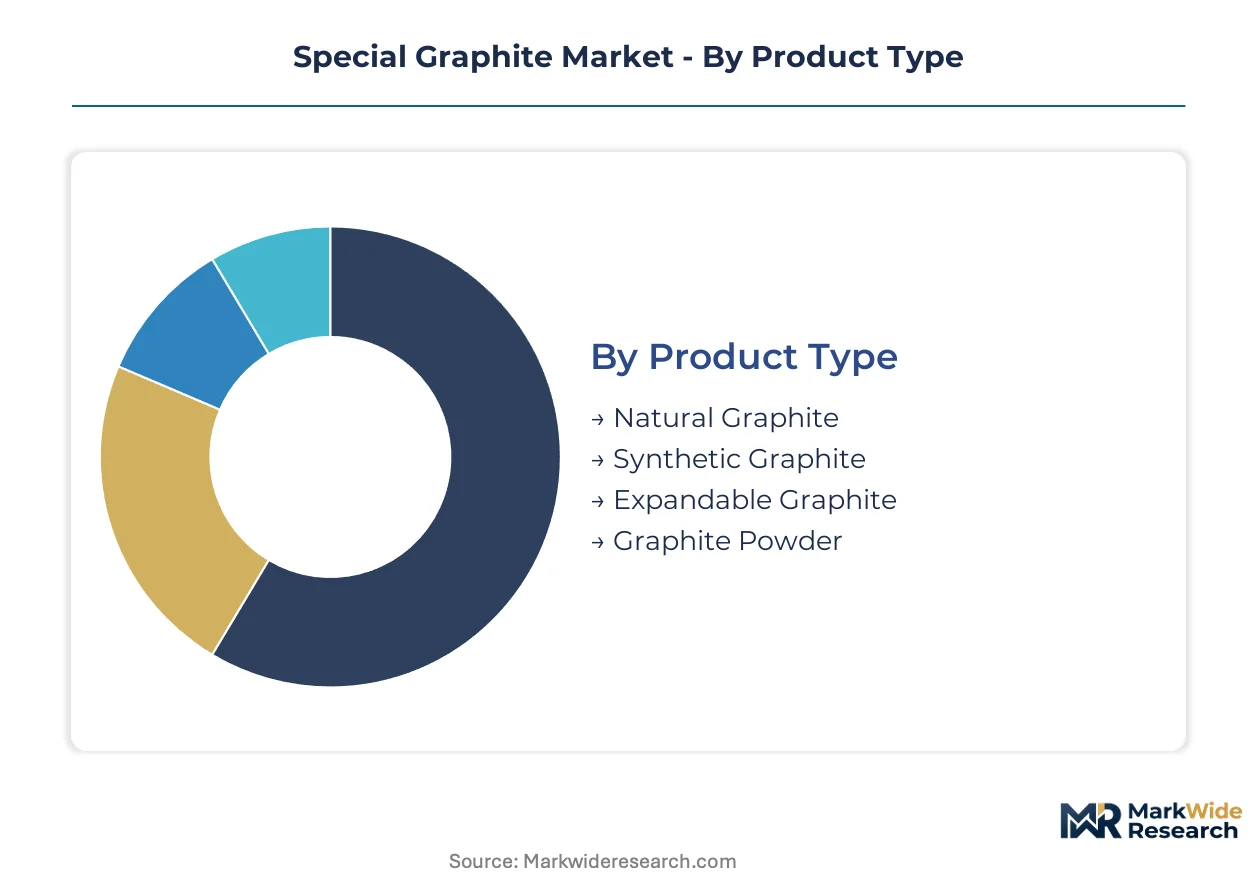
Special graphite markets fragment across multiple technical dimensions that determine pricing power and qualification barriers. Product chemistry, physical form, and end-use specifications create distinct competitive arenas with uneven substitute threats and margin profiles.
Product Type:
Synthetic graphite faces intensifying substitution pressure from silicon-anode blends in premium battery applications, while natural grades confront expandable graphite displacement in fire-retardant building materials.
- Natural Graphite:Crystalline flake material mined from metamorphic deposits, typically 90-98% carbon content before beneficiation. Steel refractories in India and Brazil absorb the largest volumes, though spherical processing for battery anodes is tightening flake purity requirements.
- Synthetic Graphite:Petroleum needle coke or coal tar pitch feedstock graphitized above 2,800°C achieves 99.95%+ purity with controlled porosity. Automotive battery anodes in Germany, South Korea, and the United States concentrate demand as cell manufacturers enforce coating specifications.
- Expandable Graphite:Intercalated sulfuric acid or nitrate compounds that exfoliate upon heating to 300°C, forming intumescent barriers for construction and transportation fire protection.
- Graphite Powder:Milled fines from electrode machining or dedicated micronization operations serving lubricant compounding and metallurgical additive markets.
Synthetic graphite anchors the volume base while expandable graphite gains share at the steepest rate.
End User:
Cost tier stratification separates commodity steel electrodes from premium battery anodes, with electronics thermal management occupying the highest specification rung.
- Electronics:Isotropic synthetic grades with matched thermal expansion coefficients bond to semiconductor packages and LED substrates. Japanese and Taiwanese packaging houses drive ultra-high purity demand above 99.999% carbon for GaN device heat spreaders.
- Automotive Batteries:Spherical synthetic graphite with controlled surface area and first-cycle efficiency dominates lithium-ion anode formulations. European cell plants in Hungary and Poland are consolidating qualified supplier bases from twenty vendors to six strategic partners.
- Steel Production:Ultra-high power electrodes for electric arc furnaces consume large-diameter synthetic graphite with low resistivity and high oxidation resistance.
- Lubricants:Natural flake and amorphous grades provide extreme-pressure film strength for metalworking fluids and industrial greases.
Steel production anchors the volume base while automotive batteries expand most quickly.
Form:
Geography of processing capacity determines competitive dynamics, with spherical graphite concentration in China's Heilongjiang and Shandong provinces creating supply vulnerability.
- Flake Graphite:Crystalline platelets above 50 mesh from Mozambique, Madagascar, and Canada deposits supply battery spheronization feedstock. Purification to battery-grade specifications requires acid leaching or thermal treatment.
- Amorphous Graphite:Microcrystalline material from Mexico and Turkey deposits serves lower-cost refractory and foundry applications where crystalline structure is less critical.
- Graphite Nanoparticles:Exfoliated graphene precursors and sub-micron powders for conductive inks and polymer composites.
- Graphite Pellets:Agglomerated fines with organic binders for steelmaking carbon raisers and friction materials.
Flake graphite anchors the volume base while graphite nanoparticles climb the fastest.
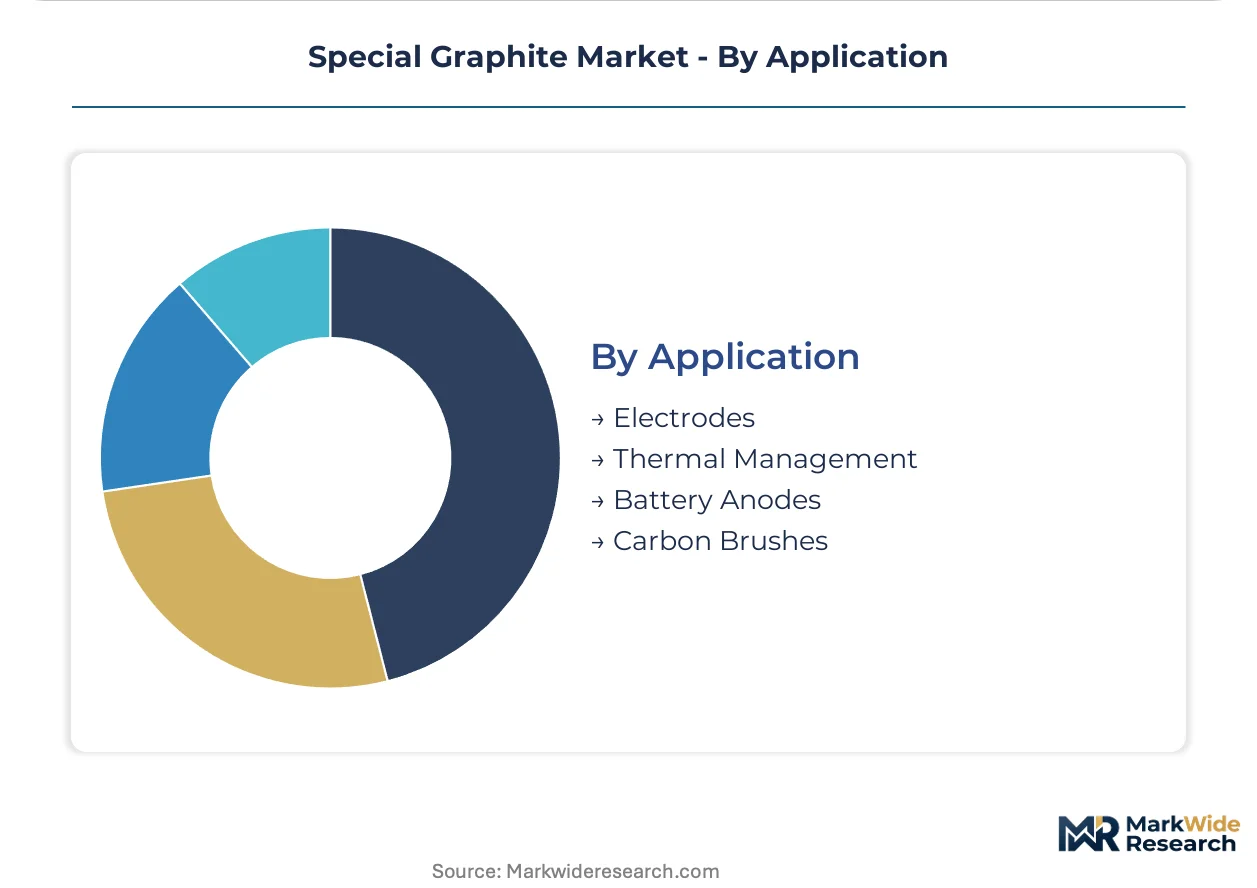
Application:
Customer type concentration among vertically integrated cell manufacturers is compressing supplier margins for battery anodes while preserving premium pricing for thermal management.
- Electrodes:Large-diameter synthetic graphite rods for electric arc furnace steelmaking, requiring low thermal expansion and high mechanical strength at 1,600°C operating temperatures. US and EU steelmakers maintain legacy specifications that friction against adopting higher-purity alternatives.
- Thermal Management:Isotropic synthetic blocks and foils for semiconductor packaging, LED modules, and aerospace heat exchangers. Japanese carbon specialists compete on matched coefficient of thermal expansion with silicon and gallium nitride substrates.
- Battery Anodes:Spherical synthetic graphite with carbon coatings and controlled porosity for lithium-ion cells. Solid-state battery interfaces represent uncontracted demand for pre-lithiated grades.
- Carbon Brushes:Electrographitized blocks for motor and generator current collection, balancing wear rate and contact resistance.
Electrodes anchor the volume base while thermal management gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards on graphite export classifications anchor China's regulatory framework, while the EU's REACH framework and EPA emissions oversight create divergent compliance environments across the three dominant production geographies.
China
Provincial emissions trading schemes in Heilongjiang and Shandong are shuttering inefficient graphitization capacity, tightening supply for compliant exporters. MIIT enforces GB standards on graphite export classifications, requiring substance registration documentation. Qingdao and Harbin processing clusters concentrate spherical graphite output, with automakers demanding faster qualification timelines than furnace expansions allow.
Germany
Electric arc furnace steelmakers in the Ruhr region sustain demand for ultra-high power electrodes, though legacy specifications friction against adopting higher-purity alternatives. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations, creating certified supply premiums for European-sourced synthetic graphite. Bavarian carbon specialists pilot continuous graphitization technology to reduce energy intensity.
United States
Domestic battery cell plants in Michigan and Ohio are consolidating qualified anode supplier bases from twenty vendors to six strategic partners. EPA emissions standards tighten particulate and sulfur dioxide limits, forcing retrofit investments or capacity mothballing decisions. Automotive OEMs in Detroit form pooled procurement vehicles to secure qualified volumes outside traditional trader channels.
Japan
Semiconductor packaging houses in Osaka and Nagoya drive ultra-high purity demand above 99.999% carbon for GaN device heat spreaders. METI oversees industrial standards alignment with international battery supply chain protocols. Japanese carbon specialists compete on matched coefficient of thermal expansion with silicon substrates, preserving premium pricing in thermal management.
South Korea
Cell manufacturers in Gyeonggi Province enforce carbon coating specifications that compress supplier margins while demanding captive spheronization capabilities. The national industrial regulator coordinates with EU Battery Regulation alignment for export-qualified material flows. Busan-Ulsan chemical complexes attract graphite anode investments with integrated coating operations.
Special Graphite Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with furnace ownership and coating capabilities determining competitive position. The upper tier commands long-term offtake agreements with minimum volume guarantees, while mid-scale players compete on qualification speed and regional proximity. Three archetypes dominate: legacy electrode producers pivoting toward battery anodes, semiconductor thermal management specialists, and petroleum needle coke-integrated synthetic graphite manufacturers. Capacity expansion and backward integration into needle coke supply represent the dominant competitive moves.
Among European manufacturing heritage companies, SGL Carbon exemplifies the electrode-to-anode pivot archetype, while GrafTech International anchors North American supply through upstream control over petroleum needle coke. Japanese specialists Nippon Kokuen Group occupy positions in ultra-high purity grades for semiconductor thermal management. These three represent distinct strategic postures without implying specific market shares or financial performance.
| Leading Market Players |
|---|
| Mersen |
| Nippon Kokuen Group |
| SGL Carbon |
| Entegris |
| Fangda Carbon New Material Co., Ltd. |
| Toyo Tanso Co., Ltd. |
| GrafTech International Ltd. |
| HEG Limited |
| Tokai Carbon Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU Battery Regulation compliance certification gates both supplier qualification and price differentiation simultaneously, forcing non-certified material into discount tiers while European-sourced synthetic graphite commands certified supply premiums. Automakers' consolidated procurement pools leverage this bifurcation to extract volume discounts from qualified vendors.
Pricing Analysis
Chinese spherical graphite trades at significant discounts to European-sourced synthetic grades, with the geographic price spread widening as EU carbon footprint declarations take effect. Contract-based long-term offtake agreements dominate, with price differentiation resting on carbon coating specifications and REACH registration status. Cost compression in battery-grade anodes is intensifying because cell manufacturers are consolidating from twenty-plus vendors to six strategic partners. Steel electrode buyers show highest price sensitivity, while semiconductor thermal management customers accept premium pricing for matched coefficient of thermal expansion grades.
Supply Chain Analysis
Strategic stockpiling of petroleum needle coke is displacing just-in-time inventory practices as feedstock volatility accelerates. Supply concentrates in China, Japan, and South Korea, with spherical processing anchored in Heilongjiang and Shandong provinces. Raw material dependencies include petroleum needle coke, coal tar pitch, and crystalline flake feedstock from Mozambique and Madagascar. Single-source vulnerability in Chinese spherical graphite processing exposes buyers to provincial emissions trading scheme disruptions. Distribution runs through vertically integrated cell manufacturers with captive coating capabilities, bypassing traditional trader channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by electric vehicle battery capacity buildouts, with furnace utilization rates tightening as qualification timelines compress. Incumbents and entrants face divergent strategic imperatives.
For Market Incumbents: Fortify backward integration into petroleum needle coke supply to insulate margins from feedstock volatility. Secure long-term offtake agreements with minimum volume guarantees before cell manufacturers complete supplier consolidation. Invest in continuous graphitization technology to reduce energy intensity and defend position against electrically heated furnace entrants. Prioritize REACH dossier maintenance to preserve European market access.
For New Entrants and Emerging Players: Lead with domestic coating and spheronization capabilities in India, where production-linked incentive schemes for advanced chemistry cell manufacturing are attracting anode investments. Target solid-state battery interface materials as the most penetrable white-space segment, where pre-lithiated graphite anodes represent uncontracted demand. Establish direct purchasing relationships with automotive OEM consortia outside traditional trader channels to bypass entrenched supplier relationships.
For Investors and Strategic Acquirers: EU Battery Regulation recycled content thresholds reshape the acquisition landscape toward European-sourced synthetic graphite producers with certified supply status. Five-to-ten year viability favors furnace owners with captive needle coke supply and coating capabilities over pure-play spheronization operators. Target acquisition archetype: mid-scale European or North American producer with underutilized graphitization capacity and pending REACH registration for novel coated grades. Watch for silicon-anode blend adoption rates as inflection indicator for synthetic graphite substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Secures feedstock supply against refinery coker unit retirements and oil price volatility. |
| Continuous Graphitization Technology Deployment | Reduces energy intensity and cycle times, enabling smaller-scale production nodes near battery plants. |
| REACH Registration Investment | Preserves European market access as EU Battery Regulation tightens substance documentation requirements. |
| Captive Coating Capability Addition | Qualifies suppliers for cell manufacturer consolidation from twenty vendors to six strategic partners. |
| Direct OEM Consortium Partnership | Bypasses traditional trader channels as Detroit automakers form pooled procurement vehicles. |
Research Methodology
Initial hypotheses were tested against primary input from carbon materials engineers, battery cell procurement directors, steelmaker technical standards committees, and graphitization furnace operators and refined through secondary validation. Primary fieldwork encompassed technical interviews across electrode producers, anode material specialists, and semiconductor packaging houses. Secondary sources included customs trade data for graphite export classifications, MIIT GB standard filings, EPA emissions compliance disclosures, and SEC filings from listed carbon companies. Bottom-up demand modeling across end-use segments was triangulated against top-down supply capacity assessments.
Variance decomposition across product chemistry, physical form, and end-use specifications structured the analytical framework over the projection horizon. Segmentation dimensions modeled include synthetic versus natural graphite grades, spherical versus flake form factors, and battery anode versus electrode versus thermal management applications. CAGRs were derived from installed electric vehicle battery capacity trajectories and steel electric arc furnace adoption curves, with furnace expansion timelines and qualification bottlenecks as graphite-specific forecast inputs.
Forecasts assume regulatory continuity in EU Battery Regulation implementation and EPA emissions standards; material policy shifts would require re-modeling. Revision becomes warranted when silicon-anode blend adoption crosses thresholds that displace engineered graphite substrates or when Chinese provincial emissions trading schemes shutter graphitization capacity faster than furnace expansions permit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Solar Control Films Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Jesmonite Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Elastic Films Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market