
 Iron and Steel Market | 2026-2036
Iron and Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Iron and Steel Market Intelligence
A shift from single-source to multi-source procurement for specialized alloy steels is repositioning supply chain dependencies for automotive and aerospace manufacturers. ArcelorMittal leverages its global production footprint to offer diverse material grades across continents. Nucor Corporation specializes in Electric Arc Furnace production, focusing on the North American market. Tata Steel sustains a strong presence in Europe and India, anchoring its strategy on long-term industrial partnerships.
Iron and steel are alloys of iron and carbon, with carbon content typically below 2%, which imparts strength and fracture resistance. These materials form the foundational backbone for modern infrastructure and industrial machinery due to their high tensile strength and formability. While flat steel products dominate value in the automotive sector, long steel products see consistent volume demand from construction. The Electric Arc Furnace production method is expanding rapidly, displacing older technologies due to its lower emissions profile and scrap recycling capabilities.
The European Union's Carbon Border Adjustment Mechanism (CBAM) is altering trade flows by pricing carbon content in imported steel. Concurrently, China's dual carbon goals accelerate the closure of inefficient mills, while US EPA emissions standards govern domestic production. These frameworks collectively create a complex compliance landscape. Future profitability depends on navigating decarbonization pressures while managing volatile input costs for energy and raw materials.
Market Dynamics
Decarbonization mandates are the central structural force shaping the iron and steel industry. This pressure compels a technological pivot away from traditional blast furnaces toward Electric Arc Furnace (EAF) production, fundamentally altering capital investment patterns, input dependencies, and global trade flows.
Growth Catalysts
- EV Manufacturing Demand:The automotive sector's need for advanced high-strength steels (AHSS) for electric vehicle body structures and battery enclosures provides a consistent, high-value demand stream for specialized flat-rolled products.
- Chinese Industrial Policy:China's dual carbon goals are accelerating the shutdown of older, less efficient blast furnaces, creating government-backed incentives for investment in lower-emission EAF and green hydrogen-based steelmaking technologies.
- Scrap Recycling Economics:The ability of EAFs to use steel scrap as a primary input reduces reliance on virgin iron ore and coking coal, offering a circular economy advantage and a hedge against raw material price volatility.
Market Restraints
- Energy Price Volatility:The profitability of Electric Arc Furnace production is highly sensitive to electricity price fluctuations, posing a significant operational cost risk in markets without stable, low-cost power grids.
- High-Grade Ore Concentration:The global supply of high-grade iron ore, essential for efficient Direct Reduced Iron (DRI) production, is concentrated in a few countries, creating supply chain vulnerabilities and pricing power for key mining regions.
- Trade Compliance Burdens:The European Union's Carbon Border Adjustment Mechanism (CBAM) imposes financial penalties and complex reporting requirements on steel imports based on their embedded carbon, creating a significant trade barrier.
Strategic Opportunities
- Hydrogen-Based Steelmaking:Developing steel production capabilities that use green hydrogen as a reductant instead of fossil fuels opens access to premium green steel markets and aligns with long-term decarbonization targets.
- Specialized Alloy Development:Formulating new steel alloys optimized for emerging applications, such as hydrogen storage tanks, carbon capture pipelines, and advanced wind turbine components, creates new, high-margin product categories.
- Digital Process Optimization:Implementing AI and digital twin technologies across steel mills offers significant opportunities to reduce energy consumption, improve product quality and yield, and enable predictive maintenance, thereby lowering operational costs.
Industry Challenges
- Capital Investment Cycles:The immense capital expenditure and long construction timelines required to build new EAF or DRI facilities represent a major hurdle, particularly for producers with aging but still-functional blast furnace assets.
- Workforce Skill Gaps:A shortage of metallurgists and data scientists skilled in advanced process controls, automation, and low-carbon steelmaking technologies impedes the operational efficiency of next-generation mills.
- Green Steel Standardization:The absence of a globally recognized definition and certification scheme for "green steel" creates market confusion, complicates procurement for buyers, and hinders the establishment of a consistent price premium.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron and Steel Market |
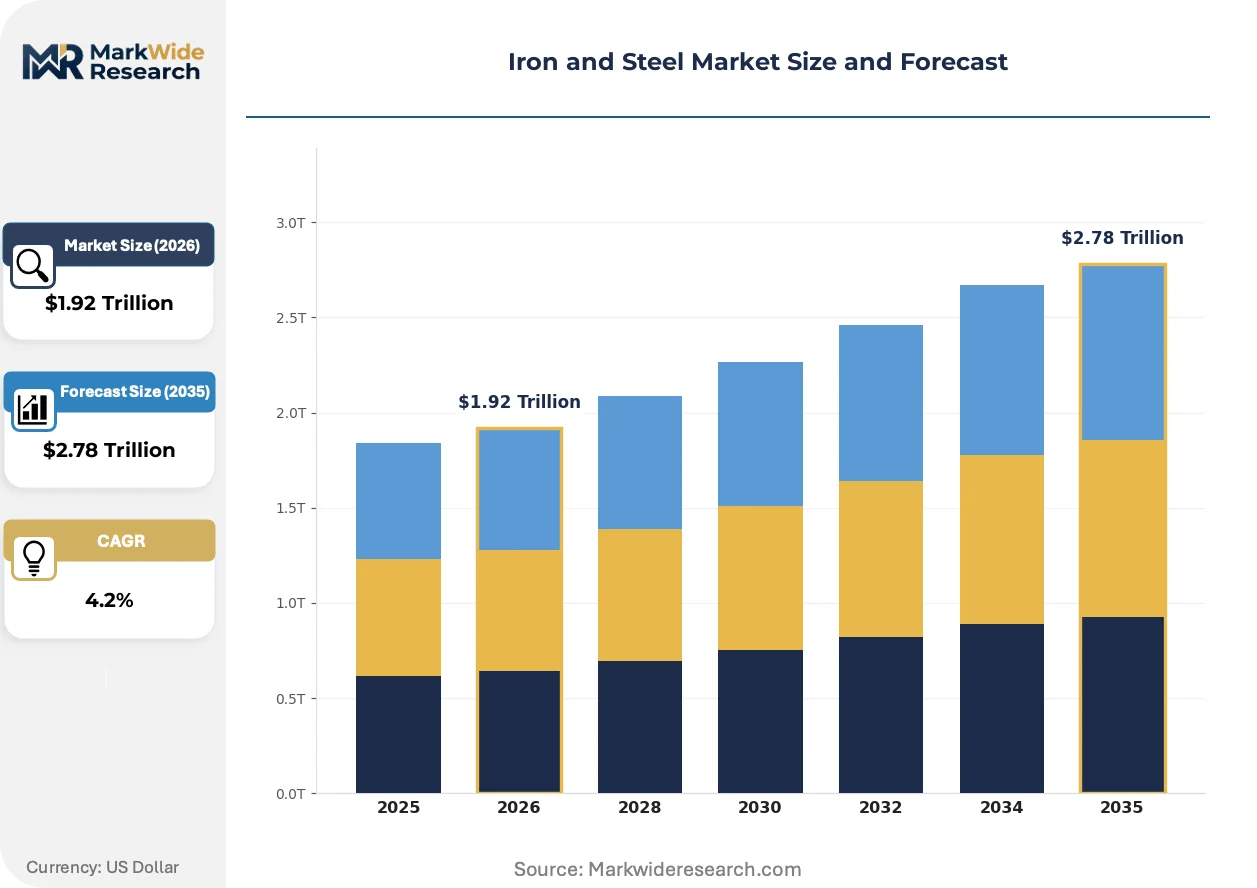
| Market Size in 2026 | $1.92 Trillion |
| Market Size in 2035 | $2.78 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Steel, Long Steel, Raw Steel, Finished Steel End User: Construction, Automotive, Manufacturing, Shipping Production Method: Bessemer Process, Electric Arc Furnace, Basic Oxygen Furnace, Open Hearth Process Material Grade: Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel |
| Companies Covered | ArcelorMittal, Nucor Corporation, Tata Steel, Nippon Steel Corporation, JSW Steel, POSCO Holdings, Steel Dynamics, Cleveland-Cliffs Inc., China Baowu Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron and Steel Market Strategic Shifts & Innovations
Digitalization and sustainability mandates are jointly reconfiguring production processes and supply chain logic. These forces are driving innovation from the furnace to the final product, prioritizing operational efficiency and transparent environmental credentials, which are becoming key competitive differentiators.
Direct Reduced Iron (DRI) technology enables lower-carbon steel production by using natural gas or hydrogen as a reducing agent. Integrated steelmakers in Europe and Asia are adopting DRI as part of their phased decarbonization strategies, often pairing it with Electric Arc Furnaces. This adoption is modularizing the traditional, monolithic blast furnace plant layout, allowing for incremental capacity conversion rather than a single, disruptive overhaul.
The US Inflation Reduction Act (IRA) provides significant tax credits for carbon capture, utilization, and storage (CCUS) and the production of low-carbon hydrogen. This policy creates a direct financial incentive for domestic steel producers to invest in decarbonization projects that were previously economically challenging. The flat-rolled steel segment, a critical supplier to the automotive industry, is most affected as producers seek to leverage these credits.
A shift toward life-cycle assessment (LCA) based purchasing is gaining traction among major steel buyers in the construction and automotive sectors. This model requires suppliers to provide verifiable data on a product's embodied carbon, moving beyond simple price and grade specifications. This trend is most pronounced in Europe, where regulations like the Corporate Sustainability Reporting Directive (CSRD) compel downstream companies to report their supply chain emissions.
Iron and Steel Market Segmentation
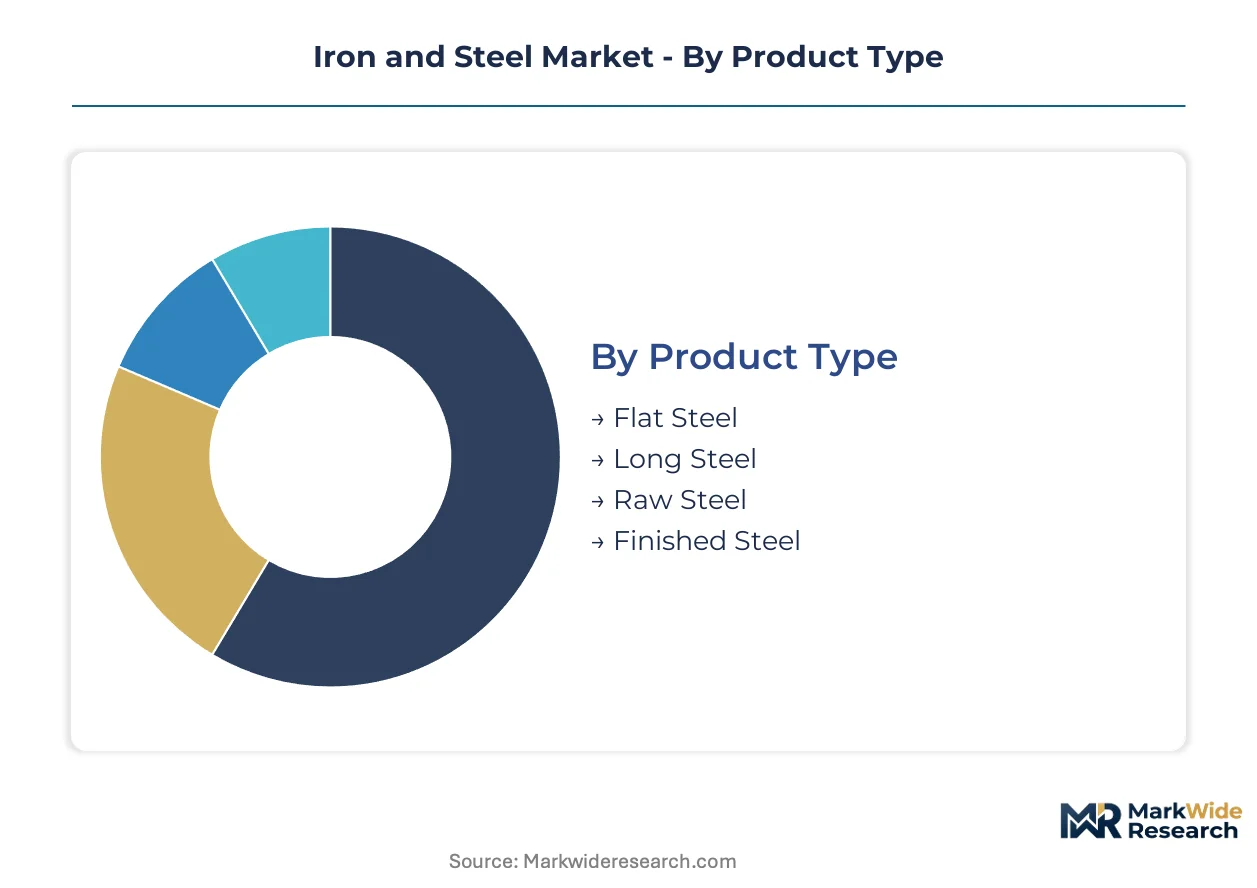
Understanding the distinct segments within the iron and steel market is crucial for producers to align production capabilities with evolving demand patterns. Each segment presents unique material specifications, regulatory compliance requirements, and end-user performance expectations. This granular view informs strategic investment and product development across the value chain.
Product Type:
Certain product types within the iron and steel market face distinct regulatory hurdles, impacting their market entry and application scope across various industries.
- Flat Steel:This category includes sheets, plates, and coils, characterized by their high surface area to thickness ratio, essential for forming operations. Demand concentrates in the automotive sector for advanced high-strength steels in EV bodies, driven by lightweighting mandates and crash safety standards.
- Long Steel:Comprising bars, rods, and wire, these products provide structural integrity and reinforcement in construction. Consistent demand from infrastructure projects and residential building supports its volume, with specifications often governed by national building codes and ISO standards.
- Raw Steel:This intermediate product serves as the primary input for further processing, including casting and rolling into finished forms.
- Finished Steel:These are final products ready for direct integration into end-user applications, having undergone all necessary shaping and treatment.
Leading the category by volume: Long Steel. Growing fastest: Flat Steel.
End User:
End-user segments dictate specific material requirements and drive innovation in steel alloy development, influencing production methodologies and supply chain configurations.
- Automotive:This sector requires specialized steels for vehicle frames, body panels, and engine components, emphasizing strength-to-weight ratios and formability. The transition to electric vehicles is accelerating demand for new alloys suitable for battery enclosures and structural integrity.
- Construction:This segment utilizes steel for structural frameworks, reinforcement, and architectural elements, prioritizing durability, load-bearing capacity, and adherence to building codes. Urbanization trends and public infrastructure investments consistently drive substantial volume demand.
- Manufacturing:Diverse manufacturing industries consume steel for machinery, tools, and equipment, requiring specific grades for wear resistance and precision.
- Shipping:The shipbuilding industry and container production rely on specialized marine-grade steels, demanding corrosion resistance and structural robustness in harsh environments.
Demand from the Construction sector remains substantial, while Automotive applications exhibit the steepest expansion trajectory.
Production Method:
Production methods are differentiated by their capital intensity, operational costs, and environmental footprint, profoundly impacting investment decisions and competitive advantage.
- Electric Arc Furnace:This method primarily uses steel scrap as a raw material, offering lower carbon emissions compared to traditional blast furnaces and enabling a circular economy approach. Decarbonization mandates and the availability of scrap are making EAF production increasingly attractive in markets like North America and Europe.
- Basic Oxygen Furnace:Relying on molten iron from blast furnaces and coking coal, this method is characterized by high volume output and established infrastructure. It remains a dominant method for primary steel production, particularly in Asia, where large-scale iron ore resources are readily accessible.
- Bessemer Process:An early steelmaking method, the Bessemer process is largely historical and has been superseded by more efficient and controllable techniques.
- Open Hearth Process:This older technology offered greater control over steel composition than the Bessemer process but has been displaced by modern, more efficient methods.
The Electric Arc Furnace method is gaining share rapidly, while the Basic Oxygen Furnace maintains significant volume globally.
Material Grade:
Material grades are distinguished by their metallurgical properties, directly influencing performance and pricing premiums across various end-use applications.
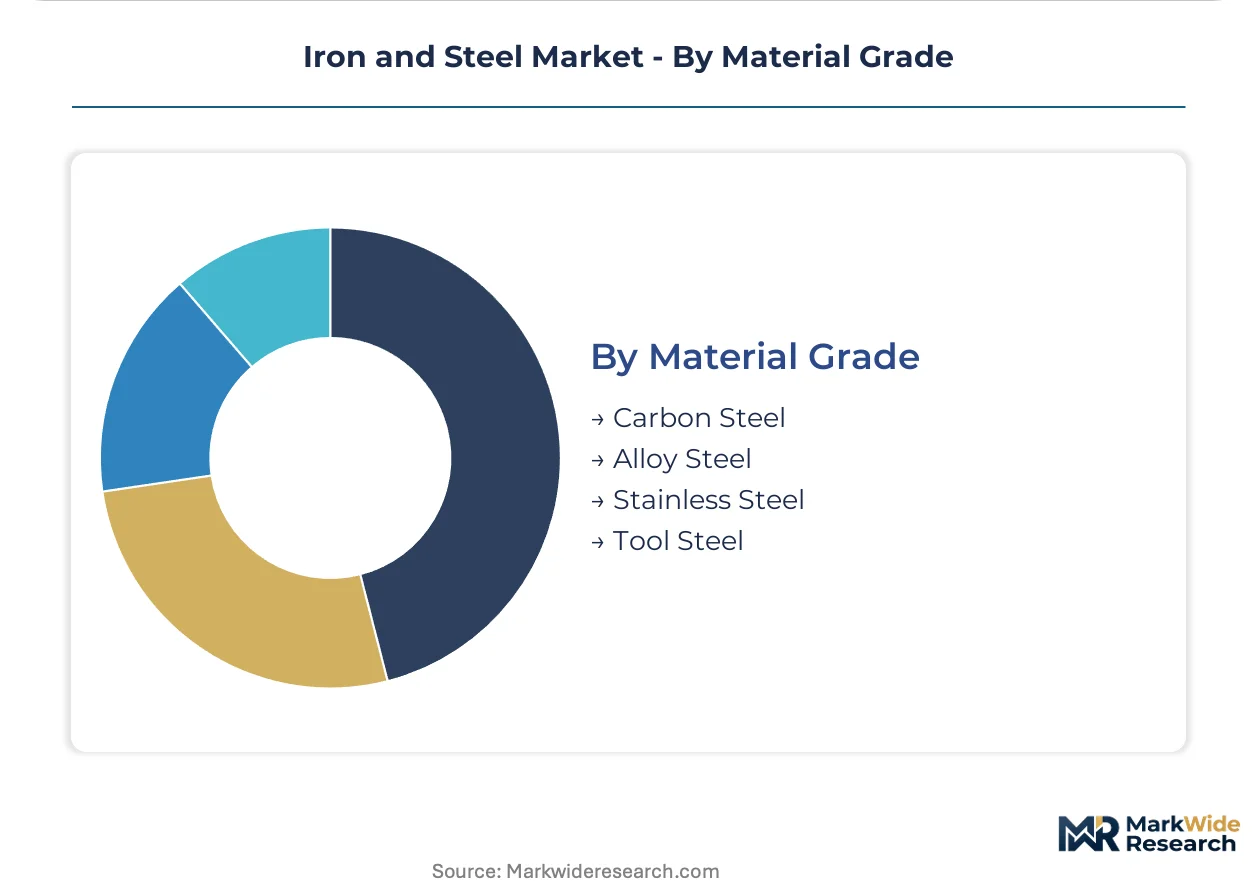
- Alloy Steel:These steels incorporate specific alloying elements like chromium, nickel, or molybdenum to enhance properties such as strength, hardness, and corrosion resistance. Aerospace components and specialized industrial machinery drive demand for these high-performance materials.
- Stainless Steel:Characterized by high chromium content, stainless steel offers superior corrosion resistance and aesthetic appeal, making it ideal for applications in food processing, medical devices, and architectural facades. Hygiene requirements and longevity are critical drivers for this grade.
- Carbon Steel:This workhorse material, containing primarily iron and carbon, forms the backbone of general construction and manufacturing due to its strength and cost-effectiveness.
- Tool Steel:Designed for high hardness, wear resistance, and toughness, tool steels are crucial for cutting tools, dies, and molds in various manufacturing operations.
Carbon Steel accounts for the largest volume in this category, with Alloy Steel applications expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's vast iron ore reserves anchor global steel production, influencing supply chains across continents. The shift towards decarbonization and Electric Arc Furnace technology is reshaping regional investment priorities. This transformation is evident in major steel-producing nations.
China
Chinese infrastructure projects and the automotive sector for electric vehicles drive significant demand. China's dual carbon goals accelerate the closure of older, inefficient mills. Hebei province's steel clusters are increasingly investing in Electric Arc Furnace technology and green hydrogen initiatives.
Germany
German advanced manufacturing and the automotive industry require high-strength steel for specialized applications. The European Union's Carbon Border Adjustment Mechanism (CBAM) significantly influences steel trade flows. The Ruhr region continues to focus on green steel production and hydrogen-based steelmaking projects.
United States
The US construction sector and automotive industry consistently demand lightweight materials. The US Inflation Reduction Act provides substantial incentives for domestic steel decarbonization projects. The Great Lakes region sees significant Electric Arc Furnace capacity expansion, utilizing abundant scrap resources.
India
India's rapid urbanization, infrastructure development, and manufacturing growth fuel substantial steel consumption. The Indian government's Production Linked Incentive (PLI) scheme encourages domestic steel production and technological upgrades. Odisha's industrial hubs are attracting new steel plant investments, particularly in integrated facilities.
Brazil
Brazilian domestic construction and export markets for semi-finished steel products maintain consistent demand. Environmental licensing requirements from agencies like IBAMA govern new mining and steelmaking projects. Minas Gerais remains a core region for iron ore mining and integrated steelmaking operations.
Iron and Steel Market Key Industry Players
Capacity expansion and technological transformation dominate the current landscape, driven by decarbonization mandates. The market structure exhibits a tiered consolidation, encompassing large multinational integrated producers and specialized regional Electric Arc Furnace operators. Strategic archetypes include global scale players, regional EAF specialists, and emerging green steel innovators. Key competitive moves involve significant capital investment in low-carbon technologies and strategic partnerships for raw material security.
Global integrated players like ArcelorMittal, a Luxembourg-based S.A., represent the extensive production footprint model, offering diverse material grades across continents. Nucor Corporation, a US-based Corporation, exemplifies the regional EAF specialist archetype, focusing on the North American market. Tata Steel, an India-based company, occupies a position anchored by long-term industrial partnerships across Europe and India. These companies collectively illustrate the varied approaches to market leadership.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nucor Corporation |
| Tata Steel |
| Nippon Steel Corporation |
| JSW Steel |
| POSCO Holdings |
| Steel Dynamics |
| Cleveland-Cliffs Inc. |
| China Baowu Group |
| Others |
Cost & Logistics Intelligence
The European Union's Carbon Border Adjustment Mechanism (CBAM) compels steel importers to price embedded carbon, forcing suppliers to adapt production methods and influencing global pricing structures. This regulatory pressure reshapes traditional supply chain economics.
Pricing Analysis
Warranty and service bundling often differentiate premium alloy steels, where after-sales technical support integrates with specialized material grades. The dominant pricing model for finished steel relies on contract-based long-term offtake agreements, influenced by embodied carbon content and specific material certifications. Price differentiation stems from factors like alloy composition for strength and corrosion resistance, alongside geographic delivery costs. Pricing pressure intensifies for conventional steel due to volatile energy input costs and CBAM penalties. The construction sector exhibits higher price sensitivity for long steel products compared to the automotive industry's demand for advanced high-strength flat steel.
Supply Chain Analysis
Certification and qualification standards, especially for specialized alloy steels, gate access to automotive and aerospace supply chains. Global supply concentrates in China, India, and Brazil for primary steel, while high-grade iron ore sources are highly concentrated. Raw material dependencies include iron ore, coking coal, and steel scrap, with electricity being critical for Electric Arc Furnace production. A key supply chain risk is single-source vulnerability for high-grade iron ore. Distribution predominantly runs through direct sales channels and long-term industrial partnerships, ensuring tailored material delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron and steel market is undergoing a profound technology-transition phase, with Electric Arc Furnace (EAF) production rapidly displacing older blast furnace technologies. This shift reshapes investment and operational strategies across the industry.
For Market Incumbents: Extend existing global production footprints by strategically converting blast furnaces to Electric Arc Furnaces in key regions like Europe and North America. Invest heavily in green steel production technologies, particularly hydrogen-based steelmaking, to mitigate decarbonization mandates and volatile input costs. Deepen long-term industrial partnerships to secure raw material supply and co-develop specialized alloys. Leverage digital process optimization to enhance operational efficiency and product quality against emerging competition.
For New Entrants and Emerging Players: Launch via specialized product offerings targeting premium green steel markets, focusing on alloys for emerging applications like hydrogen storage. Target the North American market, leveraging the US Inflation Reduction Act incentives for low-carbon steel production. Focus on developing verifiable life-cycle assessment data for products to appeal to buyers with stringent sustainability requirements. Establish strategic partnerships with technology providers for hydrogen-based steelmaking to gain early market access.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers focused on long-term decarbonization and technological transformation over the next decade. Target specialized regional Electric Arc Furnace operators or emerging green steel innovators with proven low-carbon technologies. Prioritize companies demonstrating strong intellectual property in specialized alloy development or digital process optimization. A critical signal to watch is the emergence of a globally recognized definition and certification scheme for green steel.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Aligns with global decarbonization goals and secures access to premium green steel markets. |
| Capacity Expansion | Increases Electric Arc Furnace output, leveraging scrap recycling economics and regional incentives. |
| Long-term Supply Agreement | Stabilizes raw material input costs and ensures consistent supply for specialized production. |
| Product Launch | Introduces new steel alloys optimized for emerging applications like EV battery enclosures. |
| Digital Process Optimization | Reduces energy consumption and improves yield across steelmaking operations. |
Research Approach
Trade association data, regulatory filings from the EPA and EU CBAM, and customs records anchored secondary inputs for this analysis. Primary insights were gathered through interviews with metallurgists, automotive procurement leads, construction project managers, and Electric Arc Furnace plant operators. This approach combined top-down market sizing with bottom-up validation, ensuring comprehensive data triangulation. Company financial disclosures and technology patent databases provided additional context.
Data-stream reconciliation across multiple sources informed the quantitative analytical framework over the projection horizon. Segmentation dimensions modeled included product type, end-user applications, primary production methods, material grades, and regional production capacity. Compound annual growth rates were derived from historical trends, technological adoption curves, and policy impacts. Key forecast inputs included global steel scrap availability and green hydrogen production costs.
Energy price volatility, raw material supply disruptions, and shifts in decarbonization policy are the dominant revision risks to these forecasts. All projections reflect assumptions about current technological trajectories and regulatory frameworks. A model refresh is warranted upon material change in global trade dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rolled Steel Motor Market
Metals
Lithium Foil Market
Metals
North America Iron Casting Market
Metals
Cobalt Market
Metals
Weathering Steel Market
Metals
Armour Steel Plate Market
Metals
Expanded Metal Foils Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Europe Aluminium Wire Rod Market
Metals
Global Wire Rods Market
Metals
Transition Metals Market
Metals
Ruthenium Market
Metals
Silver Powder and Flakes Market
Metals
Stainless Steel 400 Series Market
Metals
Electrodeposited Copper Foil Market
Metals
Beryllium Copper Billet Market