
 Rolled Steel Motor Market | 2026-2036
Rolled Steel Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Rolled Steel Motor Market Analytics
Multi-sourced component procurement is recalibrating how OEMs secure laminated steel cores and rotor assemblies. Siemens AG leverages captive European steel mills to anchor its supply chain for medium-power industrial motors. Nidec Motor Corporation competes through specialized high-efficiency designs for Asian appliance and automotive markets. ABB Ltd sustains broad geographic coverage by operating regional motor fabrication centers across multiple continents.
Rolled steel motors employ electrical steel laminations stamped and stacked to form magnetic cores, with silicon content typically ranging from 0.5% to 3.5% to reduce hysteresis losses during alternating-current operation. These motors convert electrical energy to mechanical torque for conveyor systems, pumps, compressors, and machine tools where continuous-duty efficiency determines operating cost. AC Motors dominate volume shipments across industrial end users due to simpler maintenance and direct grid compatibility, while Servo Motors command premium positioning in precision automation where closed-loop control justifies higher unit economics. Frame Type configurations lead in heavy manufacturing installations where structural rigidity and thermal management prove critical, whereas Disk Type designs gain traction in space-constrained HVAC retrofit applications.
EPA efficiency standards and DOE motor performance rules in the United States compel manufacturers to redesign winding configurations and magnetic circuits to meet minimum full-load efficiency thresholds. EU Ecodesign regulations and CE marking requirements under the EU Green Deal restrict market access for motors failing to meet indexed efficiency classes. Stakeholders must monitor how regional efficiency tier upgrades and carbon-border adjustment mechanisms reshape sourcing decisions for electrical steel and finished motor assemblies.
Market Dynamics
Energy efficiency mandates are compressing product lifecycles as manufacturers redesign magnetic circuits and winding configurations to meet escalating indexed efficiency thresholds across multiple jurisdictions.
Growth Catalysts
- EU Ecodesign Directive:Tiered efficiency class upgrades under the EU Green Deal compel motor replacements in German automotive stamping plants and Italian textile machinery.
- Industrial pump demand:Water infrastructure modernization across Southeast Asian manufacturing corridors drives continuous-duty motor procurement for flood control and processing facilities.
- Silicon steel lamination advances:Thinner-gauge electrical steel with optimized grain orientation reduces core losses in high-frequency inverter-fed applications.
Market Restraints
- Electrical steel supply concentration:Premium grain-oriented silicon steel production clusters in a handful of integrated steelworks, exposing motor fabricators to alloying element volatility.
- Copper winding cost exposure:Magnet wire pricing fluctuates with London Metal Exchange copper benchmarks, compressing margin on standard-efficiency product lines.
- Rare-earth magnet substitution ceiling:Ferrite and alnico alternatives cannot match neodymium-iron-boron flux density in compact high-torque designs.
Strategic Opportunities
- Indian PLI scheme for manufacturing:Production-linked incentives for capital goods attract motor assembly investments serving domestic agricultural pump and compressor demand.
- Predictive maintenance integration:Vibration sensors and thermal monitoring converge with motor control systems to enable condition-based service contracts.
- HVAC retrofit channel:Disk-type frame configurations penetrate building automation upgrades where shaft height constraints block conventional motor replacements.
Industry Challenges
- IEC efficiency testing certification:Multi-load point efficiency measurement protocols extend product validation timelines for new winding designs.
- Legacy drive compatibility:Modern high-efficiency motors with lower slip characteristics require inverter parameter recalibration when retrofitting across established VFD installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolled Steel Motor Market |
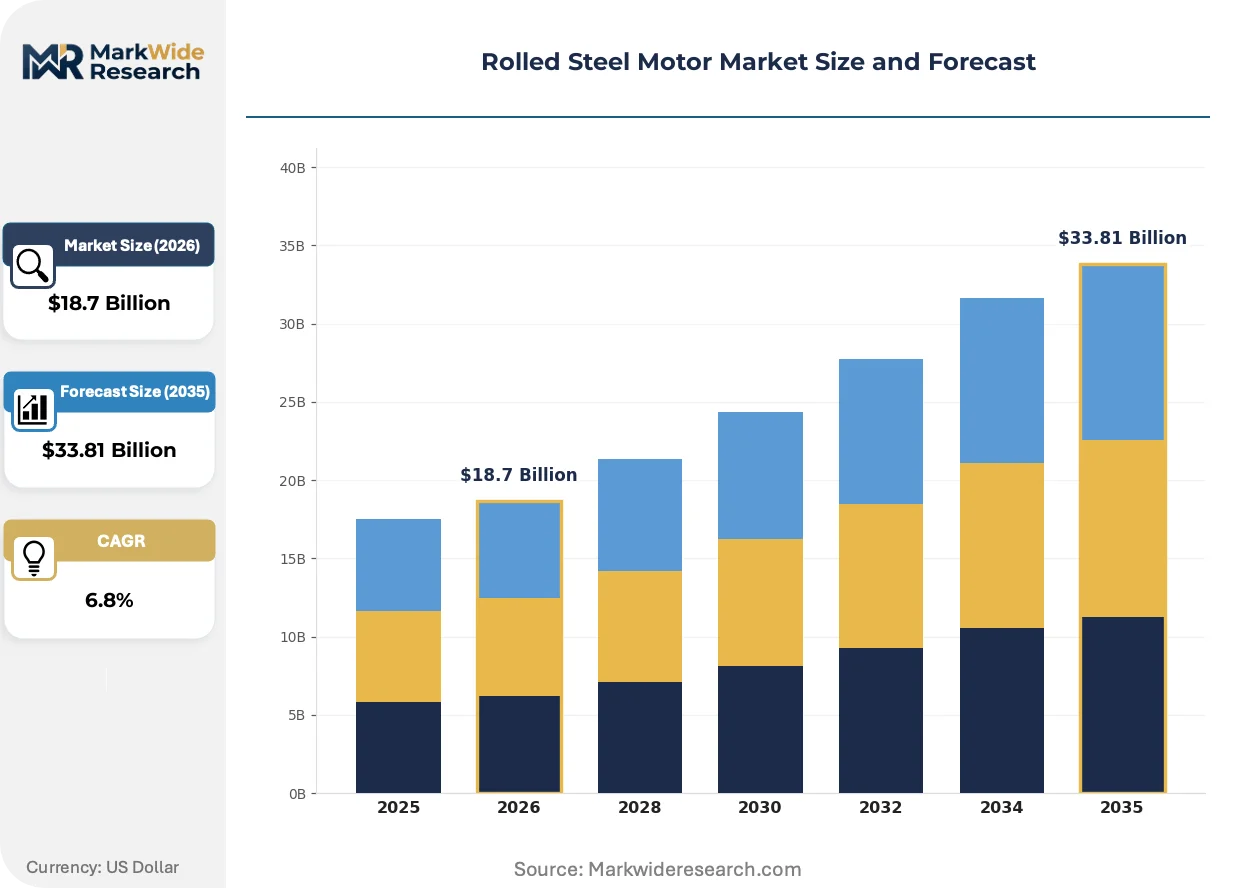
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Stepper Motors, Servo Motors End User: Manufacturing, Automotive OEMs, Energy Sector, HVAC Systems Design Configuration: Shell Type, Disk Type, Frame Type, Fork Type Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | ABB Ltd, Rockwell Automation, Siemens AG, Regal Beloit Corporation, CG Power and Industrial Solutions Limited, General Electric, Hitachi Ltd, Nidec Motor Corporation, Toshiba International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolled Steel Motor Market Evolving Landscape
Permanent magnet-assisted synchronous reluctance technology is altering competitive positioning as manufacturers pursue efficiency gains without full rare-earth dependency. Digital twin simulation and additive manufacturing prototyping compress development cycles for specialized industrial motor configurations.
Axial flux motor topology is decentralizing power density conventions in material handling and robotics applications. Warehouse automation integrators in the Netherlands and South Korea specify pancake-form-factor motors for collaborative robot joints and compact AGV wheel drives. This geometry is decentralizing the traditional dominance of radial flux designs in sub-5kW precision motion segments.
EPA Motor Efficiency Standards under the DOE framework are mandating IE3-equivalent minimums for general-purpose motors from 1-200 horsepower. US metal processing and petrochemical facilities face accelerated replacement schedules for installed base motors rated below the threshold. NEMA Premium efficiency motors now dominate specification sheets for new pump and fan packages across Ohio and Texas refining corridors.
Buyer consolidation among industrial distributors is compressing manufacturer-direct relationships and favoring integrated motion solution providers. Large MRO procurement platforms in Germany and Japan now bundle motor-drive-actuator packages, marginalizing standalone motor catalog sales. Food and beverage processing verticals in California and Bavaria demonstrate the strongest shift toward total-cost-of-ownership purchasing over unit price minimization.
Rolled Steel Motor Market Segmentation
Segmentation in the rolled steel motor market reveals how procurement criteria diverge across application environments. Buyers prioritize efficiency certification tiers in continuous-duty industrial settings, while space constraints and torque density dominate specification sheets in precision automation and building retrofit channels.
Product Type:
Buyers in this category differentiate primarily by maintenance burden and grid compatibility requirements rather than upfront unit cost.
- AC Motors:These units operate directly from alternating-current mains supply without commutation hardware. Manufacturing plants in Germany and export zones across East Asia specify AC motors for conveyor systems and pump drives where operational simplicity outweighs speed control precision.
- Servo Motors:Closed-loop feedback systems with encoder resolution below one arc-minute enable precision positioning in robotic assembly and CNC machining. Korean automotive stamping lines and Dutch warehouse automation integrators accept premium unit economics for trajectory accuracy and dynamic response.
- DC Motors:Brushed and brushless configurations serve battery-powered mobile equipment and legacy process control installations.
- Stepper Motors:Open-loop positioning drives low-cost automation in 3D printing and small-scale packaging machinery.
AC Motors lead volumes today; Servo Motors is gaining share fastest.
End User:
Application environment dictates thermal management specifications, ingress protection ratings, and duty cycle requirements across customer verticals.
- Manufacturing:Metal stamping, textile processing, and material handling operations demand continuous-duty motors with IE3 minimum efficiency. Italian machinery builders and German automotive suppliers drive replacement cycles amid EU Ecodesign tier upgrades.
- HVAC Systems:Disk-type configurations penetrate building automation retrofits where shaft height constraints block conventional frame motor replacements. California and Bavaria processing facilities demonstrate the strongest shift toward total-cost-of-ownership purchasing.
- Automotive OEMs:Stamping press lines and paint shop conveyors require high-torque medium-power units with rapid thermal cycling tolerance.
- Energy Sector:Pump stations and compressor trains in petrochemical corridors specify NEMA Premium efficiency for new installations.
Manufacturing commands the largest installed base; HVAC Systems shows the steepest expansion trajectory.
Design Configuration:
Physical mounting geometry and thermal dissipation architecture separate specifications for heavy industrial versus space-constrained deployments.
- Frame Type:Rigid cast or fabricated steel housings with integral cooling fins dominate heavy manufacturing installations. Structural rigidity and thermal management prove critical in Ohio and Texas refining corridors where NEMA Premium motors now dominate specification sheets.
- Disk Type:Pancake-form-factor motors with axial flux topology serve collaborative robot joints and compact AGV wheel drives. Netherlands and South Korean warehouse automation integrators specify these for material handling decentralization.
- Shell Type:Cylindrical housings with external fan cooling suit general-purpose pump and fan applications.
- Fork Type:Split-bearing mounts enable rapid service access in mining and aggregate processing equipment.
Frame Type anchors current procurement volumes; Disk Type climbs the fastest among emerging geometries.
Power Rating:
Operating cost sensitivity and capital expenditure thresholds stratify buyer behavior across wattage tiers.
- Medium Power:Motors in the 1-200 horsepower range face accelerated replacement schedules under EPA Motor Efficiency Standards. US metal processing facilities must upgrade installed base motors rated below IE3-equivalent minimums.
- High Power:Large synchronous and induction machines above 200 horsepower serve compressor trains and extrusion lines where efficiency gains justify magnetic circuit redesign.
- Low Power:Sub-fractional horsepower units populate appliance and small automation markets with price-sensitive sourcing.
- Ultra High Power:Custom-engineered solutions for steel mill drives and power generation auxiliaries carry extended validation timelines.
Medium Power leads current shipments; High Power shows the strongest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive stamping plants anchor procurement volumes for medium-power industrial motors, with tightening efficiency mandates compressing replacement cycles across major manufacturing clusters in Europe, Asia, and North America.
Germany
Automotive OEMs and machinery builders in Stuttgart and Munich drive demand for IE4-rated motors amid EU Ecodesign tier upgrades. The EU Green Deal accelerates retrofit schedules in Bavarian processing facilities. Siemens AG leverages captive European steel mills to secure laminated core supply chains for regional fabrication centers.
China
Export manufacturing zones in the Yangtze River Delta specify AC motors for conveyor systems and pump drives serving electronics assembly. MIIT efficiency standards and dual carbon goals compel domestic motor producers to redesign magnetic circuits. Nidec Motor Corporation competes through specialized high-efficiency designs for appliance and automotive markets in Shanghai and Shenzhen corridors.
United States
Metal processing and petrochemical facilities in Ohio and Texas refining corridors face accelerated replacement schedules under EPA Motor Efficiency Standards. DOE rules mandate IE3-equivalent minimums for general-purpose motors from 1-200 horsepower. Rockwell Automation serves industrial automation demand across Midwest manufacturing belts.
India
Agricultural pump and compressor demand in Maharashtra and Gujarat attracts motor assembly investments under the PLI scheme for capital goods. CEA regulations and BIS efficiency standards reshape procurement for continuous-duty irrigation equipment. CG Power and Industrial Solutions Limited occupies a position serving domestic industrial motor requirements.
South Korea
Warehouse automation integrators in the Seoul Capital Area and Busan-Ulsan corridor specify disk-type pancake motors for collaborative robot joints and compact AGV drives. METI-aligned efficiency benchmarks influence specification sheets for precision motion equipment. Hitachi Ltd and Toshiba International Corporation exemplify the tier of diversified industrial electrification specialists.
Rolled Steel Motor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue axial flux topologies and predictive maintenance integration. The vendor base stratifies across integrated motion solution providers, captive steel mill operators, and specialized high-efficiency designers. Three archetypes dominate: diversified industrial conglomerates with in-house electrical steel supply, pure-play motor specialists leveraging Asian manufacturing scale, and automation integrators bundling motor-drive-actuator packages. Competitive moves concentrate on backward integration into premium grain-oriented silicon steel and regional fabrication center expansion.
Among European-based industrial conglomerates, ABB Ltd and Siemens AG exemplify the archetype of geographically diversified motor fabricators operating regional production centers across multiple continents. General Electric occupies a position within the North American industrial electrification tier. These anchors represent how scale-driven producers defend margin position through captive supply chain control and multi-continent manufacturing footprints.
| Leading Market Players |
|---|
| ABB Ltd |
| Rockwell Automation |
| Siemens AG |
| Regal Beloit Corporation |
| CG Power and Industrial Solutions Limited |
| General Electric |
| Hitachi Ltd |
| Nidec Motor Corporation |
| Toshiba International Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap motor fabricators in Italy and Japan anchor regional pricing discipline through captive lamination workshops and long-term electrical steel offtake agreements. Their ownership structure insulates procurement decisions from quarterly earnings pressure, enabling sustained investment in grain-oriented silicon steel inventory positions that buffer against commodity volatility.
Pricing Analysis
Electrical steel lamination and copper magnet wire pass-through dominates cost structures, with London Metal Exchange copper benchmarks transmitting directly to winding quotations within thirty-day windows. Pricing stratifies across IE4 premium, IE3 standard, and IE2 economy tiers differentiated by efficiency certification grade and after-sales service bundling. Cost compression in standard-efficiency segments is intensifying because Chinese export manufacturers are absorbing margin erosion to maintain volume share. Agricultural pump distributors in India demonstrate the highest price sensitivity, while German automotive OEMs prioritize total-cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Grain-oriented electrical steel supply rests on integrated steelworks in Japan, South Korea, and Germany, with silicon content refinement and grain orientation processing concentrated among a half-dozen metallurgical specialists. Copper cathode and rare-earth magnet feedstock draw from Chilean mining operations and Chinese separation facilities respectively. Single-source vulnerability in premium lamination steel exposes motor fabricators to alloying element volatility and export licensing disruptions. Distribution runs through industrial MRO platforms and OEM direct procurement channels, with integrated motion solution providers gaining share over standalone motor catalog sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rolled Steel Motor Market functions as a stable compounder underpinned by mandatory efficiency tier upgrades that force replacement cycles regardless of macroeconomic conditions. Regulatory ratcheting across the EU, US, and China ensures continuous demand for higher-efficiency units.
For Market Incumbents: Deploy backward integration into electrical steel lamination to secure core supply against Japanese and Korean mill concentration. Incumbent producers must anchor regional fabrication centers near German automotive clusters and Yangtze Delta export zones to defend against emerging axial flux specialists. Captive silicon steel processing and IE4 certification investment represent the critical defensive levers against margin compression from high-efficiency entrants. For New Entrants and Emerging Players: Capture disk-type axial flux white space in warehouse automation retrofits where pancake form factors bypass radial flux incumbents. New entrants should prioritize South Korean and Dutch integrator relationships for collaborative robot joint specifications. The HVAC retrofit channel offers the most penetrable entry point, with shaft-height-constrained building automation upgrades demanding compact motor geometries that established frame-type producers underserve. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play motor specialists with undifferentiated standard-efficiency portfolios and exposure to copper price volatility. Long-term viability favors producers with captive electrical steel supply or dominant positions in IE4 and IE5 efficiency tiers. Investors should monitor IEC efficiency testing certification backlog durations as the inflection signal—extended validation timelines indicate tightening technical barriers that protect premium-tier incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Captive lamination supply insulates Siemens and ABB against Japanese mill pricing power. |
| IE4 Efficiency Certification Investment | EU Ecodesign tier upgrades compel German automotive stampers to specify premium-tier replacements. |
| Axial Flux Topology Development | Pancake motor geometry penetrates Dutch warehouse automation where radial flux designs fail. |
| Predictive Maintenance Platform Launch | Vibration sensor integration enables Korean automotive lines to shift toward condition-based service contracts. |
| Regional Fabrication Center Expansion | Indian PLI scheme incentives attract assembly investments serving Maharashtra agricultural pump demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and electrical steel mill metallurgists against secondary validation through SEC filings, customs trade data, IEC efficiency certification registries, and EU Ecodesign directive implementation reports. Bottom-up shipment tallies by power rating and frame configuration triangulated against top-down manufacturing value-added estimates across German, Chinese, and US production clusters.
Segment-weighting approaches distributed value and volume projections across AC, servo, and DC motor technologies; frame, disk, shell, and fork design configurations; and manufacturing, HVAC, automotive, and energy end-use verticals throughout the forecast period. CAGRs derived from regression analysis of historical efficiency mandate adoption curves and replacement cycle compression patterns, with electrical steel pricing volatility and copper benchmark trajectories feeding sensitivity scenarios.
Alloying element supply disruptions, unanticipated IEC efficiency testing protocol revisions, and retroactive carbon-border adjustment mechanism implementations are the dominant revision risks to projection assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Osmium Market
Metals
High Purity Boron Market
Metals
Global Brass Rods Market
Metals
North America Electrical Steel Market
Metals
Zirconium Market
Metals
Global Superconducting Wire Market
Metals
Copper Wire Market
Metals
Reconditioned Steel Drums Market
Metals
Global Copper Market
Metals
Silver-Platinum Paste Market
Metals
Armour Steel Plate Market
Metals
Pump Casing Materials Market
Metals
Galvanized Steel Market
Metals
Global Tool Steel Market
Metals
Stainless Steel Foil Market
Metals
North America Metal Finishing Market