
 Armour Steel Plate Market | 2026-2036
Armour Steel Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Armour Steel Plate Market Analysis
Market Context
Project finance structures for defense manufacturing facilities are reconfiguring competitive entry barriers, enabling mid-tier steel producers to secure long-dated offtake contracts without full capital commitment. ArcelorMittal leverages integrated European blast furnace capacity to anchor supply for armored vehicle hull programs. SSAB AB specializes in quenched and tempered grades for Nordic defense contractors. Tata Steel Limited sustains cost-competitive slab supply through captive Indian iron ore access.
Technical Definition and Segment Structure
Armour steel plate denotes alloyed carbon steel engineered to resist ballistic penetration and abrasive wear, typically achieving hardness values between 400 and 600 Brinell through controlled quenching and tempering cycles. Military vehicles consume the dominant volume share, with STANAG 4569 Level 4 plates representing the highest-specification growth corridor. Ballistic steel commands premium positioning against wear-resistant grades due to certification intensity and lot-traceability requirements. The 20-30 mm thickness band captures substantial mining sector demand for haul truck body liners, while sub-10 mm plate serves personal armor applications where weight minimization dictates material selection.
Regulatory Environment and Outlook
EU REACH compliance and the F-Gas Regulation constrain heat-treatment process chemistry, while NATO STANAG standards harmonize ballistic performance benchmarks across member procurement programs. The US Department of Defense MIL-DTL-12560 specification governs domestic armor plate acceptance, creating transatlantic certification divergence. Stakeholders must monitor evolving STANAG revision cycles and carbon-border adjustment mechanisms to align capacity investments with qualifying demand pools.
Market Dynamics
NATO STANAG 4569 certification tightening is compressing supplier qualification timelines while fragmenting procurement across national armored vehicle programs, forcing steel mills to maintain parallel metallurgical certification tracks for allied defense ministries.
Growth Catalysts
- Bundeswehr Modernization:Germany's military vehicle replacement programs are generating sustained demand for ballistic-grade plate, with localized supply chain requirements favoring EU-qualified producers.
- Quenched and Tempering Process Advances:Controlled thermal cycling improvements are expanding the hardness-performance envelope, enabling thinner plates to meet Level 4 penetration resistance.
- MIL-STD-461 Electromagnetic Hardening:US Department of Defense shielding requirements for armored electronics are creating integrated armor-EMI specification demand.
Market Restraints
- Alloy Element Volatility:Molybdenum and nickel price swings from South African and Indonesian concentrate supply disruptions compress rolling margin predictability.
- Blast Furnace Concentration:Integrated steelmaking capacity clusters in Western Europe and India, exposing buyers to single-source geographic risk during trade flow disruptions.
- REACH Process Chemistry Constraints:EU F-Gas Regulation limitations on heat-treatment atmospheres restrict quenching medium options, adding compliance cost layers.
Strategic Opportunities
- Poland Defense Industrial Expansion:Eastern European NATO members are establishing domestic armor plate conversion capacity, creating equipment and technology licensing demand.
- Autonomous Vehicle Hull Integration:Unmanned ground vehicle programs require novel plate geometries and reduced-weight configurations absent legacy turret constraints.
- Carbon Border Adjustment Mechanism:EU CBAM implementation is incentivizing low-carbon primary steel routes, rewarding electric arc furnace-based armor plate producers.
Industry Challenges
- Metallurgical Certification Bottlenecks:STANAG lot-traceability and ballistic testing queue backlogs extend order-to-delivery cycles beyond 18 months for new supplier entrants.
- Heat Treatment Energy Intensity:Quenching and tempering cycles require sustained high-temperature furnace operations, exposing margins to natural gas and electricity tariff volatility.
Report Scope
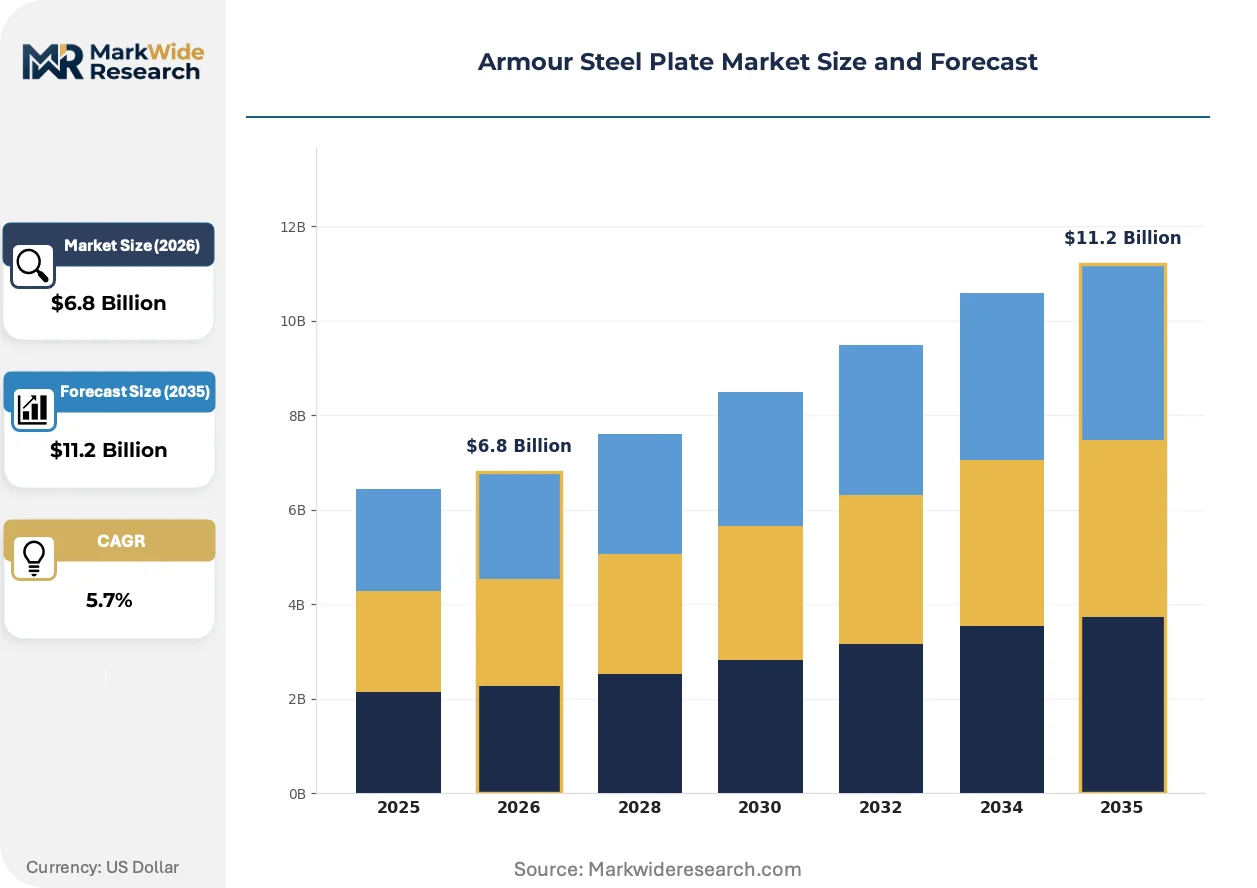
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armour Steel Plate Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Steel, Abrasion-Resistant Steel, Quenched & Tempered Steel, Wear-Resistant Steel Application: Military Vehicles, Personal Armor, Industrial Equipment, Construction Machinery End User: Defense Sector, Construction Industry, Transportation Sector, Mining Sector Thickness: Less than 10 mm, 10-20 mm, 20-30 mm, More than 30 mm |
| Companies Covered | POSCO, United States Steel Corporation, ArcelorMittal, JFE Steel Corporation, Tata Steel Limited, SSAB AB, Nippon Steel Corporation, Evraz, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armour Steel Plate Market Emerging Trajectories
Computational metallurgy and process sensor networks are compressing alloy development cycles while enabling real-time quality assurance, shifting competitive advantage toward data-integrated production systems.
Direct quenching technology integrated with rolling mill heat retention is digitizing microstructure prediction, allowing Swedish and Finnish defense contractors to specify property bands rather than fixed chemistries. Military procurement offices are adopting these digital certificates to accelerate acceptance testing. The shift is compressing qualification overhead for qualified suppliers while raising barriers for conventional batch-process competitors.
EU F-Gas Regulation phase-down schedules are forcing heat-treatment facilities to transition from sulfur hexafluoride and perfluorocarbon-based atmosphere control to nitrogen-hydrogen alternatives. German and French steel service centers are retrofitting furnace systems ahead of 2030 bans. The regulatory pressure is concentrating certified armor plate conversion capacity among capitalized integrated producers capable of absorbing environmental compliance investments.
Defense ministries are consolidating armor plate procurement through framework agreements rather than discrete vehicle program tenders, compressing supplier rosters to pre-qualified mills with established STANAG test history. The UK Ministry of Defence and Dutch Defence Materiel Organisation are piloting multi-year supply contracts indexed to alloy input costs. This concentration is visible across Nordic and Baltic procurement offices seeking supply security amid geopolitical uncertainty.
Armour Steel Plate Market Segmentation
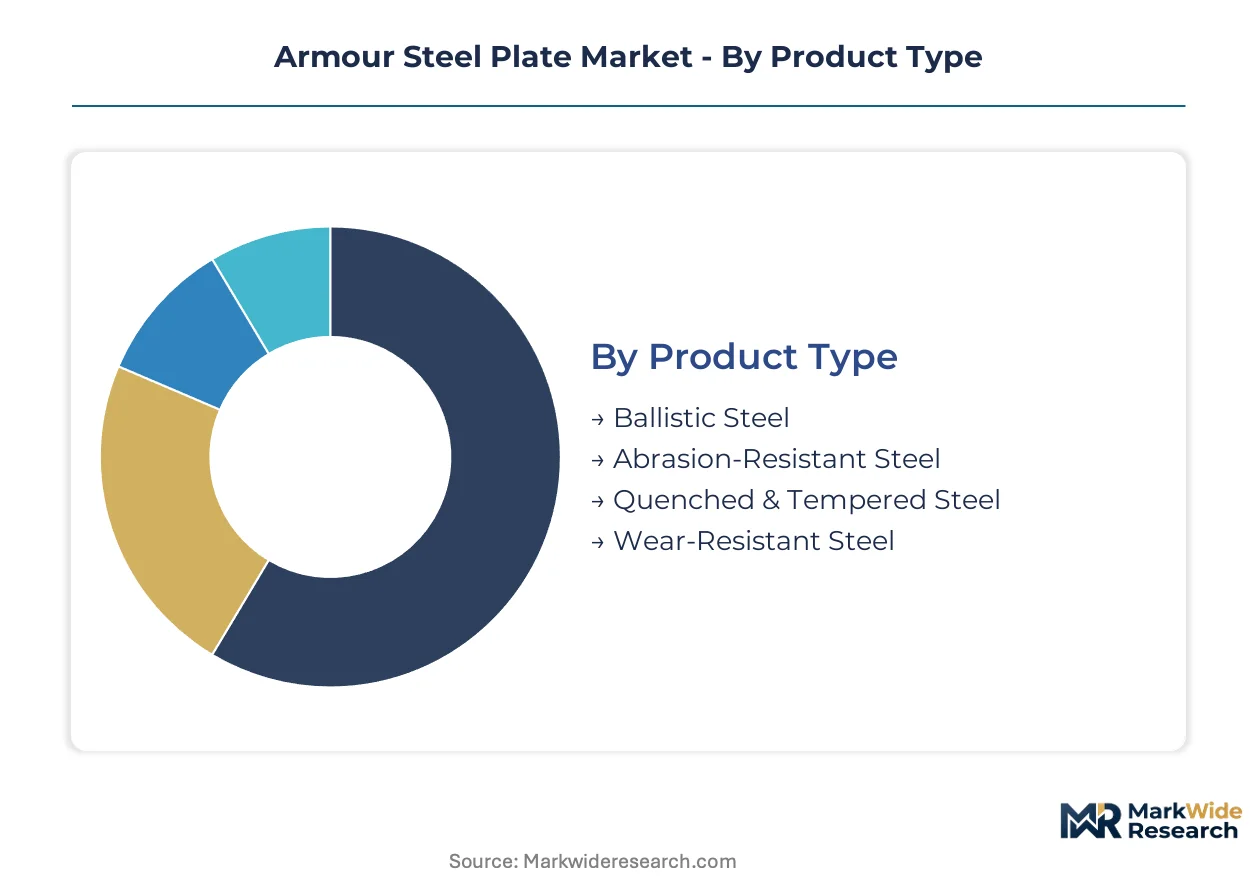
Segmentation in armour steel plate markets reflects divergent certification intensity and procurement cycle lengths. Military-grade specifications impose multi-year qualification timelines, while industrial applications permit faster supplier rotation. Understanding these velocity differences enables capacity planning across metallurgical investment horizons.
Product Type:
Cycle times stretch from six-month industrial qualification to thirty-six-month STANAG certification, creating distinct inventory and margin profiles across alloy categories.
- Ballistic Steel:High-hardness alloyed grades achieving 400-600 Brinell through controlled quenching, with lot-traceability mandates for NATO procurement. German Bundeswehr vehicle programs and Rheinmetall supply localization are concentrating demand for STANAG 4569 Level 4 certified plate.
- Quenched & Tempered Steel:Thermal-cycle engineered microstructures enabling thinner sections to meet penetration resistance thresholds. Swedish and Finnish defense contractors specify property bands rather than fixed chemistries, compressing acceptance testing through digital certificates.
- Abrasion-Resistant Steel:Manganese and boron-alloyed grades prioritizing surface hardness over ballistic performance.
- Wear-Resistant Steel:Lower-specification grades serving mining haul truck body liners with faster replacement cycles.
Ballistic steel dominates installed base value. Quenched and tempered grades are where expansion concentrates.
Application:
Cost tier stratification separates defense-specification premiums from industrial commodity pricing, with certification overhead creating non-overlapping supplier pools.
- Military Vehicles:Hull and turret armor requiring STANAG 4569 or MIL-DTL-12560 certification, with electromagnetic hardening under MIL-STD-461 adding specification layers. Poland's defense industrial expansion and Eastern European NATO procurement are generating sustained order flow for hull-grade plate.
- Personal Armor:Sub-10 mm thickness bands where weight minimization dictates material selection, combining boron carbide ceramic integration with steel backing plates. Body armor procurement cycles run shorter than vehicle programs but require individual lot ballistic testing.
- Industrial Equipment:Excavator buckets and loader blades prioritizing through-hardness over certification documentation.
- Construction Machinery:Structural reinforcement applications with standardized grade acceptance and minimal traceability requirements.
Military vehicles command the highest margin tier. Personal armor is climbing the fastest as lightweight composite-steel hybrids penetrate law enforcement procurement.
End User:
Volume concentration in defense ministries contrasts with fragmented industrial procurement, shaping contract structure from multi-year frameworks to spot-market purchasing.
- Defense Sector:National armored vehicle programs with consolidated framework agreements replacing discrete tenders. UK Ministry of Defence and Dutch Defence Materiel Organisation pilot multi-year supply contracts indexed to alloy input costs, compressing supplier rosters to pre-qualified mills.
- Mining Sector:20-30 mm thickness demand for haul truck body liners with replacement cycles tied to ore abrasion rates rather than ballistic threats. Australian and Chilean open-pit operations drive seasonal procurement patterns.
- Construction Industry:Building reinforcement and protective structures with project-based purchasing and minimal specification overhead.
- Transportation Sector:Rail and commercial vehicle armor with intermediate certification requirements between military and industrial grades.
Defense sector dominates contract value concentration. Mining sector is where volume expansion concentrates.
Thickness:
Supply concentration in integrated blast furnace capacity clusters favors thick-plate production, while thin-plate competition fragments across electric arc furnace and rolling mill configurations.
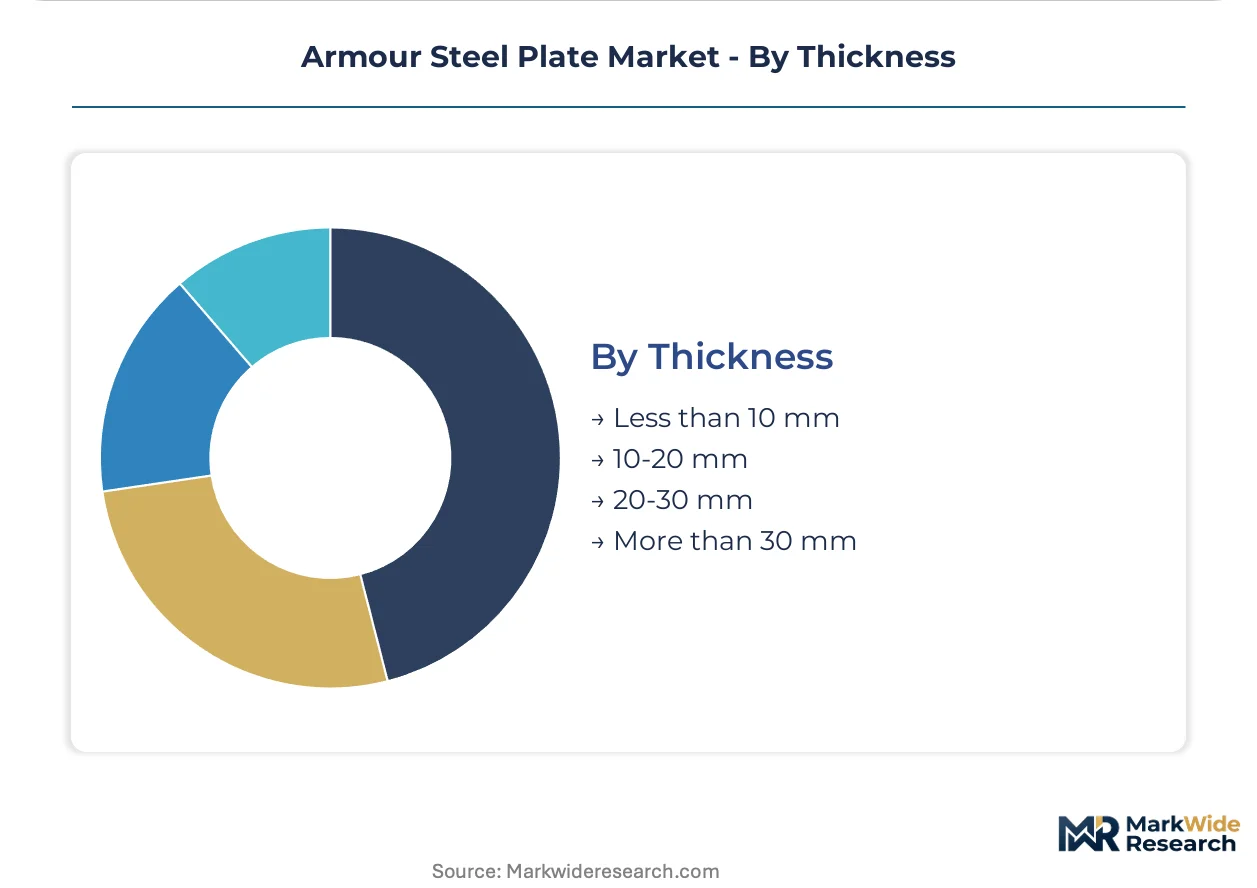
- 20-30 mm:Mining haul truck body liners and medium vehicle hull sections, balancing penetration resistance with fabricability. ArcelorMittal's European blast furnace capacity anchors supply for this thickness band across NATO armored vehicle programs.
- Less than 10 mm:Personal armor and unmanned ground vehicle hulls where reduced-weight configurations absent legacy turret constraints enable novel geometries. Autonomous vehicle programs require these specifications for payload optimization.
- 10-20 mm:Light armored vehicle doors and structural reinforcement panels.
- More than 30 mm:Heavy tank hull and turret applications with limited qualified supplier pools.
20-30 mm thickness dominates current procurement volume. Sub-10 mm plate is where technology-driven substitution concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NATO defense procurement harmonization is redirecting armor steel plate demand toward qualified suppliers within allied territories. National vehicle modernization programs and tightening STANAG certification requirements are reshaping regional supply chain configurations.
Germany
Bundeswehr military vehicle replacement programs are sustaining elevated demand for STANAG 4569 Level 4 certified plate. The F-Gas Regulation constrains heat-treatment atmosphere options, adding compliance cost layers for domestic converters. Rheinmetall's supply chain localization concentrates procurement in North Rhine-Westphalia and Lower Saxony steel service centers.
United States
Department of Defense armored vehicle procurement under MIL-DTL-12560 specifications anchors demand for domestic-qualified mills. MIL-STD-461 electromagnetic hardening requirements add specification layers for integrated armor-EMI solutions. Pittsburgh-centered integrated steel capacity and Alabama rolling mill complexes supply hull-grade plate for ground vehicle programs.
Poland
Eastern European NATO defense industrial expansion is generating sustained order flow for hull-grade plate conversion capacity. EU REACH compliance and carbon-border adjustment mechanisms shape import sourcing decisions. Domestic fabrication clusters in Silesia and Greater Poland are establishing armor plate processing facilities to capture localized procurement.
Sweden
Nordic defense contractors specify quenched and tempered grades through property-band digital certificates rather than fixed chemistries. SSAB AB's integrated blast furnace and direct quenching technology anchor regional supply for armored vehicle hulls. Scanian steel service centers compress acceptance testing timelines through computational metallurgy adoption.
India
Tata Steel Limited's captive iron ore access sustains cost-competitive slab supply for domestic armored vehicle programs. BIS certification requirements and defense procurement localization policies favor qualified domestic producers. Jamshedpur-centered integrated steelmaking capacity supplies thick-plate demand for military vehicle hull fabrication.
Armour Steel Plate Market Vendor Landscape
On the supply side, the industry is consolidating around integrated steel producers with blast furnace capacity and established STANAG certification histories. Tiered competitive structure separates capitalized multi-metals conglomerates from specialized quenched-and-tempered processors and regional conversion specialists. Two strategic archetypes dominate: integrated primary steelmakers leveraging captive raw material access, and technology-focused mills deploying direct quenching and computational metallurgy. Competitive moves center on environmental compliance investments ahead of EU F-Gas Regulation phase-downs and framework agreement positioning with defense procurement offices.
Among integrated steel producers, ArcelorMittal anchors European supply through blast furnace capacity clustered in Western Europe, while POSCO exemplifies scale-driven Asian production. Tata Steel Limited occupies a position linking captive Indian iron ore access to cost-competitive slab supply. SSAB AB represents the technology-focused archetype, with Swedish and Finnish defense contractors leveraging its direct quenching capabilities for property-band specification contracts.
| Leading Market Players |
|---|
| POSCO |
| United States Steel Corporation |
| ArcelorMittal |
| JFE Steel Corporation |
| Tata Steel Limited |
| SSAB AB |
| Nippon Steel Corporation |
| Evraz |
| Thyssenkrupp AG |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European blast furnace capacity is compressing rolling margins for STANAG-certified plate while amplifying pricing power for integrated producers with established defense ministry framework agreements. This utilization dynamic rewards mills with captive raw material access and parallel certification tracks across NATO procurement offices.
Pricing Analysis
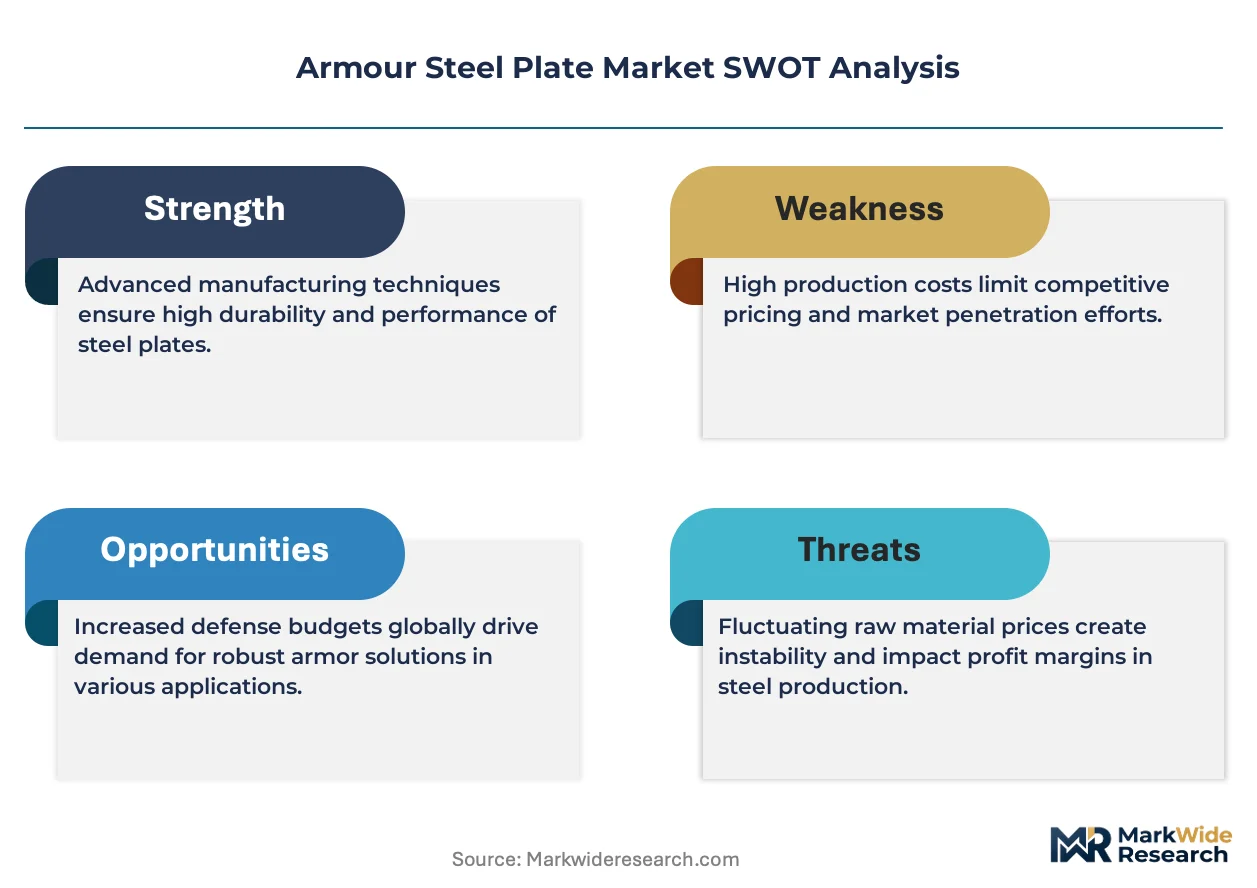
Certification level creates the primary spread across the armour steel plate market, with STANAG 4569 Level 4 qualified material commanding substantial premiums over industrial wear-resistant grades. Contract-based long-term offtake agreements dominate defense procurement, indexed to molybdenum and nickel input costs to buffer alloy element volatility. Cost compression in standard industrial grades is intensifying as South African concentrate supply disruptions feed through to rolling margins. Mining sector buyers exhibit highest price sensitivity due to replacement-cycle purchasing tied to ore abrasion rates rather than ballistic threats.
Supply Chain Analysis
Tariff exposure between EU member states and third-country slab suppliers dominates supply chain risk calculus for armor plate converters. Production gravity centers on Germany, Sweden, and India, with integrated blast furnace capacity in Western Europe and Jamshedpur-centered steelmaking anchoring thick-plate supply. Molybdenum concentrate from South Africa, nickel from Indonesia, and captive Indian iron ore constitute critical input dependencies. Single-source geographic risk concentrates during trade flow disruptions. Distribution runs through defense ministry framework agreements and Rheinmetall-localized service centers rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating across NATO defense ministries through multi-year framework agreements, compressing supplier rosters to pre-qualified mills with established STANAG test histories and fragmenting access for unqualified entrants.
For Market Incumbents: Pre-empt emerging competition from Polish and Eastern European conversion capacity by deepening direct quenching technology investments and securing exclusive property-band specification contracts with Nordic defense contractors. Accelerate F-Gas Regulation compliance retrofits ahead of 2030 bans to capture stranded competitor capacity. Prioritize electromagnetic hardening certification under MIL-STD-461 to anchor integrated armor-EMI specification demand from US Department of Defense procurement. For New Entrants and Emerging Players: Build out autonomous ground vehicle hull fabrication capabilities targeting sub-10 mm thickness specifications where legacy turret constraints are absent and novel geometries command design premiums. Poland's defense industrial expansion offers the most penetrable geographic entry point, with Silesian and Greater Poland fabrication clusters establishing armor plate processing facilities. Pursue technology licensing arrangements with Swedish direct quenching specialists rather than greenfield metallurgical qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat-treatment facility retrofits and STANAG certification queue investments, favoring electric arc furnace-based producers with lower carbon-border adjustment exposure. Target acquisition archetypes include regional conversion specialists with dormant STANAG test histories and stranded capacity in F-Gas-compliant jurisdictions. Watch for inflection signals in EU CBAM implementation schedules and STANAG revision cycle announcements that would revalue low-carbon primary steel routes.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Quenching Technology Deployment | Enables property-band digital certificates that compress Swedish and Finnish defense contractor acceptance testing timelines. |
| F-Gas Regulation Compliance Retrofit | Concentrates certified conversion capacity among capitalized German and French integrated producers ahead of 2030 bans. |
| STANAG 4569 Level 4 Certification Investment | Secures access to Bundeswehr vehicle replacement programs and Rheinmetall supply chain localization requirements. |
| Carbon Border Adjustment Mechanism Positioning | Rewards electric arc furnace-based armor plate producers with lower embedded carbon intensity in EU procurement. |
| Autonomous Vehicle Hull Geometry Development | Captures unmanned ground vehicle program demand for reduced-weight configurations absent legacy turret constraints. |
Methodological Framework
A standing panel of defense procurement officers, steel mill technical directors, heat-treatment facility operators, and NATO standardization engineers provided ongoing calibration across the primary research phase. Primary interviews with these stakeholders were cross-validated against secondary sources including STANAG revision documentation, EU F-Gas Regulation phase-down schedules, SEC filings from integrated steel producers, and customs data tracking alloy concentrate trade flows. Bottom-up volume modeling across thickness bands and certification tiers was triangulated with top-down defense budget allocation analysis.
Scenario-bracketing around alloy price volatility, STANAG certification timeline compression, and carbon-border adjustment implementation schedules framed the analytical approach across the projection horizon. Segmentation dimensions modeled included product type (ballistic, quenched and tempered, abrasion-resistant), application (military vehicles, personal armor, industrial equipment), thickness band, and end-user sector. CAGRs were derived from regression analysis against defense procurement cycle data and mining equipment replacement rates. Forecast inputs incorporated blast furnace capacity utilization signals and F-Gas Regulation compliance investment trajectories.
Stress conditions across molybdenum-nickel price spreads, STANAG testing queue backlogs, and EU CBAM carbon price trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO procurement harmonization and defense ministry framework agreement adoption. Specific risks that could revise projections include unilateral STANAG specification changes, South African concentrate supply disruptions, and accelerated F-Gas Regulation phase-down schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Medical Metal Tubing Market
Metals
Ruthenium Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Stainless Steel Sheet Market
Metals
Chrome Metal Powder Market
Metals
Global Flat Carbon Steel Market
Metals
Base Metals Market
Metals
Aluminum Ingots Market
Metals
Copper Clad Aluminum Wire Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Aluminium Conductors Market
Metals
Brazil Aluminum Market
Metals
Ferro Vanadium Market
Metals
High Purity Iron Powder Market
Metals
Zirconium Market