
 Cosmetics Contract Manufacturing Market | 2026-2036
Cosmetics Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics Contract Manufacturing Market Insights
Market Context
Indie beauty and direct-to-consumer brands is expanding their share of contract manufacturing volumes as legacy houses reduce in-house capacity. Intercos leverages its European formulation centers to serve prestige skincare clients across multiple continents. Cosmax anchors Asia-Pacific production networks with dedicated facilities for K-beauty and J-beauty brands. Kolmar Korea dominates high-volume color cosmetics through integrated packaging and filling lines.
Technical Definition and Segment Structure
Cosmetics contract manufacturing encompasses the outsourced production of finished beauty products, including emulsion-based skincare with specified viscosity ranges, pressed powder formulations, and alcohol-based fragrance compounds meeting IFRA standards. The primary commercial purpose is enabling brand owners to scale production without capital-intensive facility investments. Private label manufacturing leads volume throughput as mass-market retailers seek rapid product turnaround, while custom formulation captures margin concentration through proprietary active ingredient development. Skincare commands the fastest structural expansion due to clinical-grade ingredient complexity and shorter innovation cycles than color cosmetics.
Regulatory Framework and Outlook
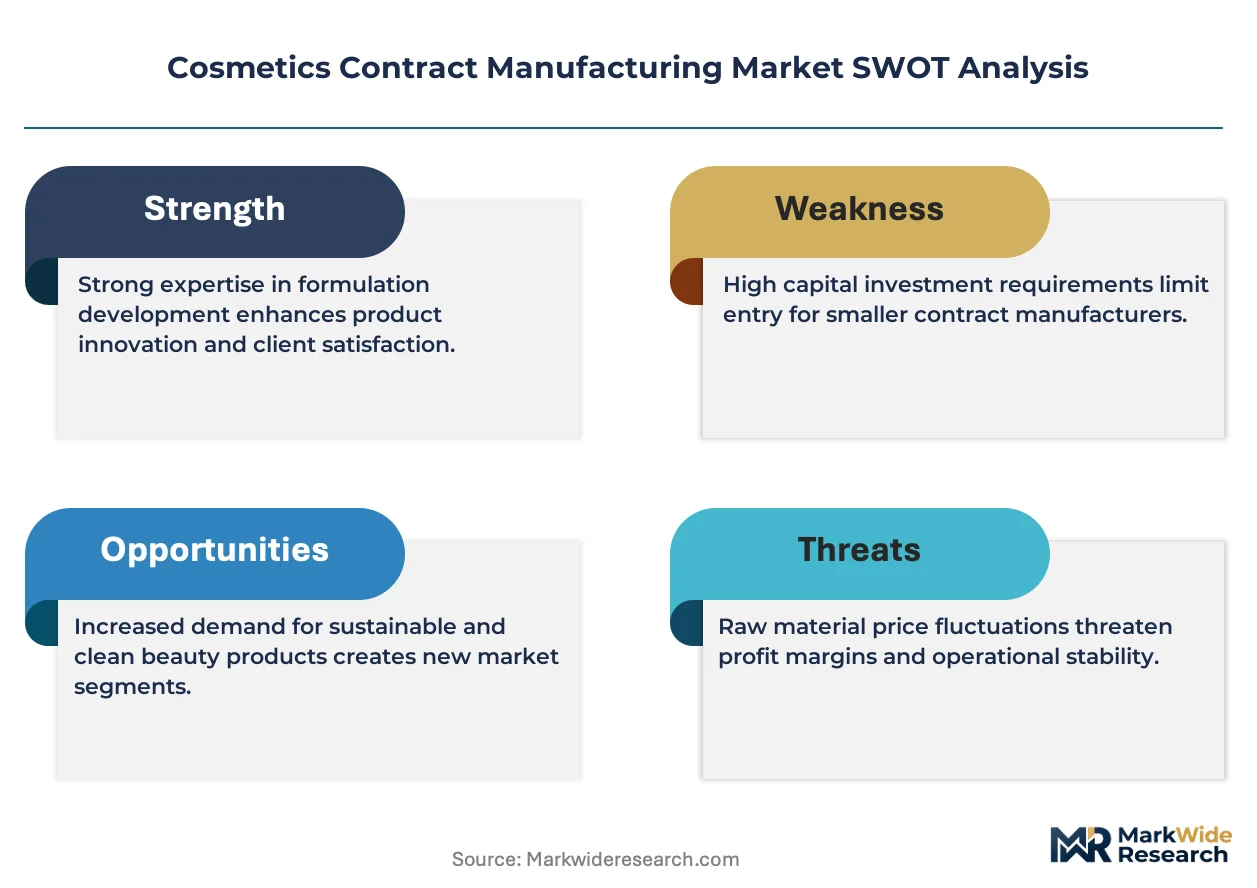
The EU REACH regulation and the US FDA's Modernization of Cosmetics Regulation Act (MoCRA) impose escalating documentation burdens on contract manufacturers, particularly around fragrance allergen labeling and facility registration. ISO 22716 Good Manufacturing Practices for cosmetics now functions as a baseline qualification for supplier approval by multinational brand owners. Stakeholders must monitor how divergent US and EU safety substantiation requirements reshape facility certification investments and geographic sourcing decisions.
Market Dynamics
Indie beauty brands are compressing product development cycles from eighteen months to under six months, forcing contract manufacturers to reconfigure formulation workflows and accelerate batch turnaround protocols.
Growth Catalysts
- MoCRA facility registration mandates:The US FDA's Modernization of Cosmetics Regulation Act requires domestic and foreign manufacturers to register facilities and list products, driving indie brands toward established contract partners with compliant infrastructure.
- Biotech-derived active ingredients:Fermentation-based ceramides and peptide complexes enable clinical-grade claims without pharmaceutical manufacturing overhead, attracting prestige skincare brands to specialized contract labs.
- Seoul production clustering:South Korean manufacturers anchor K-beauty supply chains with integrated formulation-to-packaging capabilities, capturing outsourced volumes from North American and European indie labels seeking speed-to-market.
Market Restraints
- Fragrance allergen labeling complexity:EU REACH requirements for 26 allergen disclosures on-pack increase formulation revision cycles and limit fragrance house flexibility in mass-market production runs.
- Specialty chemical concentration:A handful of German and Swiss suppliers dominate clinical-grade hyaluronic acid and retinol precursor markets, creating input cost volatility when capacity constraints emerge.
- Waterless formulation limitations:Powder-to-foam and anhydrous balm technologies face stability challenges in hot-fill manufacturing lines designed for traditional emulsions, restricting process flexibility.
Strategic Opportunities
- India domestic market penetration:The country's PLI scheme for personal care manufacturing offers fiscal incentives for contract facilities serving both local brands and export markets.
- Refill and reuse systems:Concentrate pods and aluminum cartridge formats align with EU Green Deal circular economy targets while opening premium pricing tiers for sustainable packaging partners.
- AI-driven formulation screening:Machine learning platforms predicting ingredient compatibility and stability are converging with robotic dispensing systems to compress R&D timelines for custom skincare development.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation scientists with dual expertise in clean-label compliance and clinical active delivery systems command premium compensation, straining mid-tier manufacturer margins.
- ISO 22716 certification timelines:Good Manufacturing Practice audits for cosmetics require twelve-to-eighteen-month preparation cycles, delaying supplier qualification for brands with aggressive launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics Contract Manufacturing Market |
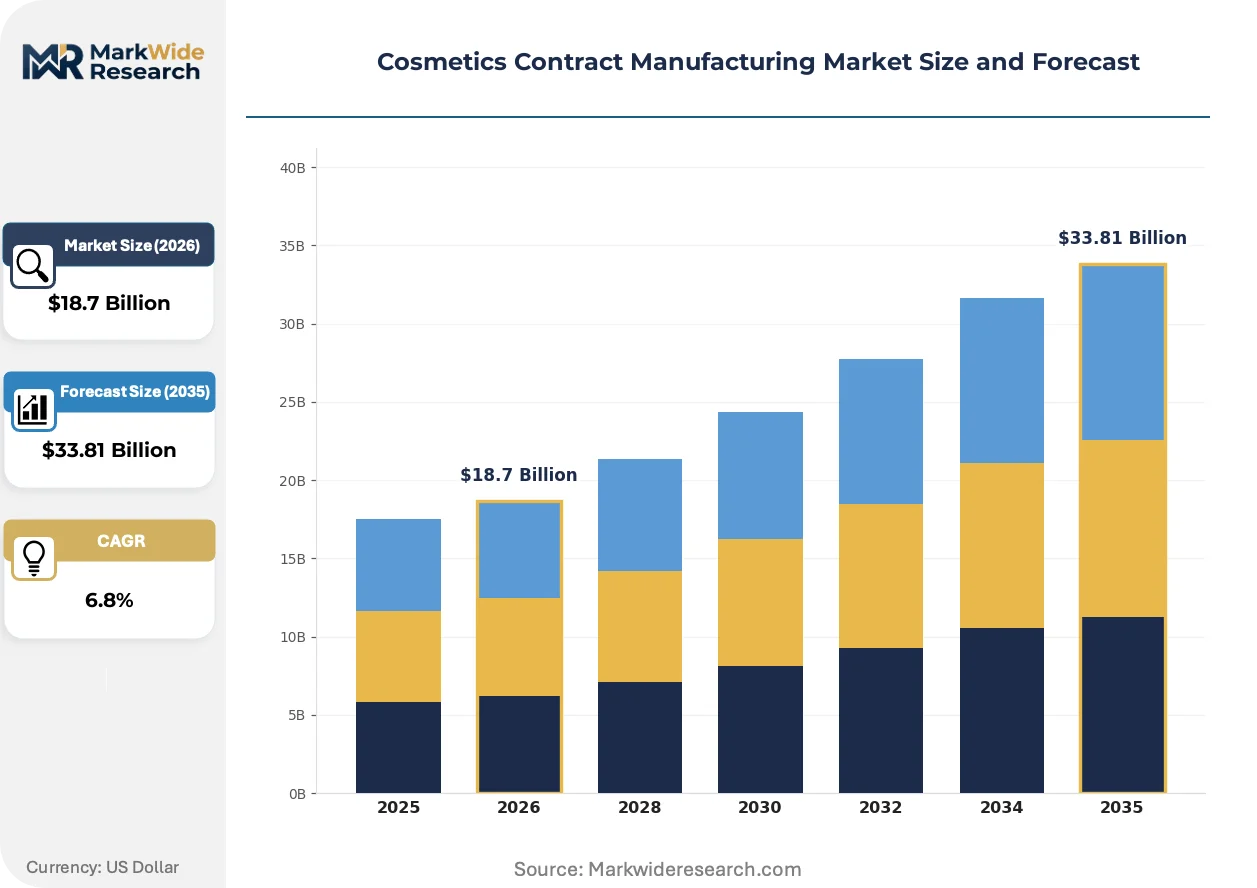
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Manufacturing Process: Private Label, Custom Formulation, Bulk Manufacturing, Toll Manufacturing Packaging Type: Tubes, Bottles, Jars, Pouches End User: Retailers, Brands, Distributors, E-commerce |
| Companies Covered | Kolmar Korea, Intercos, Cosmax, KDC/One, Cosmetic Group USA, Voyant Beauty, Cosmopak, Mana Products, HSA Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics Contract Manufacturing Market Trends and Innovations
Biotechnology and artificial intelligence are restructuring how contract manufacturers develop, validate, and scale cosmetic formulations. These shifts compress innovation timelines while raising technical barriers to entry.
Precision fermentation for cosmetic actives is overtaking traditional botanical extraction and petrochemical synthesis in high-margin skincare categories. Indie brands with clinical positioning now specify ceramides, squalane, and peptides from engineered yeast strains. This biotechnology shift enables carbon-neutral supply chain claims while locking contract manufacturers into multi-year partnerships with specialized biotech suppliers.
REACH authorization requirements for fragrance allergens are tightening documentation burdens across EU-facing production lines. Contract manufacturers must now maintain substance-by-substance safety dossiers extending back through raw material supply chains. Prestige fragrance houses are responding by consolidating supplier bases to reduce traceability complexity, favoring large integrated manufacturers over fragmented specialty houses.
Direct-to-consumer subscription models are compressing batch size economics and forcing manufacturing flexibility investments. Beauty brands now demand production runs as small as five hundred units with four-week turnaround, displacing traditional ten-thousand-unit minimums. This demand pattern shift is most visible in North American indie skincare, where micro-influencer launches drive volatile demand spikes requiring agile contract manufacturing partnerships.
Cosmetics Contract Manufacturing Market Segmentation
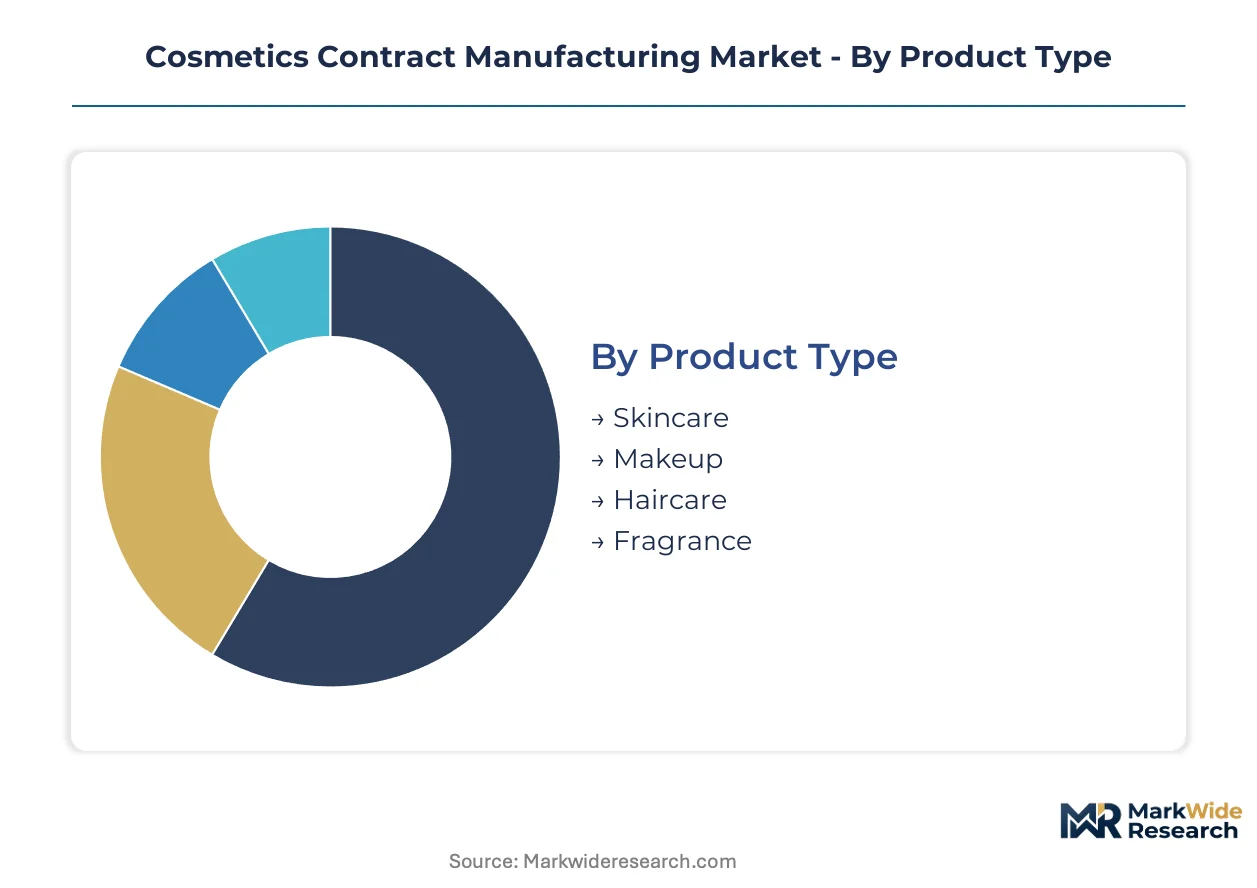
Segmentation in cosmetics contract manufacturing reveals how buyer priorities diverge across product complexity, regulatory burden, and speed-to-market requirements. Each dimension shapes facility investment decisions and partnership structures differently.
Product Type:
Buyers select manufacturing partners based on formulation complexity and clinical claim substantiation requirements.
- Skincare:Emulsion-based formulations with specified viscosity ranges and pH stability requirements dominate clinical-grade outsourcing. Demand concentrates in Seoul and Incheon manufacturing clusters where K-beauty brands compress development cycles for ceramide and peptide-based products.
- Makeup:Pressed powder formulations and liquid color cosmetics require integrated filling and packaging lines with shade-matching precision. Prestige brands in France and Italy drive outsourcing for complexion products with skincare-infused positioning.
- Haircare:Surfactant-based cleansers and conditioning emulsions with silicone-free positioning.
- Fragrance:Alcohol-based compounds meeting IFRA standards with REACH allergen documentation.
Skincare leads on scale; makeup leads on momentum.
Manufacturing Process:
Cost tier determines whether brands prioritize speed, exclusivity, or capital efficiency in partner selection.
- Private Label:Pre-developed formulations with minimal customization enable mass-market retailers to launch products within eight weeks. North American drugstore chains and European supermarket labels drive volume through this low-investment pathway.
- Custom Formulation:Proprietary active ingredient development and stability testing for differentiated positioning. Indie beauty brands in the United States and United Kingdom concentrate demand here for biotech-derived ceramides and peptide complexes.
- Bulk Manufacturing:Large-scale production of base formulations without final packaging or branding.
- Toll Manufacturing:Client-supplied raw materials processed through contracted equipment and labor.
Private label dominates volume throughput; custom formulation captures margin concentration.
Packaging Type:
Application method and sustainability positioning guide material selection and line configuration decisions.
- Tubes:Laminated and mono-material structures for cleansers, lotions, and sun care with squeeze-dispensing functionality. European brands pursuing EU Green Deal compliance drive demand for aluminum-barrier and paper-based tube alternatives.
- Bottles:PET, glass, and post-consumer recycled formats for serums, toners, and liquid formulations. South Korean manufacturers specialize in airless pump bottles for oxidation-sensitive actives serving export markets.
- Jars:Wide-mouth containers for balms, masks, and rich creams requiring finger or spatula access.
- Pouches:Flexible single-use and refill formats for travel-size and sustainable sampling applications.
Bottles anchor production scale; tubes are expanding most quickly on sustainability-driven reformulation.
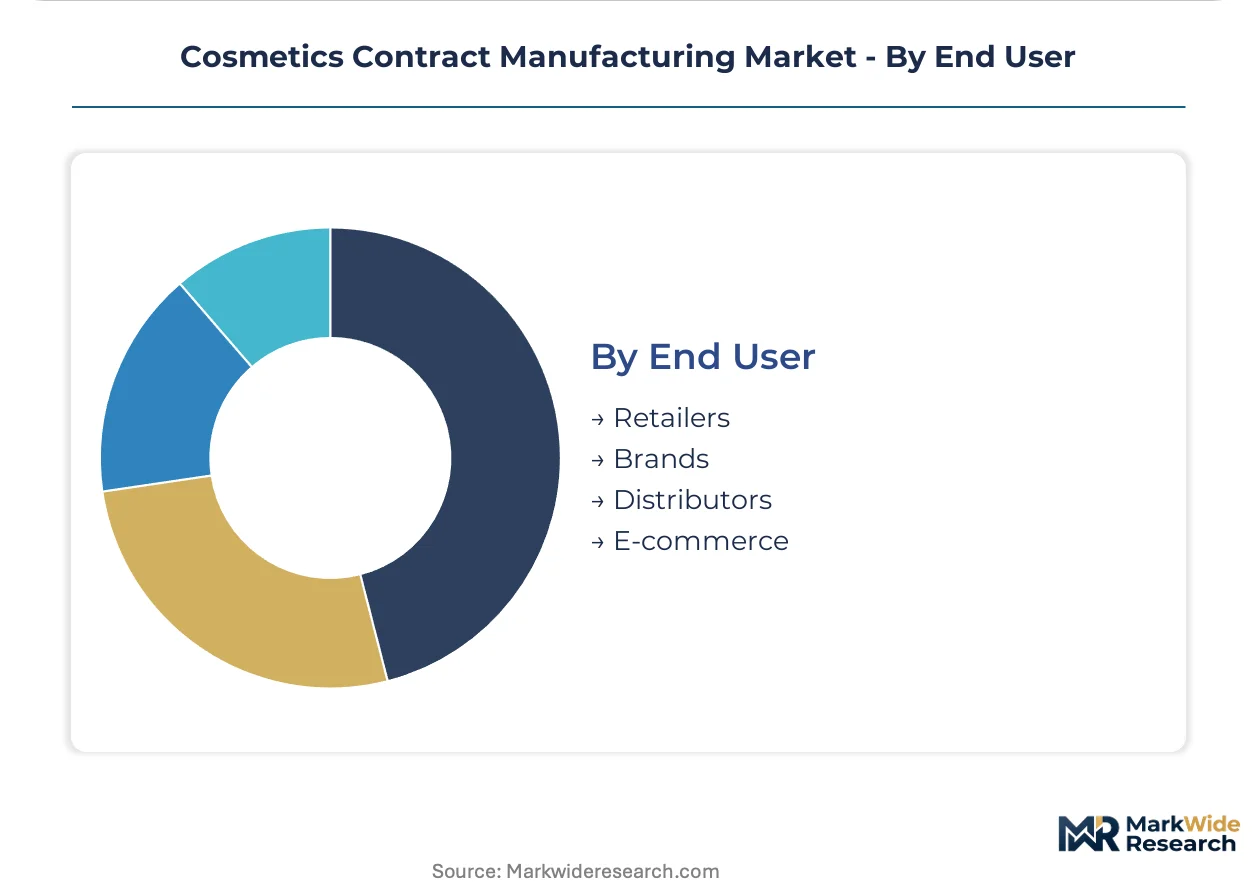
End User:
Customer type determines batch size economics, regulatory documentation depth, and speed requirements.
- Retailers:Mass-market chains and specialty beauty stores requiring rapid private-label turnaround with five-hundred-unit minimums. North American and European retailers compress development timelines to match seasonal merchandising cycles.
- Brands:Indie labels and direct-to-consumer houses outsourcing entire production without captive manufacturing. Seoul-based contract manufacturers capture disproportionate share from these clients seeking K-beauty formulation credibility.
- Distributors:Wholesalers sourcing finished goods for multi-territory resale with localized labeling.
- E-commerce:Pure-play digital brands with volatile demand spikes and subscription-model replenishment.
Retailers command volume concentration; brands drive the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions where REACH compliance costs and MoCRA facility registration burdens diverge, creating arbitrage opportunities for brands seeking speed-to-market without regulatory overhead.
United States
Indie beauty brands and direct-to-consumer labels drive contract manufacturing demand as MoCRA mandates facility registration and product listing with FDA. The regulation forces smaller brands toward established partners with compliant infrastructure rather than captive facilities. New Jersey and California host concentrated manufacturing clusters serving prestige skincare and color cosmetics markets.
South Korea
Seoul-based manufacturers anchor global K-beauty supply chains through integrated formulation-to-packaging capabilities serving North American and European indie labels. MFDS cosmetic safety standards and rapid innovation cycles compress development timelines for ceramide and peptide-based products. Incheon manufacturing corridors specialize in airless pump systems for oxidation-sensitive actives.
Italy
Prestige fragrance and complexion product outsourcing concentrates in Lombardy and Piedmont, where IFRA-compliant alcohol-based compounds and pressed powder formulations serve French and domestic luxury houses. ANSM fragrance allergen documentation requirements align with REACH substance-by-substance safety dossiers. Milan-area facilities specialize in skincare-infused color cosmetics with clinical-grade positioning.
Germany
Clinical-grade hyaluronic acid and retinol precursor supply chains concentrate among specialized chemical suppliers serving contract manufacturers across skincare segments. BfR safety assessments and REACH authorization requirements tighten documentation burdens for EU-facing production lines. Hamburg and Düsseldorf clusters focus on private-label manufacturing for mass-market retail chains.
India
The PLI scheme for personal care manufacturing offers fiscal incentives attracting contract facilities serving domestic brands and export markets. CDSCO cosmetic registration requirements and state-level manufacturing policies reshape facility investment decisions. Maharashtra and Gujarat industrial corridors develop capacity for surfactant-based haircare and emulsion skincare production.
Cosmetics Contract Manufacturing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with prestige skincare favoring integrated formulation partners while mass-market color cosmetics concentrate among high-volume filling operations. The vendor base organizes into three tiers: multinational full-service houses with continental coverage, regional specialists dominating single geographies, and boutique labs serving indie brands with custom development. Consolidation pressures intensify as ISO 22716 certification requirements and biotech ingredient partnerships raise capital barriers. Geographic expansion and strategic technology licensing represent the dominant competitive moves as players seek REACH-compliant EU capacity and Seoul-adjacent K-beauty credibility.
Within the Asia-Pacific specialist tier, Kolmar Korea and Cosmax occupy positions exemplifying high-volume color cosmetics integration and K-beauty formulation credibility respectively. Intercos represents the European full-service archetype with multi-continental prestige skincare coverage. These three anchors illustrate how geographic clustering around regulatory hubs and ingredient supply chains determines competitive positioning without requiring specific operational claims about individual facilities.
| Leading Market Players |
|---|
| Kolmar Korea |
| Intercos |
| Cosmax |
| KDC/One |
| Cosmetic Group USA |
| Voyant Beauty |
| Cosmopak |
| Mana Products |
| HSA Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Indie beauty brands demanding sub-six-month development cycles are forcing contract manufacturers to absorb expedited formulation costs and specialized biotech ingredient premiums that compress margins across mid-tier facilities.
Pricing Analysis
Distributor margins for finished cosmetics typically absorb 35-50 points before retail markup, creating a three-tier pricing structure across premium, standard, and economy levels that stratifies by ISO 22716 certification grade and volume commitment. Custom formulation services with proprietary active development command substantial premiums over private-label throughput, while pricing pressure stems from compressed batch economics as brands demand 500-unit minimums versus traditional 10,000-unit runs. Mass-market retailers exhibit highest price sensitivity due to thin private-label margins, whereas prestige skincare brands prioritize speed and clinical-grade substantiation over unit cost.
Supply Chain Analysis
Clinical-grade hyaluronic acid and retinol precursor supply rests on German and Swiss specialty chemical producers, with fermentation-derived ceramides and peptide complexes increasingly sourced from South Korean biotech suppliers. Fragrance compound supply draws from IFRA-compliant houses concentrated in France and Italy, while packaging components—airless pumps, aluminum tubes, mono-material bottles—feed from Chinese and South Korean molding facilities. Single-source vulnerability in high-purity active ingredients creates exposure when capacity constraints emerge at specialty chemical suppliers. Distribution runs through brand-direct fulfillment centers for indie labels and consolidated retail distribution networks for mass-market chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by indie beauty's pivot toward clinical-grade ingredient substantiation and biotech-derived actives that command premium positioning.
For Market Incumbents: Anchor K-beauty formulation credibility through Seoul-adjacent facility investments or strategic licensing partnerships with established Korean manufacturers. ISO 22716 certification and REACH-compliant documentation infrastructure defend against regulatory escalation while biotech supplier exclusivity agreements lock in fermentation-derived active supply chains threatened by capacity constraints. For New Entrants and Emerging Players: Enter via India's PLI scheme for personal care manufacturing, where fiscal incentives and underdeveloped contract manufacturing infrastructure create white-space opportunity in surfactant-based haircare and emulsion skincare. Target domestic Indian brands seeking export-grade production standards with toll manufacturing models that minimize capital intensity while building regulatory compliance track records. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique custom formulation labs possessing biotech supplier partnerships and ISO 22716 certification in progress. Long-term viability favors facilities with demonstrated agility in sub-1000-unit production runs and documented REACH compliance infrastructure. Watch for MoCRA facility registration deadline enforcement as inflection indicator for compliance-capable asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Supplier Partnership | Fermentation-derived ceramide access enables carbon-neutral supply chain claims for prestige skincare brands. |
| ISO 22716 Certification Investment | Good Manufacturing Practice qualification opens multinational brand owner procurement pipelines and defends margin position. |
| Seoul-Adjacent Facility Expansion | Proximity to K-beauty innovation clusters compresses development timelines for North American and European indie labels. |
| Refill System Packaging Line | Aluminum cartridge and concentrate pod formats align with EU Green Deal circular economy targets. |
| AI-Driven Formulation Platform | Machine learning screening converges with robotic dispensing to compress R&D timelines for custom skincare development. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with contract manufacturing executives, cosmetic chemists, indie brand founders, and procurement leads at multinational beauty houses with secondary validation from FDA MoCRA facility registration databases, ECHA REACH substance dossiers, and MFDS cosmetic safety filings. Customs records for cosmetic ingredient trade flows, SEC filings from publicly traded manufacturing groups, and ISO certification registries provided bottom-up volume anchors triangulated against top-down market sizing.
Historical reference periods anchored the projection horizon across product type, manufacturing process tier, packaging format, and end-user category segmentation dimensions. CAGRs were derived through regression analysis of facility capacity expansion announcements, ingredient supplier capacity utilization indicators, and brand outsourcing intensity patterns. Forecast inputs incorporated REACH authorization timelines for fragrance allergens, MoCRA facility registration compliance rates, and biotech-derived active ingredient adoption curves in prestige skincare.
Inputs from regulatory filing databases and supplier capacity announcements were available through the study window; gaps in private-label contract terms and undisclosed biotech supplier pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions about regulatory enforcement intensity and indie brand outsourcing penetration. Regulatory deadline delays, biotech fermentation yield breakthroughs, or major brand insourcing decisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Anti-Aging Serums Market