
 Lithium Foil Market | 2026-2036
Lithium Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Foil Market Outlook
Buyer concentration in the automotive sector is restructuring procurement dynamics across the lithium foil value chain as cell manufacturers consolidate supplier rosters. Tianqi Lithium leverages its spodumene-to-foil integration to secure captive feedstock for thin-foil output. Albemarle Corporation anchors North American supply through its Silver Peak brine operations and downstream refining footprint. Ganfeng Lithium dominates Asian spot markets with vertical control over African hard-rock offtake.
Lithium foil is a metallic lithium product rolled to thicknesses typically below 150 micrometers, with battery-grade variants requiring sodium content below 200 parts per million and oxygen-controlled surfaces for stable solid-electrolyte interface formation. The material serves primarily as anode material in next-generation solid-state and lithium-metal batteries where conventional graphite cannot achieve target energy densities. Battery Grade product lines command the deepest margin pools as automotive cell makers qualify suppliers against NMPA and OEM-specific protocols. Thin Foil formats are outpacing Thick Foil in volume growth due to solid-state battery designs demanding sub-50-micrometer layers. Composite Foil variants incorporating copper or polymer substrates represent an emerging architecture for dendrite suppression.
China's NMPA enforces GB/T standards for lithium metal purity in electrochemical applications, while the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that reshape material sourcing economics. The US EPA and OSHA jointly govern lithium handling facilities through process safety and air emissions frameworks that elevate capital costs for domestic foil rolling capacity. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs become a decisive factor in site selection and customer qualification timelines.
Market Dynamics
Solid-state battery commercialization timelines are compressing procurement cycles as automotive cell makers qualify sub-50-micrometer lithium foils against OEM-specific protocols. This technical threshold is restructuring supplier relationships and capital allocation across the anode material value chain.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint disclosure and recycled content thresholds are accelerating closed-loop material sourcing investments among European cell manufacturers.
- Solid-state architectures:Automotive battery producers are specifying lithium-metal anodes to achieve energy density targets unreachable with conventional graphite systems.
- East Asian manufacturing clusters:South Korea's cathode production corridors and Japan's precision electronics belt concentrate qualified demand for ultra-thin foil formats.
Market Restraints
- Spodumene concentrate volatility:Hard-rock lithium feedstock prices swing with African mine output disruptions, compressing rolling margins for thin-foil producers.
- Chinese NMPA purity enforcement:GB/T standards for sodium content below 200 ppm disqualify secondary feedstock streams, narrowing qualified supplier pools.
- Technical thickness floors:Sub-20-micrometer foils suffer handling yield losses above 15% in current rolling configurations, capping volume scalability.
Strategic Opportunities
- Composite foil architectures:Copper-laminate and polymer-substrate variants for dendrite suppression command premium positioning in next-generation cell designs.
- US IRA domestic content credits:Inflation Reduction Act incentives are pulling rolling capacity investment toward Nevada and North Carolina industrial corridors.
- Aviation electrification:Urban air mobility developers are qualifying lithium-metal anodes for weight-critical battery packs in regional electric aircraft programs.
Industry Challenges
- Cleanroom rolling expertise:Oxygen-controlled surface engineering for stable solid-electrolyte interface formation requires metallurgists with thin-film battery experience, a scarce labor pool concentrated in Japanese and Korean industrial clusters.
- Dual certification timelines:Simultaneous NMPA and OEM qualification protocols extend vendor approval cycles to 18-24 months, freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Foil Market |
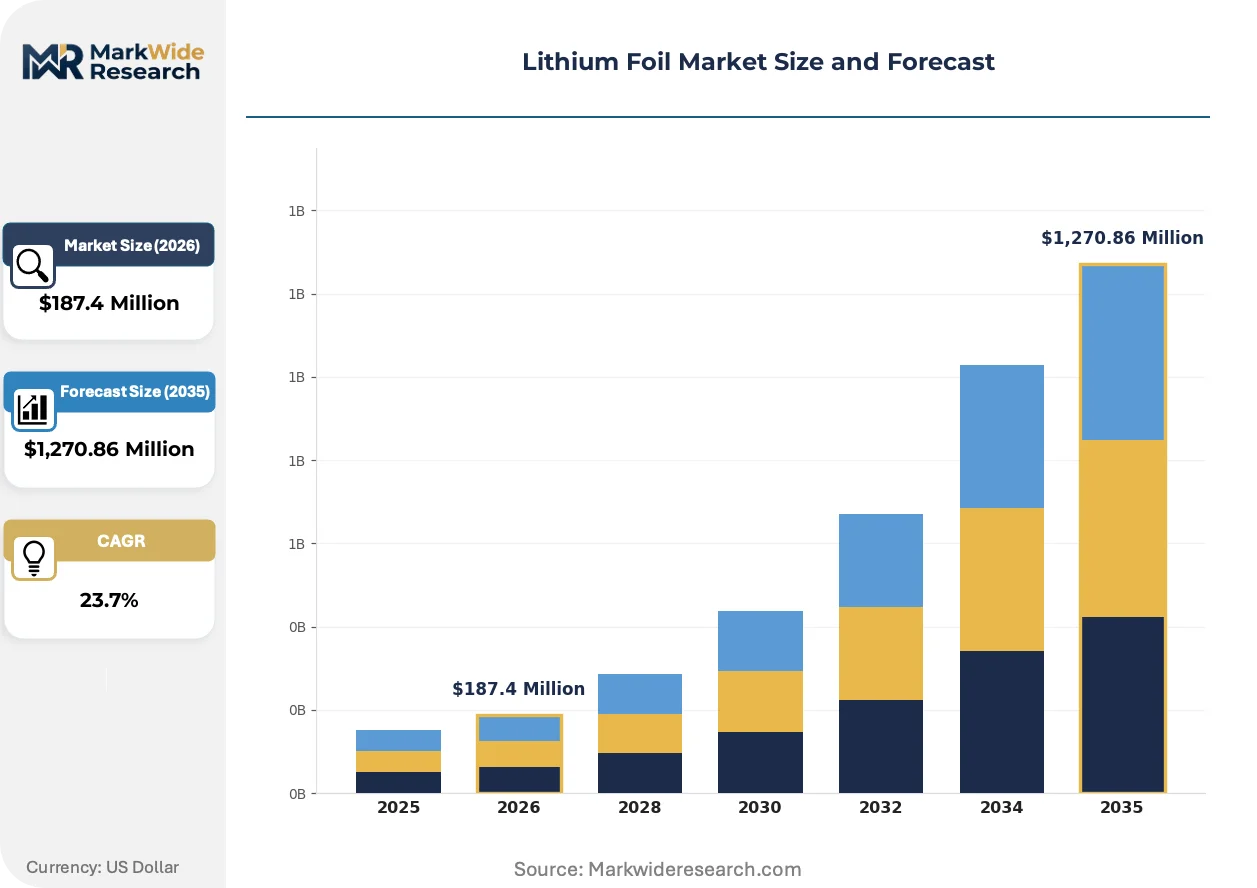
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Research Grade, Electronics Grade Form: Thin Foil, Thick Foil, Coated Foil, Composite Foil Application: Battery Manufacturing, Electrochemical Devices, Medical Devices, Aerospace Components End User: Consumer Electronics, Automotive Industry, Energy Storage, Scientific Research |
| Companies Covered | Tianqi Lithium, Arcadium Lithium, Albemarle Corporation, Allkem, Livent, Sociedad Química y Minera de Chile, Pilbara Minerals, Lithium Americas, Ganfeng Lithium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Foil Market Strategic Shifts
Dry electrode coating techniques and roll-to-roll processing advances are eliminating solvent-based manufacturing steps. These process innovations are compressing capital intensity while tightening thickness tolerances for battery-grade foil output.
Roll-to-roll dry coating is decentralizing electrode manufacturing by eliminating solvent recovery infrastructure requirements. Automotive cell makers in South Korea and Japan are piloting in-house anode lamination lines. This equipment shift is compressing the traditional coated electrode supply chain into vertically integrated cell plants.
China's NMPA has tightened GB/T lithium metal purity specifications for electrochemical applications beyond prior industrial grades. The enforcement is disqualifying legacy refining outputs and forcing feedstock traceability upgrades. Battery-grade foil producers are responding with spodumene-to-foil integration to secure qualified material streams.
Automotive OEMs are consolidating supplier rosters around qualified thin-foil vendors capable of sub-50-micrometer consistency. Long-term offtake agreements with volume guarantees are displacing spot-market purchasing for solid-state cell programs. This concentration is most visible in German and South Korean automotive supply chains where cell makers pre-qualify vendors against proprietary protocols.
Lithium Foil Market Segmentation
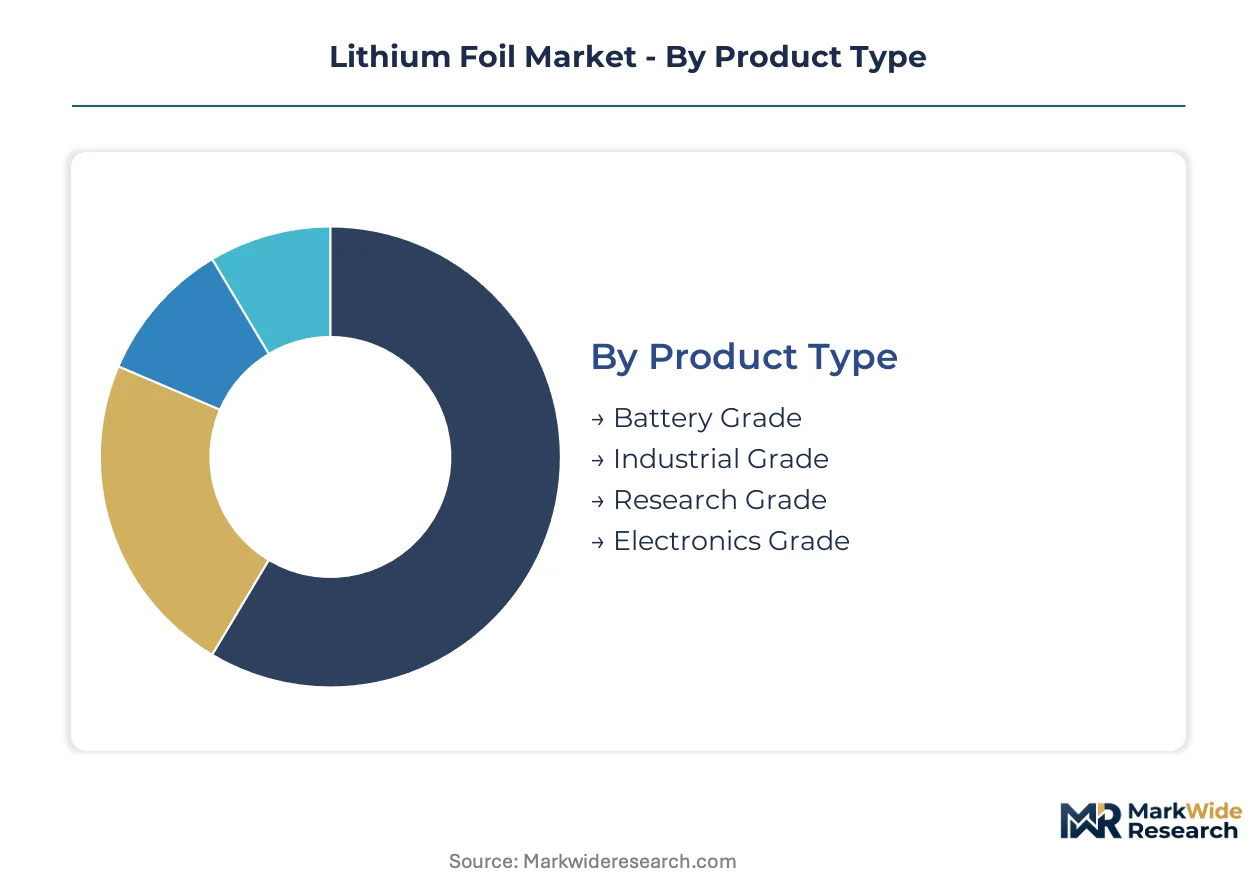
Lithium foil segmentation reveals how purity grades and physical formats align with diverging value pools across solid-state battery commercialization and industrial applications. Format thickness and certification tiers now determine supplier qualification pathways more than raw material sourcing alone.
Product Type:
Battery Grade commands premium positioning through sodium content below 200 ppm and oxygen-controlled surfaces, while Industrial Grade and Research Grade serve adjacent volume pools with relaxed specifications.
- Battery Grade:Rolled to sub-150-micrometer thickness with sodium content below 200 ppm and oxygen-controlled surfaces for stable solid-electrolyte interface formation. Automotive cell makers in South Korea and Japan qualify suppliers against NMPA and OEM-specific protocols, with qualification cycles extending 18-24 months.
- Industrial Grade:Metallurgical lithium with higher tolerances for oxygen and alkali metal contaminants, serving alloy production and chemical synthesis. China's spodumene-to-foil integrated producers dominate this segment through captive feedstock from African hard-rock offtake.
- Research Grade:Ultra-high purity variants for laboratory-scale solid-state battery prototyping and materials science investigation.
- Electronics Grade:Precision-thickness foils for thermal interface materials and electromagnetic shielding in semiconductor packaging.
Today's leader: Battery Grade. Tomorrow's challenger: Electronics Grade.
Form:
Thickness differentiation separates solid-state battery-qualified supply from legacy industrial rolling, with composite architectures emerging as dendrite-suppression solutions.
- Thin Foil:Sub-50-micrometer formats specified for lithium-metal anodes in next-generation solid-state designs. South Korean cathode production corridors concentrate procurement of these ultra-thin variants as automotive cell makers compress commercialization timelines.
- Thick Foil:Conventional rolling above 100 micrometers for primary battery production and industrial chemical applications. Japanese precision electronics belt maintains specialized capacity for medical device and aerospace specifications.
- Coated Foil:Surface-modified variants with protective layers to minimize atmospheric degradation during cell assembly.
- Composite Foil:Copper-laminate and polymer-substrate architectures for dendrite suppression in high-energy-density cell designs.
Thin Foil expands most quickly through solid-state adoption. Composite Foil gains share fastest as next-generation cell architectures mature.
Application:
Battery Manufacturing absorbs the deepest investment in qualification infrastructure, while Electrochemical Devices and Medical Devices impose specialized purity and traceability requirements.
- Battery Manufacturing:Primary demand driver spanning solid-state lithium-metal cells and conventional primary battery production. EU Battery Regulation carbon footprint disclosure mandates are accelerating closed-loop material sourcing investments among European cell manufacturers.
- Electrochemical Devices:Capacitors, sensors, and specialized energy storage components requiring consistent electrochemical surface properties.
- Medical Devices:Implantable power sources and diagnostic equipment with biocompatibility and long-term stability requirements.
- Aerospace Components:Weight-critical thermal management and primary power systems for electric aircraft programs.
Battery Manufacturing anchors current volume. Aerospace Components shows the steepest expansion trajectory as urban air mobility developers qualify lithium-metal anodes.
End User:
Automotive Industry procurement is consolidating supplier rosters around qualified thin-foil vendors, while Energy Storage and Scientific Research represent fragmented demand with distinct specification profiles.
- Automotive Industry:Solid-state cell programs specifying sub-50-micrometer lithium-metal anodes for energy density targets unreachable with graphite systems. Long-term offtake agreements with volume guarantees are displacing spot-market purchasing in German and South Korean supply chains.
- Consumer Electronics:Primary lithium batteries for wearables, medical patches, and portable devices with space-constrained form factors.
- Energy Storage:Grid-scale and residential battery systems with cost-sensitive specifications and lower purity requirements.
- Scientific Research:Laboratory-scale procurement for materials characterization and next-generation cell chemistry development.
Automotive Industry dominates premium positioning. Scientific Research provides the pathway for format and purity innovations that migrate to commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the deepest lithium foil rolling capacity while South Korea concentrates the most demanding automotive qualification programs, creating a bifurcated geography where production and premium validation sit in separate jurisdictions.
China
Spodumene-to-foil integrated producers dominate battery-grade output through captive African hard-rock offtake. NMPA GB/T standards for sodium content below 200 ppm disqualify secondary feedstock streams, forcing traceability upgrades across Jiangxi and Sichuan processing corridors. The Yangtze River Delta cluster anchors thin-foil rolling for domestic solid-state cell pilots.
South Korea
Automotive cell makers in the cathode production corridors specify sub-50-micrometer lithium-metal anodes for next-generation solid-state designs. MFDS alignment with NMPA protocols streamlines dual certification for qualified suppliers. The Gyeonggi-Incheon belt concentrates cleanroom rolling expertise for oxygen-controlled surface engineering.
Japan
Precision electronics manufacturers in the Kansai and Chubu regions maintain specialized capacity for medical device and aerospace foil specifications. METI funding for solid-state battery commercialization accelerates domestic anode material qualification. The Nagoya-Toyota industrial corridor hosts pilot lines for composite foil architectures with copper-laminate substrates.
United States
Silver Peak brine operations anchor North American feedstock supply for downstream refining investments. EPA and OSHA joint governance of lithium handling facilities elevates capital costs for domestic rolling capacity, pushing development toward Nevada and North Carolina industrial corridors. IRA domestic content credits pull investment toward integrated spodumene-to-foil projects.
Germany
Automotive OEM supply chains pre-qualify thin-foil vendors against proprietary protocols for solid-state cell programs. EU Battery Regulation carbon footprint disclosure mandates accelerate closed-loop material sourcing investments among European cell manufacturers. The Stuttgart-Munich corridor concentrates long-term offtake negotiations with volume guarantees displacing spot-market purchasing.
Lithium Foil Market Competitive Environment
Chinese producers anchor the integrated feedstock tier; South Korean and Japanese specialists hold the premium qualification tier. The vendor base organizes around three strategic archetypes: spodumene-to-foil integrators securing captive material streams, brine-based refiners anchoring regional supply security, and thin-foil specialists commanding cleanroom rolling premiums. Competitive moves concentrate on backward integration into African hard-rock offtake and capacity expansion near automotive cell manufacturing clusters.
Among integrated lithium producers, Tianqi Lithium represents the spodumene-to-foil archetype with Chinese corporate structure, while Albemarle Corporation occupies a position exemplifying brine-based North American supply security. Ganfeng Lithium anchors the Asian spot market presence through its corporate form. These three entities sit within distinct competitive tiers based on feedstock geography and downstream integration depth.
| Leading Market Players |
|---|
| Tianqi Lithium |
| Arcadium Lithium |
| Albemarle Corporation |
| Allkem |
| Livent |
| Sociedad Química y Minera de Chile |
| Pilbara Minerals |
| Lithium Americas |
| Ganfeng Lithium |
| Others |
Value Chain & Pricing Dynamics
Dry electrode coating techniques and roll-to-roll processing advances are compressing capital intensity while tightening thickness tolerances, simultaneously lowering entry barriers for thin-foil rolling capacity and concentrating pricing power among qualified cleanroom operators in South Korea and Japan. This dual effect is fragmenting supply at the industrial grade tier while hardening premiums for battery-grade variants certified to NMPA and OEM protocols.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for industrial-grade foil, yet battery-grade premiums widen as sub-50-micrometer qualification scarcity persists. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-certified cleanroom output from conventional rolling and secondary feedstock streams. Cost compression in standard-tier supply is intensifying because Jiangxi spodumene-to-foil integrators are flooding spot markets with captive African hard-rock material. Automotive cell makers in South Korea show least price sensitivity due to 18-24 month qualification lock-in, while energy storage procurement teams remain most responsive to spot discounts.
Supply Chain Analysis
Scrap lithium recovery and foil edge-trim reclamation flows are emerging as critical feedstock supplements as NMPA sodium-content enforcement disqualifies primary refining streams below battery-grade thresholds. Geographic concentration centers on China for rolling capacity, South Korea for cathode corridor demand, and Japan for precision electronics specifications. Raw material dependencies draw from African hard-rock spodumene, Chilean and Argentine brine, and Australian spodumene concentrate. Single-source vulnerability runs through Chinese control of mid-stream refining and rolling infrastructure. Distribution runs through long-term offtake agreements with volume guarantees displacing spot-market purchasing in German and South Korean automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium foil market reads as a late-cycle quality story where sub-50-micrometer qualification scarcity and 18-24 month OEM certification timelines are hardening premium positioning for cleanroom-capable suppliers. Solid-state battery commercialization is pulling demand toward sodium-content thresholds below 200 ppm and oxygen-controlled surface engineering that disqualifies legacy rolling capacity.
For Market Incumbents: Deepen captive feedstock security through upstream control over African hard-rock offtake and spodumene-to-foil integration to defend margin position against Jiangxi spot-market flooding. Expand cleanroom rolling capacity in South Korea's Gyeonggi-Incheon belt to capture automotive cell maker consolidation around qualified thin-foil vendors. Prioritize simultaneous NMPA and MFDS certification investments to compress dual approval timelines that currently freeze procurement decisions. For New Entrants and Emerging Players: Composite foil architectures with copper-laminate or polymer-substrate dendrite suppression represent the most penetrable technology wedge for next-generation cell designs where incumbents lack specialized capacity. Target aviation electrification programs in urban air mobility and regional electric aircraft as qualification pathways with less entrenched supplier rosters than automotive. Pursue equipment partnerships with Japanese precision electronics belt specialists to license oxygen-controlled surface engineering expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade rolling assets with spodumene integration but lacking battery-grade certification infrastructure. Five-to-ten year viability hinges on migration path from commodity spot supply to long-term offtake relationships with automotive cell makers. Watch NMPA enforcement consistency as the inflection signal—tightened GB/T standards accelerate qualified supplier consolidation, while relaxed interpretation extends industrial-grade viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into African Hard-Rock Offtake | Secures captive spodumene feedstock streams against NMPA sodium-content enforcement. |
| Cleanroom Rolling Capacity Expansion | Captures premium positioning in South Korean automotive cell maker qualification programs. |
| Composite Foil Architecture Development | Addresses dendrite suppression requirements in next-generation solid-state cell designs. |
| Dual Certification Investment (NMPA/MFDS) | Compresses vendor approval cycles from 18-24 months to accelerate procurement decisions. |
| Aviation Electrification Partnership | Opens alternative qualification pathway through urban air mobility lithium-metal anode programs. |
Study Parameters
Multiple input streams — primary interviews with battery material procurement directors, solid-state cell engineering leads, and cleanroom rolling operators; secondary validation through NMPA GB/T standard filings, customs trade data, and automotive OEM supply chain disclosures; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Primary fieldwork captured qualification timeline data, certification cost structures, and offtake agreement terms from South Korean cathode corridor and Japanese precision electronics belt stakeholders. Secondary sources included spodumene concentrate price benchmarks, EPA and OSHA lithium handling facility permits, and IRA domestic content credit guidance documents.
Historical capacity deployment patterns were cross-referenced against expert panel inputs from metallurgists with thin-film battery experience and regulatory affairs specialists tracking NMPA enforcement trends. Segmentation modeling spanned product type tiers, thickness format categories, application end-uses, and regional manufacturing clusters across the projection horizon. CAGRs were derived from rolling capacity expansion schedules, solid-state battery commercialization roadmaps, and automotive OEM cell sourcing commitments. Industry-specific forecast inputs included spodumene-to-foil integration yields, cleanroom rolling throughput rates, and dual certification timeline distributions.
The model holds under sustained NMPA GB/T enforcement and automotive OEM consolidation around qualified thin-foil vendors; deviation in regulatory interpretation or solid-state battery timeline delays would shift volume and value trajectories. Forecasts reflect assumptions about feedstock traceability upgrade costs, cleanroom labor pool availability, and long-term offtake agreement penetration. Periodic stress-testing of base assumptions is recommended against African mine output disruptions, EU Battery Regulation recycled content threshold adjustments, and aviation electrification program acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Carbon Steel Market
Metals
Aluminum Ingots Market
Metals
Global Copper Cathode Market
Metals
Iron Casting Market
Metals
Neodymium Market
Metals
Global Aluminum Extruded Products Market
Metals
Platinum Market
Metals
Stainless Steel 400 Series Market
Metals
Steel Drums Market
Metals
Global Oxygen-Free Copper Market
Metals
HSLA Steel Plate Market
Metals
Bismuth Market
Metals
Crude Steel Market
Metals
Global Tantalum Market
Metals
Global Brass Rods Market
Metals
Copper and Copper Alloy Scrap and Recycling Market