
 Expanded Metal Foils Market | 2026-2036
Expanded Metal Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Metal Foils Market Analysis
The capital-intensity divergence between precision-slitting capabilities and commodity punching operations is redrawing competitive tiers in expanded metal foils. Dexmet Corporation leverages its proprietary MicroGrid technology to anchor premium supply contracts for aerospace-grade foils. Wallner Expac sustains European market presence through specialized brass and copper product lines serving architectural and industrial channels.
Expanded metal foils are perforated sheet materials manufactured through slitting and stretching processes that create uniform diamond-shaped apertures without material waste, typically produced in thicknesses from 0.025 mm to 6.0 mm depending on end-use structural or conductive requirements. Aluminum foils dominate architectural applications where corrosion resistance and lightweight panels matter, while copper foils represent the fastest-growing product category driven by battery current collector demand from electronics and automotive end users. The thickness dimension stratifies across light gauges for EMI shielding in electronics, medium gauges for HVAC filtration media, and heavy gauges for industrial walkways and machine guards where load-bearing capacity determines specification.
The EPA governs metal finishing emissions in the United States, while REACH and RoHS in Europe restrict hazardous substance content in construction and electronics applications, directly shaping alloy composition choices and surface treatment processes. China's GB standards and dual carbon goals are tightening energy intensity benchmarks for aluminum and copper processing, affecting import eligibility for foil products. Stakeholders must monitor evolving battery safety certification requirements from multiple jurisdictions as these will determine which foil grades qualify for next-generation energy storage contracts.
Market Dynamics
Battery-grade copper expanded foil procurement is redrawing competitive positioning as electric vehicle manufacturers impose stricter purity and traceability requirements on current collector suppliers.
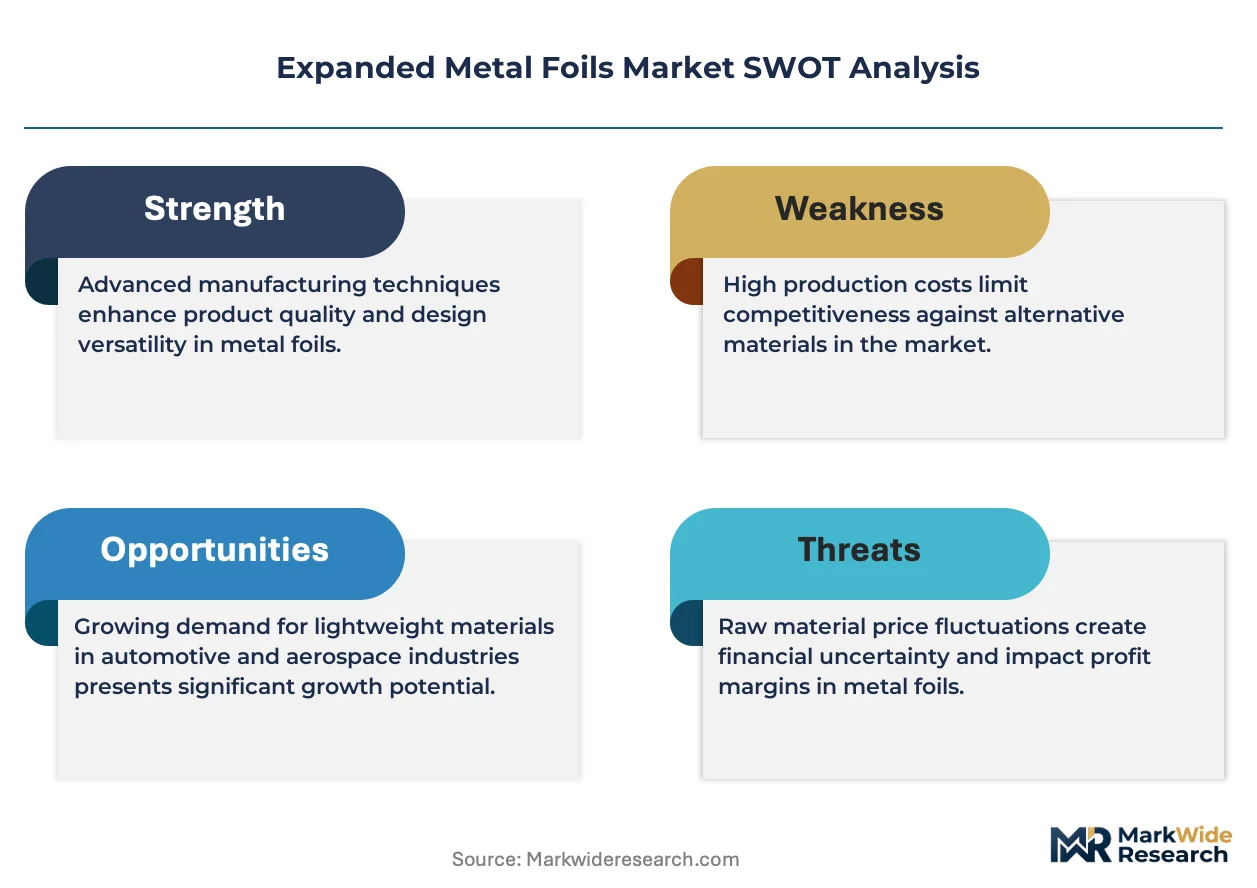
Growth Catalysts
- EU Battery Regulation:Mandated recycled content thresholds and carbon footprint declarations are accelerating qualification of European-sourced foils for energy storage contracts.
- Electrodeposition advances:Thin-film coating technologies enable sub-10-micron copper layers on expanded substrates, reducing lithium-ion cell weight without sacrificing conductivity.
- South Korea's battery corridor:Concentrated cathode and cell manufacturing around Ulsan and Gwangju is generating dedicated demand for precision-slit foils with tight aperture tolerances.
Market Restraints
- Copper price volatility:LME copper fluctuations compress converter margins and complicate long-term supply agreements with automotive OEMs.
- Premium slitting capacity scarcity:Germany and Japan host the majority of precision equipment capable of battery-grade tolerances, creating geographic supply risk.
- Alternative current collector designs:Carbon nanotube and graphene composite substrates threaten foil penetration in next-generation solid-state cell architectures.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Production-linked incentives for advanced chemistry cell manufacturing will localize foil demand previously served by imports.
- Grid-scale storage integration:Utility battery installations require heavy-gauge aluminum expanded foils for thermal management in containerized systems.
- EU Green Deal industrial funding:Carbon border adjustment mechanisms and green hydrogen subsidies favor low-emission foil production methods in qualifying facilities.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous pursuit of UL, IEC, and GB standards for battery applications extends qualification cycles by 12-18 months.
- Skilled slitting technician scarcity:Precision foil production requires operators trained in tension control and edge quality management, with limited vocational pipeline.
- Legacy HVAC specification inertia:Mechanical contractors in commercial building markets resist switching from perforated sheet to expanded foil despite material efficiency advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Metal Foils Market |
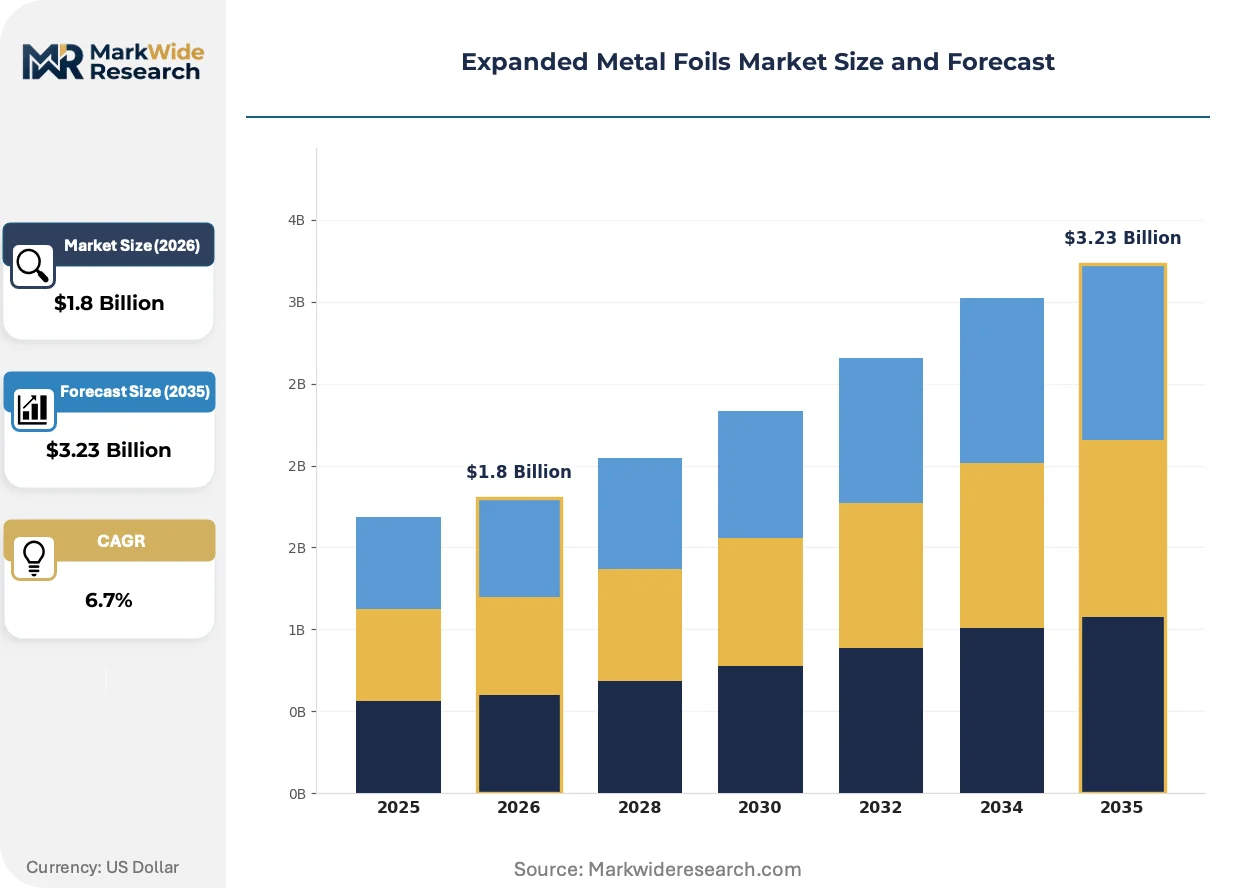
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Copper, Brass Application: Architectural, Automotive, HVAC, Industrial Thickness: Light, Medium, Heavy, Extra Heavy End User: Aerospace, Construction, Manufacturing, Electronics |
| Companies Covered | Dexmet Corporation, Wallner Expac, CTru Metals, Yilida Metal Wire Mesh Co., Ltd., New Metals Inc., MicroGrid, The Expanded Metal Company Limited, Alabama Metal Industries Corporation, Niles International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Metal Foils Market Emerging Trajectories
Active materials deposition techniques and aperture geometry optimization are compressing the performance gap between expanded foils and solid current collectors in high-rate battery applications.
Electrochemical vapor deposition of silicon-carbon composites onto copper MicroGrid substrates is miniaturizing active material loading while maintaining structural integrity during lithiation cycles. Solid-state battery developers in Germany and Japan are qualifying these enhanced foils for prototype cells. The technology is compressing the timeline for commercial solid-state adoption by solving interface stability challenges that previously required thicker, heavier collectors.
REACH Annex XVII restrictions on nickel release are forcing alloy substitutions in architectural brass foils across European construction markets. Surface treatment providers are accelerating development of barrier coatings that maintain aesthetic finishes while meeting migration limits. Germany's KBA and France's ANSM have both signaled alignment with ECHA guidance, tightening enforcement timelines for facade applications.
Automotive OEMs are consolidating supplier bases and demanding direct mill relationships rather than distributor intermediaries for battery-grade foil procurement. Tier-1 cell manufacturers are responding by establishing captive slitting operations near assembly plants. This pattern is most visible in Hungary and Poland, where CATL and Samsung SDI facilities are co-locating with precision metal processors to compress logistics lead times.
Expanded Metal Foils Market Segmentation
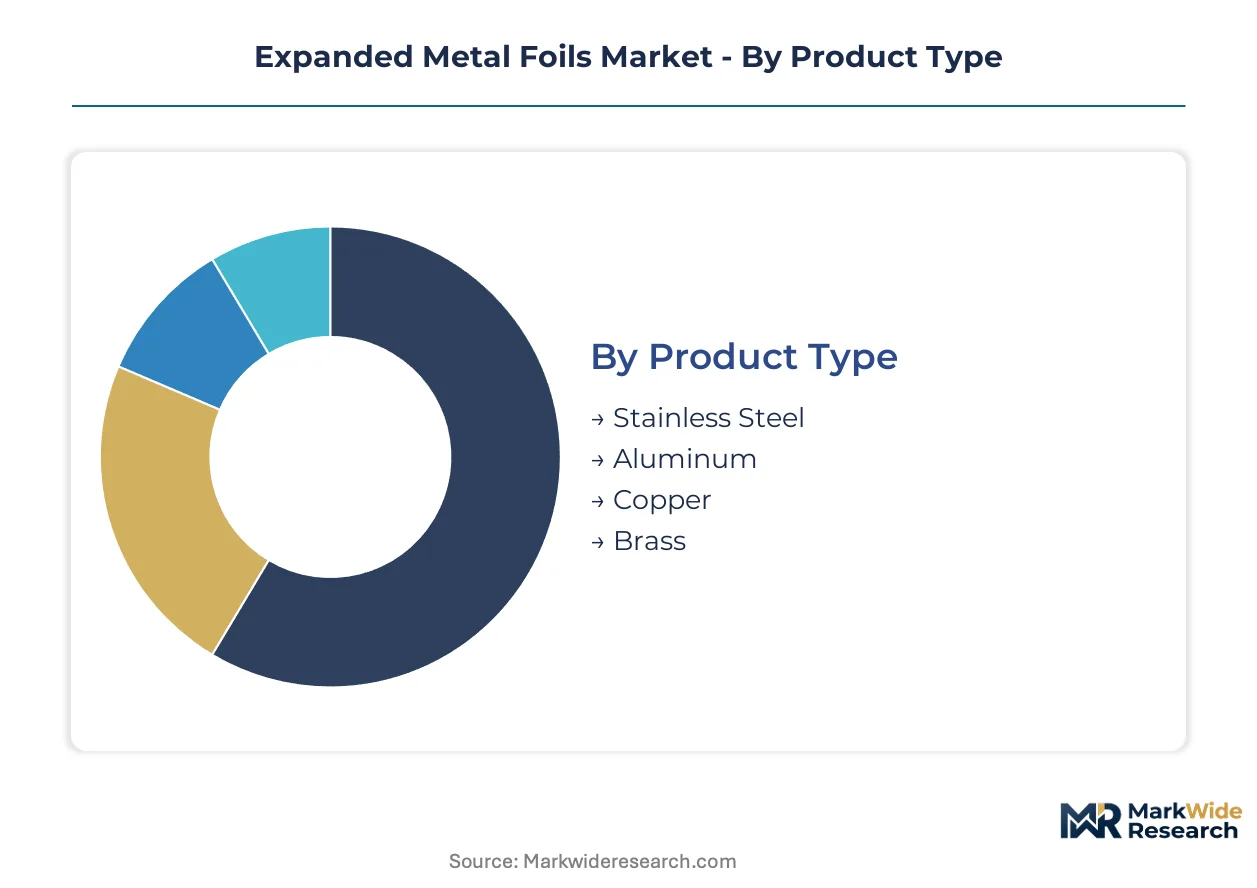
Segmentation in expanded metal foils reveals how material specifications and end-use requirements channel demand through distinct procurement pathways. Each dimension—product chemistry, application environment, gauge thickness, and customer industry—carries unique certification burdens and margin structures that reshape supplier strategies.
Product Type:
Product chemistry determines which distribution channels dominate procurement, with battery-grade copper flowing through direct mill relationships while architectural aluminum moves via metal service centers.
- Copper:Battery current collector applications demand 99.9% purity expanded foils with sub-10-micron coating compatibility. Procurement concentrates in South Korea's Ulsan-Gwangju battery corridor and Hungary's emerging cell manufacturing zone, driven by cathode manufacturer qualification requirements.
- Aluminum:Corrosion-resistant expanded panels serve HVAC filtration and architectural cladding where lightweight structural efficiency matters. Demand clusters in Germany's commercial construction markets and China's building sector, constrained by REACH and GB standards on surface treatment emissions.
- Stainless Steel:Industrial walkways and machine guards requiring load-bearing capacity specify 300-series expanded mesh through mechanical contractors.
- Brass:Decorative architectural applications in European facades face REACH Annex XVII nickel release restrictions, forcing alloy reformulation.
Aluminum dominates installed base by volume. Copper is where expansion concentrates fastest.
Application:
Application environments stratify by certification intensity, with automotive and aerospace demanding traceable supply chains while HVAC tolerates commodity sourcing.
- Automotive:Electric vehicle battery packs require current collector foils with documented carbon footprints and recycled content thresholds under EU Battery Regulation. Cell manufacturers in Poland and Germany impose direct mill relationships, bypassing distributors.
- Architectural:Facade and interior panel specifications favor brass and aluminum expanded foils where aesthetic finish and corrosion resistance intersect. France's ANSM and Germany's KBA have aligned with ECHA guidance on nickel migration, tightening enforcement for European construction projects.
- HVAC:Filtration media and heat exchanger applications specify medium-gauge aluminum foils, though mechanical contractors show inertia switching from perforated sheet alternatives.
- Industrial:Walkways, machine guards, and screening applications prioritize structural load ratings over surface precision, channeling through metal service centers.
Industrial applications anchor volume throughput. Automotive commands the steepest expansion trajectory.
Thickness:
Gauge selection maps directly to functional performance requirements, with lighter foils commanding precision-slitting premiums and heavy gauges competing on raw material efficiency.
- Light:Sub-0.5 mm foils serve EMI shielding in electronics and thin-film battery substrates where aperture uniformity determines conductivity. Production concentrates in Germany and Japan where precision slitting equipment maintains tight tolerances.
- Medium:0.5-2.0 mm gauges balance structural integrity with weight for HVAC filtration and industrial screening. China's GB standards and dual carbon goals are tightening energy intensity benchmarks for aluminum processing at this thickness range.
- Heavy:2.0-4.0 mm expanded mesh supports industrial walkways and machine guards where OSHA load-bearing specifications apply.
- Extra Heavy:Above 4.0 mm gauges serve specialized infrastructure and offshore applications requiring maximum impact resistance.
Medium gauge holds the broadest installed base. Light gauge captures the fastest share gains.
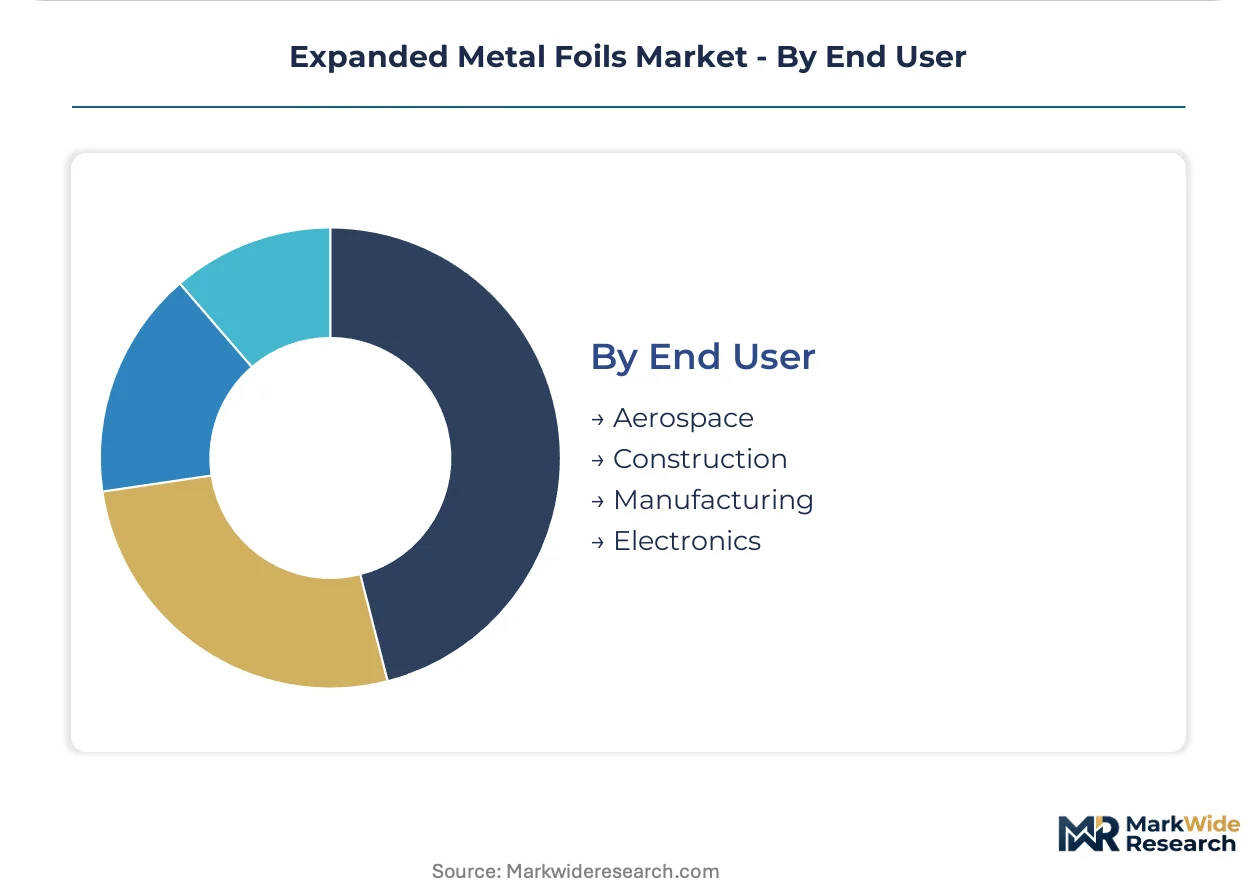
End User:
Customer industry concentration shapes supplier capability investments, with aerospace and electronics demanding qualification depth that excludes commodity producers.
- Electronics:Smartphone and laptop manufacturers specify light-gauge copper MicroGrid foils for EMI shielding and miniature battery cells. South Korea's electronics supply chain sources through precision metal processors with IEC certification.
- Aerospace:FAA-certified applications require documented material traceability and flame-resistance testing for expanded foil components. Dexmet Corporation anchors this segment through proprietary MicroGrid technology.
- Construction:Commercial building contractors procure architectural foils through regional metal distributors, with specification inertia slowing expanded foil adoption despite material efficiency advantages.
- Manufacturing:General industrial users prioritize cost and availability over certification depth, sourcing heavy-gauge products through commodity channels.
Manufacturing end users represent the largest volume base. Electronics drives the fastest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and South Korea demonstrate the least price elasticity for battery-grade foils, accepting premiums for precision tolerances, while Indian and Chinese purchasers in HVAC and industrial segments drive hard on raw material pass-through mechanics.
Germany
Automotive OEMs in Stuttgart and Munich impose direct mill relationships for current collector procurement under EU Battery Regulation recycled content mandates. ECHA REACH compliance and KBA enforcement on nickel release restrictions shape alloy selection for architectural applications. The automotive corridor from Wolfsburg to Ingolstadt concentrates cathode manufacturer demand for precision-slit copper foils.
South Korea
Ulsan-Gwangju battery manufacturing clusters generate dedicated demand for sub-10-micron coating-compatible foils with documented carbon footprints. MFDS alignment with IEC battery safety standards extends qualification timelines for imported substrates. Samsung SDI and LG Energy Solution operations near Gwangju are co-locating with precision metal processors to compress logistics lead times.
China
Building sector demand for aluminum architectural panels competes with EV battery procurement for copper foil capacity. GB standards and MIIT dual carbon goals tighten energy intensity benchmarks for aluminum processing at medium gauges. Shenzhen and Ningbo house the majority of expanded foil converters serving domestic electronics manufacturers.
United States
EPA metal finishing emission controls shape alloy composition and surface treatment processes for construction and electronics applications. FAA certification requirements for aerospace-grade foils concentrate demand around precision processors with documented material traceability. The Southeast manufacturing belt shows emerging battery cell investment pulling foil procurement eastward from traditional Midwest metal centers.
India
PLI scheme incentives for advanced chemistry cell manufacturing will localize foil demand previously served by Chinese and Korean imports. BIS standards for electrical conductivity in battery applications are tightening specification thresholds. Tamil Nadu and Gujarat are emerging as the primary states for cell manufacturing co-location with metal processing facilities.
Expanded Metal Foils Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in expanded metal foils, with capability stratification running deepest in battery-grade copper processing. Precision-slitting equipment scarcity in Germany and Japan has created geographic bottlenecks that favor incumbent operators with established automotive qualifications. Two strategic archetypes dominate: technology-anchored premium suppliers holding aerospace and electronics certifications, and scale-driven commodity converters serving HVAC and industrial walkaway segments. Competitive moves center on captive slitting operations near battery cell plants and electrodeposition technology licensing for sub-10-micron coating compatibility.
Among North American fabricators, Dexmet Corporation and Alabama Metal Industries Corporation occupy positions at opposite ends of the capability spectrum, with the former exemplifying technology-anchored premium supply and the latter representing scale-driven industrial mesh production. Wallner Expac anchors European specialist positioning through brass and copper product lines. These three names illustrate how geographic concentration of precision equipment shapes competitive access rather than raw production capacity alone.
| Leading Market Players |
|---|
| Dexmet Corporation |
| Wallner Expac |
| CTru Metals |
| Yilida Metal Wire Mesh Co., Ltd. |
| New Metals Inc. |
| MicroGrid |
| The Expanded Metal Company Limited |
| Alabama Metal Industries Corporation |
| Niles International |
| Others |
Supply Flow & Price Mechanics
EU Battery Regulation recycled content mandates gate both supplier qualification and price tier separation, forcing cell manufacturers to pay premiums for documented carbon footprints while excluding uncertified converters from automotive procurement pools. This dual-gating mechanism concentrates pricing power among German and South Korean precision slitters with established OEM relationships.
Pricing Analysis
After-sales service contracts and technical qualification support now drive lifetime value more than foil unit pricing. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified MicroGrid suppliers from battery-grade specialists and commodity HVAC converters. Price differentiation hinges on aperture tolerance certification and direct mill relationship status. Cost compression in standard-grade aluminum runs through Chinese energy intensity benchmarks tightening processing margins. HVAC contractors in commercial construction show highest price sensitivity, while automotive cell manufacturers accept premiums for traceable supply chains.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites inventory positioning for copper cathode feedstock bound for East Asian foil converters. Supply concentrates in Germany, South Korea, and Japan for precision-slitting equipment and battery-grade output; China anchors medium-gauge aluminum for architectural and HVAC applications. Raw material dependencies center on LME copper cathodes, primary aluminum ingots, and specialized slitting tooling from German equipment builders. Single-source vulnerability concentrates in precision tension-control systems manufactured by a narrow supplier base in Baden-Württemberg. Distribution runs through direct mill relationships for automotive battery contracts, regional metal service centers for construction and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical qualification services and carbon footprint documentation represent the fastest-expanding revenue layer, outpacing base foil pricing as EU Battery Regulation compliance costs mount.
For Market Incumbents: Consolidate precision-slitting capacity near battery cell manufacturing clusters in Hungary and Poland to compress logistics lead times. Lock in direct mill relationships with CATL and Samsung SDI before alternative current collector designs reach commercial scale. Backward integration into electrodeposition coating technology defends margin position against thin-film substrate competitors. For New Entrants and Emerging Players: Anchor in India's PLI scheme beneficiary states—Tamil Nadu and Gujarat—where localized foil demand will displace Korean and Chinese imports. Target grid-scale storage integrators requiring heavy-gauge aluminum thermal management foils, a segment with lower certification barriers than automotive. Pursue joint qualification pathways with BIS-certified testing laboratories to accelerate market entry. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward low-emission European foil production assets. Five-to-ten-year viability favors precision processors with captive slitting operations and automotive qualification depth over commodity converters exposed to aluminum energy intensity regulations. Watch electrodeposition technology licensing deals as the inflection signal for solid-state battery substrate readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Slitting Operation Establishment | CATL and Samsung SDI co-location in Hungary compresses logistics lead times for battery-grade foils. |
| Electrodeposition Technology Licensing | Sub-10-micron coating compatibility opens solid-state battery prototype qualification pathways. |
| Carbon Footprint Certification Investment | EU Battery Regulation compliance secures direct mill relationships with Stuttgart and Munich OEMs. |
| Backward Integration into Copper Cathode Sourcing | LME price volatility hedging stabilizes converter margins for long-term automotive supply agreements. |
| REACH-Compliant Surface Treatment Development | Barrier coating advances maintain brass foil architectural demand under ECHA nickel release restrictions. |
Methodological Framework
Cross-validation between primary interviews with slitting equipment operators, battery cell procurement managers, and architectural specification consultants anchors the qualitative findings. Secondary validation draws from SEC filings of listed metal processors, ECHA REACH guidance documents, MIIT energy intensity disclosures, and customs trade data for copper and aluminum foil shipments. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Sensitivity analysis across aperture tolerance thresholds, recycled content compliance costs, and electrodeposition adoption rates frames the projection envelope. Segmentation dimensions modeled include material chemistry, gauge thickness, end-use certification intensity, and regional production hub clustering. CAGRs derive from installed base replacement cycles and emerging application penetration curves. Forecast inputs incorporate battery cell manufacturing capacity announcements and HVAC specification inertia parameters.
Material uncertainties—solid-state battery commercialization timelines, LME copper volatility spikes, and REACH Annex XVII enforcement intensity—sit outside the modeled envelope. Practitioners should keep alternative scenarios live as carbon border adjustment mechanism scope and dual carbon goal implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Nickel Oxide Target Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Industrial Metal Strips Market
Metals
Huntite Market
Metals
Global Aluminum Extruded Products Market
Metals
Tin Chloride Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Aluminum Wire Market
Metals
Europe Metal Casting Market
Metals
Trivalent Chromium Finishing Market
Metals
Aluminum Scrap Recycling Market
Metals
Titanium Powder Market
Metals
Vietnam Aluminum Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
US Copper Scrap Market
Metals
South America Metal Finishing Market