
 US Carbon Black Market | 2026-2036
US Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
US Carbon Black Market Insights
Tire manufacturing is recalibrating the US Carbon Black Market as electric vehicle production expands and tread formulations require higher reinforcement grades. Cabot Corporation leverages its Gulf Coast manufacturing footprint to supply furnace black volumes directly to major tire builders. Birla Carbon anchors its position through backward integration into carbon feedstock sourcing. Orion Engineered Carbons specializes in acetylene black for battery conductive additives, a segment gaining traction beyond traditional rubber applications.
Carbon black is a colloidal carbon material produced by incomplete combustion of hydrocarbons, with primary particle sizes ranging from 10 to 500 nanometers and surface areas between 20 and 250 square meters per gram; its fundamental purpose is to reinforce elastomers, impart conductivity, and provide UV protection across industrial formulations. Specialty Carbon Black commands premium positioning due to stringent dispersion requirements in coatings and plastics, while Rubber Reinforcement remains the volume anchor tied to tire sector procurement cycles. Furnace Black dominates manufacturing output owing to cost efficiency and scalability, though Thermal Black retains niche status for high-purity applications where low ash content proves critical.
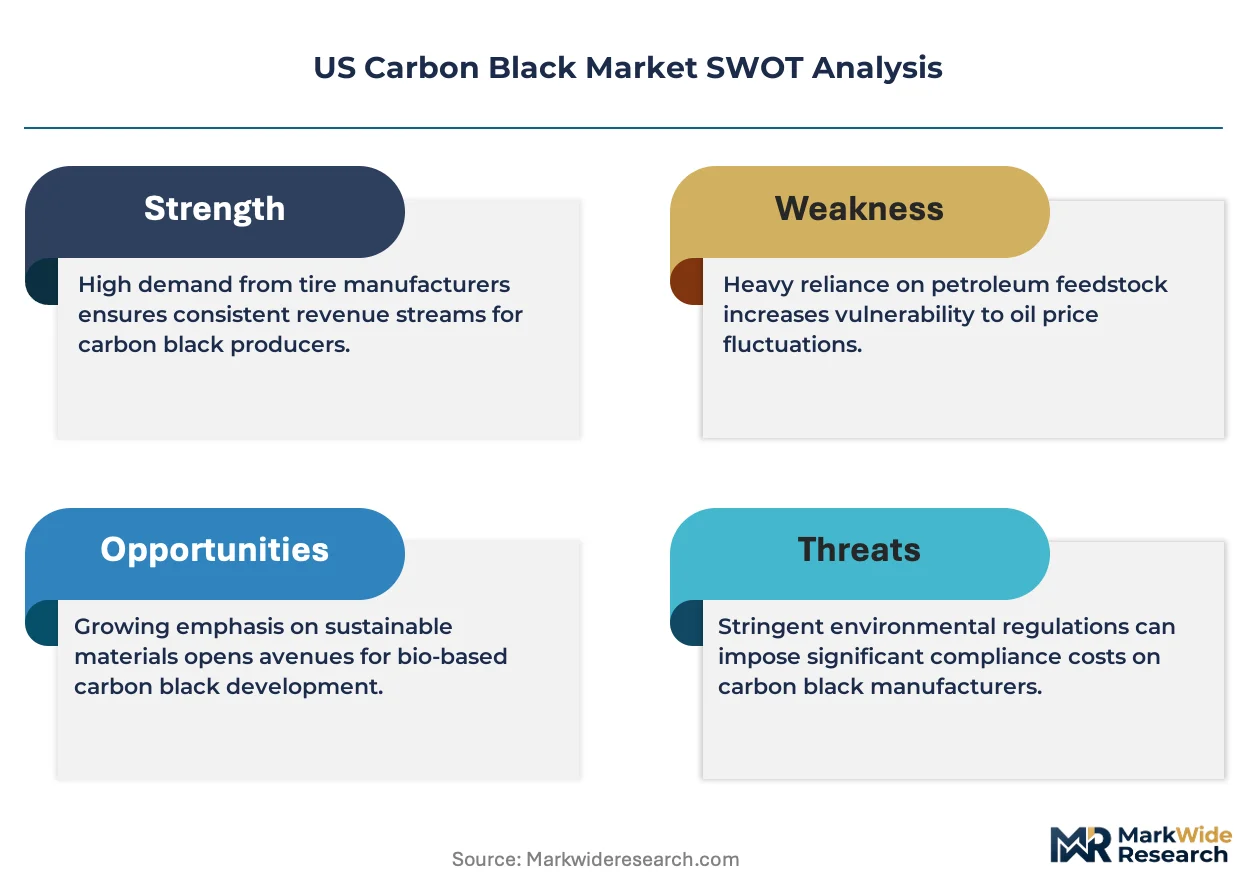
EPA emissions standards under the Clean Air Act constrain furnace black plant expansions, while OSHA permissible exposure limits shape workplace engineering controls and respiratory protection mandates. NHTSA tire performance regulations indirectly drive carbon black specification upgrades as rolling resistance and wear targets tighten. Stakeholders must monitor feedstock cost volatility linked to refinery output shifts and assess conductive grade capacity additions serving battery anode demand.
Market Dynamics
Tire manufacturers are recalibrating their carbon black specifications as electric vehicle platforms demand higher reinforcement grades with lower rolling resistance, compressing traditional procurement cycles and favoring Gulf Coast supply proximity.
Growth Catalysts
- NHTSA tire performance mandates:Rolling resistance and tread wear regulations are forcing compounders to upgrade to higher surface-area furnace black grades, tightening supplier qualification timelines.
- Battery conductive additives:Lithium-ion anode formulations are pulling acetylene black volumes beyond historical rubber applications, creating parallel demand channels.
- Gulf Coast petrochemical corridor concentration:Refinery integration into carbon feedstock supply is shortening logistics loops for domestic tire builders.
Market Restraints
- EPA Clean Air Act emissions caps:Furnace black plant expansions face permitting bottlenecks that extend project timelines and constrain domestic capacity additions.
- Carbon feedstock cost volatility:Refinery output shifts tied to transportation fuel demand swings transmit directly into carbon black production economics.
- Silica-silane tread formulations:Partial substitution in low-rolling-resistance tire segments is compressing volume growth in standard reinforcement grades.
Strategic Opportunities
- Texas-Louisiana industrial corridor densification:Proximity to hydrogen and carbon capture infrastructure positions existing plants for low-emission process retrofits.
- Conductive grade capacity for energy storage:Battery anode demand is outpacing domestic acetylene black supply, opening margin expansion for specialty production investments.
- OSHA workplace exposure rule tightening:Respiratory protection mandates are accelerating demand for pelletized, low-dust carbon black handling systems.
Industry Challenges
- Process control engineering talent scarcity:Furnace black reactor optimization requires specialized combustion expertise that competes with broader petrochemical sector hiring.
- EPA Title V operating permit timelines:New source review procedures for modified emissions profiles extend commissioning schedules and compress project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Carbon Black Market |
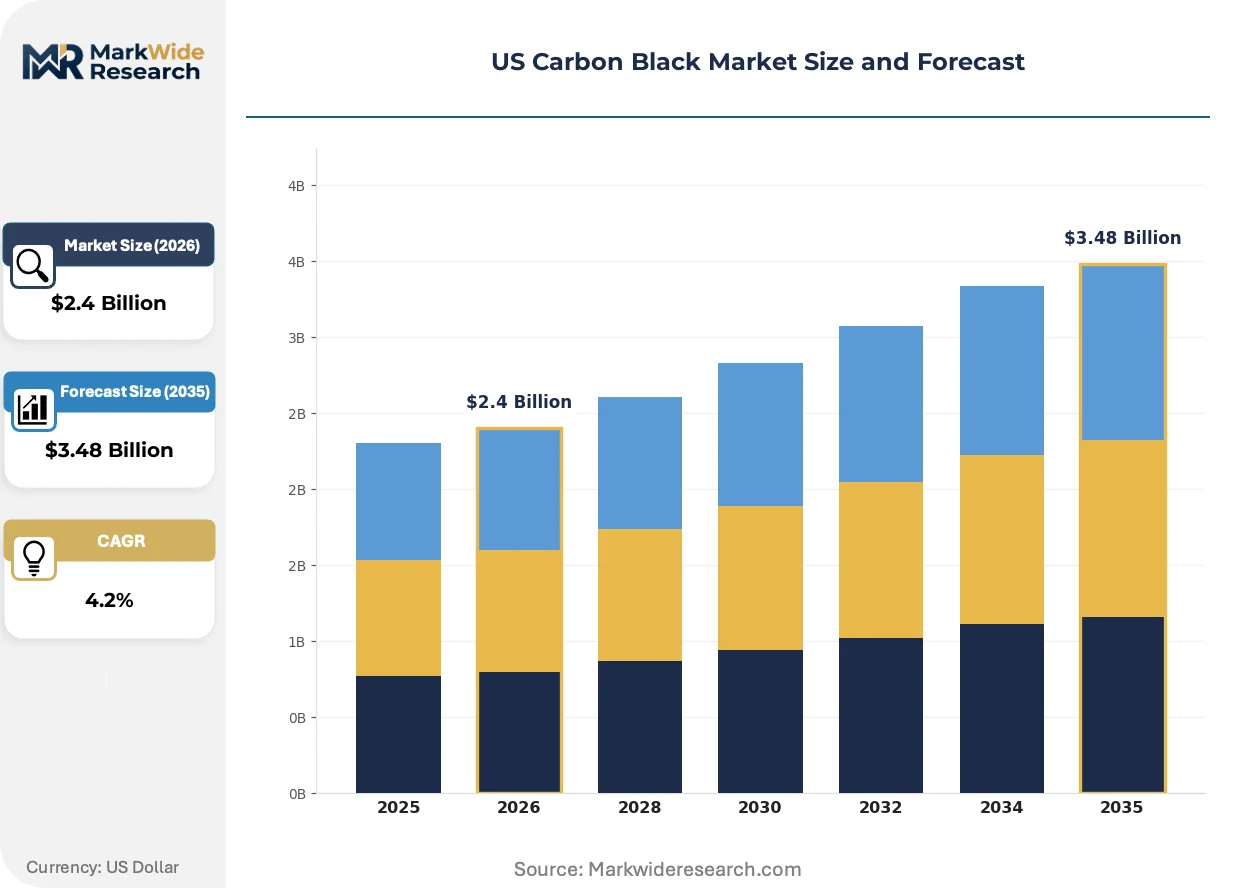
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Carbon Black, High Performance Carbon Black, Specialty Carbon Black, Rubber Reinforcement End Use Industry: Tires, Coatings, Plastics, Inks Manufacturing Process: Furnace Black, Thermal Black, Acetylene Black, Lamp Black Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Cabot Corporation, Birla Carbon, Orion Engineered Carbons, Continental Carbon Company, Sid Richardson Carbon & Energy Co, Tokai Carbon Co., Ltd., Mitsubishi Chemical Corporation, Phillips Carbon Black Limited, Aditya Birla Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Carbon Black Market Trends and Innovations
Carbon black production is bifurcating between commodity furnace black tied to tire cycles and specialty grades serving conductive applications, with process technology and regulatory compliance emerging as the primary axes of differentiation.
Acetylene black production for battery conductive additives is expanding into anode material supply chains previously dominated by graphite and carbon nanotubes. Cell manufacturers are qualifying domestic acetylene sources to reduce import dependency for high-purity conductive grades. This technology is expanding into energy storage applications beyond automotive, compressing the timeline for specialty carbon black capacity additions.
EPA emissions standards under the Clean Air Act are constraining furnace black plant modifications and new source permitting. Industrial consequence includes extended project development timelines and elevated compliance capital requirements for existing Gulf Coast facilities. The tire reinforcement segment is responding by consolidating procurement around qualified suppliers with permitted expansion headroom.
Compounders are compressing their supplier qualification cycles as electric vehicle platforms demand faster formulation iterations. Direct mill integration agreements are displacing traditional distributor relationships for high-volume tire builders. This pattern is most visible in the Southeast manufacturing corridor where domestic tire plant construction is concentrating procurement leverage.
US Carbon Black Market Segmentation
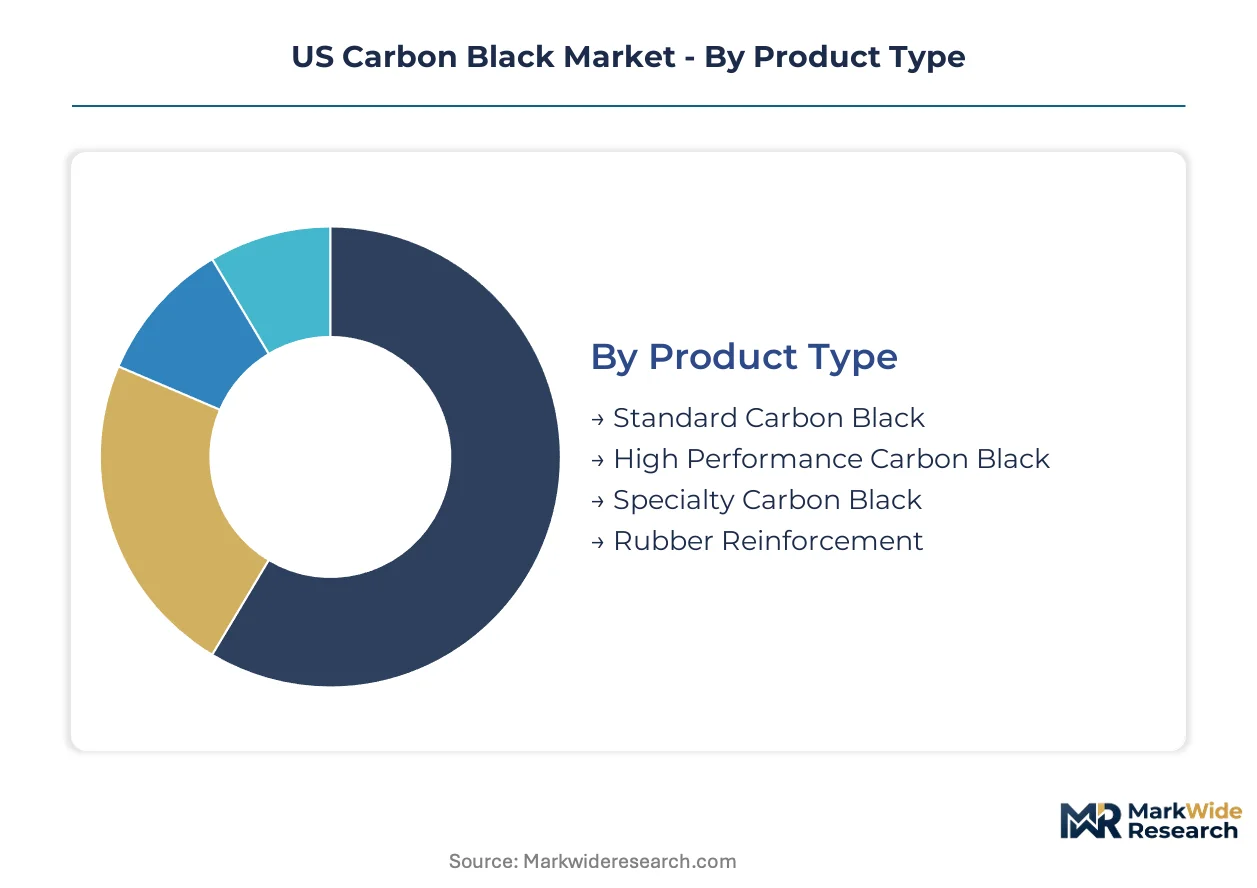
Carbon black procurement decisions in the US market hinge on performance specifications, regulatory compliance, and supply chain proximity. Tire compounders dominate volume, while battery and coatings applications pull specialty grades into faster expansion trajectories.
Product Type:
Buyers differentiate primarily by reinforcement performance and dispersion requirements, with price premiums scaling sharply for conductive and high-purity grades.
- Rubber Reinforcement:Furnace black dominates this volume anchor, delivering tensile strength and abrasion resistance to tire treads and carcass compounds. Demand concentrates with Gulf Coast tire builders seeking qualified suppliers with EPA-permitted expansion headroom.
- Specialty Carbon Black:High-purity grades with controlled particle morphology serve battery anode conductive networks and premium coatings. Growth tilts toward Texas-Louisiana corridor producers investing in acetylene black capacity for energy storage applications.
- Standard Carbon Black:Commodity furnace black grades for general rubber goods and industrial belting face margin compression from silica substitution in low-rolling-resistance segments.
- High Performance Carbon Black:Ultra-high surface area grades above 150 m²/g command qualification premiums from EV tire compounders balancing wear resistance against rolling resistance targets.
Volume sits with Rubber Reinforcement; growth tilts toward Specialty Carbon Black.
End Use Industry:
Application-specific formulation requirements create divergent procurement patterns across industrial verticals.
- Tires:The dominant demand channel, consuming furnace black for tread, sidewall, and carcass reinforcement. NHTSA rolling resistance mandates are compressing qualification cycles and favoring direct mill integration agreements with domestic producers.
- Plastics:Masterbatch compounders specify carbon black for UV stabilization and conductivity in automotive and packaging applications. Demand concentrates in Southeast manufacturing corridors adjacent to polymer processing clusters.
- Coatings:High-dispersion specialty grades serve automotive refinish and industrial protective coatings. Stringent VOC regulations constrain formulation flexibility and elevate premium grade procurement.
- Inks:Pigment blacks for publication gravure and newsprint face structural decline from digital media substitution, though packaging ink demand provides residual volume.
Procurement scale favors Tires; margin expansion concentrates in Plastics conductive applications.
Manufacturing Process:
Process selection determines feedstock flexibility, emissions profile, and product purity ceiling.
- Furnace Black:The cost-efficient workhorse process, combusting aromatic feedstocks in refractory reactors. EPA Title V permitting bottlenecks constrain domestic capacity additions and consolidate supply around existing Gulf Coast assets.
- Acetylene Black:Thermal decomposition of acetylene yields ultra-high purity conductive material for lithium-ion battery anodes. Cell manufacturers are qualifying domestic sources to reduce import dependency for this critical energy storage input.
- Thermal Black:Natural gas cracking produces low-ash, high-purity grades for specialty rubber and food-contact applications. Niche positioning reflects feedstock cost sensitivity and limited scale economies.
- Lamp Black:Historical process retained for artistic and specialty coating pigments where specific surface chemistry properties outweigh production economics.
Output volume concentrates in Furnace Black; capacity investment flows toward Acetylene Black.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and inventory velocity needs.
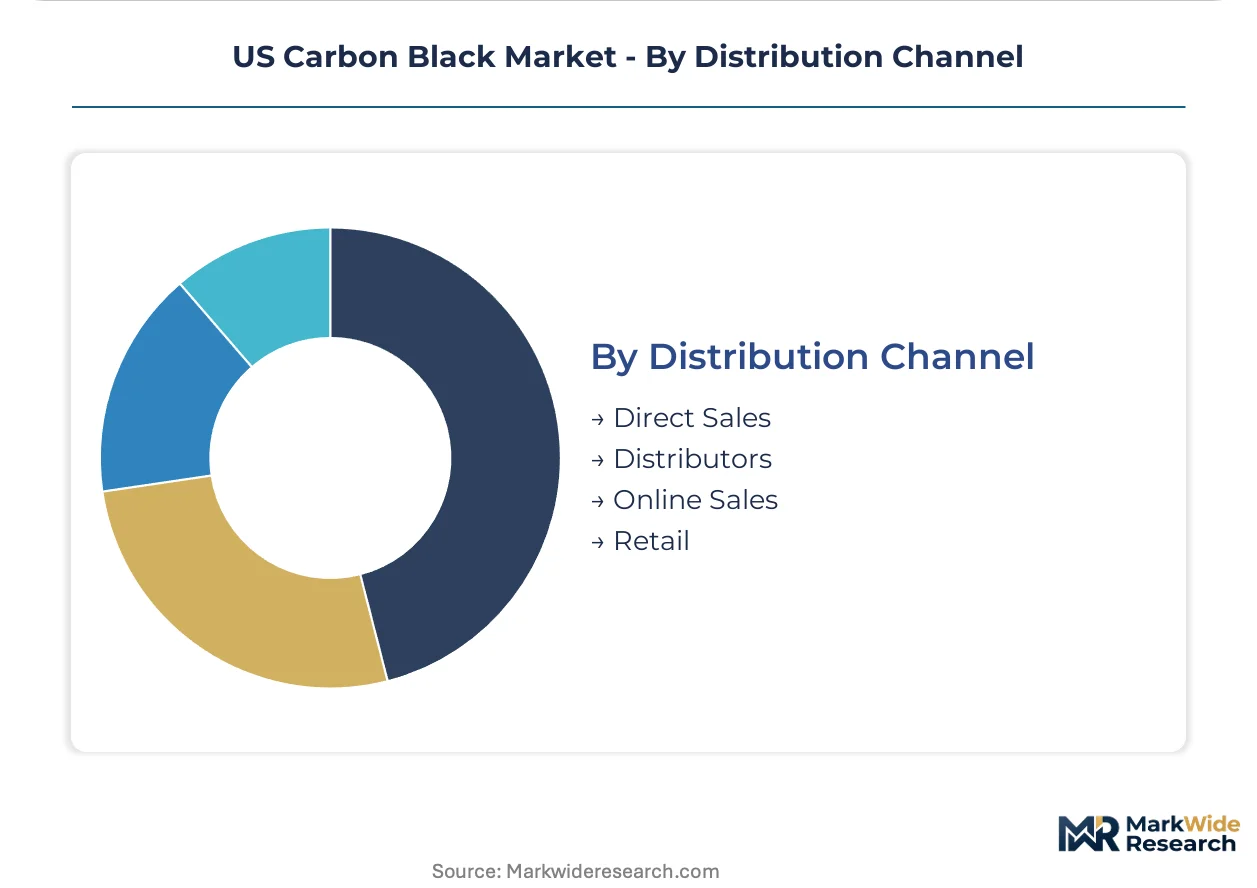
- Direct Sales:High-volume tire manufacturers negotiate direct mill supply agreements, leveraging concentrated procurement in the Southeast manufacturing corridor to compress logistics costs and secure allocation priority.
- Distributors:Regional stocking distributors serve mid-tier compounders and specialty formulators requiring technical support and smaller lot flexibility.
- Online Sales:E-procurement platforms gain traction for standardized grades among smaller industrial rubber goods producers seeking price transparency.
- Retail:Limited to artisan and small-scale coating applications with minimal commercial significance.
Transaction volume flows through Direct Sales; channel diversification expands fastest in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US carbon black production concentrates along the Gulf Coast petrochemical corridor, while consumption disperses across tire manufacturing clusters in the Southeast and Midwest. This geographic mismatch shapes logistics economics and supplier qualification patterns. EPA regional offices in Dallas and Atlanta administer divergent permitting timelines that affect capacity expansion feasibility.
Texas Gulf Coast
Refinery integration supplies aromatic feedstocks to furnace black producers clustered between Houston and Beaumont. EPA Region 6 Title V permitting authority shapes expansion timelines for existing facilities. Port Arthur and Baytown anchor the nation's densest carbon black manufacturing concentration, with pipeline networks connecting to regional hydrogen infrastructure.
Louisiana Industrial Corridor
Baton Rouge and Lake Charles host legacy carbon black assets positioned for carbon capture retrofits. State environmental quality regulations align with federal OSHA workplace exposure mandates for pelletized handling systems. The corridor's proximity to LNG export terminals creates feedstock cost volatility tied to natural gas pricing swings.
Southeast Manufacturing Belt
Tire plant construction in South Carolina, Georgia, and Tennessee pulls carbon black volumes eastward from Gulf Coast suppliers. NHTSA regional enforcement offices in Atlanta monitor rolling resistance compliance for tires produced in this corridor. Greenville-Spartanburg and Nashville metropolitan areas concentrate compounder demand for high-performance reinforcement grades.
Ohio River Valley
Legacy rubber goods manufacturing in Akron and Cincinnati sustains demand for standard furnace black grades. OSHA regional administrators in Chicago administer workplace exposure compliance across this industrial footprint. The region's aging carbon black handling infrastructure faces pelletized system upgrade requirements.
California
CARB emissions regulations constrain carbon black usage in coatings and plastics formulations across Los Angeles and Bay Area industrial zones. Battery manufacturers in Fremont and San Jose qualify conductive grades for anode applications. The state's advanced recycling mandates are reshaping carbon black sourcing for circular economy plastics.
US Carbon Black Market Competitive Landscape
Top-tier vendors anchor the integrated petrochemical tier, while mid-scale specialists occupy niche conductive and thermal black positions. The US market structures around three to four domestic furnace black producers with Gulf Coast manufacturing footprints, supplemented by importers serving coastal specialty grade demand. Strategic archetypes include refinery-integrated commodity producers, acetylene black specialists for battery applications, and regional distributors with technical service capabilities. Capacity expansion and direct mill integration agreements constitute the dominant competitive moves as tire manufacturers consolidate procurement leverage.
Among domestic integrated producers, Cabot Corporation and Birla Carbon exemplify the refinery-tied commodity archetype with extensive Gulf Coast manufacturing infrastructure. Orion Engineered Carbons occupies a distinct position emphasizing specialty conductive grades for energy storage applications beyond traditional rubber reinforcement. These three entities represent the primary competitive anchors shaping supply availability and qualification standards across tire and battery end-use segments.
| Leading Market Players |
|---|
| Cabot Corporation |
| Birla Carbon |
| Orion Engineered Carbons |
| Continental Carbon Company |
| Sid Richardson Carbon & Energy Co |
| Tokai Carbon Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Phillips Carbon Black Limited |
| Aditya Birla Group |
| Others |
Pricing and Supply Chain Analysis
Refinery-integrated commodity producers anchor supply discipline along the Gulf Coast, translating captive feedstock access into pricing power that resists volatility for qualified tire compounders while compressing margins for spot-market buyers lacking direct mill integration.
Pricing Analysis
Cost-down pressure on standard furnace black grades accelerates because silica-silane tread formulations erode volume leverage for commodity reinforcement tiers. Contract-based long-term offtake dominates tire procurement, with price differentiation hinging on EPA permitting status and Gulf Coast logistics proximity. EV tire compounders exhibit lowest price sensitivity for ultra-high surface-area grades above 150 m²/g, while general rubber goods manufacturers face acute margin compression from feedstock cost transmission.
Supply Chain Analysis
ISO 14001 and Responsible Care certification gates supplier qualification for major tire builders, filtering out non-compliant distributors from direct mill agreements. Domestic production concentrates in Texas and Louisiana, with residual thermal black capacity in Ohio. Feedstock dependency rests on refinery aromatic stream output and natural gas pricing swings. Single-source vulnerability concentrates around Port Arthur furnace black clusters. Distribution runs through direct sales contracts for high-volume tire manufacturers, with regional distributors serving specialty coatings and plastics compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Title V permitting bottlenecks and feedstock cost volatility are forcing consolidation around Gulf Coast incumbents with expansion headroom, squeezing marginal producers out of qualified supplier rosters.
For Market Incumbents: Extend carbon capture retrofit investments across Texas-Louisiana assets to preempt EPA emissions enforcement and secure permitting priority for capacity additions. Deepen backward integration into hydrogen infrastructure to deflect natural gas price volatility. Lock direct mill integration agreements with Southeast tire plant expansions before qualification windows close. For New Entrants and Emerging Players: Regional distributors with technical service capabilities offer the most penetrable channel for specialty conductive grades targeting battery anode qualification. Target California battery manufacturers seeking domestic acetylene black alternatives to Asian import dependency. Lead with carbon footprint certification and fast-tracked EPA pre-consultation to differentiate against legacy furnace black suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor acetylene black specialists in the Texas-Louisiana corridor with existing battery qualification pipelines and unutilized permitting headroom. Long-term viability centers on energy storage demand outrunning domestic conductive grade supply. Monitor NHTSA rolling resistance mandate tightening as the inflection signal for high-performance reinforcement grade premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | EPA Region 6 permitting priority secures expansion headroom for Gulf Coast furnace black assets. |
| Acetylene Black Capacity Addition | Battery anode qualification pipelines reduce import dependency for lithium-ion cell manufacturers. |
| Direct Mill Integration Agreement | Southeast tire plant construction compresses logistics costs and locks procurement allocation priority. |
| Pelletized Handling System Upgrade | OSHA respiratory protection mandates accelerate demand for low-dust carbon black delivery formats. |
| Backward Integration into Feedstock | Refinery aromatic stream access insulates production economics from transportation fuel demand swings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving carbon black plant managers, tire compounder procurement leads, battery cell manufacturing engineers, and EPA regional compliance officers. Bottom-up volume triangulation against top-down value estimates incorporated American Chemistry Council production surveys, SEC 10-K disclosures from integrated petrochemical producers, and NHTSA tire performance compliance databases.
Segment-level modeling applied product-grade tiers, end-use industry verticals, manufacturing process technologies, and regional production hub configurations across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EV tire penetration rates and battery conductive additive qualification timelines. Forecast inputs included refinery output shift scenarios and EPA Title V permitting queue projections.
Caveats apply where EPA emissions rule acceleration or silica substitution breakthroughs in low-rolling-resistance treads could materially shift the outlook. A model refresh is warranted upon material change in NHTSA tire performance mandate stringency or domestic acetylene black capacity commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Precipitated Calcium Carbonate Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
North America Potassium Permanganate Market