
 Molybdenum Disilicide Market | 2026-2036
Molybdenum Disilicide Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum Disilicide Market Foresight
Specialized distributor networks for high-temperature refractory materials is reshaping how molybdenum disilicide reaches end-users across fragmented industrial geographies. Kanthal leverages its Sandvik parent integration to sustain captive supply chains from powder to finished heating elements. I Squared R Element Co. anchors North American aftermarket service for furnace rebuilds, while Zhengzhou Chida dominates domestic Chinese production scale for export-grade sintered products.
Molybdenum disilicide is an intermetallic compound of molybdenum and silicon with a melting point exceeding 2,030°C, manufactured primarily through powder metallurgy sintering or chemical vapor deposition coating to enhance oxidation resistance in cyclic thermal environments. It serves as the core conductor in radiant heating elements for furnaces operating between 1,600°C and 1,850°C where metallic alloys fail. Sintered molybdenum disilicide occupies the highest volume tier due to its cost efficiency in standard industrial heater replacements, while coated variants command premium positioning in aerospace crucible applications where thermal shock tolerance determines service life. Electronics end users represent the fastest-growing demand pool as semiconductor diffusion furnaces require ultra-pure, non-contaminating heating elements.
EPA emissions rules for industrial furnaces and EU ETS carbon pricing frameworks are forcing upgrades from legacy silicon carbide to higher-efficiency molybdenum disilicide elements that reduce energy intensity per thermal cycle. China's GB standards for refractory materials and SAMR quality certification requirements shape export eligibility for domestic producers serving European and North American buyers. Stakeholders must monitor divergence between regional carbon accounting methodologies and their cascading effects on furnace retrofit capital allocation priorities.
Market Dynamics
Furnace emissions compliance timelines in the US and EU are forcing accelerated replacement cycles for legacy heating elements, compressing capital allocation decisions and reshaping procurement relationships between refractory distributors and industrial end users.
Growth Catalysts
- EPA Industrial Furnace Standards:Tightening emissions thresholds for metal heat-treating operations mandate thermal efficiency upgrades, directly stimulating element replacement demand in automotive and aerospace supply chains.
- Semiconductor Diffusion Furnace Expansion:Electronics manufacturers in Taiwan and South Korea require ultra-pure MoSi2 heating elements for silicon wafer processing at sustained 1,600°C+ temperatures.
- Shandong-Henan Refractory Cluster Density:China's concentrated powder metallurgy infrastructure enables integrated sintering-to-export supply chains that reduce lead times for international furnace rebuilds.
Market Restraints
- Molybdenum Concentrate Volatility:Raw material input costs fluctuate with mining output from Chile and the US, compressing margin stability for sintered product manufacturers.
- Silicon Carbide Substitution in Lower-Temperature Zones:Legacy SiC elements retain cost advantage in furnace sections operating below 1,500°C, limiting MoSi2 penetration in budget-constrained retrofits.
- REACH Registration Burden:EU chemical compliance requirements for intermetallic compounds create administrative friction for Chinese exporters seeking European market access.
Strategic Opportunities
- India's PLI-Linked Semiconductor Fabrication:Domestic chip manufacturing incentives under India's production-linked incentive scheme will generate localized demand for high-purity heating elements in new diffusion furnace installations.
- Chemical Vapor Deposition Coating Convergence:Hybrid CVD-sintered architectures combining oxidation resistance with structural durability open aerospace crucible applications previously closed to standard grades.
- EU ETS Carbon Pricing Acceleration:Rising carbon cost exposure for energy-intensive industries creates regulatory tailwind for efficiency-maximizing furnace upgrades across German and Italian metal processing sectors.
Industry Challenges
- High-Temperature Ceramics Engineering Talent Scarcity:Specialized expertise in intermetallic sintering process control remains concentrated among retiring cohorts in Japanese and German research institutions.
- SAMR Export Certification Timelines:China's quality certification bureaucracy creates unpredictable delays for domestic producers seeking to fulfill European furnace rebuild contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum Disilicide Market |
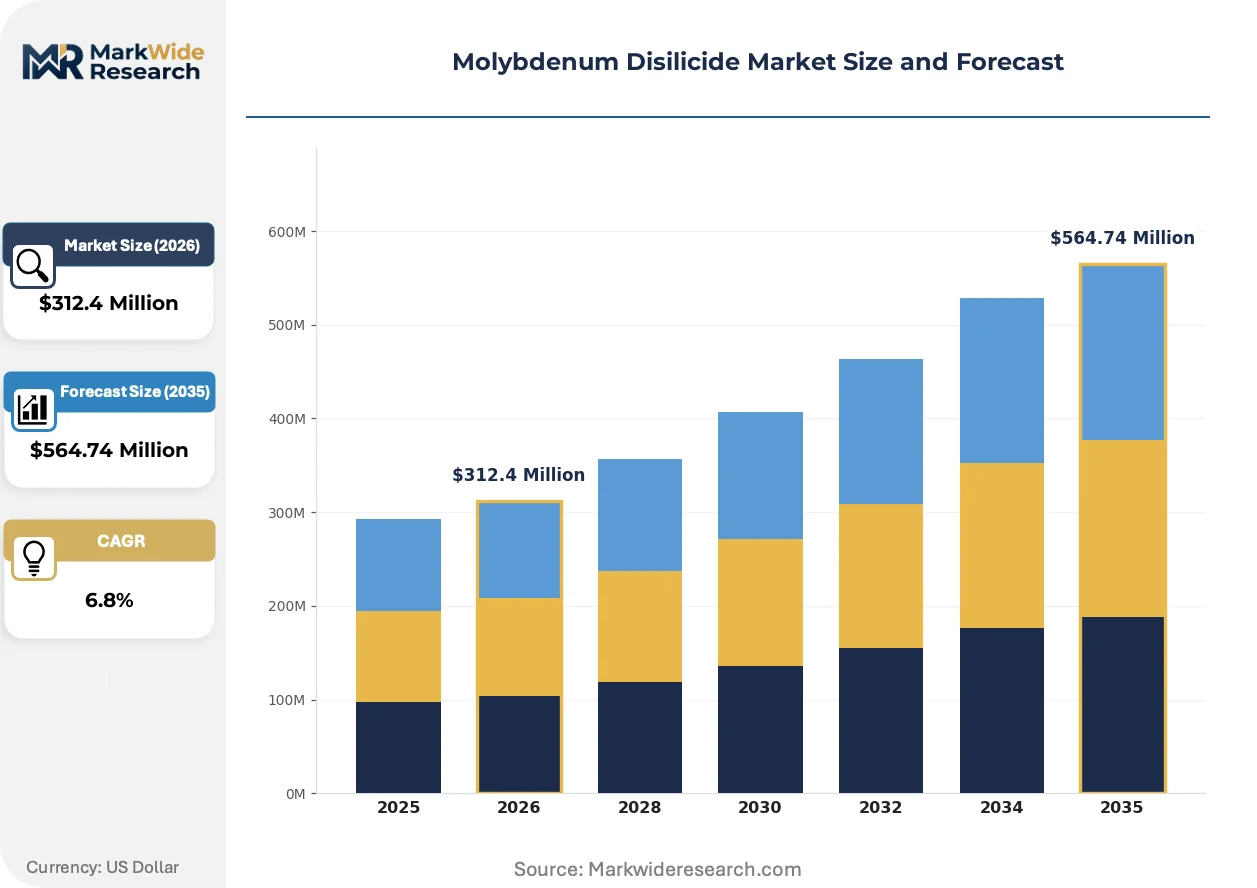
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Molybdenum Disilicide, Uncoated Molybdenum Disilicide, Machined Molybdenum Disilicide, Sintered Molybdenum Disilicide Application: Aerospace, Automotive, Electronics, Industrial Heaters End User: Manufacturing, Research Institutions, Aerospace Organizations, Electronics Companies Delivery Mode: Direct Supply, Online Sales, Distributors, Retail |
| Companies Covered | Kanthal (Sandvik Group), I Squared R Element Co., American Elements, MHI (Mitsubishi Heavy Industries), Zhengzhou Chida, ZIRCAR, Yantai Torch, Shanghai Caixing, SCHUPP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum Disilicide Market Shifts & Advancements
Active materials engineering and regulatory carbon accounting are converging to redefine how furnace operators evaluate heating element lifecycle economics, shifting procurement criteria from upfront cost toward thermal efficiency and emissions compliance.
Advanced CVD-coated molybdenum disilicide architectures deliver superior oxidation resistance in cyclic thermal environments exceeding 1,800°C. Aerospace crucible manufacturers in France and Germany are adopting these variants for single-crystal superalloy casting applications. The technology is migrating from niche defense procurement toward broader commercial aviation supply chains as thermal shock tolerance specifications tighten.
EU ETS Phase IV carbon pricing mechanisms now embed furnace energy intensity into operating cost structures for metal processors. German steel and aluminum heat-treatment facilities face measurable carbon cost exposure per thermal cycle. This regulatory pressure concentrates upgrade demand among mid-cap operators in North Rhine-Westphalia and Bavaria seeking to defend margin positions through efficiency investments.
Aftermarket service unbundling is disrupting traditional bundled heater replacement contracts. Industrial furnace operators in Japan now separately procure diagnostic assessment, element sourcing, and installation supervision. This behavioral shift fragments supplier relationships and elevates specialized distributor technical capabilities, with Tokyo-Osaka corridor rebuild specialists capturing expanded margin pools through service modularization.
Molybdenum Disilicide Market Segmentation
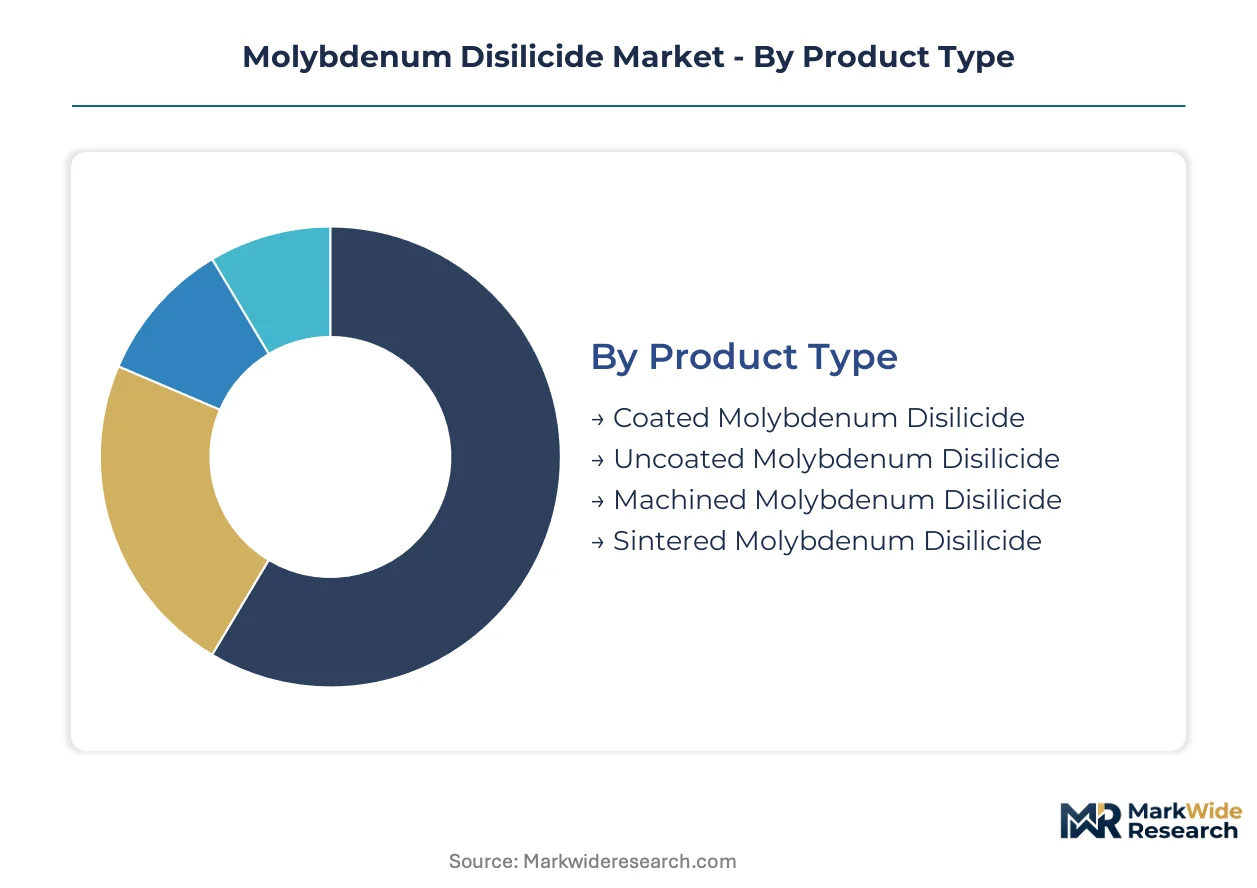
Molybdenum disilicide procurement patterns diverge sharply across product grades and end-use specifications. Furnace operators in Germany and Japan prioritize certified sintered elements for emissions compliance, while semiconductor fabs in Taiwan demand ultra-pure coated variants for contamination-sensitive processes.
Product Type:
Mature sintering infrastructure dominates industrial volume, yet emerging coating technologies are capturing premium aerospace applications through enhanced oxidation resistance.
- Sintered Molybdenum Disilicide:Powder metallurgy consolidation at 1,700-1,800°C yields dense intermetallic structures with cost efficiency for standard furnace retrofits. China's Shandong-Henan refractory corridor supplies international rebuild contracts under compressed EPA and EU ETS compliance timelines.
- Coated Molybdenum Disilicide:Chemical vapor deposition applies protective silica layers that extend service life beyond 2,000 thermal cycles. French and German aerospace crucible manufacturers specify these variants for single-crystal superalloy casting where thermal shock tolerance determines component yield.
- Uncoated Molybdenum Disilicide:Baseline intermetallic elements serve budget-constrained furnace sections below 1,600°C where oxidation exposure remains moderate.
- Machined Molybdenum Disilicide:Precision-ground geometries fit custom fixture requirements in research-scale thermal processing equipment.
Sintered Molybdenum Disilicide retains volume leadership; Coated Molybdenum Disilicide holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity furnace retrofits from specification-driven semiconductor and aerospace procurement.
- Industrial Heaters:Radiant heating elements for metal heat-treating furnaces operating at 1,600-1,850°C constitute the foundational demand pool. German steel processors in North Rhine-Westphalia upgrade legacy silicon carbide installations to defend margin positions against EU ETS carbon cost exposure.
- Electronics:Semiconductor diffusion furnaces require ultra-pure MoSi2 conductors that eliminate metallic contamination during silicon wafer processing. Taiwan and South Korea fabrication facilities specify certified non-outgassing grades for sustained high-temperature operation.
- Aerospace:Crucible and fixture applications in superalloy casting demand thermal shock resistance beyond standard industrial specifications.
- Automotive:Heat-treating operations for powertrain components utilize MoSi2 elements where precision temperature uniformity affects metallurgical properties.
Industrial Heaters anchors procurement volume; Electronics is climbing the fastest as semiconductor capacity expansion accelerates.
End User:
Customer type determines certification requirements, with commercial manufacturers prioritizing cost efficiency and research institutions emphasizing specification flexibility.
- Manufacturing:Metal processors and ceramics producers operate the largest installed base of MoSi2-equipped furnaces, driving replacement demand through regulatory compliance cycles.
- Electronics Companies:Semiconductor fabricators impose stringent purity protocols that exclude standard industrial grades from diffusion furnace procurement.
- Aerospace Organizations:Defense and commercial aviation suppliers specify CVD-coated variants for investment casting operations requiring thermal cycle consistency.
- Research Institutions:University and national laboratory thermal processing facilities utilize machined and custom geometries for experimental materials synthesis.
Manufacturing commands the largest addressable base; Electronics Companies is gaining share fastest through semiconductor fabrication buildouts.
Delivery Mode:
Supply concentration shapes channel selection, with integrated producers favoring direct relationships and fragmented end-users relying on distributor technical support.
- Distributors:Specialized refractory distributors in the Tokyo-Osaka corridor and Germany's Ruhr region provide diagnostic assessment, element sourcing, and installation supervision as unbundled services. Technical capabilities differentiate margin capture in aftermarket rebuild cycles.
- Direct Supply:Captive supply chains from Kanthal and Zhengzhou Chida serve high-volume furnace OEMs and multinational metal processors with consolidated procurement functions.
- Online Sales:Standard-grade elements for small-scale research equipment and maintenance spools reach fragmented end-users through digital channels.
- Retail:Limited presence for consumer-scale thermal processing accessories and replacement components.
Distributors retains channel dominance in fragmented industrial geographies; Direct Supply is expanding fastest among consolidated multinational accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Yantai port corridor on China's Shandong Peninsula anchors the densest concentration of molybdenum disilicide powder metallurgy infrastructure, with integrated sintering-to-export supply chains serving furnace rebuild contracts across three continents.
China
Shandong and Henan provinces host vertically integrated refractory clusters where Zhengzhou-based producers manage captive powder sourcing through export-grade certification pipelines. SAMR quality certification requirements shape eligibility for European and North American furnace contracts, compressing lead times for international rebuilds. The Zhengzhou-Luoyang industrial corridor concentrates sintered product capacity for semiconductor diffusion furnace elements.
Germany
North Rhine-Westphalia steel and aluminum heat-treatment facilities face measurable carbon cost exposure under EU ETS Phase IV mechanisms, forcing accelerated replacement of legacy silicon carbide installations. ETS compliance timelines compress capital allocation decisions for mid-cap operators defending margin positions through efficiency investments. The Ruhr region's specialized refractory distributors now unbundle diagnostic assessment from element sourcing and installation supervision.
United States
EPA Industrial Furnace Standards tightening emissions thresholds for metal heat-treating operations directly stimulate MoSi2 element replacement demand across automotive and aerospace supply chains. The Great Lakes manufacturing corridor and Southeast metal processing belt concentrate furnace retrofit activity. American Elements and I Squared R Element Co. anchor aftermarket service networks for diagnostic-led rebuild cycles.
Japan
Tokyo-Osaka corridor rebuild specialists capture expanded margin pools through aftermarket service modularization, separating diagnostic assessment from procurement and installation. METI industrial efficiency guidelines reinforce thermal upgrade incentives for legacy furnace infrastructure. Nagoya-area automotive heat-treatment facilities specify certified sintered elements for powertrain component processing.
France
Aerospace crucible manufacturers in the Auvergne-Rhône-Alpes cluster specify CVD-coated MoSi2 variants for single-crystal superalloy casting operations where thermal shock tolerance determines component yield. REACH registration requirements for intermetallic compounds create administrative friction for non-European suppliers seeking market access. The Grenoble-Lyon corridor concentrates advanced ceramics engineering expertise for high-temperature materials process control.
Molybdenum Disilicide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies across captive supply chains, specialized distributors, and research-scale fabricators. Three archetypes dominate: Sandvik-affiliated integrated producers controlling powder-to-element pipelines; regional aftermarket service specialists unbundling diagnostic and installation functions; and Chinese export-scale sintering houses leveraging cluster density for cost positioning. Competitive moves concentrate on backward integration into molybdenum concentrate sourcing and geographic expansion through distributor technical capability acquisition.
Within the integrated producer tier, Kanthal represents captive supply chain architecture from powder metallurgy through finished heating element distribution. Among North American aftermarket specialists, I Squared R Element Co. occupies a position exemplifying diagnostic-led furnace rebuild service unbundling. At the export-scale end, Zhengzhou Chida anchors Chinese domestic production scale for international sintered product supply.
| Leading Market Players |
|---|
| Kanthal (Sandvik Group) |
| I Squared R Element Co. |
| American Elements |
| MHI (Mitsubishi Heavy Industries) |
| Zhengzhou Chida |
| ZIRCAR |
| Yantai Torch |
| Shanghai Caixing |
| SCHUPP |
| Others |
Supply & Pricing Matrix
China's Shandong-Henan refractory corridor concentrates sintered MoSi2 capacity for export-grade furnace elements, compressing lead times for international buyers while anchoring volume-discount leverage among integrated producers serving EPA and EU ETS compliance timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CVD-coated aerospace crucible grades from sintered industrial heater elements and uncoated baseline products. Price differentiation hinges on SAMR certification tier for export eligibility and volume scale in furnace rebuild contracts. Cost compression in standard sintered grades is intensifying because Shandong cluster producers compete on lead-time reliability for carbon-compliance deadlines. Research institutions exhibit highest price sensitivity due to fragmented procurement budgets, while semiconductor fabs accept premium positioning for contamination-free diffusion furnace specifications.
Supply Chain Analysis
Extended payment terms from Chinese sintering houses to molybdenum concentrate traders stabilize raw material flows through volatile mining output cycles. Supply concentrates in China, Germany, and Japan, with powder metallurgy infrastructure drawing from Chilean and US molybdenum mines and high-purity silicon feedstock. Single-source vulnerability sits with Shandong-Henan cluster dominance for export-grade certification pipelines. Distribution runs through specialized refractory distributors in Germany's Ruhr region and Japan's Tokyo-Osaka corridor, unbundling diagnostic assessment from element sourcing for aftermarket rebuild cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace element procurement is shifting toward platform-economics logic as aftermarket service modularization separates diagnostic assessment from installation supervision, creating interoperability standards across unbundled supplier relationships.
For Market Incumbents: Insulate sintered product margins by securing captive molybdenum concentrate offtake from Chilean mining operations, countering raw material volatility that compresses cost structures for standard-grade competitors. Deepen certification investment in SAMR and REACH compliance pipelines to defend European furnace rebuild contracts against emerging Chinese export-scale rivals.
For New Entrants and Emerging Players: India's PLI-linked semiconductor fabrication clusters offer white-space penetration for high-purity coated MoSi2 elements as domestic chip manufacturing incentives generate localized diffusion furnace demand. Target aftermarket service modularization in Japan's Tokyo-Osaka corridor through technical partnership with diagnostic-led rebuild specialists, capturing margin pools from unbundled procurement behavior.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized refractory distributors with unbundled service capabilities and captive technical assessment relationships. Long-term viability over the coming decade rests on exposure to regulatory carbon pricing acceleration in EU metal processing and semiconductor capacity expansion in Taiwan and South Korea. Acquisition focus should center on mid-scale Chinese sintering houses with SAMR-certified export pipelines and established European distributor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molybdenum Concentrate | Captive raw material sourcing from Chilean mines stabilizes margin exposure to mining output volatility. |
| CVD Coating Technology Licensing | Technology transfer to aerospace crucible manufacturers in France and Germany opens premium application segments. |
| Aftermarket Service Unbundling | Diagnostic assessment separation from installation supervision captures expanded margin pools in Japan's rebuild corridor. |
| REACH Registration Completion | ECHA compliance for intermetallic compounds removes administrative friction for Chinese exporters seeking European access. |
| Semiconductor Fab Partnership Program | Direct supply relationships with Taiwan and South Korea diffusion furnace operators secure ultra-purity certification demand. |
Research Methodology
Initial hypotheses were tested against primary input from furnace OEM procurement directors, refractory distributor technical sales leads, plant engineers at German heat-treatment facilities, and semiconductor fab maintenance managers, then refined through secondary validation against SEC filings from heating element manufacturers, EPA emissions compliance databases, EU ETS carbon market registries, and customs trade data for molybdenum concentrate flows. Bottom-up demand modeling from end-use installation bases and top-down supply capacity assessments from powder metallurgy infrastructure were triangulated to converge on volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product grade tier, end-use industry, purity certification level, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and regulatory compliance deadline clustering. Industry-specific forecast inputs included EPA Industrial Furnace Standards implementation timelines and EU ETS Phase IV carbon price trajectory assumptions for energy-intensive metal processors.
Practitioners should monitor molybdenum concentrate spot price volatility, SAMR certification backlog durations, and semiconductor fabrication capacity announcement flows for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Cermet Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Nickel Superalloy Market