
 Green Steel Market | 2026-2036
Green Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Green Steel Market Outlook
Subscription-based carbon accounting and emissions verification is consolidating around steel procurement platforms. ArcelorMittal leverages its integrated European mill network to bundle certified low-carbon grades with traceability software. H2 Green Steel anchors its offtake strategy through long-term supply contracts tied to automotive OEM decarbonization targets. POSCO competes by extending its hydrogen reduction pilot into commercial-scale output for shipbuilding and energy infrastructure clients.
Green steel denotes iron and steel produced with substantially reduced carbon dioxide emissions, typically below one tonne CO2 per tonne of crude steel equivalent, achieved through hydrogen direct reduction, renewable-powered electric arc furnaces, or biochar substitution in metallurgical processes. Its primary purpose is to supply emission-intensive downstream industries with compliant feedstock under tightening carbon accounting protocols. Hydrogen-reduced steel commands premium positioning as blast furnace replacement timelines compress in Europe and Northeast Asia. Scrap recycling occupies the volume tier due to immediate availability and lower capital intensity, though quality constraints limit deployment in automotive exposed panels. Carbon capture utilization segments attract project finance where geological storage or chemical feedstock offtake exists.
The EU Carbon Border Adjustment Mechanism and REACH compliance protocols are reshaping import competitiveness for conventional steel into European manufacturing supply chains. EPA greenhouse gas reporting rules and the US Inflation Reduction Act hydrogen production credits are accelerating domestic green steel project development in the Gulf Coast and Midwest industrial corridors. Stakeholders must monitor offtake contract structures, hydrogen supply cost curves, and certification standard convergence between ISO and national frameworks to secure position before capacity commitments lock in regional supply hierarchies.
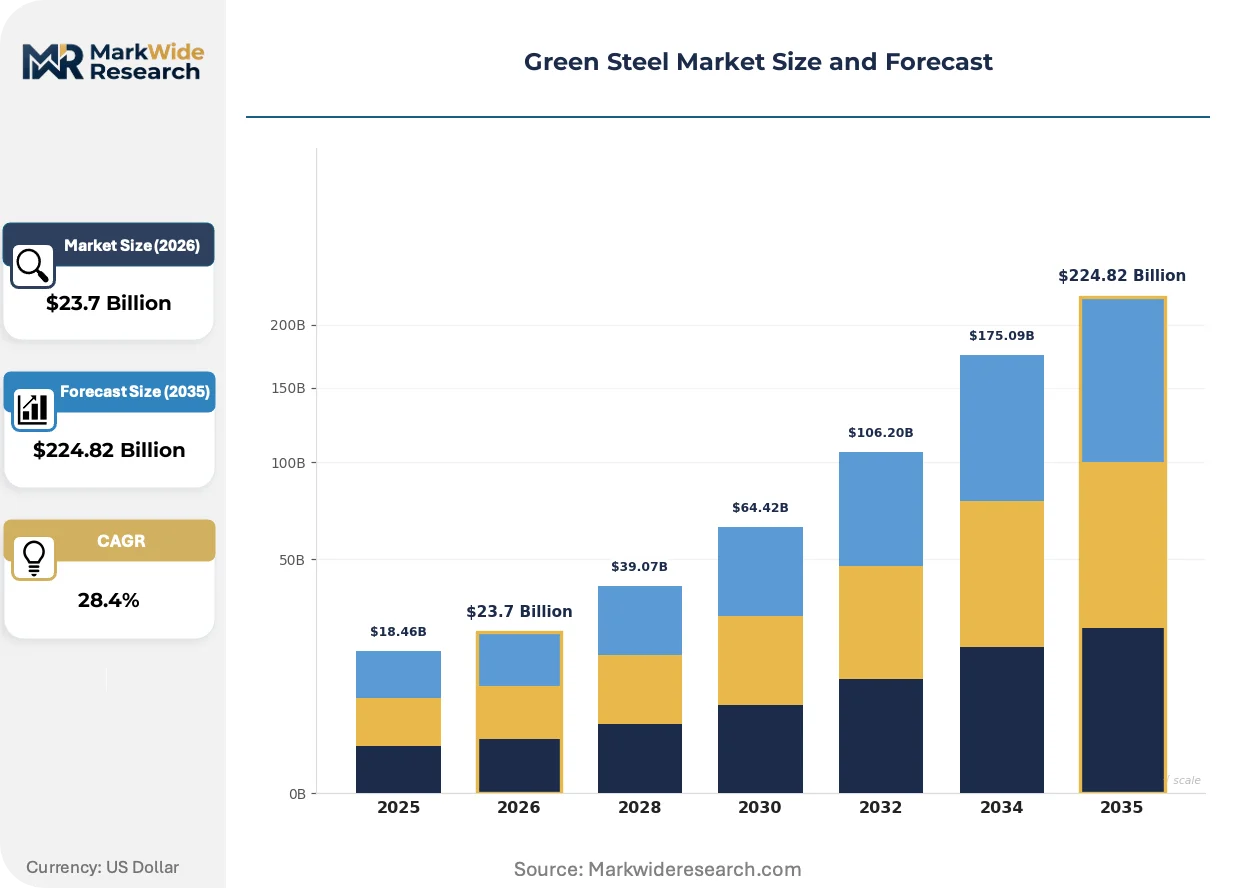
Market Dynamics
Hydrogen direct reduction economics are compressing blast furnace replacement timelines across European and Northeast Asian steel corridors, forcing incumbent producers to reconfigure capital allocation toward renewable-powered electric arc furnace clusters before 2030 carbon accounting deadlines lock in supply hierarchies.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Import charges on conventional steel are redirecting procurement budgets toward certified low-carbon grades for automotive and construction supply chains entering European manufacturing networks.
- Automotive OEM decarbonization targets:Scope 3 emissions mandates from vehicle manufacturers are creating binding offtake commitments for hydrogen-reduced steel in exposed panel and structural component applications.
- Hydrogen electrolyzer cost curves:Renewable hydrogen production economics are crossing threshold viability for direct reduction integration in coastal industrial zones with offshore wind access.
Market Restraints
- Renewable electricity input volatility:Grid stability and PPA pricing uncertainty are constraining continuous smelting operations in markets without baseload clean power contracts.
- Scrap quality limitations:Automotive-grade flat products require virgin ore-derived feedstock, restricting secondary steel substitution in premium exposed panel segments.
- Geological storage availability:Carbon capture utilization depends on depleted oil field or saline aquifer proximity, fragmenting project finance access across industrial corridors.
Strategic Opportunities
- US Inflation Reduction Act hydrogen credits:Production tax incentives are enabling Gulf Coast and Midwest green steel project development with integrated renewable hydrogen supply.
- Shipbuilding and energy infrastructure:Heavy plate demand from offshore wind foundations and LNG vessel construction is opening premium offtake channels outside automotive supply chains.
- Subscription-based carbon accounting platforms:Procurement software bundling traceability verification with certified steel grades is capturing recurring revenue from compliance-driven buyers.
Industry Challenges
- Metallurgical engineer scarcity:Hydrogen direct reduction and renewable EAF operation require specialized furnace management expertise absent from conventional blast furnace workforces.
- ISO certification timeline compression:Converging national frameworks and third-party verification protocols are creating audit bottlenecks for commercial-scale output qualification.
- Legacy asset stranded risk:Integrated mill reconfiguration demands simultaneous hydrogen supply contracting, renewable power offtake, and customer certification alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Steel Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $224.82 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Steel, Hydrogen-Reduced Steel, Bio-based Steel, Electric Arc Furnace Steel Application: Automotive Components, Construction Materials, Energy Sector, Heavy Machinery End User: Manufacturers, Construction Companies, Automotive OEMs, Energy Providers Technology: Direct Reduced Iron, Carbon Capture Utilization, Electrolytic Reduction, Scrap Recycling |
| Companies Covered | Nucor Corporation, Thyssenkrupp Steel, ArcelorMittal, Tata Steel, SSAB, H2 Green Steel, POSCO, JSW Steel, Boston Metal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Steel Market Strategic Shifts
Production technology trajectories are diverging between hydrogen-based virgin steel and scrap-intensive circular routes, with certification standards and procurement platforms emerging as the coordinating layer between physically distinct supply chains.
Renewable-powered electric arc furnace clusters are expanding into coastal industrial zones with dedicated offshore wind or solar PV supply. Steel producers in Sweden and Spain are securing 24/7 clean power contracts to guarantee continuous melting operations for automotive-grade flat products. This infrastructure buildout is expanding into regions previously dependent on imported metallurgical coal, compressing the geographic footprint of emission-intensive primary steelmaking.
REACH compliance protocols and EU Green Deal implementation timelines are tightening import competitiveness thresholds for conventional steel. European manufacturers face binding Scope 3 disclosure requirements that cascade down to feedstock procurement decisions. German and French automotive suppliers are restructuring supplier qualification processes to exclude uncertified steel grades from contract eligibility.
Long-term offtake contracting is displacing spot market purchasing for low-carbon steel grades. Automotive OEMs in Germany, Sweden, and South Korea are locking in decade-spanning supply agreements with indexed pricing tied to renewable hydrogen cost trajectories. This contractual shift is concentrating procurement relationships around vertically integrated producers with captive clean power and hydrogen supply, marginalizing merchant steel traders in premium grade segments.
Green Steel Market Segmentation
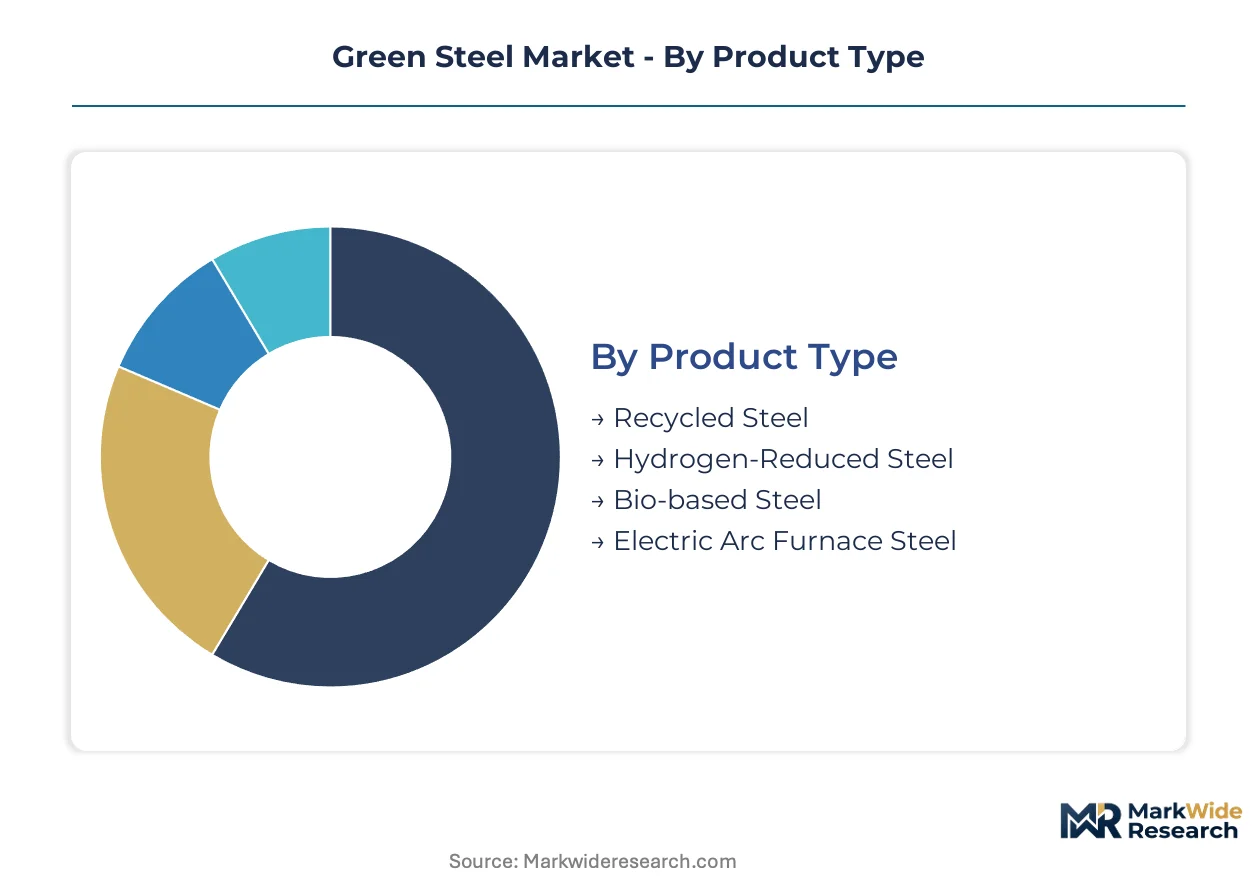
Green steel procurement decisions split across metallurgical pathways and carbon accounting requirements. Buyers prioritize traceability certification, hydrogen sourcing transparency, and Scope 3 compliance alignment over conventional grade specifications.
Product Type:
Cost tier differentiation separates immediate availability from premium positioning across metallurgical routes.
- Hydrogen-Reduced Steel:Virgin iron ore processed through hydrogen direct reduction achieves sub-one-tonne CO2 per tonne crude steel equivalent. German and Swedish automotive OEMs anchor offtake agreements for exposed panel applications where scrap quality constraints block recycled alternatives.
- Recycled Steel:Electric arc furnace processing of ferrous scrap delivers immediate volume with lower capital intensity. Construction materials and non-exposed automotive components in South Korea concentrate demand, though residual copper contamination limits deployment in premium flat products.
- Electric Arc Furnace Steel:Renewable-powered EAF clusters in coastal industrial zones with offshore wind access are scaling output for structural grades. Grid stability and 24/7 clean power contracting remain operational constraints.
- Bio-based Steel:Metallurgical coal substitution with biochar in blast furnace operations offers transitional emission reductions. Pilot-scale production in Brazil and Nordic regions targets construction and heavy machinery segments with less stringent purity requirements.
Volume sits with Recycled Steel; growth tilts toward Hydrogen-Reduced Steel.
Application:
End-use specifications dictate metallurgical pathway selection through quality thresholds and carbon disclosure intensity.
- Automotive Components:Exposed body panels and structural members require virgin ore-derived feedstock for surface quality and crash performance. German OEMs enforce certified low-carbon grade procurement through binding Scope 3 mandates.
- Construction Materials:Rebar and structural sections tolerate higher residual element content, enabling scrap-intensive production. LEED and BREEAM certification protocols are redirecting commercial project specifications toward EPD-verified steel sourcing.
- Energy Sector:Offshore wind foundations and LNG vessel construction demand heavy plate with specialized toughness specifications. South Korean shipbuilders are contracting dedicated hydrogen-reduced capacity for monopile and transition piece fabrication.
- Heavy Machinery:Earthmoving equipment and industrial presses utilize high-strength grades where fatigue resistance outweighs surface cosmetic requirements. Mining sector procurement in Australia and Canada is integrating carbon intensity into supplier scorecards.
Construction Materials command current volume; Energy Sector applications are climbing the fastest.
End User:
Procurement sophistication varies across organizational scale and supply chain position.
- Automotive OEMs:Vertically integrated manufacturers with binding decarbonization targets are locking in decade-spanning supply agreements with indexed hydrogen cost pricing. German, Swedish, and South Korean headquarters anchor these contractual structures.
- Construction Companies:Project-based buyers respond to green building certification requirements rather than internal carbon targets. Large infrastructure contractors in France and Spain are consolidating procurement through certified steel platforms.
- Manufacturers:Diverse industrial equipment producers face fragmented customer pressure for Scope 3 disclosure. Mid-tier metal fabricators in Italy and Poland struggle with certification cost absorption.
- Energy Providers:Utility-scale renewable developers and oil majors transitioning to offshore wind are specifying low-carbon steel for turbine foundations and subsea infrastructure. Long project development timelines align with green steel capacity buildout schedules.
Automotive OEMs dominate premium grade absorption; Energy Providers represent the steepest expansion trajectory.
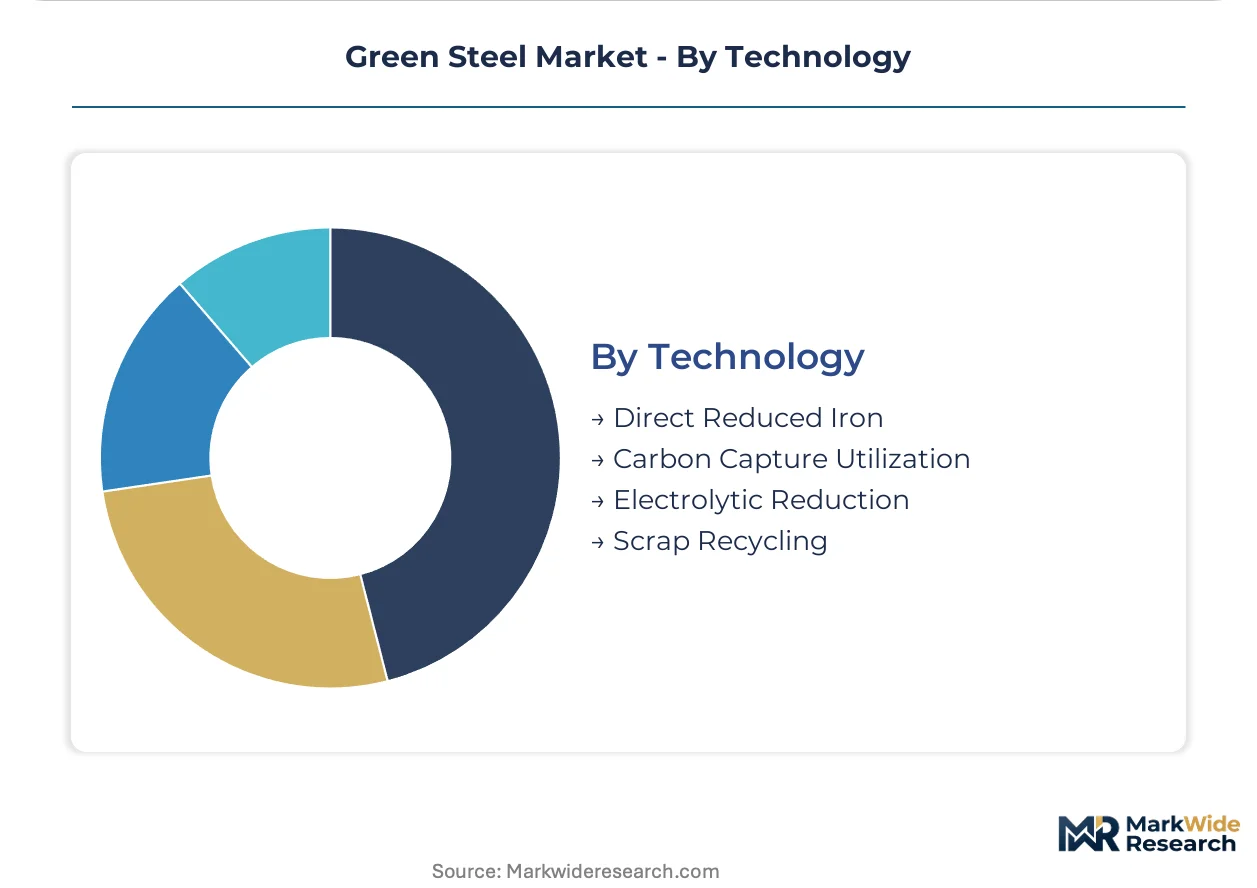
Technology:
Production method selection hinges on feedstock access, power cost structures, and carbon storage geology.
- Direct Reduced Iron:Hydrogen-based DRI shaft furnaces are replacing blast furnaces in European and Middle Eastern corridors with natural gas or renewable hydrogen feedstock. Coastal locations with ammonia import terminals or electrolyzer parks concentrate project development.
- Scrap Recycling:Electric arc furnace remelting of post-consumer and industrial scrap delivers the lowest embodied carbon where renewable power contracts secure continuous operation. Quality sorting and shredder technology upgrades are expanding prime-grade scrap availability.
- Carbon Capture Utilization:Post-combustion capture from conventional blast furnace gas streams enables emission reduction where geological storage or chemical feedstock offtake exists. US Gulf Coast and North Sea regions leverage depleted oil field proximity.
- Electrolytic Reduction:Molten oxide electrolysis at laboratory and pilot scale offers theoretical zero-emission virgin steel production. Alkaline and solid oxide cell configurations are competing for technical validation before commercial scaling.
Scrap Recycling holds installed capacity dominance; Direct Reduced Iron is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in coastal industrial zones with renewable hydrogen access, while consumption concentrates in automotive and construction corridors with binding carbon disclosure mandates. This geographic split is compressing logistics costs into green steel pricing premiums.
Germany
Automotive OEM decarbonization targets in Bavaria and Baden-Württemberg are pulling hydrogen-reduced steel through supplier qualification gates. The EU Carbon Border Adjustment Mechanism tightens import competitiveness for conventional Turkish and Chinese steel. Duisburg and Bremen harbor zones anchor pilot DRI-EAF clusters with dedicated offshore wind PPAs.
Sweden
Boden and Luleå in Norrbotten concentrate Europe's first commercial-scale hydrogen direct reduction capacity. The Swedish Energy Agency's industrial decarbonization grants de-risk electrolyzer park development tied to iron ore pellet supply. SSAB's Oxelösund and Luleå operations exemplify vertical integration from mine to certified flat products.
United States
Gulf Coast hydrogen hub designations in Texas and Louisiana are attracting green steel project finance anchored to IRA production tax credits. Nucor's electric arc furnace network in the Southeast and Midwest expands renewable power contracting for Scope 3 compliance. Cleveland-Cliffs and U.S. Steel reconfiguration timelines in Ohio and Pennsylvania hinge on hydrogen pipeline access.
South Korea
POSCO's Gwangyang complex anchors hydrogen reduction pilot scaling toward commercial output for shipbuilding and LNG vessel construction. The national hydrogen economy roadmap mandates steel sector emission intensity cuts by 2030. Busan-Ulsan heavy plate demand from offshore wind foundations is opening premium offtake channels outside automotive supply chains.
China
Baowu Steel and HBIS Group pilot hydrogen injection into blast furnaces in Shanghai and Hebei corridors under dual carbon goals enforcement. The MIIT's steel industry ultra-low emission transformation guidelines compress conventional capacity timelines. Jiangsu and Shandong provincial carbon trading schemes price marginal ton differentials into procurement decisions.
Green Steel Market Competitive Environment
Capital-heavy integrated producers compete with asset-light greenfield developers for offtake contract anchoring. The market structures around three tiers: legacy mill reconfigurations, pure-play hydrogen DRI ventures, and scrap-intensive EAF operators. Consolidation pressure intensifies as decade-spanning automotive supply agreements lock in procurement relationships before 2030 capacity deadlines.
Among European-based integrated producers, ArcelorMittal and Thyssenkrupp Steel occupy positions bridging blast furnace legacy assets toward hydrogen direct reduction clusters. Nucor Corporation exemplifies the EAF-centric archetype with renewable power contracting scale. H2 Green Steel represents the pure-play greenfield model with captive hydrogen supply integration.
| Leading Market Players |
|---|
| Nucor Corporation |
| Thyssenkrupp Steel |
| ArcelorMittal |
| Tata Steel |
| SSAB |
| H2 Green Steel |
| POSCO |
| JSW Steel |
| Boston Metal |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM Scope 3 mandates in Germany and Sweden are forcing hydrogen-reduced steel procurement into long-term offtake contracts, compressing spot market liquidity and amplifying premium capture for certified grades with traceable hydrogen sourcing.
Pricing Analysis
Margin tightening in hydrogen-reduced grades reflects electrolyzer capital recovery timelines and renewable power contract indexation. Three-tier pricing structure across premium certified, transitional bio-based, and standard scrap-intensive levels stratifies buyers by Scope 3 disclosure intensity. Cost compression in recycled steel intensifies as Chinese export surpluses pressure European EAF operators. Construction contractors exhibit highest price sensitivity; automotive exposed panel procurement shows inelastic demand for virgin ore-derived feedstock.
Supply Chain Analysis
Freight cost differentials between coastal hydrogen hubs and inland automotive manufacturing clusters are reshaping procurement geography. Production concentrates in Sweden, Germany, and South Korea where offshore wind or nuclear baseload secures continuous smelting. Iron ore pellet supply draws from Brazilian and Australian mines; hydrogen feedstock rests on electrolyzer parks and ammonia import terminals. Single-source vulnerability in specialized DRI shaft furnace equipment fragments project timelines. Distribution runs through mill-direct contracts with automotive OEMs, bypassing traditional steel traders in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Carbon Border Adjustment Mechanism enforcement is accelerating capacity consolidation, eliminating merchant traders and unintegrated blast furnace operators unable to secure renewable hydrogen supply before certification deadlines lock in supply hierarchies.
For Market Incumbents: Extend captive hydrogen supply through electrolyzer park joint ventures in coastal industrial zones with dedicated offshore wind access. ArcelorMittal and Thyssenkrupp must accelerate DRI-EAF cluster commissioning in Duisburg and Bremen before 2030 carbon accounting deadlines strand legacy blast furnace assets. Certification investment in ISO-compliant traceability software defends position against pure-play greenfield entrants with integrated carbon accounting platforms.
For New Entrants and Emerging Players: The premium-to-economy price gap in automotive-grade flat products creates white-space opportunity for hydrogen-reduced capacity with indexed renewable power contracts. Target South Korean shipbuilding and offshore wind foundation demand outside automotive supply chain concentration. Enter through decade-spanning offtake agreements with energy infrastructure developers whose project timelines align with green steel capacity buildout schedules.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated developers with captive mine-to-metal control and electrolyzer park offtake. Five-to-ten year viability hinges on hydrogen production cost curves crossing threshold parity with natural gas-based DRI. Monitor convergence between national certification frameworks and ISO protocols as inflection signal for commercial-scale output qualification bottlenecks clearing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Park Joint Venture | Secures renewable hydrogen supply for DRI-EAF clusters in coastal zones with offshore wind access. |
| Long-term Automotive Offtake Contract | Locks in decade-spanning procurement relationships with German OEMs before 2030 certification deadlines. |
| Traceability Software Certification | Bundles carbon accounting verification with steel grades to capture recurring revenue from compliance-driven buyers. |
| Shipbuilding Supply Agreement | Opens premium heavy plate channels outside automotive concentration through South Korean monopile demand. |
| Blast Furnace Reconfiguration | Replaces emission-intensive assets with hydrogen direct reduction before EU Carbon Border Adjustment Mechanism tightens import competitiveness. |
Study Parameters
Independent corroboration across steel procurement executives, hydrogen project developers, and automotive supplier quality engineers underwrites the qualitative findings. Primary interviews with EPC contractors, renewable power offtake specialists, and metallurgical furnace operators combined with secondary validation from customs trade data, EU ETS registry filings, and SEC 10-K disclosures. Bottom-up capacity buildout tracking and top-down carbon accounting policy analysis triangulate market sizing.
Rate-of-change decomposition across the projection horizon isolates hydrogen electrolyzer cost curves, renewable power PPA pricing, and certification standard convergence as demand drivers. Segmentation modeling spans metallurgical pathway, carbon intensity tier, end-use application, and geographic production cluster. CAGRs derive from installed capacity timelines, offtake contract velocity, and policy implementation schedules. Industry-specific inputs include blast furnace retirement announcements and automotive OEM decarbonization target disclosures.
Inputs from electrolyzer manufacturers and steel mill engineering firms were available through the study window; gaps in actual hydrogen-reduced steel production cost data introduce uncertainty bands around margin projections. Forecasts reflect assumptions on EU Carbon Border Adjustment Mechanism enforcement timing and renewable power contract availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Nickel Alloy Market