
 Stainless Steel Market | 2026-2036
Stainless Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Market Intelligence
The direct-to-fabricator sales channel for specialized grades is reconfiguring traditional supply chains previously dominated by large-scale distributors. Tsingshan Holding Group leverages its massive production scale to influence pricing in commodity-grade segments. Meanwhile, Outokumpu differentiates through its focus on high-performance austenitic and duplex stainless steels. Aperam competes on a portfolio of specialty alloys for niche applications in Europe and South America.
Stainless steel is an iron-based alloy containing a minimum of 10.5% chromium by mass. This composition creates a passive, self-repairing chromium oxide layer that provides its characteristic corrosion resistance. Austenitic grades remain the largest product type segment due to their formability and versatility. Demand from construction and chemical processing applications continues to drive volume, while aerospace offers higher margins for specialized alloys.
Producers must navigate a complex regulatory environment, including the EU's REACH regulation on chemical substances and US EPA emissions standards for steel mills. In parallel, China's GB standards dictate specific performance and compositional requirements for market access. Stakeholder success depends on balancing the use of recycled scrap with the sourcing of critical virgin alloys like nickel and chromium to meet tightening sustainability and performance mandates.
Market Dynamics
The market is defined by a tension between decarbonization mandates demanding higher recycled content and end-users requiring virgin alloys like nickel to meet advanced performance specifications. This balance dictates material flow and production strategy.
Growth Catalysts
- Sustainable Infrastructure:Construction sector demand for corrosion-resistant materials in infrastructure, particularly in India, provides significant volume for standard austenitic and duplex grades.
- Decarbonization Policies:China's dual carbon goals promote high-performance stainless steels for applications in renewable energy and electric vehicle components, creating a regulatory pull.
- Circular Economy Alignment:The material's high recyclability aligns with corporate sustainability mandates, creating a preference over less recyclable alternatives in consumer and industrial applications.
Market Restraints
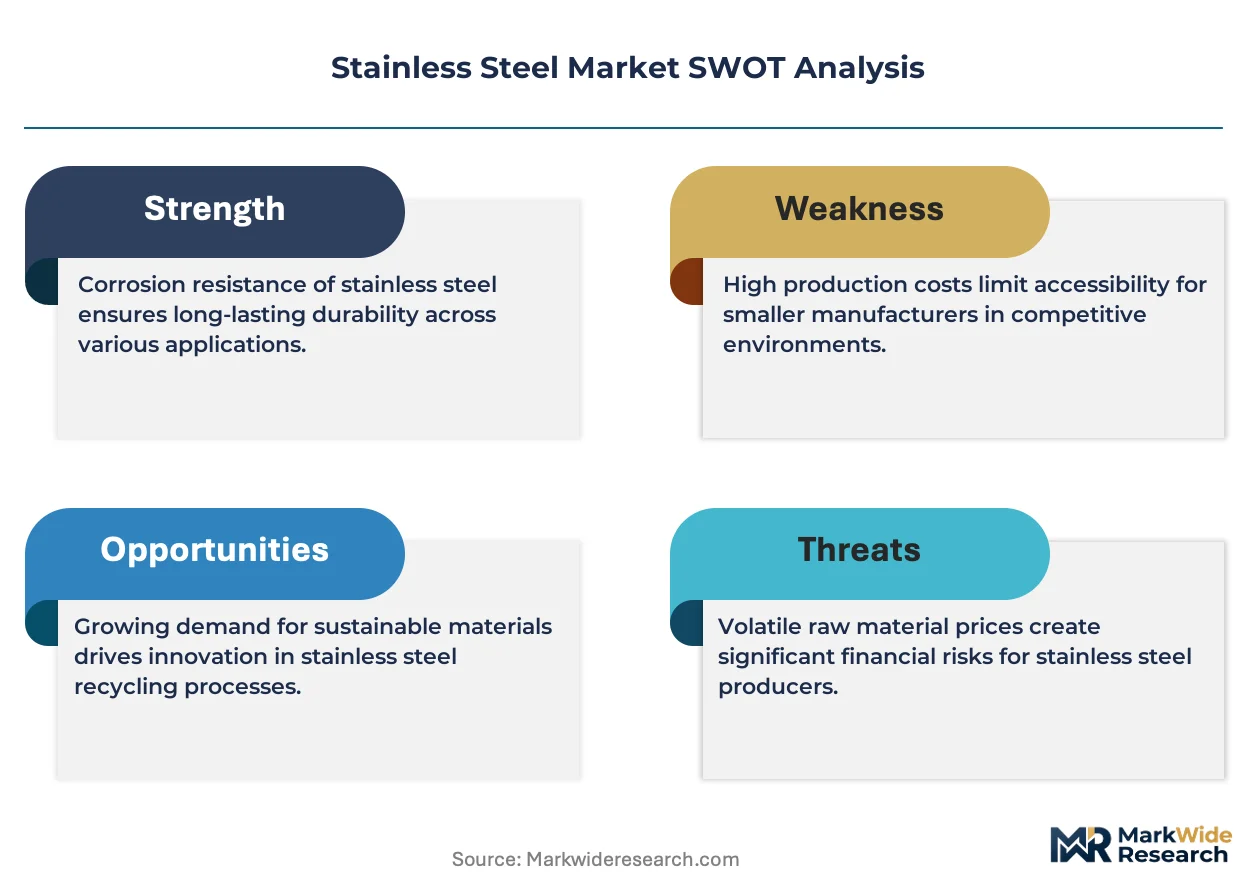
- Input Cost Volatility:Price fluctuations in key alloying elements, especially nickel and chromium, create significant margin uncertainty for producers without robust hedging strategies.
- Regulatory Compliance Burden:Adherence to complex chemical regulations, including the EU's REACH framework, increases testing and documentation costs, acting as a barrier to trade.
- Substitution from Alternatives:High-strength aluminum and composites present a substitution threat in weight-sensitive applications like automotive and aerospace structures.
Strategic Opportunities
- Hydrogen Infrastructure:The build-out of hydrogen production and transport systems requires specialized stainless steels resistant to hydrogen embrittlement, opening a high-value niche.
- Advanced Medical Applications:Demand for biocompatible, high-purity stainless steels for minimally invasive surgical instruments and implants represents a high-margin growth avenue.
- Digital Sales Channels:Direct-to-fabricator sales platforms for specialized grades can bypass traditional distribution, capturing higher margins from small and medium-sized enterprises.
Industry Challenges
- Capital-Intensive Modernization:Upgrading mills to comply with emissions rules from regulators like the US EPA and to install low-carbon production technology demands significant capital.
- Complex Input Management:Operationally balancing recycled scrap with virgin alloys to meet both sustainability targets and strict compositional requirements is a persistent challenge.
- Certification Fragmentation:The need to certify products against multiple, non-harmonized standards from bodies like ISO, ASTM, and China's SAMR complicates global logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Market |
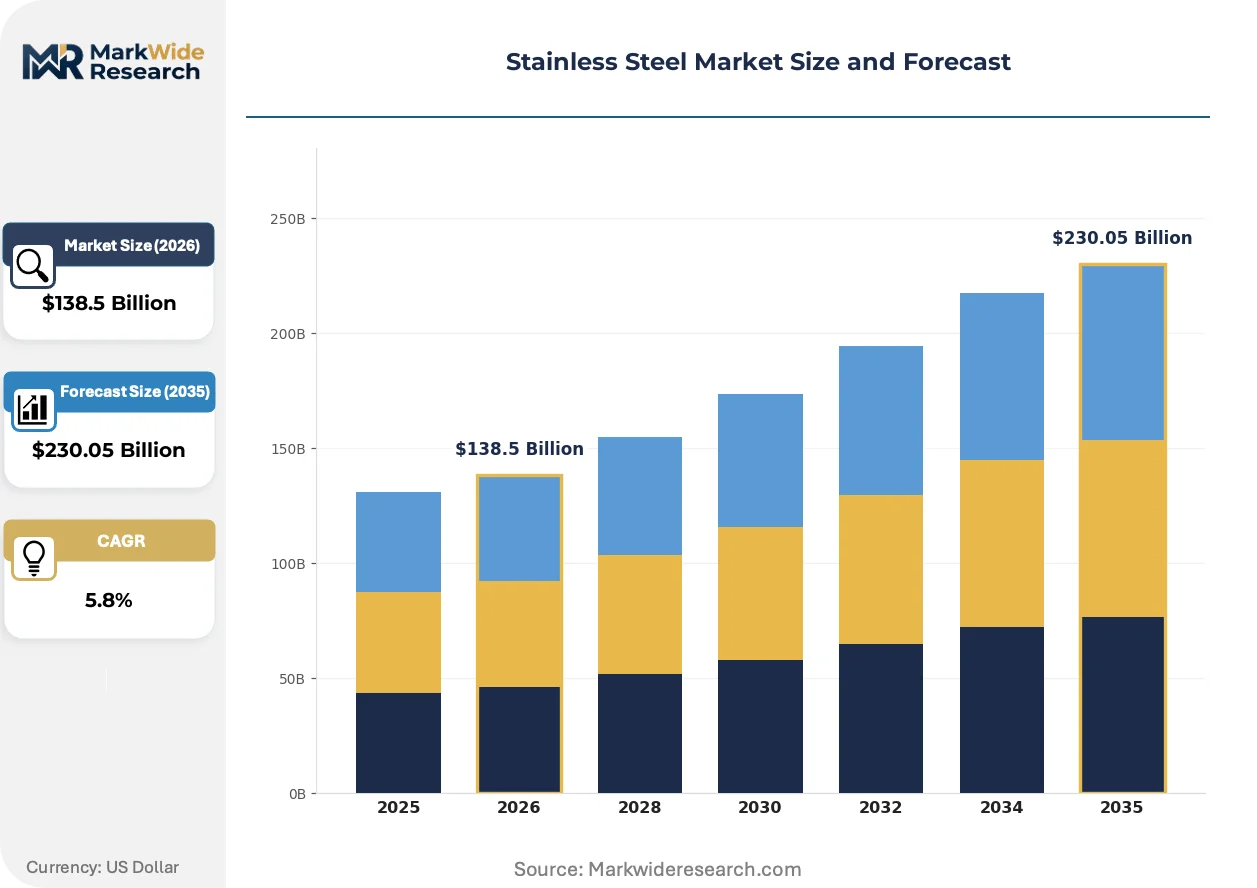
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $230.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Austenitic, Ferritic, Martensitic, Duplex, Precipitation Hardening, Others Form: Coils, Sheets, Plates, Bars, Tubes, Wire Application: Construction, Chemical Processing, Food Processing, Aerospace, Oilfield Equipment, Consumer Goods End User: Manufacturers, Fabricators, OEMs, Contractors, Distributors, Wholesalers |
| Companies Covered | Outokumpu, Jindal Stainless, Tsingshan Holding Group, Aperam, Nippon Steel Stainless Steel, China Baowu Stainless Platform, Acerinox Group, YUSCO, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Market Strategic Shifts & Innovations
Material development is increasingly focused on specialized alloys that deliver performance in extreme environments. This push for specialization occurs alongside a systemic shift in how carbon intensity is measured and penalized across global supply chains, altering production economics.
Advanced nitrogen-alloyed stainless steels provide superior strength and corrosion resistance versus conventional grades. The aerospace and chemical processing sectors adopt these materials for components operating under high stress and in corrosive media. The market for high-performance alloys is migrating from a reliance on more expensive superalloys to these specialized stainless steels for demanding applications.
The European Union's Carbon Border Adjustment Mechanism (CBAM) introduces a tariff on the embedded carbon of imported steel. This regulation directly incentivizes low-carbon production methods, such as using electric arc furnaces and maximizing scrap content. Non-EU producers must now document and reduce their product carbon footprint to maintain price competitiveness in the European market.
A shift towards life-cycle cost analysis influences material specification in large-scale infrastructure projects. This procurement behavior disrupts the dominance of commodity grades by prioritizing long-term durability over minimal upfront cost. The trend is most visible in coastal infrastructure and chemical plant construction in North America and Europe, where corrosion is a primary concern.
Stainless Steel Market Segmentation
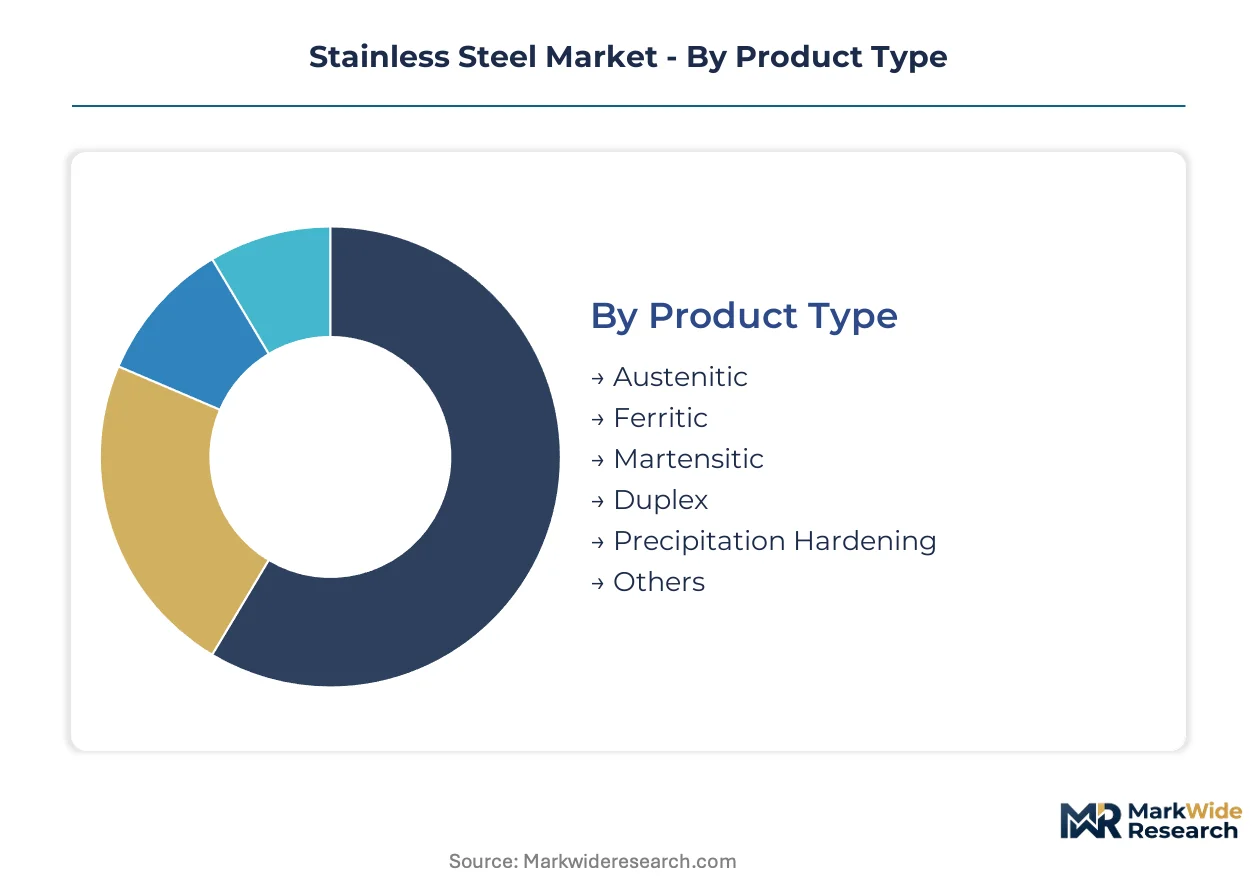
The stainless steel market's segmentation provides a granular view of material characteristics, processing forms, and end-use applications. Understanding these distinctions helps producers align their product portfolios with specific demand patterns and regulatory requirements across different industries. Each segment reflects unique performance needs and economic value propositions.
Product Type:
The product type dimension exhibits a mature core alongside emerging high-performance variants. Producers navigate a diverse landscape to meet varying end-user specifications.
- Austenitic:These iron-chromium-nickel alloys feature excellent formability, weldability, and corrosion resistance, making them highly versatile. Demand from construction and chemical processing applications, particularly in India, drives significant volume.
- Duplex:Offering superior strength and corrosion resistance due to their mixed microstructure, duplex grades are crucial for demanding environments. Infrastructure projects in coastal regions, like those in North America, increasingly specify these alloys for enhanced durability.
- Ferritic:Containing chromium but no nickel, ferritic grades offer good corrosion resistance and are often used in automotive exhaust systems.
- Martensitic:These grades are hardenable by heat treatment, making them suitable for applications requiring high strength and wear resistance, such as surgical instruments.
- Precipitation Hardening:These alloys achieve high strength through heat treatment and are valued in aerospace components for their strength-to-weight ratio.
- Others:This category includes specialized alloys designed for niche applications with unique performance requirements.
Austenitic stainless steel retains volume leadership; Duplex grades hold the steepest expansion curve.
Form:
Supply concentration in primary forms dictates the efficiency of downstream processing across the value chain.
- Coils:Produced via hot or cold rolling, coils serve as the primary input for numerous manufacturing processes, enabling efficient large-scale fabrication. Automotive and appliance manufacturers in China consume substantial volumes for stamping and forming.
- Sheets:These flat products are widely used in construction, consumer goods, and industrial equipment due to their versatility and ease of fabrication. European construction projects utilize sheets for facade cladding and roofing.
- Plates:Thicker than sheets, plates are specified for heavy-duty structural applications and pressure vessels in chemical processing plants.
- Bars:Available in various cross-sections, bars are essential for machining parts, fasteners, and structural components in industrial machinery.
- Tubes:Seamless and welded tubes are critical for fluid transport in chemical processing, oil and gas, and medical applications.
- Wire:Used in mesh, springs, and welding electrodes, wire forms cater to specialized applications requiring flexibility or intricate shapes.
The value addition for downstream fabricators is highest in specialized forms like tubes, while coils represent foundational volume.
Application:
End-use demand patterns reveal where specific performance characteristics are most valued, influencing material specification.
- Construction:This sector demands corrosion-resistant and durable materials for long-lasting infrastructure, including bridges, buildings, and coastal structures. Sustainable infrastructure initiatives in India drive significant demand for standard and duplex grades.
- Chemical Processing:Requires highly corrosion-resistant alloys for tanks, pipes, and reactors that handle aggressive chemicals and extreme temperatures. Specialized nitrogen-alloyed stainless steels are increasingly adopted in European chemical plants.
- Food Processing:Stainless steel ensures hygiene and prevents contamination in equipment such as tanks, pipes, and preparation surfaces.
- Aerospace:High-strength, lightweight, and corrosion-resistant alloys are critical for aircraft components operating under extreme conditions.
- Oilfield Equipment:Demands robust materials resistant to corrosion and high pressure for drilling, extraction, and transport infrastructure.
- Consumer Goods:Stainless steel is valued for its aesthetics, durability, and hygiene in appliances, kitchenware, and decorative items.
Construction applications command the largest volume, while aerospace and medical applications provide higher margin differentiation.
End User:
Customer procurement behavior shapes distribution channels and service requirements across the industry.
- Manufacturers:These entities directly purchase stainless steel as raw material for producing finished goods, requiring consistent quality and large volumes. Automotive manufacturers in Germany are major consumers of specific grades.
- Fabricators:These businesses process raw stainless steel into semi-finished or finished components, often requiring specialized grades and technical support. Small and medium-sized fabricators in the US increasingly use digital sales channels.
- OEMs:Original Equipment Manufacturers integrate stainless steel components into their final products, focusing on performance and supply chain reliability.
- Contractors:Primarily in construction, contractors specify and procure stainless steel for structural elements, cladding, and fittings.
- Distributors:These intermediaries manage inventory and supply a wide range of stainless steel products to smaller end-users.
- Wholesalers:Operating on larger scales, wholesalers supply bulk quantities to distributors, manufacturers, and large projects.
Manufacturers represent the largest direct purchasing segment, while fabricators are pivotal for specialized grade consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals are significantly influencing the global stainless steel market, promoting high-performance alloys for green technologies. Meanwhile, infrastructure development in India and North America drives substantial demand for standard and duplex grades. Regulations like the EU's REACH framework and US EPA emissions standards also shape production strategies across major manufacturing hubs.
China
Demand for stainless steel in China stems from renewable energy projects and electric vehicle component manufacturing. China's dual carbon goals and national GB standards mandate specific performance and compositional requirements for market access. Industrial clusters in the Yangtze River Delta, including Shanghai, are centers for advanced manufacturing and high-performance alloy consumption.
India
India's significant infrastructure projects provide a robust demand for corrosion-resistant stainless steel, particularly standard austenitic and duplex grades. Government initiatives supporting sustainable infrastructure development prioritize durable materials for long-term applications. Construction activities in Western India, including Gujarat, drive material consumption for urban and industrial development.
United States
The United States market sees demand from coastal infrastructure projects and the aerospace sector for specialized alloys. US EPA emissions standards for steel mills necessitate capital investments in modern production technologies. The Gulf Coast region, with its extensive oilfield equipment manufacturing and chemical processing plants, consumes substantial volumes of corrosion-resistant materials.
Germany
Germany's industrial machinery and automotive sectors require high-quality stainless steels, including specialty chemical processing applications. The EU's REACH regulation on chemical substances and the Carbon Border Adjustment Mechanism (CBAM) influence production methods and import costs. North Rhine-Westphalia remains a critical hub for heavy industry and advanced material fabrication within Europe.
Japan
Japan exhibits consistent demand for high-performance stainless steels in its advanced automotive, electronics, and specialized industrial equipment sectors. METI initiatives often support research and development into new materials and production efficiencies. The Kanto region, encompassing Tokyo, integrates significant R&D capabilities with high-tech manufacturing, driving innovation in alloy development.
Stainless Steel Market Key Industry Players
Commodity-grade producers and high-performance specialists split the market for stainless steel, creating distinct competitive dynamics. The market structure features large-scale integrated players alongside niche-focused manufacturers and specialized fabricators. Strategic archetypes include volume-driven mills, technology-focused innovators, and application-specific solution providers. Dominant competitive moves involve continuous capacity expansion and strategic portfolio diversification to meet evolving demand.
Within the scale-driven commodity segment, Tsingshan Holding Group exemplifies a player leveraging massive production capacity to influence pricing across global markets. Outokumpu represents a technology-focused specialist, differentiating through its emphasis on high-performance austenitic and duplex stainless steels. Aperam, a European-based company, occupies a position focused on specialty alloys for niche applications in specific geographic markets.
| Leading Market Players |
|---|
| Outokumpu |
| Jindal Stainless |
| Tsingshan Holding Group |
| Aperam |
| Nippon Steel Stainless Steel |
| China Baowu Stainless Platform |
| Acerinox Group |
| YUSCO |
| POSCO |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's commodity-grade stainless steel production influences global pricing and supplier behavior. This utilization signal dictates competitive strategies and investment decisions across the market.
Pricing Analysis
Geographic price spreads reflect varying production costs and regional demand dynamics. The market operates with a hybrid pricing model combining commodity spot rates for standard grades and contract-based long-term agreements for specialized alloys. Price differentiation stems from quality grade, specific certifications like ISO, and the volume scale of purchases. Pricing softness stems from intense competition in commodity segments, particularly from large-scale producers like Tsingshan. Manufacturers purchasing large volumes exhibit higher price sensitivity compared to fabricators requiring niche, high-performance materials.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, especially for large-volume transactions. Geographic supply concentration primarily centers on China, India, and Germany for varied product types. The industry relies heavily on virgin alloys like nickel and chromium, alongside recycled scrap. Input cost volatility presents a significant structural risk for producers globally. Distribution for specialized grades increasingly runs through direct-to-fabricator channels, while traditional distributors still manage commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stainless steel market is undergoing a buyer-power shift, driven by the fragmentation of specialized demand across niche applications. This reconfigures traditional distribution channels and procurement dynamics.
For Market Incumbents: Insulate core market share by investing in advanced nitrogen-alloyed stainless steels to counter substitution threats from high-strength aluminum. Consolidate production capacity in regions with favorable regulatory environments, such as those promoting low-carbon manufacturing. Invest in certifications against multiple global standards to ease market access and reduce compliance burdens. Control specialized distribution channels to maintain direct relationships with high-margin fabricators.
For New Entrants and Emerging Players: Establish a beachhead in high-value niche segments like hydrogen infrastructure and advanced medical applications. Target underpenetrated small and medium-sized enterprises requiring specialized, biocompatible stainless steels. Leverage digital sales channels to offer tailored product specifications and technical support, bypassing established large-scale distributors. Focus on specific performance requirements where existing commodity grades fall short.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across low-carbon production technologies and specialized alloy development. Seek acquisition targets that possess patented high-performance alloy formulations or advanced recycling capabilities. Long-term viability is anchored in meeting stringent sustainability mandates and demand for extreme-environment performance. The signal to watch is the effectiveness of the EU's CBAM in altering global production economics for imported steel.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Low-Carbon Production | Increases competitive advantage under regulations like the EU CBAM for European market access. |
| R&D in Hydrogen-Resistant Alloys | Addresses a high-value niche in emerging energy infrastructure development. |
| Digital Sales Platform Development | Captures higher margins from small and medium-sized fabricators globally. |
| Acquisition of Specialty Alloy Manufacturer | Expands product portfolio into high-performance segments with superior margins. |
| Investment in Advanced Recycling Technology | Aligns with global circular economy mandates and secures critical input materials. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research for validation. Primary insights were gathered from R&D directors, procurement leads in construction and automotive, specialized fabricators, and distribution channel partners. Secondary data sources included government reports from the EU and China, company financial filings, and industry association publications. A bottom-up and top-down triangulation approach ensured comprehensive market sizing and forecast accuracy.
Forecast inputs considered historical market trends, current demand drivers, and projected technological advancements across the analysis window. The analytical framework modeled segmentation dimensions including product type, form, application, end user, and regional demand patterns. Compound Annual Growth Rates were derived from an assessment of historical market expansion and future demand projections. Key industry-specific inputs included anticipated infrastructure spending in India and electric vehicle component demand in China.
Stress conditions across input cost volatility and geopolitical trade policies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning regulatory stability and technological adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminium Rolled Products Market
Metals
Lanthanum Market
Metals
North America and Europe Metal Powder Market
Metals
Galvanized Steel Coil Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Global Mercury Market
Metals
Bismuth Oxide Market
Metals
Iron Casting Market
Metals
Cerium Market
Metals
Tungsten Metal Powder Market
Metals
Rolled Steel Motor Market
Metals
Huntite Market
Metals
Global Duplex Stainless Steel Market
Metals
Titanium Mill Products Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Clutch Spring Wires Market