
 Global Wire Rods Market | 2026-2036
Global Wire Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wire Rods Market Outlook
Aluminum conductor composites is pivoting wire rod economics in overhead power transmission, pressuring traditional copper-clad and galvanized steel alternatives. ArcelorMittal S.A. leverages integrated mini-mill capacity across Europe and the Americas to control melt-to-rod conversion costs. NIPPON STEEL Corporation anchors premium alloy wire output for tire cord and bridge cable applications through proprietary controlled-cooling technology. HBIS Group dominates volume shipments of construction-grade coil into Southeast Asian fabrication hubs.
Wire rods are hot-rolled steel products drawn into continuous coils typically 5.5 to 42 millimeters in diameter, subsequently cold-drawn into wire for reinforcement mesh, fasteners, springs, or electrical conductors. Low carbon wire commands the largest volume share in residential and commercial construction rebar and mesh, though margin pools concentrate in alloy wire for automotive valve spring and tire bead applications where JIS and OEM certification requirements create supply scarcity. Medium carbon wire sustains above-average growth in pre-stressed concrete strand for bridge and wind-tower projects across coastal zones.
China's MEE enforces dual carbon goals that cap blast furnace output and elevate electric-arc furnace wire rod in domestic quotas, while India's BIS mandates IS 1786 certification for earthquake-zone reinforcement grades. REACH and RoHS frameworks in Europe restrict hexavalent chromium surface treatments, redirecting coating demand toward zinc-aluminum and epoxy alternatives. Stakeholders must monitor scrap-based EAF cost curves against iron ore pellet premiums, as this spread determines which producers can sustain alloy wire qualification without captive primary steelmaking.
Market Dynamics
The wire rods market pivots on scrap-based electric-arc furnace economics displacing blast furnace output as China's MEE enforces dual carbon caps and carbon border adjustments reshape trade flows into Europe.
Growth Catalysts
- India's PLI scheme for specialty steel:The production-linked incentive framework subsidizes high-grade alloy wire capacity expansion for tire cord and bridge cable applications, pulling investment toward BIS-certified earthquake-resistant grades.
- Overhead transmission aluminum conductor composites:Grid operators in coastal wind zones specify aluminum-clad steel core wire for span efficiency, compressing demand for traditional galvanized alternatives in 400kV-plus backbone networks.
- REACH-compliant coating substitution:ECHA restrictions on hexavalent chromium surface treatments redirect specification toward zinc-aluminum and epoxy alternatives, creating qualified-supplier scarcity that rewards early reformulation investments.
Market Restraints
- Iron ore pellet premium volatility:EAF wire rod producers without captive scrap networks face margin compression when seaborne pellet prices spike against shredded scrap indices, particularly affecting alloy qualification runs.
- Blast furnace concentration in Hebei Province:China's output caps concentrate supply risk in a single provincial cluster, where MEE enforcement variability creates quota uncertainty for construction-grade coil exports.
- Copper-clad aluminum substitution ceiling:Electrical conductivity requirements in IEC standards limit aluminum conductor penetration in sub-110kV distribution, capping addressable market expansion regardless of cost advantage.
Strategic Opportunities
- Vietnam's fabrication hub emergence:Japanese and South Korean fastener makers relocate drawing and cold-heading capacity to Haiphong and Da Nang, creating localized demand for medium-carbon coil with shortened logistics loops.
- EU Green Deal steel procurement mandates:CSRD-aligned embodied carbon disclosure requirements favor EAF-sourced wire in public infrastructure tenders, rewarding producers with verified Scope 3 data.
- Tire cord grade scarcity in Southeast Asia:OEM qualification timelines for JIS-certified bead wire exceed 18 months, creating first-mover advantage for integrated mills with proprietary controlled-cooling technology.
Industry Challenges
- Metallurgical technician shortage:EAF transition requires operators skilled in residual element control for alloy wire qualification, yet vocational pipelines in India and Vietnam lag capacity expansion timelines.
- OEM certification cycle compression:Automotive valve spring specifications now demand 24-month qualification windows versus historical 36-month cycles, straining R&D throughput without corresponding margin recovery.
- Legacy blast furnace asset stranding:Integrated mills face accelerated depreciation of basic oxygen furnace wire rod capacity under carbon pricing regimes, complicating portfolio transition financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wire Rods Market |
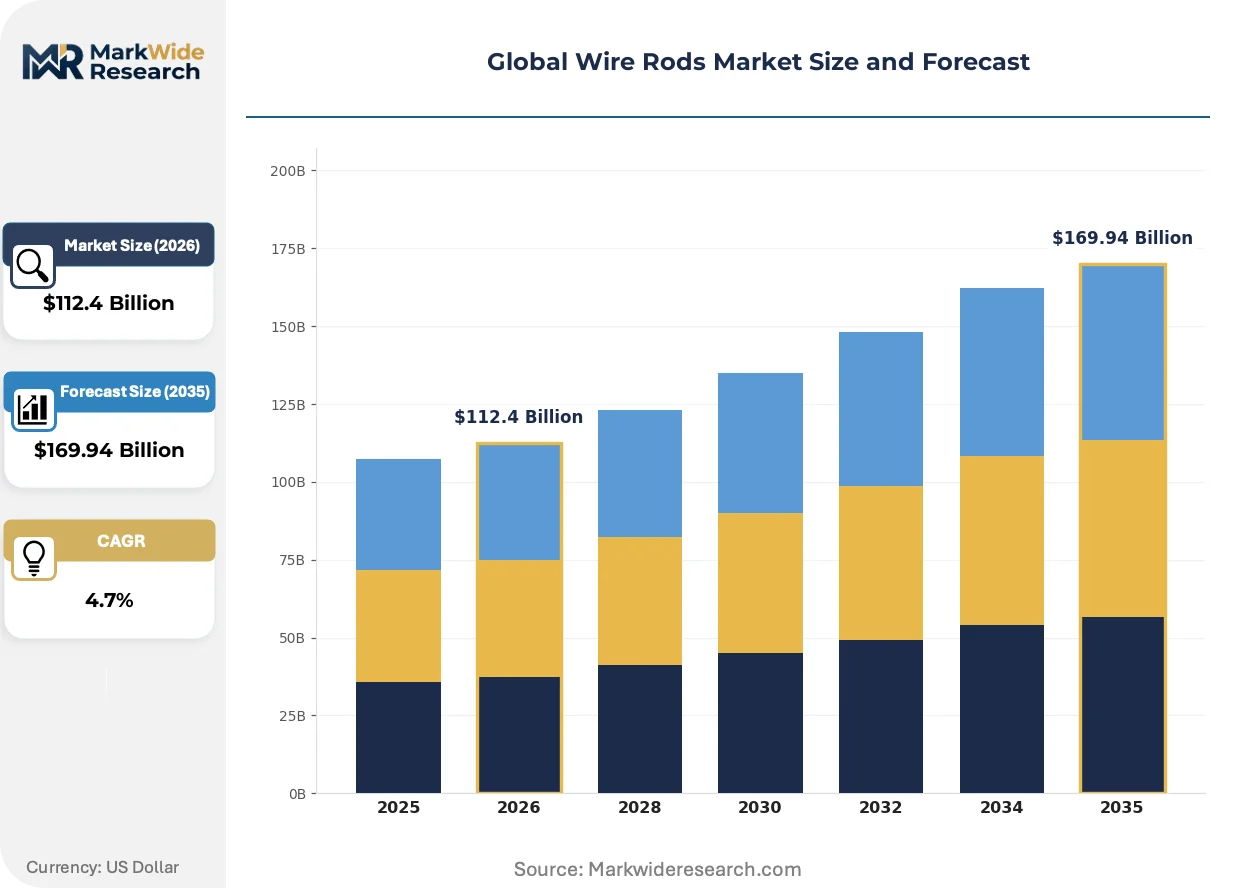
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Carbon Wire, Medium Carbon Wire, High Carbon Wire, Alloy Wire Application: Construction, Automotive, Manufacturing, Wire Products Form: Coiled, Straightened, Cut-Length, Others End User: OEMs, Fabricators, Retailers, Distributors |
| Companies Covered | ArcelorMittal S.A., EVRAZ plc, JSW, NIPPON STEEL Corporation, Kobe Steel Ltd., JFE Steel Corporation, HBIS Group, Shagang Group, Gruppo Pittini S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wire Rods Market Strategic Shifts
Process metallurgy and digital thread traceability are compressing specification variance while regulatory carbon accounting forces supply chain reconfiguration. Material substitution in conductivity applications and coating chemistry reformulation dominate technical agendas.
Controlled-cooling path technology is converging with in-line surface inspection systems to eliminate offline testing bottlenecks. Tire cord and bridge cable producers in Japan and Germany adopt this pairing to compress lead times from melt to qualified coil. The integration enables single-heat traceability that satisfies OEM audit requirements without batch segregation.
REACH Annex XVII restrictions on chromium trioxide in passivation layers took full effect across EU member states in 2024, forcing wire drawers to qualify zinc-aluminum and silane-based alternatives. Surface treatment suppliers in Italy and Poland report 14-month reformulation cycles for salt-spray performance parity. Construction-grade shipments into German automotive fasteners now require coating documentation meeting SCIP database submission rules.
Buyers in Indian infrastructure procurement now mandate mill test certificate digitization through blockchain-verified platforms, displacing paper-based third-party inspection. State highway authorities in Maharashtra and Tamil Nadu pilot this for rebar and pre-stressed strand tenders. The shift compresses payment cycles but excludes smaller mills lacking ERP integration, concentrating contract awards toward HBIS Group and integrated regional players with captive IT infrastructure.
Global Wire Rods Market Segmentation
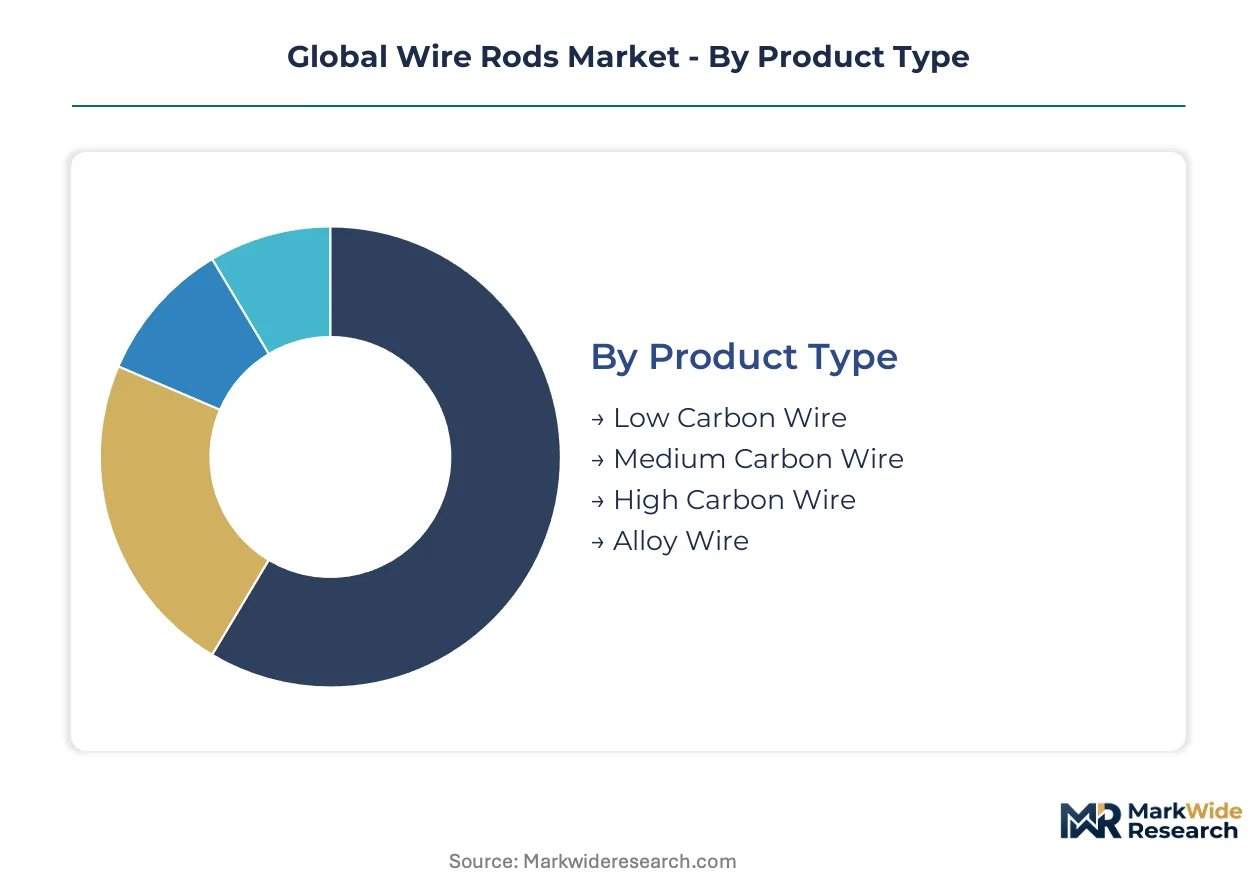
Wire rod specification variance drives fundamentally different procurement economics across construction, automotive, and electrical applications. Buyers segment demand by carbon content for mechanical performance, by coil geometry for downstream processing efficiency, and by certification tier for OEM qualification requirements.
Product Type:
Carbon content determines tensile strength ceiling, weldability trade-offs, and the cost premium commanded in alloy formulations.
- Low Carbon Wire:Contains 0.05-0.30% carbon content, delivering superior ductility and weldability for mesh welding and rebar tie wire. Residential and commercial construction across India absorbs the largest volumes, with Maharashtra state highway tenders specifying IS 1786-compliant grades for earthquake-zone reinforcement.
- Alloy Wire:Incorporates chromium, vanadium, or silicon for elevated fatigue resistance and temper stability. Automotive valve spring and tire bead wire specifications in Japan and Germany demand JIS-certified controlled-cooling microstructures that command 3-4x base carbon wire pricing.
- Medium Carbon Wire:Balances strength and formability for pre-stressed concrete strand in bridge and wind-tower applications.
- High Carbon Wire:Delivers maximum tensile strength for spring wire and rope applications requiring abrasion resistance.
Volume sits with low carbon grades for construction mesh; growth tilts toward alloy wire for automotive electrification and tire lightweighting.
Application:
End-use performance requirements create divergent specification rigor, from basic tensile testing for construction mesh to 24-month OEM qualification cycles for automotive safety components.
- Construction:Reinforcement mesh, rebar tie wire, and pre-stressed strand dominate tonnage offtake. India's national highway and railway electrification programs absorb record volumes of medium and high carbon grades, with BIS mandating digitized mill test certificates for state tenders.
- Automotive:Valve spring, tire cord, and suspension wire demand vacuum-degassed steel with inclusion control below 15 micrometers. OEM qualification timelines now compress to 24 months versus historical 36-month cycles, straining R&D throughput at Japanese and German tier suppliers.
- Manufacturing:Cold-heading quality for fasteners and bearings requires spheroidized annealing compatibility.
- Wire Products:General-purpose wire drawing for fencing, nails, and staples serves fragmented regional fabricators.
Construction commands absolute tonnage; automotive captures margin concentration through specification scarcity.
Form:
Downstream processing equipment and logistics economics determine coil versus straightened preferences across fabrication hubs.
- Coiled:Standard 5.5-42mm diameter hot-rolled coils enable continuous drawing operations at high-volume wire mills. Vietnam's emerging fabrication hubs in Haiphong and Da Nang favor coiled delivery for relocated Japanese and South Korean fastener capacity.
- Straightened:Cold-straightened and stress-relieved rod serves automated cold-heading machines requiring precise feed alignment.
- Cut-Length:Pre-cut segments eliminate shearing operations at construction sites for rebar coupling and mesh prefabrication.
- Others:Peeled, ground, or polished rod serves specialty bearing and aerospace applications.
Coiled form dominates mill shipments; cut-length gains share in modular construction prefabrication.
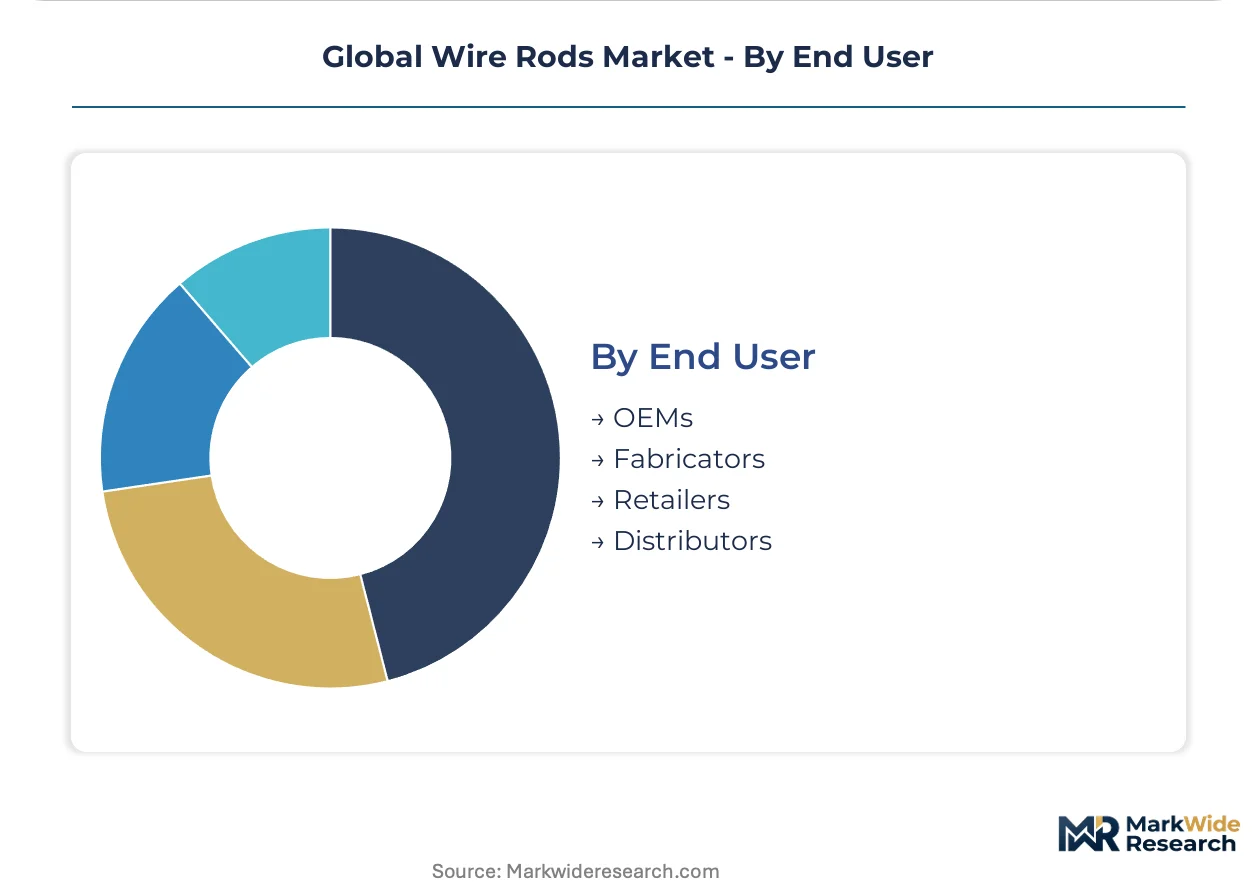
End User:
Procurement sophistication spans from spot-market distributors to integrated OEMs with captive metallurgical audit teams.
- OEMs:Automotive and tire manufacturers enforce residual element limits, inclusion ratings, and heat-to-heat traceability through blockchain-verified platforms. ArcelorMittal and NIPPON STEEL anchor premium supply through proprietary controlled-cooling technology.
- Fabricators:Wire drawers and fastener makers balance specification compliance against scrap-based EAF cost curves, with Vietnamese and Indonesian operators expanding medium-carbon capacity.
- Distributors:Stocking intermediaries serve fragmented construction and manufacturing accounts with standard grades.
- Retailers:Small-lot sales of cut-length and straightened rod for maintenance and repair operations.
OEMs concentrate value capture; fabricators drive volume elasticity through EAF sourcing flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor and coastal economic zones concentrate wire rod demand around fabrication clusters. China's Hebei Province output caps redirect export flows. Vietnam's Haiphong and Da Nang zones attract cold-heading capacity relocation from Northeast Asia.
China
Hebei Province blast furnace concentration supplies construction-grade coil for Southeast Asian fabrication hubs. MEE dual carbon enforcement caps provincial output quotas and elevates electric-arc furnace wire rod in domestic allocation. Tianjin and Tangshan mills face margin pressure from iron ore pellet premium volatility against scrap-based competitors.
India
National highway expansion and railway electrification programs absorb record medium and high carbon volumes across Maharashtra and Tamil Nadu state tenders. BIS mandates IS 1786 certification for earthquake-zone reinforcement grades with digitized mill test certificates. Gujarat and Karnataka fabrication clusters draw coil shipments for fastener and mesh production.
Japan
Automotive valve spring and tire cord specifications demand JIS-certified controlled-cooling microstructures from Kansai and Chubu region mills. METI industrial standards enforce residual element limits below 15 micrometers for vacuum-degassed steel. Nagoya-area producers compress OEM qualification cycles to 24 months through integrated metallurgical audit systems.
Germany
REACH Annex XVII chromium trioxide restrictions force wire drawers to qualify zinc-aluminum coating alternatives for automotive fastener shipments. ECHA compliance documentation now requires SCIP database submission for construction-grade deliveries. North Rhine-Westphalia and Bavarian mills face CSRD-aligned embodied carbon disclosure mandates in public infrastructure tenders.
Vietnam
Japanese and South Korean fastener makers relocate drawing and cold-heading capacity to Haiphong and Da Nang special economic zones. Localized medium-carbon coil demand shortens logistics loops from Chinese and Indian mill sources. Provincial industrial zones offer tax incentives for qualified wire rod warehousing and surface treatment operations.
Global Wire Rods Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated steel mills commanding premium alloy grades while regional fabricators compete on EAF cost curves. The market structures around three tiers: global integrated producers with captive primary steelmaking, scrap-based mini-mill specialists, and emerging Southeast Asian fabricators. Consolidation pressures concentrate among Hebei Province blast furnace operators facing carbon quota enforcement. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as REACH compliance redirects procurement specifications.
Within the integrated mill tier, ArcelorMittal S.A. and NIPPON STEEL Corporation exemplify producers with proprietary metallurgical control systems, while HBIS Group occupies a position representing volume-scale construction-grade supply into Asian fabrication hubs. These three entities anchor distinct competitive vectors: European and Americas mini-mill integration, Japanese premium alloy certification, and Chinese export volume concentration respectively.
| Leading Market Players |
|---|
| ArcelorMittal S.A. |
| EVRAZ plc |
| JSW |
| NIPPON STEEL Corporation |
| Kobe Steel Ltd. |
| JFE Steel Corporation |
| HBIS Group |
| Shagang Group |
| Gruppo Pittini S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Iron ore pellet premium indices cascade through wire rod supply chains, compressing margins at Tianjin and Tangshan blast furnace mills while elevating scrap-based electric-arc furnace cost advantages into pricing tiers across Asian export markets.
Pricing Analysis
Short lead-time premiums separate qualified coil pricing from spot construction-grade transactions, with JIS-certified tire cord wire commanding substantial uplifts against standard mesh grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and geographic delivery cost. Price differentiation hinges on BIS earthquake-zone compliance and OEM qualification status. Margins are tightening at Hebei Province blast furnace operators due to MEE carbon quota enforcement. Distributors serving fragmented fabricators exhibit highest price sensitivity; automotive OEMs with captive audit teams show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for specialty alloy grades, redirecting procurement toward Gujarat and Karnataka fabrication clusters. Supply concentrates in China, India, and Japan for distinct specification tiers. Raw material flows draw from seaborne iron ore pellets, shredded ferrous scrap, and alloying elements including chromium and vanadium. Single-source vulnerability concentrates at Hebei Province blast furnace clusters under MEE enforcement variability. Distribution runs through mill-direct contracts for OEMs and stocking intermediaries for construction accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire rod markets are becoming a vertical-integration race, with scrap network control and proprietary cooling technology emerging as the decisive upstream levers separating margin capture from commodity exposure.
For Market Incumbents: Cement controlled-cooling technology advantages through R&D partnerships with Japanese and German OEM audit teams, insulating premium alloy wire from EAF-based cost compression. Secure captive scrap supply agreements in Vietnam and Indonesia to defend position against emerging Southeast Asian fabricators expanding medium-carbon capacity.
For New Entrants and Emerging Players: Vietnamese fastener fabricators relocating from Northeast Asia represent the most penetrable buyer archetype, requiring localized medium-carbon coil with shortened logistics loops. Target BIS-certified earthquake-grade rebar tenders in Maharashtra and Tamil Nadu where digitized mill test certificate requirements exclude smaller mills lacking ERP integration. Pursue toll-processing arrangements with established surface treatment suppliers to bypass 14-month REACH-compliant coating reformulation cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor scrap-based EAF specialists with alloy qualification capabilities in India and Vietnam, where metallurgical technician shortages strain capacity expansion timelines. Long-term viability centers on producers with verified Scope 3 data for EU Green Deal steel procurement mandates. Watch carbon border adjustment implementation progress as the inflection signal determining blast furnace asset stranding velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Networks | Captive ferrous scrap supply insulates EAF operators from seaborne pellet premium volatility affecting Tianjin mills. |
| Proprietary Controlled-Cooling Investment | Single-heat traceability capability satisfies JIS-certified OEM audit requirements without batch segregation penalties. |
| REACH-Compliant Coating Reformulation | Zinc-aluminum qualification ahead of ECHA enforcement captures qualified-supplier scarcity premiums in German automotive fasteners. |
| Blockchain-Verified Certificate Digitization | ERP-integrated mill test platforms secure contract awards from Maharashtra state highway authorities piloting paperless inspection. |
| Relocation to Vietnamese Fabrication Hubs | Haiphong and Da Nang special economic zones offer tax incentives for cold-heading capacity serving Japanese fastener demand. |
Study Parameters
Document review covered trade customs databases, BIS certification registries, and ECHA restriction timelines, complemented by interviews with EAF plant managers, automotive tier supplier procurement leads, wire drawer technical directors, and surface treatment R&D specialists. Secondary validation drew from SEC filings of integrated steel producers, MEE carbon policy circulars, and OECD steel trade flow data. Bottom-up coil shipment analysis triangulated against top-down construction and automotive demand modeling.
Segmented volume and value estimates emerged from carbon content tiers, application rigor levels, and regional production hub configurations across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating infrastructure program timelines and OEM electrification content shifts. Forecast inputs included scrap-to-pellet cost spreads, MEE quota enforcement probability, and JIS certification queue lengths.
Revisions become necessary when carbon border adjustment implementation accelerates, MEE enforcement variability resolves, or OEM qualification cycles compress beyond current 24-month baselines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Platinum Market
Metals
Ferrite Market
Metals
Copper Smelting Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Aluminium Collars Market
Metals
Aluminum Welding Wires Market
Metals
Metal Alloys Market
Metals
Copper Foil Market
Metals
Gold Smelting Market
Metals
Galvanizing Market
Metals
Europe Aluminium Wire Rod Market
Metals
Transition Metals Market
Metals
Aluminum Tubes Market
Metals
Huntite Market
Metals
Aluminum Ingots Market
Metals
Galvanized Steel Market