
 Silver Powder and Flakes Market | 2026-2036
Silver Powder and Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Powder and Flakes Market Outlook
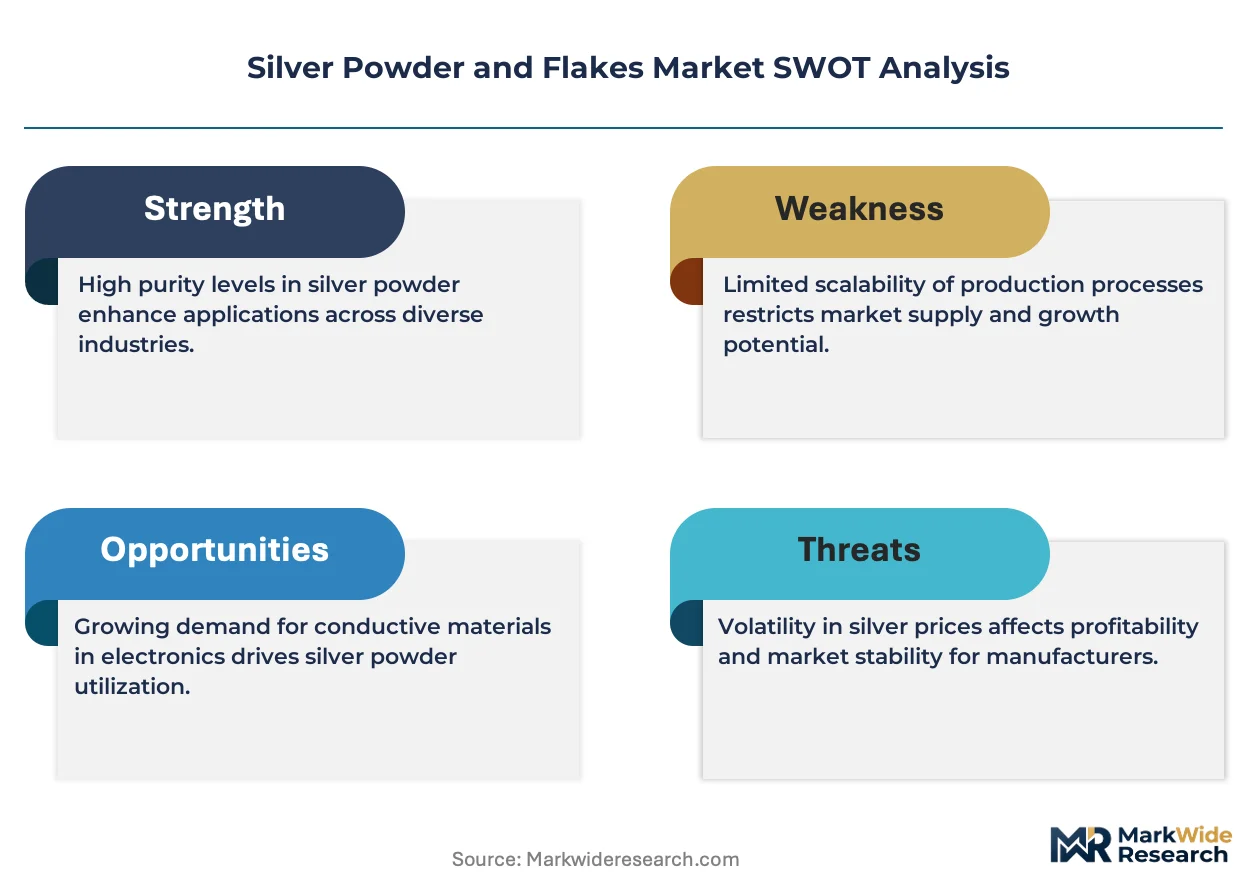
ISO 14001 environmental management certification is bifurcating the supplier base into qualified and non-qualified tiers for European automotive and electronics buyers. DOWA Hightech leverages its integrated smelting-to-powder operations to sustain cost discipline across high-purity grades. Johnson Matthey anchors its position through precious metal refining expertise that extends into customized flake morphologies for conductive ink formulators.
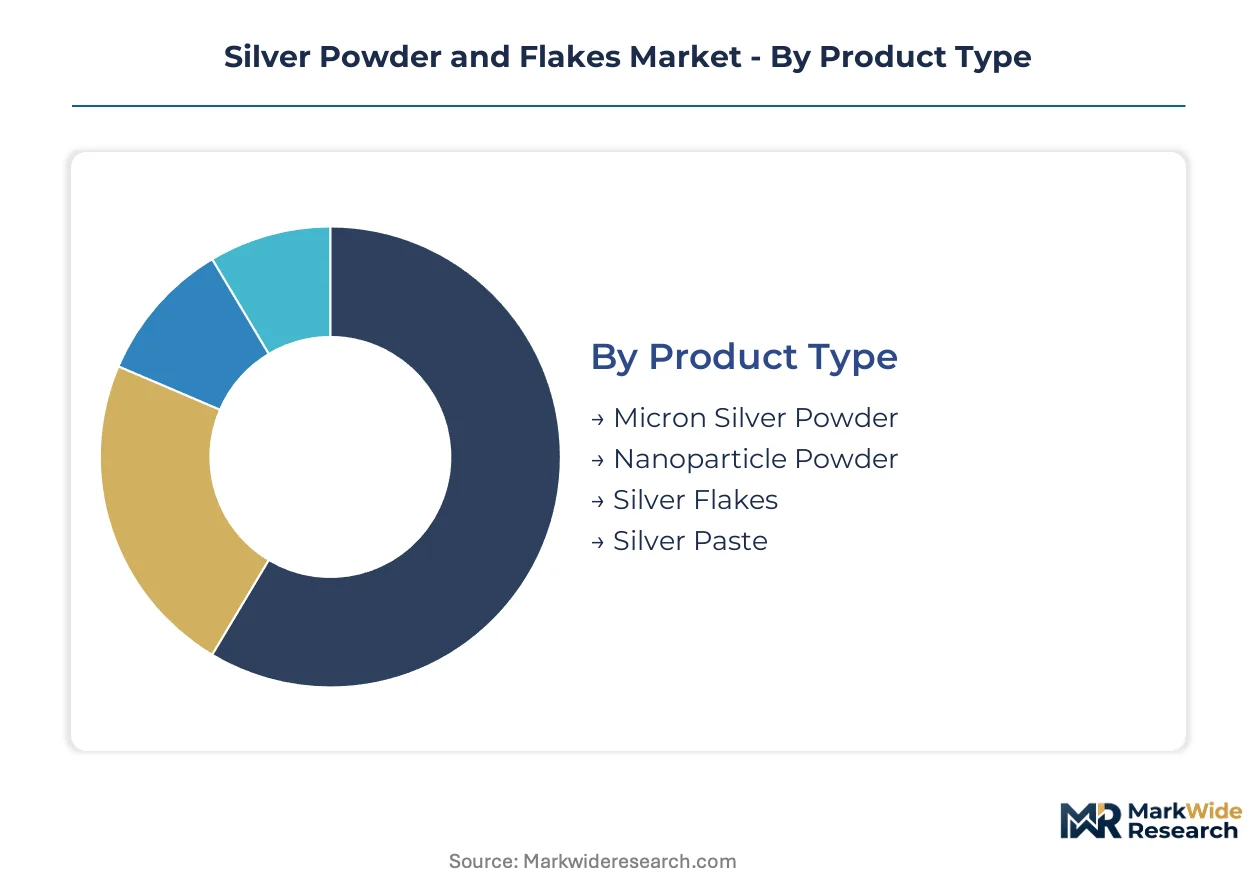
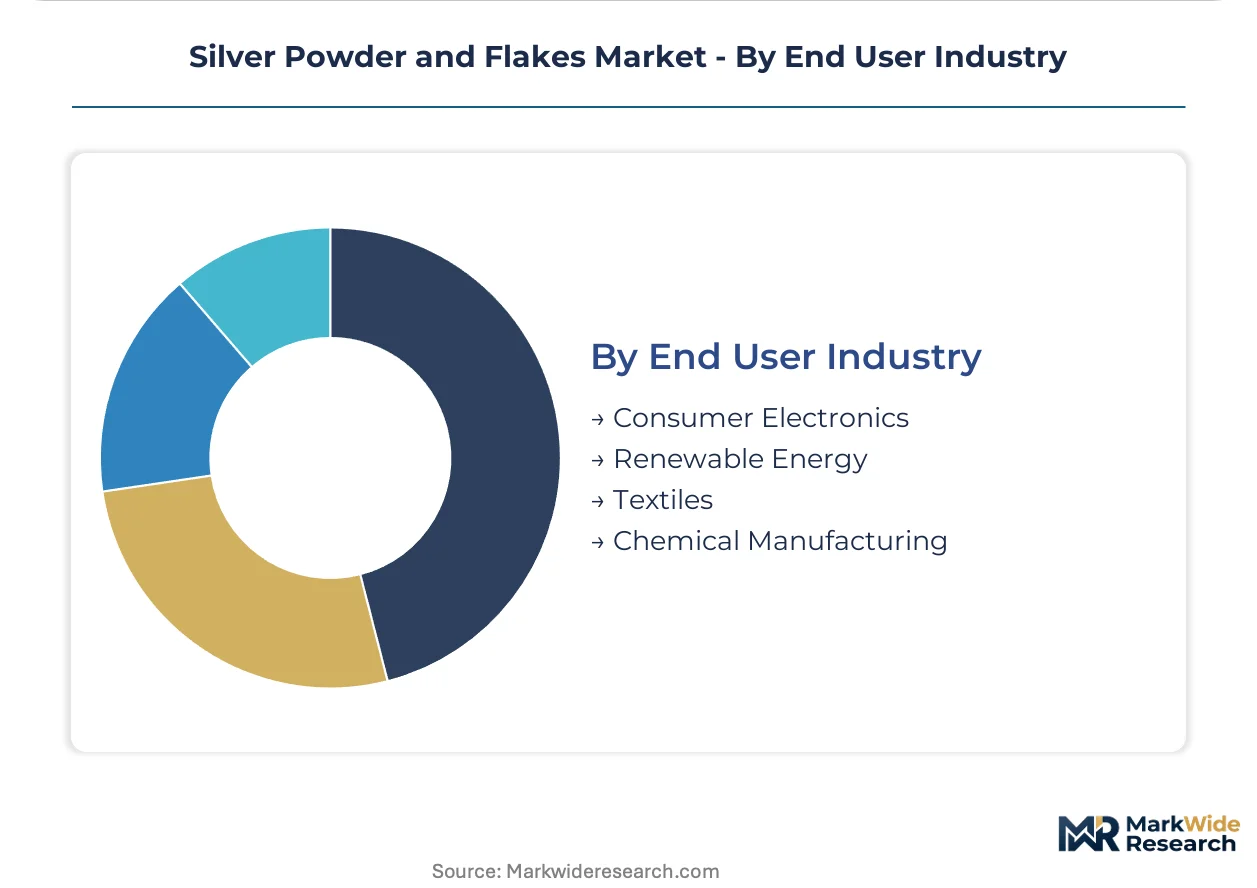
Silver powder and flakes comprise refined metallic silver processed into particulate or lamellar forms, typically achieving purity levels of 99.9% or higher through electrolytic or chemical reduction methods, and serve primarily as conductive fillers in printable electronic circuits and metallization layers. Silver paste dominates value capture within the product type dimension because photovoltaic cell manufacturers consume paste in volume for front-side grid printing, while nanoparticle powder represents the fastest-expanding structural pocket as inkjet and aerosol jet printing migrate toward finer feature resolution. Within end user industry segmentation, renewable energy commands the largest demand block due to solar wafer expansion, whereas consumer electronics sustains premium pricing for ultra-fine flake grades used in flexible circuit substrates.
EPA hazardous waste rules and OSHA permissible exposure limits govern silver powder handling and effluent control at U.S. production facilities, while REACH registration requirements in Europe constrain market access for non-compliant Asian exporters. China's GB standards for electronic-grade silver materials, administered by SAMR, shape domestic quality benchmarks that increasingly influence global procurement specifications. Buyers must monitor regulatory divergence between jurisdictions to avoid supply chain disqualification as material traceability mandates tighten across multiple geographies.
Market Dynamics
Photovoltaic cell manufacturers are consolidating silver paste procurement around certified suppliers as crystalline silicon wafer output scales across East Asian production clusters, tightening qualification windows and fragmenting the supplier base into ISO 14001-compliant and non-compliant tiers.
Growth Catalysts
- Solar cell metallization expansion:Crystalline silicon module producers in China and Southeast Asia are scaling front-side grid printing operations, pulling volume demand for high-purity silver paste through qualified supply channels.
- REACH compliance mandates:European battery sustainability rules are tightening material traceability requirements for imported silver derivatives, advantaging registered suppliers with documented supply chain audit trails.
- Nanoparticle inkjet migration:Printed electronics formulators are adopting finer silver powders for aerosol jet and inkjet deposition, enabling sub-20-micron feature resolution in flexible circuit substrates.
Market Restraints
- Primary silver price volatility:London Bullion Market Association spot pricing fluctuations transmit directly into powder and flake production costs, compressing margin predictability for conductive ink compounders.
- Smelter concentration in East Asia:Electrolytic refining capacity clusters in Chinese and Korean integrated operations, creating geographic single-source vulnerability for European and North American downstream processors.
- Alternative conductive fillers:Copper-polymer composites and carbon nanotube inks are displacing silver in cost-sensitive printed antenna and RFID tag applications where conductivity requirements permit substitution.
Strategic Opportunities
- Indian solar manufacturing buildout:Production-linked incentive schemes for domestic photovoltaic module assembly are creating qualified silver paste demand from new cell metallization lines in Gujarat and Tamil Nadu.
- EU battery passport traceability:Digital product passport requirements under the EU Green Deal are mandating granular material origin documentation, opening premium pricing tiers for blockchain-traceable silver supply.
- Copper-silver hybrid sintering:Low-temperature bonding processes combining copper core particles with silver shells are converging thermal management and electrical conductivity functions in power semiconductor packaging.
Industry Challenges
- Electrolytic refining technician scarcity:Skilled operators capable of maintaining 99.99% purity electrolysis cells are concentrating at legacy Japanese and German smelters, constraining new capacity ramp rates.
- ISO 14001 certification timeline:Environmental management system audit and implementation cycles extend 18-24 months, delaying supplier qualification for automotive electronics procurement frameworks.
- Legacy paste formulation integration:Solar cell manufacturers running established screen-printing lines face yield risk when qualifying next-generation nanoparticle silver pastes with different rheological profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Powder and Flakes Market |
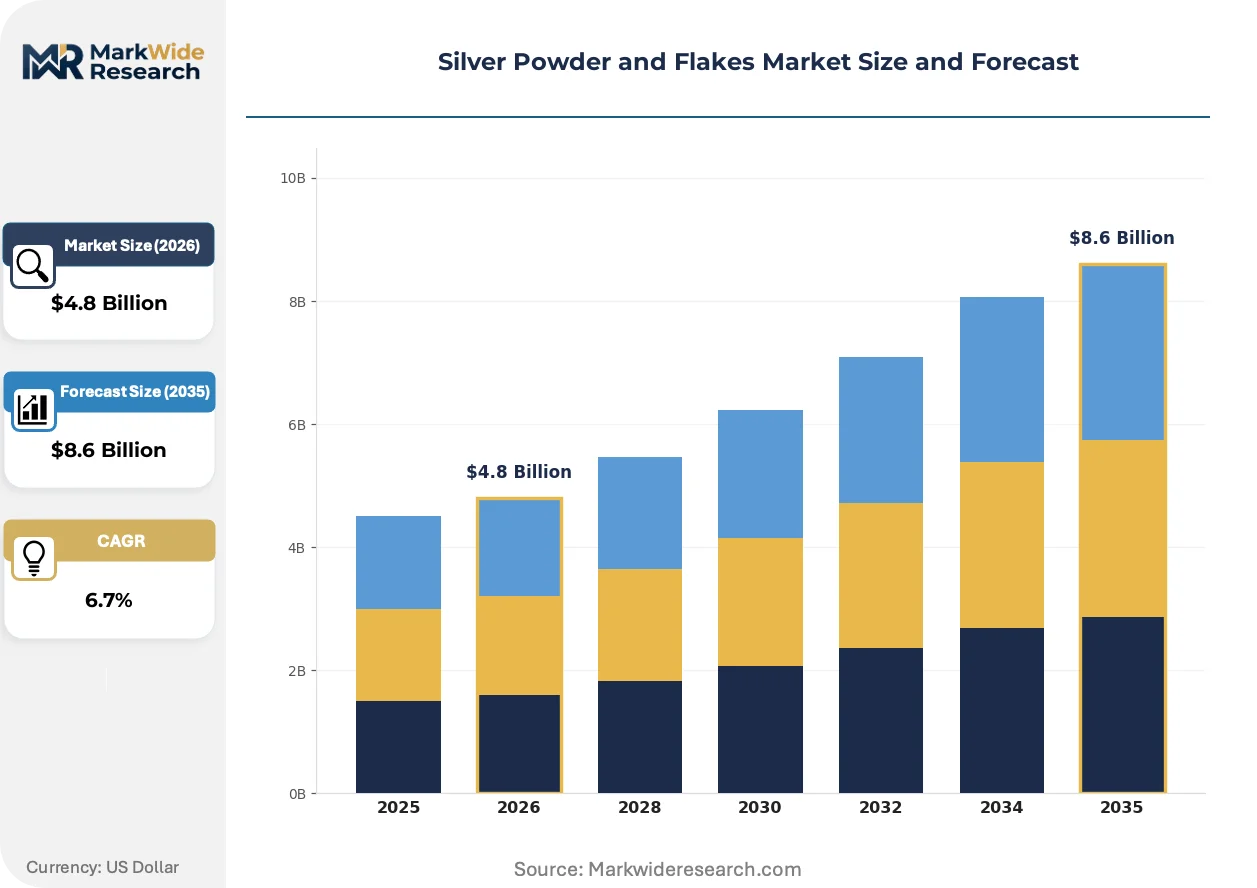
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micron Silver Powder, Nanoparticle Powder, Silver Flakes, Silver Paste Form: Powder, Flakes, Agglomerates, Dispersions Application: Conductive Inks, Electronics Manufacturing, Photovoltaics, Antimicrobial Coatings End User Industry: Consumer Electronics, Renewable Energy, Textiles, Chemical Manufacturing |
| Companies Covered | Ferro Corporation, DOWA Hightech, Johnson Matthey, E. I. du Pont de Nemours and Company, Technic, Ames Goldsmith, Metalor Technologies, Tongling Nonferrous Metals Group Holding, Mitsui Mining & Smelting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Powder and Flakes Market Strategic Shifts
Silver powder processing is bifurcating between commodity-scale solar paste production and precision-grade nanoparticle synthesis, with regulatory traceability requirements and deposition technology advances driving parallel innovation tracks.
Ultrafine silver nanoparticle dispersions are decomposing traditional flake-dominated conductive ink formulations. Printed electronics manufacturers in South Korea and Taiwan are adopting these dispersions for roll-to-roll flexible circuit production. The technology is decomposing incumbent supply relationships as inkjet deposition equipment vendors specify particle size distributions incompatible with conventional milling processes.
EU battery sustainability regulations are extending material passport requirements to silver-containing electrical contacts in energy storage systems. The European Chemicals Agency is finalizing substance database integration rules that will mandate batch-level origin documentation from 2027. Battery pack assemblers in Poland and Hungary are pre-qualifying silver suppliers with existing REACH registration portfolios to avoid procurement disruption.
Direct procurement contracts between photovoltaic cell manufacturers and integrated smelter-powder processors are compressing traditional distributor channels. Long-term offtake agreements now span five-to-seven year horizons with fixed purity specifications and indexed pricing clauses. This pattern is most pronounced in China, where Tongling Nonferrous Metals and regional solar paste compounders have established captive supply relationships bypassing spot market intermediaries.
Silver Powder and Flakes Market Segmentation
Silver powder and flakes demand fragments across distinct technical specifications where purity thresholds, particle morphology, and rheological properties determine supplier qualification. Procurement patterns diverge sharply between volume-driven solar paste buyers and precision-focused electronics formulators seeking nanoscale control.
Product Type:
Margins concentrate in nanoparticle grades where synthesis complexity creates supply scarcity, while paste formulations capture value through metallization chemistry integration.
- Micron Silver Powder:Particulate silver with controlled 1-10 micron diameter distributions, produced through chemical reduction or atomization processes. Crystalline silicon solar cell manufacturers in China consume this grade in volume for rear-side busbar printing, though screen-printing line compatibility limits rapid formulation shifts.
- Nanoparticle Powder:Sub-100 nanometer silver dispersions enabling sub-20-micron feature resolution in inkjet and aerosol jet deposition systems. South Korean and Taiwanese printed electronics specialists are migrating toward these grades for roll-to-roll flexible circuit production, decomposing traditional flake-dominated supply relationships.
- Silver Flakes:Lamellar particles with high aspect ratios providing planar conductivity in thick-film applications.
- Silver Paste:Pre-formulated metallization compounds combining silver solids with organic vehicles and glass frits for photovoltaic front-side grid printing.
The dominant share belongs to silver paste, while nanoparticle powder is closing the gap fastest.
Form:
Processing economics favor powder and flake feedstocks for compounders, whereas end-users increasingly specify ready-to-print dispersions to bypass in-house formulation investment.
- Powder:Dry particulate silver requiring solvent dispersion and rheological adjustment before deposition. Japanese and German smelters concentrate electrolytic refining capacity for 99.99% purity grades, constraining new capacity ramp rates due to skilled technician scarcity.
- Flakes:Mechanically milled lamellar particles with thickness below 1 micron and diameter exceeding 10 microns. Consumer electronics manufacturers in Japan specify ultra-fine flake grades for flexible circuit substrates where surface roughness tolerance is tightest.
- Agglomerates:Clustered primary particles designed for controlled sintering behavior in low-temperature bonding applications.
- Dispersions:Pre-stabilized silver suspensions in organic or aqueous vehicles, eliminating formulation steps for inkjet deposition equipment operators.
Powder retains the largest volume position, though dispersions are expanding most quickly as equipment vendors specify particle size distributions incompatible with conventional milling.
Application:
Value capture skews toward photovoltaics where paste consumption scales with wafer throughput, while conductive inks sustain premium pricing through formulation complexity.
- Conductive Inks:Printable silver formulations for RFID antennas, membrane switches, and flexible circuit traces. Copper-polymer composites and carbon nanotube alternatives are displacing silver in cost-sensitive printed antenna applications where conductivity requirements permit substitution.
- Electronics Manufacturing:Die-attach adhesives, EMI shielding coatings, and connector plating feedstocks. REACH registration requirements constrain market access for non-compliant Asian exporters serving European automotive electronics procurement frameworks.
- Photovoltaics:Front-side and rear-side metallization for crystalline silicon cells, representing the largest demand block as module output scales across East Asian production clusters.
- Antimicrobial Coatings:Silver ion release formulations for medical devices and textile treatments, subject to evolving EPA hazardous waste rules and OSHA permissible exposure limits at U.S. production facilities.
Photovoltaics commands the dominant application share, while conductive inks are gaining share fastest through printed electronics diversification.
End User Industry:
Renewable energy procurement concentrates volume around qualified suppliers with ISO 14001 certification, whereas consumer electronics sustains premium tiers through ultra-fine specification requirements.
- Consumer Electronics:Flexible circuit substrates, touch sensor electrodes, and semiconductor packaging applications. Samsung and Apple supply chain auditors specify documented environmental management systems, bifurcating the supplier base into qualified and non-qualified tiers.
- Renewable Energy:Photovoltaic cell metallization and energy storage electrical contacts. India's production-linked incentive schemes for domestic module assembly are creating qualified silver paste demand from new cell lines in Gujarat and Tamil Nadu.
- Textiles:Antimicrobial fiber treatments and conductive fabric coatings for wearable electronics.
- Chemical Manufacturing:Catalyst precursors and specialty reagent applications requiring high-purity silver derivatives.
Renewable energy holds the dominant industry position, while consumer electronics is climbing the fastest through flexible substrate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in silver powder logistics, moving metallization materials from Anhui smelters to Jiangsu solar cell fabs with minimal transshipment friction.
China
Tongling Nonferrous Metals and regional smelters feed crystalline silicon module output scaling across Jiangsu and Zhejiang provinces. SAMR-administered GB standards for electronic-grade silver materials shape domestic quality benchmarks that increasingly influence global procurement specifications. Hefei and Suzhou industrial clusters host integrated powder-to-paste operations that bypass traditional distributor channels through direct long-term offtake agreements.
Japan
Mitsui Mining & Smelting concentrates electrolytic refining capacity for 99.99% purity grades, constraining new capacity ramp rates due to skilled technician scarcity at legacy facilities. METI industrial policy prioritizes domestic semiconductor packaging supply chain security, tightening qualification windows for imported silver derivatives. Kansai region smelters maintain captive relationships with Osaka-area conductive ink formulators serving flexible circuit substrate demand.
Germany
REACH registration requirements constrain market access for non-compliant Asian exporters serving automotive electronics procurement frameworks. ECHA substance database integration rules mandate batch-level origin documentation from 2027, advantaging registered suppliers with documented supply chain audit trails. Saxony and Bavaria host precision flake processing operations supplying EMI shielding coatings for European EV battery pack assemblers.
India
Production-linked incentive schemes for domestic photovoltaic module assembly create qualified silver paste demand from new cell metallization lines in Gujarat and Tamil Nadu. BIS quality certification timelines extend supplier qualification cycles, delaying market entry for uncertified powder traders. Mundra Port infrastructure supports direct import of high-purity feedstocks for Ahmedabad-area solar paste compounders.
South Korea
Printed electronics specialists migrate toward nanoparticle dispersions for roll-to-roll flexible circuit production, decomposing traditional flake-dominated supply relationships. MFDS industrial chemical registration requirements govern silver powder handling standards at Busan-Ulsan processing facilities. Seoul Capital Area equipment vendors specify particle size distributions incompatible with conventional milling processes, pulling demand toward sub-100 nanometer grades.
Silver Powder and Flakes Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with ISO 14001 environmental management credentials bifurcating the supplier base into qualified and non-qualified tiers for European automotive and electronics buyers. Three archetypes dominate: integrated smelter-powder processors controlling electrolytic refining through captive operations, precious metal refiners extending expertise into customized flake morphologies, and regional compounders serving photovoltaic paste demand through formulation chemistry integration. Competitive moves concentrate on backward integration into smelting capacity and five-to-seven year direct procurement contracts that compress traditional distributor channels.
Within the integrated processor tier, DOWA Hightech and Tongling Nonferrous Metals Group Holding exemplify smelting-to-powder operations that sustain cost discipline across high-purity grades. Johnson Matthey occupies a position among precious metal specialists leveraging refining expertise into customized material specifications for conductive ink formulators.
| Leading Market Players |
|---|
| Ferro Corporation |
| DOWA Hightech |
| Johnson Matthey |
| E. I. du Pont de Nemours and Company |
| Technic |
| Ames Goldsmith |
| Metalor Technologies |
| Tongling Nonferrous Metals Group Holding |
| Mitsui Mining & Smelting |
| Others |
Value Chain & Pricing Dynamics
Electrolytic refining capacity utilization above 85% at Chinese and Korean integrated smelters compresses marginal cost floors for 99.9% purity grades, while simultaneously concentrating pricing power among operators with captive powder-to-paste operations. This scale dynamic creates asymmetric pressure on European and North American compounders lacking backward integration into primary silver refining.
Pricing Analysis
Volume-discount tiering separates photovoltaic paste procurement into three distinct pricing bands: premium nanoparticle dispersions for inkjet deposition equipment, standard micron-grade powders for screen-printing lines, and economy flake feedstocks for thick-film conductive inks. Solar cell manufacturers with five-to-seven year direct offtake agreements capture 15-20% cost advantages over spot market buyers, though REACH registration premiums add 8-12% to European automotive electronics procurement. Price erosion runs through economy flake tiers as copper-polymer composites displace silver in RFID antenna applications. Photovoltaic paste buyers exhibit highest price sensitivity due to silver's 10-15% share of module bill-of-materials, whereas medical device antimicrobial coating formulators tolerate premium pricing for documented batch traceability.
Supply Chain Analysis
China, Japan, and South Korea anchor global silver powder production through integrated smelter-to-powder operations at Tongling Nonferrous Metals, Mitsui Mining & Smelting, and DOWA Hightech facilities. Raw material flows draw from London Bullion Market Association-certified silver bullion, electrolytic cathode feedstocks, and recycled industrial scrap streams. Single-source vulnerability concentrates in East Asian electrolytic refining capacity, where skilled technician scarcity constrains new entrant ramp rates. Distribution runs through direct long-term contracts between integrated processors and photovoltaic cell manufacturers, compressing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver powder and flakes demand sits in early-cycle expansion as photovoltaic cell metallization scales across India's production-linked incentive zones and EU battery passport traceability mandates create premium documentation tiers. Nanoparticle inkjet migration and copper-silver hybrid sintering technologies extend addressable applications beyond traditional thick-film electronics.
For Market Incumbents: Compound certification advantages by accelerating ISO 14001 audit completion for automotive electronics procurement frameworks before 18-24 month implementation cycles delay qualification. Secure captive smelting capacity through offtake agreements with legacy Japanese and German electrolytic refiners facing technician attrition, insulating against primary silver price volatility transmission. Prioritize nanoparticle dispersion R&D partnerships with Seoul Capital Area equipment vendors specifying sub-100 nanometer particle distributions. For New Entrants and Emerging Players: Lead with India's Gujarat and Tamil Nadu solar manufacturing buildout as the most penetrable geography, where BIS certification timelines delay incumbent market entry and production-linked incentive schemes accelerate qualified paste demand. Target copper-silver hybrid sintering applications in power semiconductor packaging as a white-space segment converging thermal management and electrical conductivity functions. Establish formulation chemistry partnerships with Ahmedabad-area solar paste compounders leveraging Mundra Port feedstock access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated smelter-powder processors with documented REACH registration portfolios and existing blockchain-traceable supply chain infrastructure. Long-term viability over the next decade hinges on regulatory divergence between EU battery passport requirements and evolving Asian material origin documentation standards. Monitor ECHA substance database integration rule implementation as the critical inflection signal for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Refining | Captive 99.99% purity capacity at Tongling Nonferrous Metals insulates margin from LBMA spot volatility transmission. |
| REACH Registration Portfolio Expansion | Documented supply chain audit trails secure automotive electronics procurement frameworks under ECHA mandates. |
| Nanoparticle Dispersion Synthesis Scale-Up | Sub-100 nanometer grades align with Seoul Capital Area equipment vendor specifications for roll-to-roll flexible circuits. |
| Direct Long-Term Offtake Agreements | Five-to-seven year contracts with crystalline silicon module producers compress traditional distributor channel economics. |
| Blockchain-Traceable Supply Chain Infrastructure | Granular material origin documentation captures EU battery passport premium pricing tiers from 2027. |
Study Parameters
A spread of perspectives from solar cell metallization engineers, conductive ink formulation chemists, precious metal procurement managers, and electrolytic refining technicians converged on the working assumptions driving demand segmentation. Primary fieldwork combined structured interviews with secondary validation against customs records, SAMR GB standard filings, ECHA substance database entries, and SEC 10-K disclosures from listed precious metal processors. Bottom-up volume modeling triangulated against top-down macroeconomic sensitivity analysis across the projection horizon.
Segmentation dimensions modeled include product type hierarchy, purity grade tiering, particle morphology specifications, end-use industry concentration, and regional regulatory framework clusters. CAGRs were derived through exponential smoothing of historical shipment data and elasticity-adjusted forward projections. Forecast inputs incorporated photovoltaic wafer capacity expansion schedules, inkjet deposition equipment vendor roadmaps, and evolving EU battery sustainability rule implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained crystalline silicon module output growth, stable LBMA silver pricing corridors, or uninterrupted REACH registration compliance pathways would require recalibration. Recalibration cycles align with material shifts in solar cell metallization technology adoption, regulatory database integration milestones, and primary silver supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper Clad Aluminum Wire Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Platinum Compounds Market
Metals
Motor Lamination Material Market
Metals
Niobium Market
Metals
High Purity Tungsten Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Nickel Powder Plating Market
Metals
Global Chromium Market
Metals
Aluminum Welding Market
Metals
Nickel Oxide Target Market
Metals
Ferrosilicon Market
Metals
7075 T6 Aluminum Market
Metals
High Purity Boron Market
Metals
Global Vanadium Market
Metals
Aluminum Ingots Market