
 Stainless Steel 400 Series Market | 2026-2036
Stainless Steel 400 Series Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel 400 Series Market Intelligence
The rising specification of ferritic grades in automotive exhaust systems, displacing traditional materials, is repositioning the value chain toward heat and corrosion-resistant alloys. Outokumpu leverages its specialized portfolio in high-performance grades for demanding applications. thyssenkrupp competes on its integrated production capabilities and extensive distribution network, particularly within Europe's automotive supply chain. POSCO sustains its market position through large-scale production and technological innovation in steel manufacturing.
Stainless Steel 400 Series comprises a family of ferritic and martensitic chromium alloys, notable for their magnetic properties and minimal nickel content. These grades are engineered for applications requiring good corrosion resistance and strength, particularly in elevated temperature environments. Within product types, coils dominate volume, feeding automated production lines for automotive parts. The automotive end-user segment drives technical innovation, while demand from the general manufacturing sector focuses on plate and bar forms.
Material specifications are shaped by multiple regulatory frameworks. The EU's REACH regulation governs the use of certain alloying elements, while vehicle emissions standards from the US EPA and China's MEE mandate more durable exhaust system components. These rules effectively push designers toward higher-performance ferritic steels. Stakeholders must now navigate the evolving cost-performance trade-off as environmental compliance standards become more stringent across industrial and automotive applications.
Market Dynamics
The central structural force shaping the Stainless Steel 400 Series market is the global regulatory push for stricter emissions control. Mandates from bodies like the EU, US EPA, and China's MEE are compelling material substitution in automotive exhaust systems, favoring heat-resistant ferritic grades.
Growth Catalysts
- Automotive Sector Requirements:Demand for high-performance exhaust systems that can withstand elevated temperatures and corrosive gases drives the specification of ferritic grades, particularly in hot-end components like manifolds and catalytic converters.
- Stringent Emissions Regulations:The EU Green Deal and US EPA standards mandate lower vehicle emissions over a longer lifetime, effectively requiring more durable materials and accelerating the displacement of traditional steels.
- Industrialization in China:China's vast manufacturing and industrial base, coupled with government support for advanced materials, creates concentrated demand for 400 series steels across automotive, appliance, and construction sectors.
Market Restraints
- Input Cost Volatility:The price of chromium, a primary alloying element in 400 series stainless steel, is subject to significant market fluctuations, which can impact production costs and final product pricing stability.
- Substitution from Other Materials:In less demanding or non-structural applications, these steels face competition from advanced aluminum alloys and higher-nickel austenitic stainless grades that may offer different performance or cost advantages.
- Technical Limitations:The inherent magnetic properties of ferritic and martensitic steels preclude their use in specialized applications where non-magnetic materials are essential, such as in certain medical devices or sensitive electronic equipment.
Strategic Opportunities
- Hydrogen Economy Components:The need for corrosion-resistant and durable materials in hydrogen fuel cells, storage tanks, and transport infrastructure presents a significant new application frontier for specialized 400 series grades.
- Building and Construction Codes:Tighter fire safety and structural integrity regulations in commercial and residential construction could create new demand for 400 series alloys in load-bearing elements and architectural cladding.
- Southeast Asian Market Expansion:Growing automotive production and industrial development in countries like Vietnam and Thailand offer underpenetrated markets for suppliers of specialized stainless steel products beyond the dominant Chinese market.
Industry Challenges
- Capital-Intensive Production:Manufacturing high-performance ferritic grades requires significant capital investment in specialized cold-rolling mills and annealing and pickling lines, creating high barriers to entry for new producers.
- Specialized Talent Scarcity:A shortage of metallurgists and process engineers with deep expertise in ferritic alloy development, production optimization, and application engineering can constrain innovation and quality control.
- Navigating Global Standards:Adhering to a complex and fragmented landscape of international standards, from the EU's REACH to China's GB standards, introduces significant compliance costs and logistical hurdles for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel 400 Series Market |
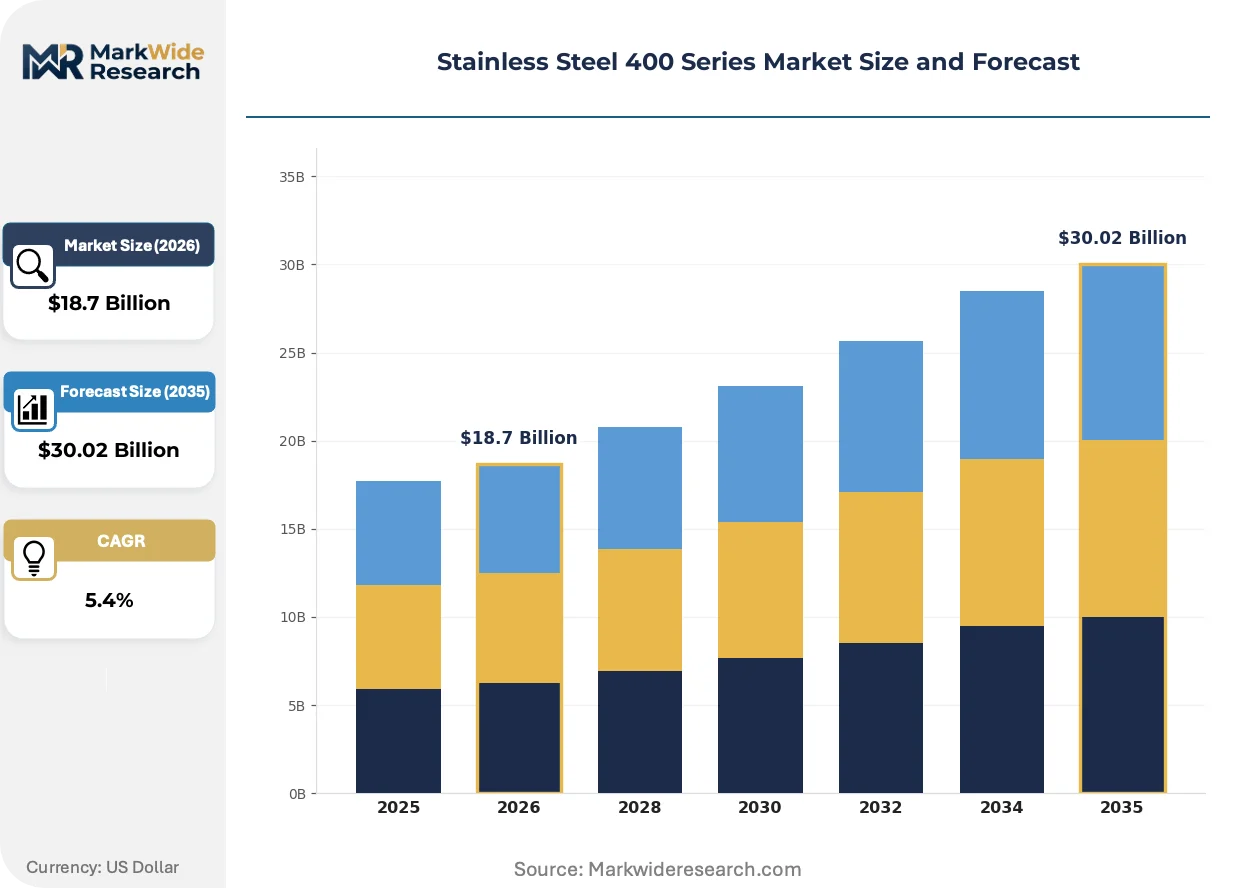
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Plate, Coil, Bar End User: Automotive, Aerospace, Construction, Manufacturing Form: Cold Rolled, Hot Rolled, Annealed, Pickled Application: Kitchenware, Automotive Parts, Industrial Equipment, Chemical Processing |
| Companies Covered | Jindal Stainless, Tsingshan, Outokumpu, thyssenkrupp, Aperam, POSCO, Baosteel, Yieh United Steel Corp, Acerinox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel 400 Series Market Strategic Shifts & Innovations
Environmental compliance is the primary engine of innovation, forcing a technical realignment in alloy design and manufacturing processes. The market's evolution is defined by the pursuit of materials that meet higher performance and durability thresholds mandated by new regulations.
Advanced high-chromium ferritic steels are engineered for superior oxidation and corrosion resistance at extreme temperatures. Automotive OEMs are the principal adopters, specifying these materials for hot-end exhaust components to meet durability targets. This advanced material science is converging with computational modeling to optimize system designs for both performance and regulatory compliance.
The European Union's Green Deal establishes demanding targets for vehicle pollutant reduction, including NOx and particulates. This policy directly compels the use of more durable materials in exhaust systems to ensure emission control systems function effectively throughout a vehicle's life. Consequently, the automotive exhaust segment is most affected, driving a rapid shift toward specialized 400 series alloys.
A significant change in buying behavior is the prioritization of lifecycle cost analysis over initial material price. This trend is moving purchasing away from transactional, commodity-based acquisitions toward strategic, long-term supply agreements for certified, high-performance alloys. The shift is most visible within the European automotive supply chain, where OEM warranty and durability mandates dictate material selection.
Stainless Steel 400 Series Market Segmentation
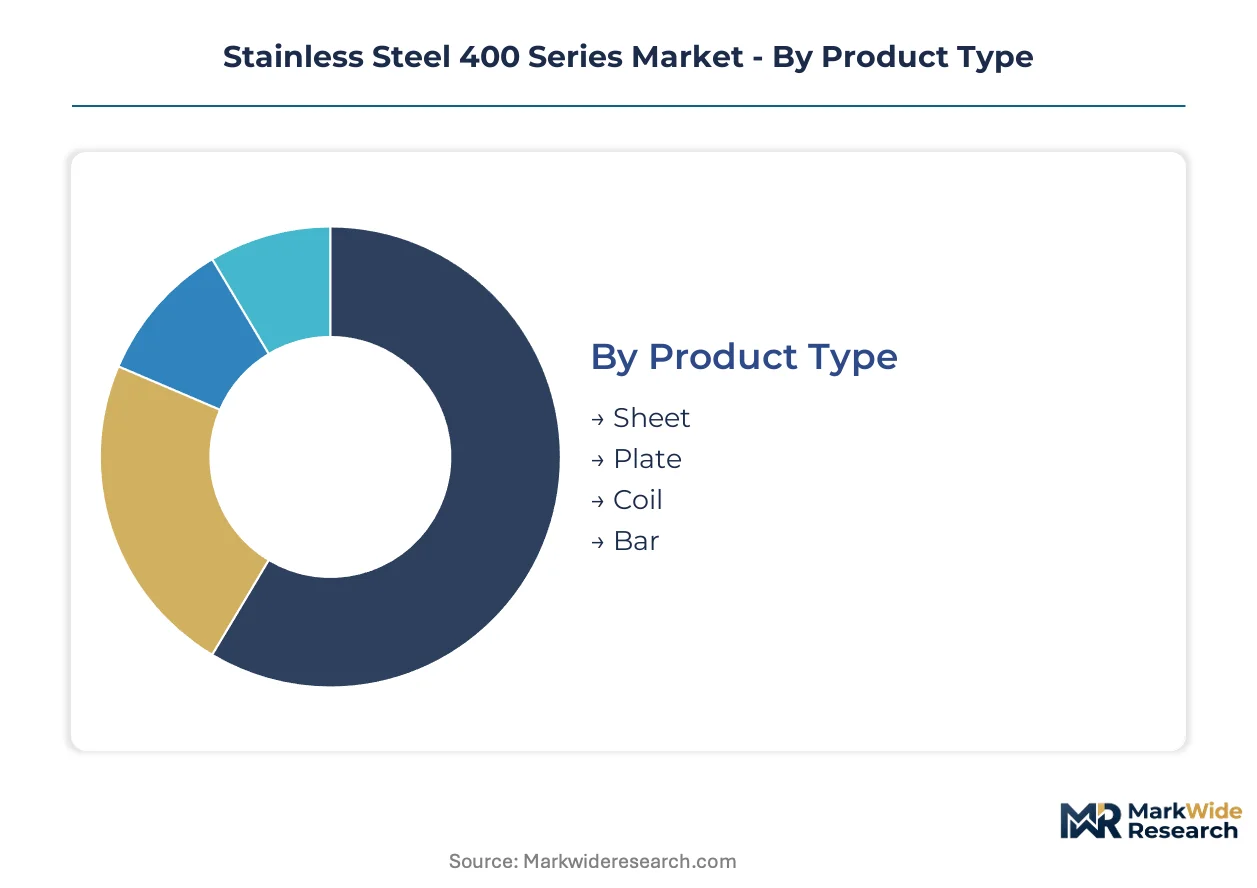
The Stainless Steel 400 Series market segmentation reveals distinct demand profiles and material specifications across various product forms, end-user industries, processing stages, and specific applications. Understanding these segments is crucial for manufacturers to align production capabilities with evolving market requirements and regulatory pressures. This granular view enables stakeholders to identify high-growth niches and optimize product development strategies for specialized ferritic and martensitic alloys.
Product Type:
The product type segmentation highlights material lifecycle dynamics, where existing infrastructure upgrades or component replacements often dictate specific form factor demand. Manufacturers frequently prioritize specific product types to meet the diverse technical requirements of downstream fabrication processes.
- Coil:These continuous rolls of stainless steel are extensively used in automated production lines, particularly within the automotive sector, for manufacturing high-volume exhaust components. Demand concentrates in China, driven by its large-scale vehicle manufacturing base and industrial production.
- Sheet:Flat, thin forms of 400 series stainless steel offer versatility for stamping, forming, and deep drawing operations across multiple industries, including appliances and construction. Growing demand for corrosion-resistant cladding and structural elements in commercial buildings drives its specification.
- Plate:Thicker flat forms provide enhanced structural integrity and are specified for heavy-duty industrial equipment and certain construction applications.
- Bar:Solid, elongated forms are utilized for machining into fasteners, shafts, and other components requiring high strength and precision.
Volume placements concentrate in Coil; the faster expansion belongs to Sheet.
End User:
End-user demand patterns reflect the diverse performance requirements for 400 series stainless steel across various industrial sectors. Each segment imposes unique material property demands and regulatory compliance mandates on steel suppliers.
- Automotive:This sector is the primary driver for 400 series stainless steel, particularly for exhaust systems, catalytic converters, and structural components requiring high heat and corrosion resistance. Stricter emissions regulations from the EU and US EPA mandate the use of durable ferritic grades.
- Manufacturing:The broad manufacturing sector uses 400 series steels for industrial machinery, equipment casings, and various components where strength and moderate corrosion resistance are essential. Demand from China's extensive industrial base underpins significant volume consumption.
- Aerospace:Specialized martensitic grades find use in non-critical structural components and fasteners where magnetic properties are acceptable, often balancing cost with performance.
- Construction:These steels are specified for architectural elements, structural components, and interior fittings requiring aesthetic appeal and corrosion resistance in specific building codes.
Automotive and Manufacturing end-users collectively drive the largest demand, while Aerospace applications require the most stringent material specifications.
Form:
The market's form segmentation reflects the primary processing stages that tailor 400 series steels for specific downstream fabrication needs. Each form offers distinct advantages in terms of surface finish, dimensional accuracy, and mechanical properties.
- Cold Rolled:This form undergoes processing at room temperature, resulting in a smooth surface finish, improved dimensional accuracy, and enhanced mechanical properties suitable for precision components. Automotive OEMs specify cold-rolled coils for intricate exhaust system parts.
- Hot Rolled:Processed at high temperatures, hot-rolled forms are characterized by their rougher surface and greater thickness, making them ideal for structural applications and heavy-duty industrial equipment. Demand from the general manufacturing sector utilizes these forms for bulk material.
- Annealed:This heat treatment process improves ductility and reduces hardness, making the material easier to form and machine for various applications.
- Pickled:A chemical treatment removes surface impurities and scale, preparing the steel for further processing or enhancing its corrosion resistance.
Hot Rolled and Cold Rolled forms constitute the bulk of production output, with Annealed and Pickled forms representing specialized finishing treatments.
Application:
Application-specific demand for 400 series stainless steel underscores its utility in environments requiring specific combinations of corrosion resistance and strength. Each application area presents unique design challenges and material selection criteria.
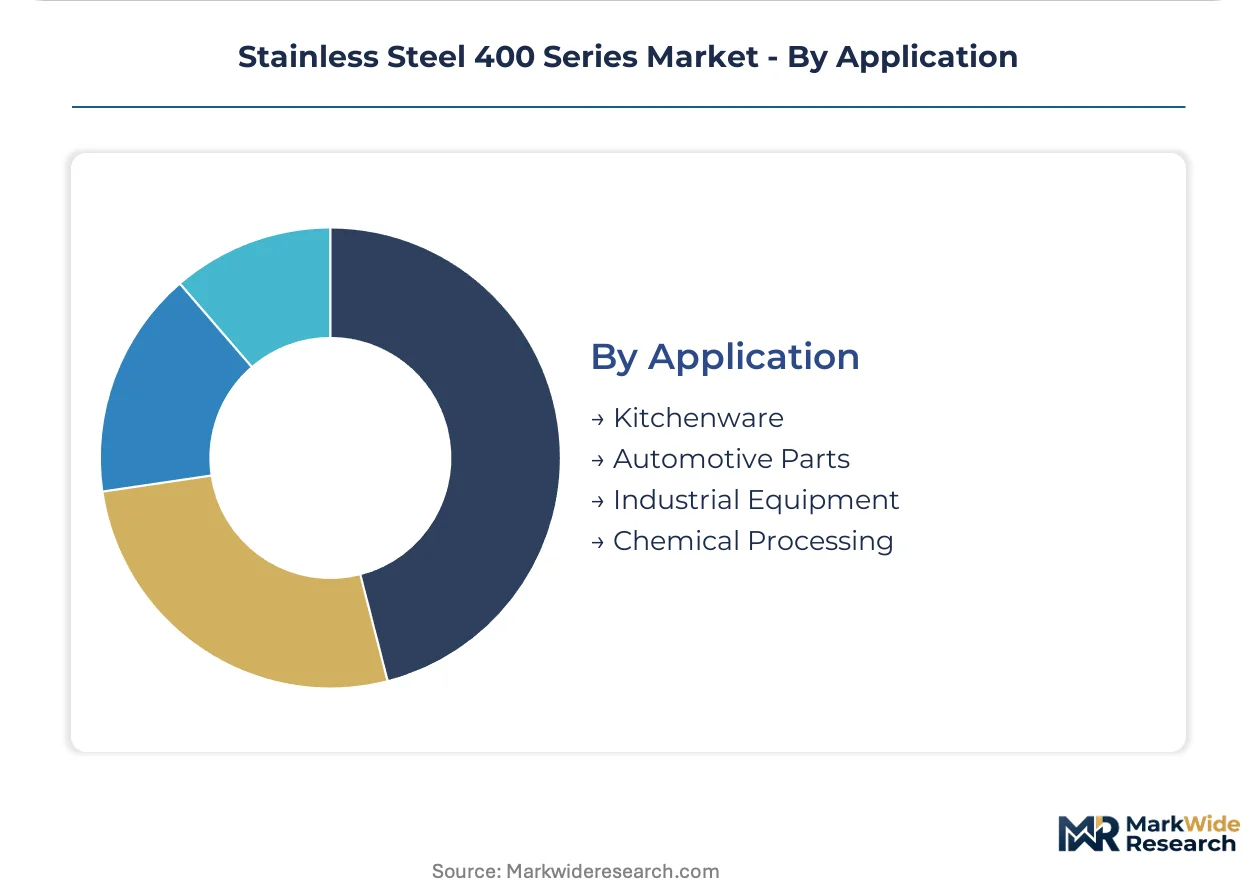
- Automotive Parts:This segment includes exhaust systems, manifolds, catalytic converter casings, and various under-the-hood components that must withstand high temperatures and corrosive gases. Stringent EU Green Deal vehicle standards accelerate material substitution towards these durable alloys.
- Industrial Equipment:These steels are used in machinery, processing equipment, and storage tanks where good corrosion resistance and mechanical strength are necessary for operational longevity. Demand concentrates in regions with extensive heavy industry, like China.
- Kitchenware:Ferritic grades offer a cost-effective solution for sinks, cooking utensils, and appliance components due to their magnetic properties and moderate corrosion resistance.
- Chemical Processing:While higher-nickel grades are often preferred, specific 400 series alloys find use in less aggressive chemical environments or for certain equipment components.
Automotive Parts and Industrial Equipment applications consume the largest volumes, driven by durability and performance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive Special Economic Zones (SEZs) and industrial parks underpin its dominant position in both production and consumption of Stainless Steel 400 Series. These areas attract major steel manufacturers and downstream industries, driving significant regional market activity. The global market exhibits concentrated demand, primarily fueled by automotive and manufacturing sectors.
China
Demand for 400 series steels in China is propelled by its vast automotive production and growing appliance sector. Government support for advanced materials through initiatives like "Made in China 2025" encourages domestic specification. The Yangtze River Delta region, with its numerous automotive and manufacturing hubs, drives concentrated consumption.
Germany
The German automotive industry's stringent requirements for high-performance exhaust systems fuel demand for ferritic grades. EU Green Deal regulations mandate reduced vehicle emissions, compelling material upgrades in vehicle components. The Ruhr Area remains a metallurgical and automotive engineering cluster, specializing in advanced material applications.
United States
Automotive exhaust system upgrades and general manufacturing needs contribute to US demand for 400 series stainless steel. US EPA emissions standards push vehicle manufacturers towards more durable and heat-resistant materials. The Great Lakes region, a traditional automotive and heavy industry belt, sees significant application in component fabrication.
India
India's expanding automotive sector and infrastructure development are increasing the specification of 400 series alloys. The Production Linked Incentive (PLI) scheme for auto components encourages domestic manufacturing and material innovation. The Chennai-Bengaluru industrial corridor is emerging as a hub for both automotive production and general engineering.
South Korea
High-tech manufacturing and a strong automotive industry in South Korea drive specific demand for advanced ferritic grades. Korean environmental regulations, mirroring global standards, require durable materials in various industrial applications. The Ulsan industrial cluster, home to major automotive and shipbuilding firms, shows concentrated material usage.
Stainless Steel 400 Series Market Key Industry Players
Top-tier vendors anchor the global Stainless Steel 400 Series market, while mid-tier specialists and regional fabricators address specific demands. The market structure is tiered, characterized by a mix of large integrated producers and niche players. Strategic archetypes include large-scale integrated mills focused on volume, specialized high-performance alloy producers targeting demanding applications, and regional distributors leveraging localized networks. Capacity expansion into advanced material production and strategic partnerships with automotive OEMs are dominant competitive moves among these players.
At the scale-driven end, Outokumpu and thyssenkrupp exemplify integrated production capabilities. Outokumpu leverages its specialized portfolio in high-performance grades for demanding applications, representing a focus on value-added products and technical expertise. thyssenkrupp competes on its extensive distribution network, particularly within Europe's automotive supply chain, showcasing a strong regional market presence and logistical strength. POSCO sustains its market position through large-scale production and technological innovation in steel manufacturing, anchoring the high-volume segment with continuous process improvements.
| Leading Market Players |
|---|
| Jindal Stainless |
| Tsingshan |
| Outokumpu |
| thyssenkrupp |
| Aperam |
| POSCO |
| Baosteel |
| Yieh United Steel Corp |
| Acerinox |
| Others |
Cost & Logistics Intelligence
Chromium price index fluctuations directly influence the cost of 400 series stainless steel, cascading into tiered pricing for end-users. This volatility affects both long-term contracts and spot market transactions, impacting profitability across the value chain.
Pricing Analysis
Short lead times command a premium for specialized 400 series ferritic grades, while standard coils often trade at commodity spot prices. The dominant pricing structure is contract-based long-term offtake, particularly for automotive OEMs. Price differentiation stems from certification level (e.g., specific automotive standards) and volume scale. Pricing softness stems from input cost volatility, especially for chromium. Automotive OEMs are least price-sensitive for performance-critical parts, while general manufacturing buyers are most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with chromium ore extraction, largely concentrated in South Africa and Kazakhstan, creating upstream supply risks. The supply chain for 400 series stainless steel concentrates production in China, South Korea, and Europe. Raw material dependencies include chromium, minimal nickel, and iron ore. Commodity price volatility represents a key structural risk. Distribution runs through a network of large integrated mills and specialized regional fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Stainless Steel 400 Series market is fundamentally a cost-of-compliance story, where the EU Green Deal's vehicle emission standards create a significant barrier-to-entry moat for specialized ferritic alloy producers. Meeting these regulations demands advanced material science and stringent quality control.
For Market Incumbents: Deploy targeted R&D into advanced high-chromium ferritic steels to maintain a technical lead against emerging material substitutes like advanced aluminum alloys. Establish long-term supply agreements with automotive OEMs to secure volume against the threat of new entrants. Invest in specialized cold-rolling mills to address the capital-intensive production barrier, ensuring consistent quality and scale.
For New Entrants and Emerging Players: Enter via specialized niche applications requiring specific martensitic grades, such as non-critical aerospace fasteners, to avoid direct competition with large integrated mills. Target underpenetrated Southeast Asian markets, leveraging growing automotive production in countries like Vietnam and Thailand. Focus on offering customized plate and bar forms for general manufacturing, emphasizing quick delivery and technical support to build market share.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate specialized production capabilities in high-performance ferritic alloys. Long-term viability (over a 5-10 year window) is strong for firms with robust intellectual property in alloy design and regulatory compliance. Acquisition targets should be mid-sized producers with established automotive OEM certifications and a skilled metallurgist workforce. A key signal to watch is the tightening of global emissions standards, indicating increased demand for advanced materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Ferritics | Ensures supply for growing automotive demand driven by stricter emissions regulations. |
| R&D in Hydrogen Economy Materials | Positions for future demand in corrosion-resistant components for fuel cells and storage. |
| Partnerships with Automotive OEMs | Secures long-term contracts and co-development opportunities for next-generation exhaust systems. |
| Geographic Expansion into Southeast Asia | Captures underpenetrated markets with rising industrialization and vehicle production. |
| Investment in Cold-Rolling Technology | Enhances precision manufacturing for intricate automotive components and high-value products. |
Research Approach
Customs/trade data, SEC 10-K filings, and industry association reports formed the secondary backbone for market sizing and trend identification. This was combined with primary interviews with metallurgists, automotive OEM procurement leads, steel plant managers, and distribution channel partners. Bottom-up and top-down triangulation ensured data accuracy and consistency across the analysis.
Historical trendline analysis informed the baseline projections for the Stainless Steel 400 Series market across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user, form, and regional regulatory compliance. Compound annual growth rates were derived from a blend of historical performance and projected future demand. Automotive production volumes and emissions regulation timelines served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical shifts or unforeseen technological disruptions. Forecasts reflect assumptions regarding regulatory enforcement and raw material stability. Deviation in chromium supply chain stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Nickel Foam Market
Metals
Copper Azoles Market
Metals
Steel Long Products Market
Metals
Global Aluminum Extruded Products Market
Metals
Trivalent Chromium Finishing Market
Metals
Grain Oriented Electrical Steel Market
Metals
Anodized Titanium Market
Metals
Copper and Brass Flat Products Market
Metals
US Ferrochrome Market
Metals
Aluminium Forging Market
Metals
Tin Chloride Market
Metals
Recycled Metal Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Rare Earth Metals Market
Metals
Copper and Copper Alloy Powder Market
Metals
Beryllium Copper for Telecommunication Market