
 Weathering Steel Market | 2026-2036
Weathering Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Weathering Steel Market Intelligence
Low-alloy copper-chromium-nickel formulations is tilting fabrication protocols toward atmospheric corrosion resistance without protective coatings. ArcelorMittal leverages integrated ore-to-plate capacity across European and North American mills to control alloy consistency. NIPPON STEEL CORPORATION anchors high-strength weathering grades for seismic bridge designs in Japan and export markets. Tata Steel competes on cost-optimized coil production serving South Asian construction and rail infrastructure programs.
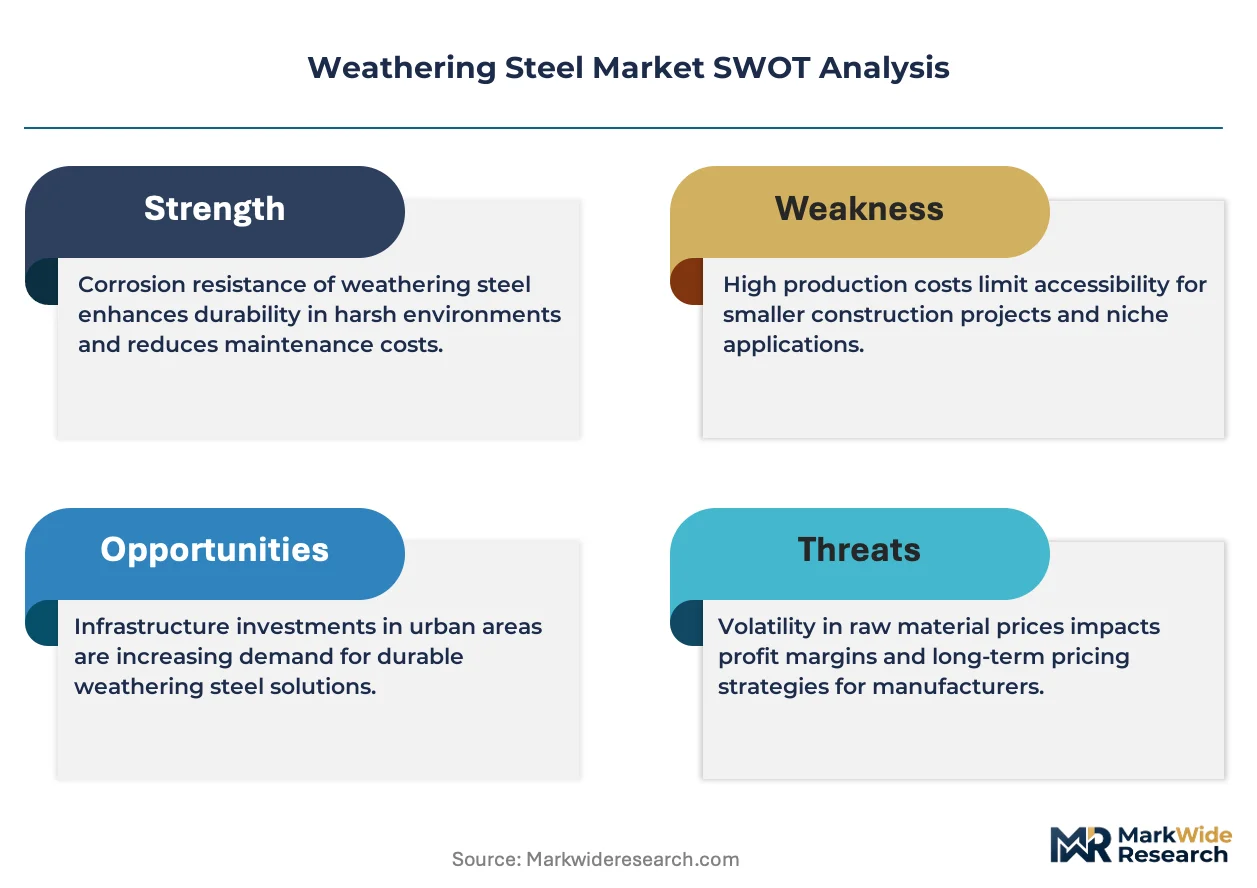
Weathering steel is a high-strength, low-alloy steel containing copper, chromium, nickel, and phosphorus that develops a stable oxide patina when exposed to atmospheric cycles, eliminating the need for paint systems in structural applications. The alloy typically achieves yield strengths of 345–485 MPa depending on grade thickness, with the protective rust layer forming over 18–36 months of cyclic wetting and drying. Steel Plates dominate volume consumption in heavy bridge girders and primary structural members where section modulus requirements dictate thick material. Steel Sheets sustain faster growth in architectural cladding and building envelope applications where designers exploit the aesthetic patina for visual differentiation. Bridge Engineering occupies the deepest margin pool due to specification-driven procurement, extended project timelines, and performance warranties tied to decades of structural integrity.
The American Society for Testing and Materials (ASTM) governs A588 and A242 specifications that define chemical composition and mechanical property thresholds for domestic infrastructure eligibility. The European Committee for Standardization (CEN) administers EN 10025-5 structural delivery conditions that mandate impact toughness and through-thickness ductility for cold climates. Japan's Ministry of Economy, Trade and Industry (METI) aligns JIS G3114 with seismic performance criteria that restrict supplier qualification to proven domestic and import sources. Stakeholders must monitor divergence between regional alloy specifications and emerging performance-based procurement frameworks that could fragment qualified supplier pools across export markets.
Market Dynamics
Federal highway agencies are accelerating performance-based procurement frameworks that prioritize lifecycle cost over first-cost bidding, compressing supplier qualification windows and reshaping competitive positioning around proven atmospheric corrosion warranties rather than alloy chemistry alone.
Growth Catalysts
- Bridge Engineering Procurement:Infrastructure owners in the United States specify weathering steel for coastal and deicing-salt environments where maintenance access is costly, locking in multi-decade material commitments.
- EN 10025-5 Cold-Climate Certification:European structural delivery conditions mandating through-thickness ductility and impact toughness are expanding addressable markets into Nordic bridge and offshore wind applications.
- Atmospheric Corrosion Modeling:Predictive patina formation algorithms developed by national metallurgical laboratories are reducing engineering conservatism and enabling thinner section designs.
Market Restraints
- Scrap Copper and Nickel Volatility:Low-alloy formulations require consistent minor element inputs; London Metal Exchange price swings for copper concentrate directly compress mill margin predictability.
- Integrated Mill Concentration:Ore-to-plate production capability clusters in Western Europe and Japan, creating supply vulnerability for buyers in South Asia and Southeast Asia lacking qualified domestic sources.
- Paint System Substitution in Marine Zones:Hot-dip galvanized and thermal-spray aluminum coatings retain specification preference for salt-spray environments exceeding 500 meters from shore, capping weathering steel penetration.
Strategic Opportunities
- Indian Coastal Infrastructure:The country's Dedicated Freight Corridor and Sagarmala port modernization programs lack qualified domestic weathering steel capacity, creating import substitution potential for certified foreign mills.
- Architectural Cladding Specification:Building envelope designers are specifying pre-weathered coil stock for visual differentiation in commercial and cultural projects, opening volume outside traditional heavy civil.
- Seismic-Grade Alloy Development:Japan's METI-aligned JIS G3114 seismic performance criteria are creating a premium tier for high-strength low-yield-ratio grades in earthquake-prone export markets.
Industry Challenges
- Welding Procedure Qualification:Fabricators must develop and certify WPS/PQR documentation for each thickness and joint configuration, extending project mobilization timelines by 8–14 weeks.
- Patina Aesthetic Variability:End-users reject panels exhibiting uneven oxide formation or runoff staining on adjacent surfaces, forcing contractors to implement controlled wetting protocols that add field labor cost.
- Cross-Border Specification Divergence:ASTM A588 chemistry windows do not align with EN 10025-5 impact requirements, complicating inventory pooling for multinational contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weathering Steel Market |
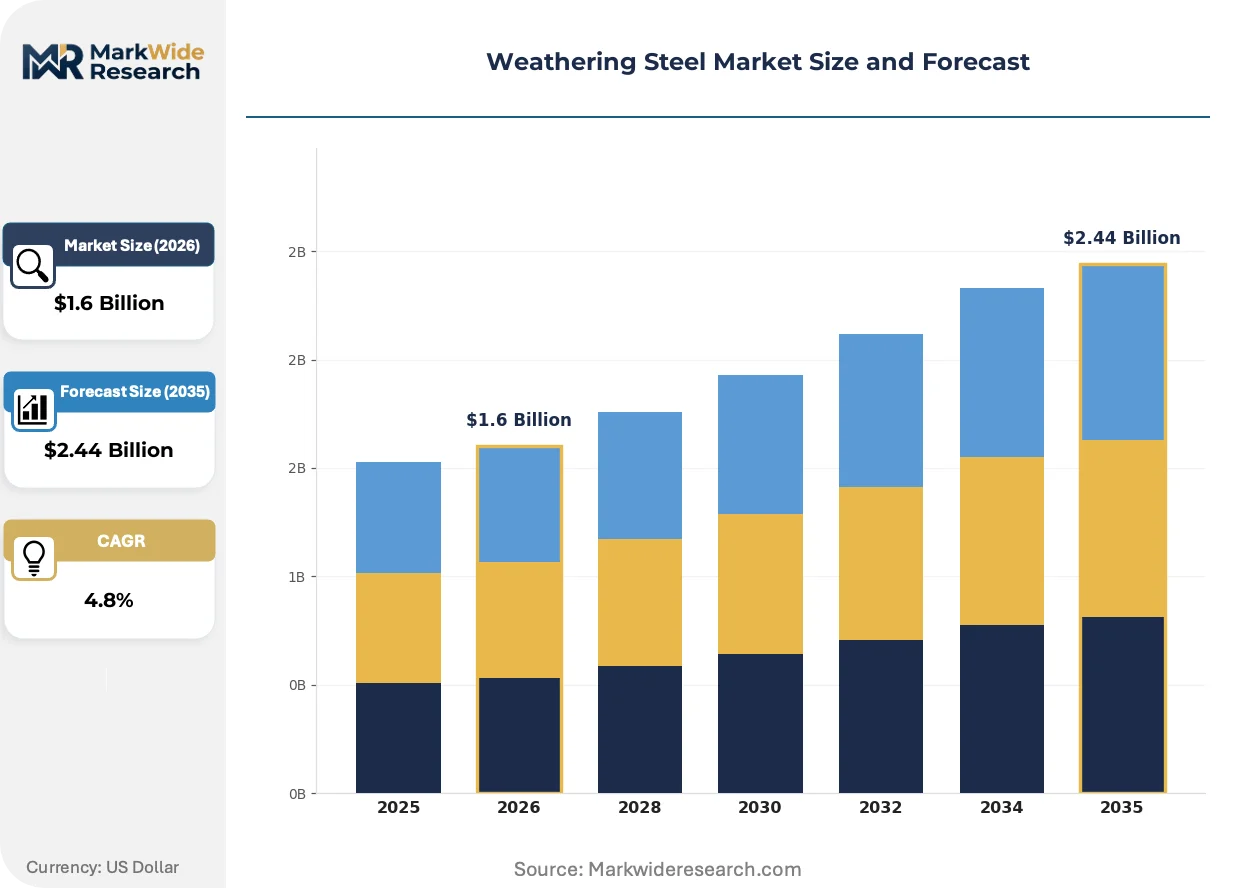
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Plates, Steel Sheets, Steel Coils, Steel Bars End User: Construction, Bridge Engineering, Shipbuilding, Architectural Design Application: Corrosion Resistance, Structural Support, Aesthetic Appeal, Marine Structures Form: Flat, Rolled, Fabricated, Welded |
| Companies Covered | ArcelorMittal, NIPPON STEEL CORPORATION, Tata Steel, JFE Steel Corporation, United States Steel Corporation, SSAB AB, POSCO, BlueScope Steel Limited, HBIS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weathering Steel Market Strategic Shifts & Innovations
Digital specification tools and predictive corrosion modeling are compressing the engineering validation cycle, while regulatory bodies on three continents tighten performance mandates that favor proven alloy systems over experimental formulations.
High-strength low-alloy chemistry is migrating from conventional 345 MPa yield grades toward 485 MPa seismic-capable specifications. Bridge designers in Japan and the US Pacific Northwest are adopting these grades for moment-resisting connections in high-seismic zones. The shift is migrating from empirical safety-factor design toward strain-based performance criteria that reward consistent through-thickness properties.
The European Committee for Standardization is tightening EN 10025-5 Annex J requirements for through-thickness ductility in plates exceeding 50 mm thickness. Mill operators must now demonstrate Z-direction reduction-of-area values above 35% for cold-climate bridge eligibility. Nordic infrastructure authorities are responding by consolidating procurement around mills with proven vacuum-degassing capability, squeezing second-tier suppliers from qualified-bidder lists.
Asset owners are unbundling material supply from fabrication and erection contracts, creating direct mill-to-owner procurement channels that bypass traditional contractor intermediaries. State departments of transportation in the United States now issue separate weathering steel plate solicitations from structural steel packages, compressing contractor margin capture. This channel restructuring is most visible in Texas and California, where Caltrans and TxDOT maintain pre-qualified mill lists and conduct independent metallurgical audits.
Weathering Steel Market Segmentation
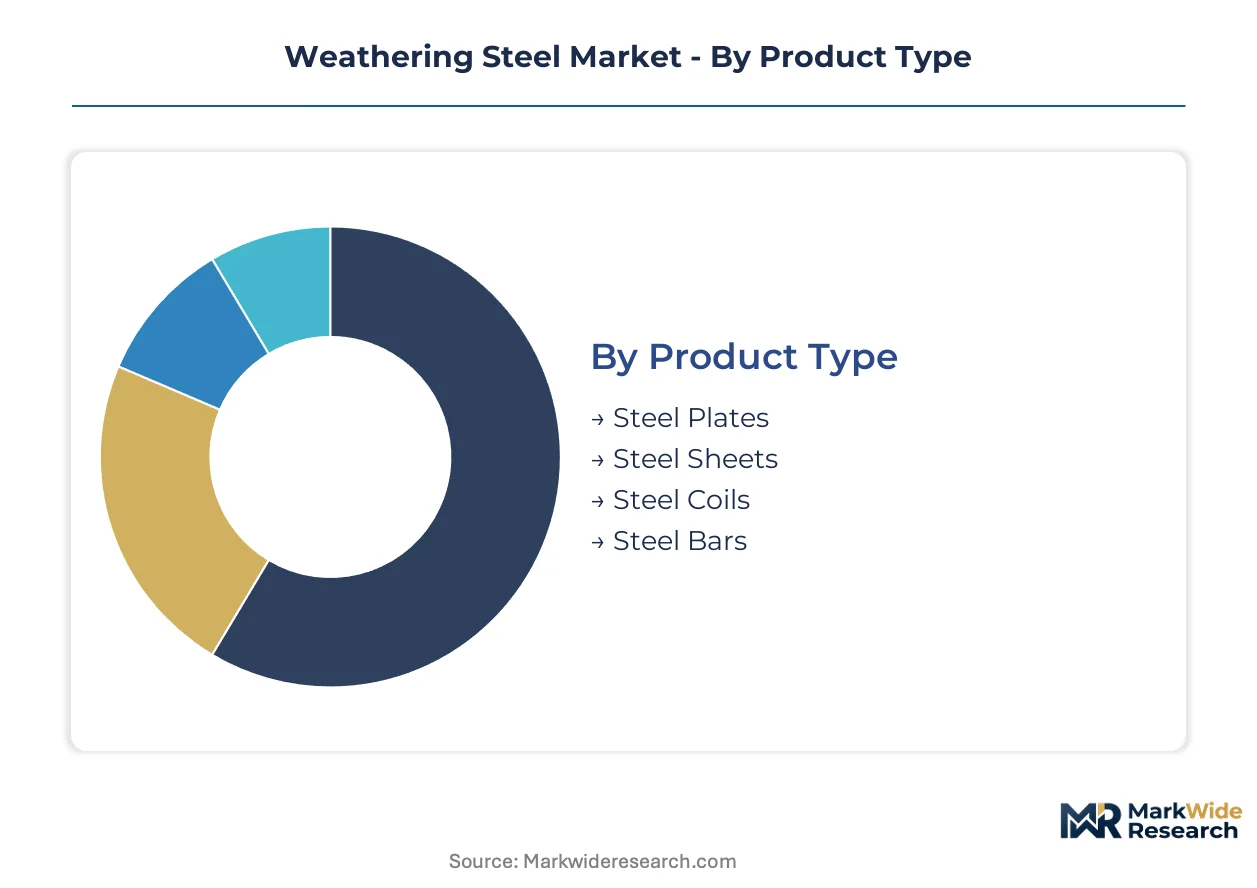
Weathering steel procurement divides across material form, structural function, and exposure environment. Specification engineers match alloy grade to load-bearing requirements and atmospheric corrosion severity, creating distinct demand pools with divergent margin profiles.
Product Type:
Use-case spectrum spans heavy structural members through thin-gauge architectural envelopes, with thickness and surface area driving alloy selection and mill sourcing.
- Steel Plates:Thick-section material ranging 6–150 mm delivers the yield strengths required for bridge girders and primary structural members. Demand concentrates in United States federal highway programs and Japanese seismic bridge designs where section modulus requirements dictate heavy plate procurement.
- Steel Sheets:Thin-gauge coil and cut-length products enable architectural cladding and building envelope applications. Designers in commercial and cultural projects specify pre-weathered sheet stock for visual differentiation, with adoption climbing fastest in European urban regeneration schemes.
- Steel Coils:Continuous-rolled material supports high-volume fabrication of standardized structural components and secondary members.
- Steel Bars:Long products serve reinforcement and connection hardware in concrete-steel composite construction.
Established volume favors Steel Plates; emerging adoption favors Steel Sheets.
End User:
Customer type determines specification stringency, with public infrastructure authorities imposing metallurgical audits absent from private construction.
- Bridge Engineering:Public agencies specify weathering steel for coastal and deicing-salt environments where maintenance access is costly. Caltrans and TxDOT maintain pre-qualified mill lists and conduct independent certification, locking in multi-decade material commitments with proven atmospheric corrosion warranties.
- Construction:Commercial and industrial building frames employ weathering steel for uncoated structural economy. Nordic contractors source EN 10025-5 certified material for cold-climate warehouses and logistics facilities.
- Architectural Design:Building envelope designers exploit the aesthetic patina for visual differentiation in museums, cultural centers, and premium commercial facades.
- Shipbuilding:Above-deck superstructure applications remain limited by salt-spray exposure constraints beyond 500 meters from shore.
Bridge Engineering commands specification premiums; Architectural Design is gaining share fastest.
Application:
Functional requirement shapes alloy chemistry, with corrosion severity dictating copper-chromium-nickel ratios and phosphorus content.
- Corrosion Resistance:The core value proposition eliminates paint systems through stable oxide patina formation over 18–36 months of atmospheric cycling. Infrastructure owners in coastal United States states specify this performance for lifecycle cost reduction.
- Structural Support:Load-bearing applications demand consistent through-thickness properties and Z-direction ductility for seismic and fatigue resistance.
- Marine Structures:Harbor piers and waterfront installations face salt-spray exposure that exceeds weathering steel's uncosted corrosion limits, capping penetration.
- Aesthetic Appeal:Surface finish quality drives procurement for visible architectural applications where uneven oxide formation triggers rejection.
Corrosion Resistance anchors procurement volume; Aesthetic Appeal shows steepest expansion trajectory.
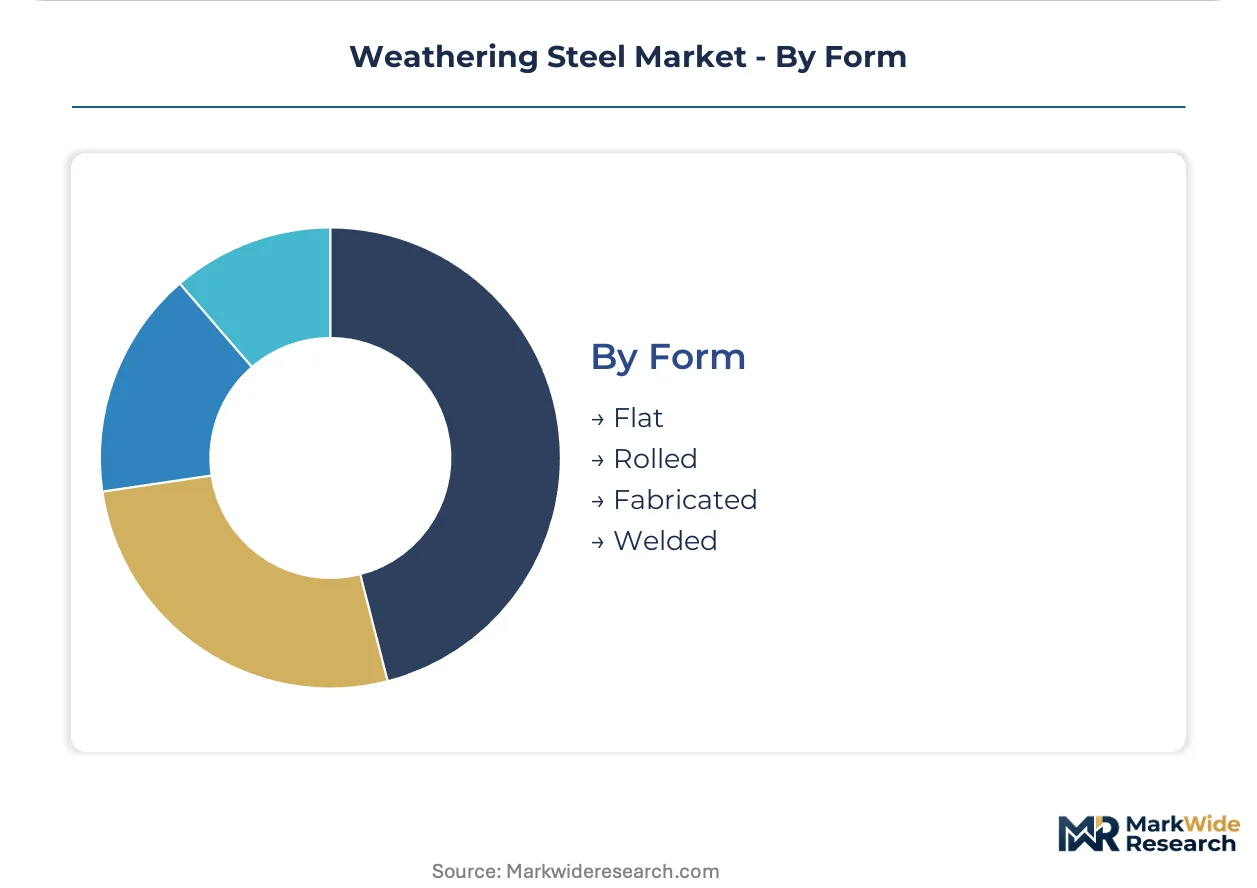
Form:
Processing stage determines supply chain position, with mill-direct flat products contrasting fabricated and welded value-added forms.
- Flat:As-rolled plate and sheet from integrated mills serves heavy fabrication shops with in-house cutting and forming capability.
- Rolled:Coil products enable continuous processing for high-volume structural component manufacturing.
- Fabricated:Cut, drilled, and shaped members reduce field labor for contractors lacking heavy processing equipment.
- Welded:Pre-assembled girders and trusses require certified welding procedure qualification, extending project mobilization timelines.
Flat and Rolled forms dominate mill shipments; Fabricated and Welded forms capture margin through contractor value-add.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal highway agencies and coastal infrastructure authorities concentrate procurement power across four major economies, with specification-driven demand clustering where bridge engineering programs and atmospheric corrosion warranties align.
United States
Caltrans and TxDOT maintain pre-qualified mill lists for bridge girders in coastal and deicing-salt environments. The Federal Highway Administration's performance-based procurement frameworks prioritize lifecycle cost over first-cost bidding. Steel plate fabrication clusters in Houston and Los Angeles serve Pacific Coast and Gulf Coast megaprojects.
Japan
METI-aligned JIS G3114 seismic performance criteria restrict supplier qualification to proven domestic and import sources for earthquake-resistant bridge designs. The Ministry of Economy, Trade and Industry enforces through-thickness ductility standards for high-seismic zones. Kobe and Chiba mill complexes anchor production for domestic infrastructure and export markets.
Germany
EN 10025-5 cold-climate certification mandates Z-direction reduction-of-area values above 35% for Nordic bridge eligibility. The European Committee for Standardization tightens Annex J requirements for plates exceeding 50 mm thickness. Ruhr Valley integrated mills supply vacuum-degassed material for German and Scandinavian procurement authorities.
India
The Dedicated Freight Corridor and Sagarmala port modernization programs lack qualified domestic weathering steel capacity, forcing import dependence. BIS standards for structural steel delivery conditions are evolving toward atmospheric corrosion resistance specifications. Mumbai and Visakhapatnam port authorities drive coastal infrastructure demand without captive mill supply.
South Korea
POSCO anchors domestic plate production for bridge engineering and shipbuilding superstructure applications. The Korean Industrial Standards align with seismic performance criteria for high-strength low-alloy grades. Pohang and Gwangyang mill complexes serve domestic contractors and export markets across Southeast Asia.
Weathering Steel Market Key Industry Players
Channel-controlling players compete with product-specialist players across specification tiers defined by alloy certification rather than volume scale alone. Ore-to-plate integrated capacity clusters in Western Europe and East Asia, creating supply vulnerability for buyers in South Asia lacking qualified domestic sources. Three archetypes dominate: multinational steel majors with metallurgical laboratory networks, regional integrated mills with coastal logistics advantages, and coil-focused specialists serving architectural cladding niches. Capacity expansion and strategic partnerships represent the dominant competitive moves as mills seek to pre-qualify for federal highway programs.
Within the multinational major tier, ArcelorMittal and NIPPON STEEL CORPORATION exemplify channel control through integrated ore-to-plate capacity across European and North American mills. Tata Steel occupies a position among cost-optimized coil producers serving South Asian construction programs. These three companies represent the spectrum from high-strength seismic-grade development to volume-driven architectural supply.
| Leading Market Players |
|---|
| ArcelorMittal |
| NIPPON STEEL CORPORATION |
| Tata Steel |
| JFE Steel Corporation |
| United States Steel Corporation |
| SSAB AB |
| POSCO |
| BlueScope Steel Limited |
| HBIS Group |
| Others |
Cost & Logistics Intelligence
Scrap copper and nickel concentrate supply clusters in Chile, Indonesia, and the Philippines concentrate alloy input pricing power among Western European and Japanese integrated mills, positioning ore-to-plate producers to capture margin pools that coil-dependent fabricators cannot access.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between integrated mills and federal highway agencies, with copper and nickel volatility passed through via quarterly adjustment clauses. Price differentiation rests on EN 10025-5 cold-climate certification grade and atmospheric corrosion warranty duration. Pricing pressure stems from scrap minor-element volatility compressing mill margin predictability. State departments of transportation exhibit highest price sensitivity due to first-cost bidding constraints, while seismic-grade bridge engineering programs show lowest sensitivity due to performance-based procurement mandates.
Supply Chain Analysis
Iron ore and copper concentrate feedstock draws from Australia, Brazil, and Chile into Western European and Japanese integrated mills. Scrap copper and nickel minor-element inputs hinge on London Metal Exchange price cycles. Single-source vulnerability concentrates in vacuum-degassing plate capacity for thick-section bridge girders. Distribution runs through mill-direct channels to state pre-qualified bidder lists, bypassing traditional contractor intermediaries in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Weathering steel procurement is approaching a platform-economics inflection as asset owners unbundle material supply from fabrication contracts, creating direct mill-to-owner interoperability that rewards pre-qualified supplier networks over spot-market relationships.
For Market Incumbents: Entrench position by deepening captive ore-to-plate capacity in North America and Europe to offset scrap volatility, while accelerating atmospheric corrosion warranty certification to defend against emerging coil-specialist entrants in architectural cladding segments. For New Entrants and Emerging Players: Indian coastal infrastructure programs lacking qualified domestic mill supply represent the most penetrable entry point for certified foreign producers, with pre-weathered coil stock for European architectural regeneration schemes offering secondary white-space access through aesthetic differentiation positioning. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mills with vacuum-degassing capability and pre-qualified federal highway status, as these assets command durable procurement channel control across multi-decade infrastructure replacement cycles. The signal to watch is divergence between ASTM A588 and EN 10025-5 specification alignment efforts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Minor-Element Supply | Captive copper and nickel concentrate sourcing insulates mill margins from London Metal Exchange volatility cycles. |
| EN 10025-5 Cold-Climate Certification Investment | Annex J through-thickness ductility qualification opens Nordic bridge and offshore wind procurement pools. |
| Pre-Weathered Coil Production Capacity | Architectural cladding specification growth in European urban regeneration schemes rewards aesthetic-differentiation capability. |
| Direct Mill-to-Owner Channel Development | Caltrans and TxDOT pre-qualified bidder list access compresses contractor intermediation and captures margin. |
| Seismic-Grade Alloy R&D Partnership | JIS G3114-aligned high-strength low-yield-ratio development targets Japan and US Pacific Northwest bridge engineering demand. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across bridge engineering procurement officers, integrated mill metallurgical directors, structural steel fabricators, and state department of transportation specification engineers. Secondary validation drew from ASTM specification documentation, EN 10025-5 delivery condition standards, Federal Highway Administration procurement frameworks, and customs trade data. Bottom-up volume triangulation against top-down macroeconomic indicators ensured cross-verification.
Calibration against historical bridge steel consumption patterns and infrastructure budget appropriations anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product form, end-use application, alloy certification grade, and regional specification cluster. CAGRs were derived from regression analysis of procurement volume trends against atmospheric corrosion warranty adoption curves and federal highway program funding trajectories.
Macroeconomic conditions sit as an overlay; deviation in infrastructure appropriation cycles, scrap metal price volatility, or specification harmonization timelines would shift the trajectory. Cross-checking against state DOT pre-qualified mill list maintenance patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Flat-Rolled Stainless Steel Market
Metals
Global Copper Sputtering Target Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Europe Aluminium Powder Market
Metals
Reconditioned Steel Drums Market
Metals
Stainless Steel Sheet Market
Metals
Titanium Mill Products Market
Metals
Global Vanadium Market
Metals
Battery Metals Market
Metals
Saudi Arabia Aluminum Market
Metals
Aluminum Extrusion Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Aluminum Sheet Market
Metals
US Ferrochrome Market
Metals
Ferrochrome Market
Metals
Motor Lamination Material Market