
 Electrodeposited Copper Foil Market | 2026-2036
Electrodeposited Copper Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Electrodeposited Copper Foil Market Intelligence
The end-use mix for electrodeposited copper foil is expanding its concentration in electric vehicle battery applications, shifting away from traditional printed circuit board dominance. Doosan Corporation leverages its scale in producing ultra-thin foils required for high-energy-density batteries. Furukawa Electric Co., Ltd. differentiates through its focus on specialized foils for high-frequency printed circuit boards. Meanwhile, Chang Chun Group competes by offering a broad portfolio catering to both consumer electronics and automotive sectors.
Electrodeposited copper foil is a thin sheet of high-purity copper produced through an electrolytic process involving a rotating titanium drum cathode. This process allows for precise control over thickness, often down to a few micrometers, creating a material with excellent electrical conductivity and ductility. Within end-use industries, electric vehicle battery manufacturing represents the fastest-growing segment, surpassing mature applications in consumer electronics. For applications, demand for foils used in lithium-ion battery anodes is eclipsing that for traditional rigid printed circuits.
Market standards are shaped by frameworks like the EU's RoHS directive, which restricts hazardous substances in electronics, and China's GB standards for battery components. Concurrently, incentives such as the US Inflation Reduction Act (IRA) influence supply chain decisions for battery-grade foil production. Producers must now navigate the dual challenge of meeting increasingly stringent performance specifications for ultra-thin foils while localizing supply chains to meet regional content requirements.
Market Dynamics
The market's central dynamic is the reorientation of demand and capital investment away from traditional printed circuit boards toward electric vehicle battery anodes, driven by the global energy transition. This shift dictates technology development and supply chain strategy.
Growth Catalysts
- Policy Incentives:Government frameworks like the US Inflation Reduction Act stimulate regional demand by providing subsidies for localized battery component manufacturing.
- Technology Advancement:High-Current Density Electrodeposition enables thinner foils, which are critical for increasing the energy density of electric vehicle batteries.
- Geographic Concentration:Intense demand from battery hubs in South Korea and China creates a powerful pull for foil producers to co-locate.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations of high-purity copper, complicating cost management and impacting producer margins.
- Supply Chain Concentration:Production of high-performance foil is concentrated in Asia, creating vulnerability to geopolitical risks and logistical disruptions for automakers.
- Technical Production Hurdles:Manufacturing defect-free foils below 6 micrometers at scale remains a challenge, limiting yield rates and constraining supply.
Strategic Opportunities
- Supply Chain Regionalization:New battery gigafactories in North America and Europe create an opportunity for localized foil production to serve automotive ecosystems.
- Next-Generation Applications:Foils for solid-state batteries and high-frequency electronics for 6G networks offer new avenues for high-margin growth.
- Regulatory Tailwinds:China's GB standards for battery safety drive demand for premium copper foils, benefiting producers meeting these higher specifications.
Industry Challenges
- High Capital Expenditure:Building new electrodeposition facilities requires massive investment in specialized equipment like titanium drums, creating a high barrier to entry.
- Complex Qualification Cycles:Producers face long qualification cycles to meet the stringent standards of automotive OEMs and battery manufacturers.
- Specialized Talent Scarcity:A shortage of engineers with expertise in electrolytic deposition hinders capacity expansion and process optimization efforts industry-wide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrodeposited Copper Foil Market |
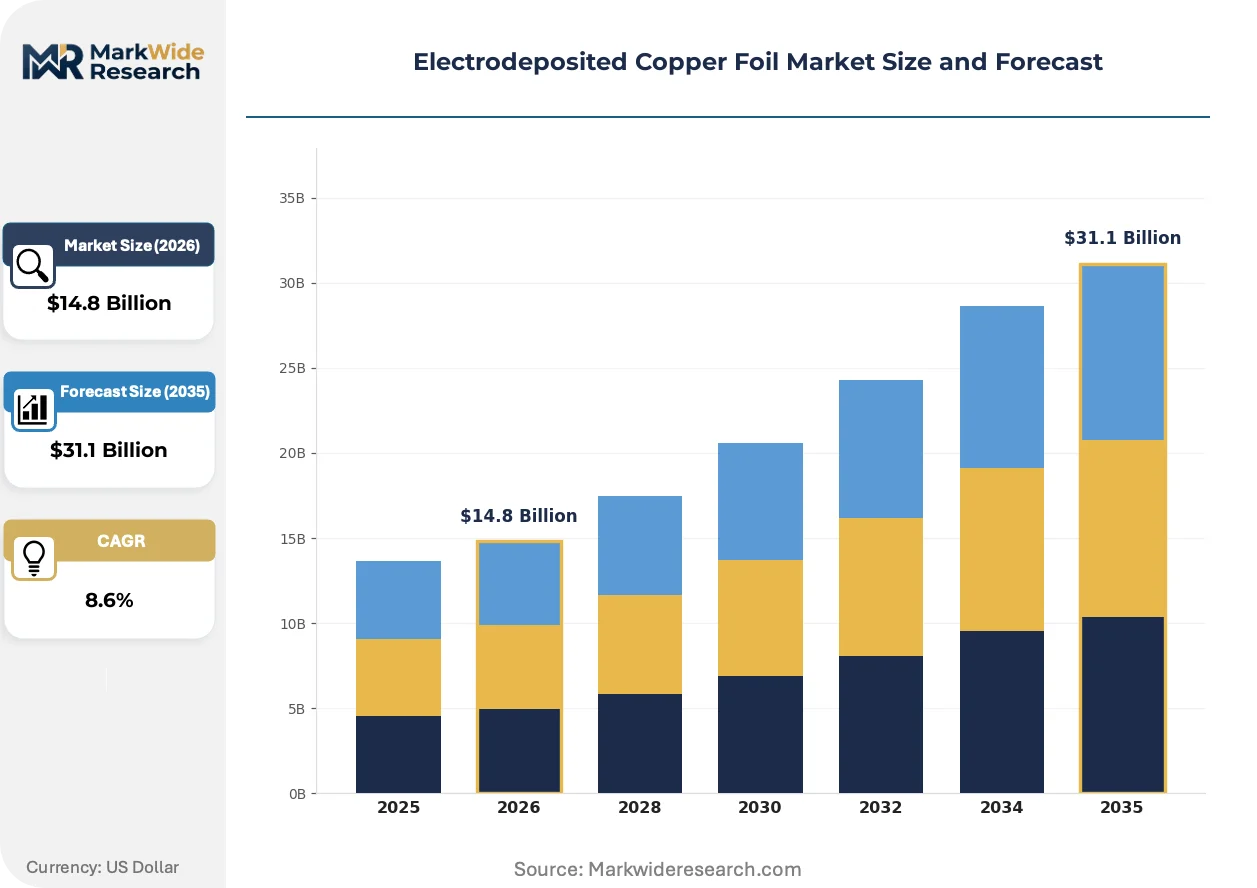
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Thickness: Ultra-Thin, Thin, Medium, Thick, Extra Thick End Use Industry: Printed Circuit Board Manufacturing, Electric Vehicle Battery, Consumer Electronics Assembly, Telecommunications Equipment, Aerospace Components Technology: Traditional Electrodeposition, Pulse Electrodeposition, Continuous Electrodeposition, High-Current Density Electrodeposition, Acid Copper Plating Application: Flexible Printed Circuits, Rigid Printed Circuits, Lithium-Ion Battery Anodes, EMI Shielding, Interconnects |
| Companies Covered | Doosan Corporation, LS Mtron Ltd., Furukawa Electric Co., Ltd., Nan Ya Plastics Corporation, Circuit Foil Luxembourg, Mitsui Mining & Smelting Co., Ltd., Chang Chun Group, Sumitomo Metal Mining Co., Ltd., JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrodeposited Copper Foil Market Strategic Shifts & Innovations
Technological advancements are pushing the physical limits of copper foil to enhance battery performance, while geopolitical pressures simultaneously compel a fundamental reorganization of the supply chain toward regionalization.
High-Current Density Electrodeposition technology facilitates the production of ultra-thin foils with superior surface uniformity. Battery manufacturers are rapidly adopting these advanced foils to increase the energy density of lithium-ion cells. This manufacturing evolution is converging with anode material science, enabling the use of silicon-heavy anodes that require smoother, more durable foils to manage volumetric expansion during cycling.
The European Union's Critical Raw Materials Act is establishing new mandates for supply chain security and localization. These policies incentivize the onshoring of battery component manufacturing, including copper foil, to reduce strategic dependencies on non-EU sources. Producers targeting the European EV market must now invest in regional production to meet content requirements and qualify for associated subsidies.
A definitive shift toward long-term supply agreements and joint development partnerships is redefining procurement for battery-grade foil. This collaborative model is displacing transactional, spot-market purchasing, particularly for high-performance foils where supply is constrained. The trend is most visible in the automotive sector, where OEMs and battery makers partner directly with foil producers to secure future capacity.
Electrodeposited Copper Foil Market Segmentation
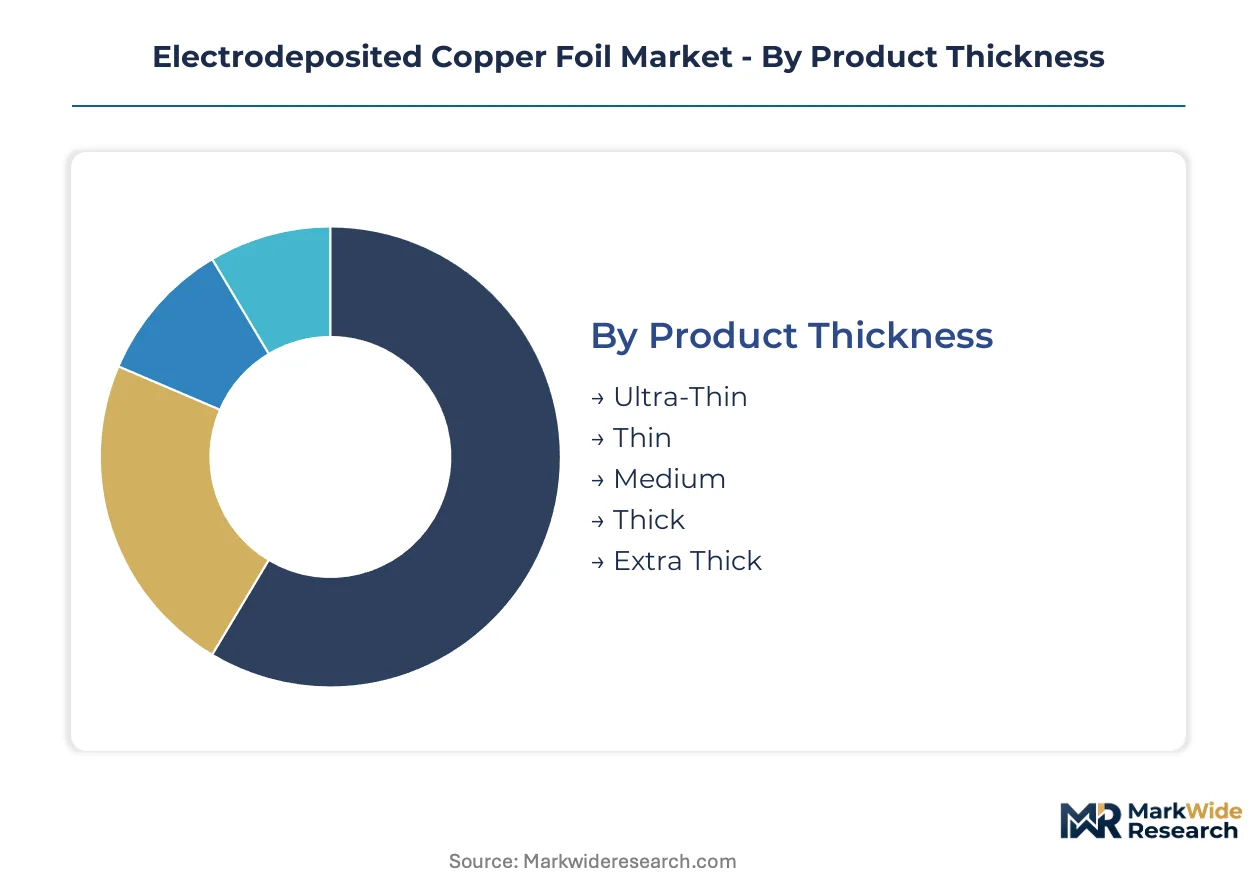
The electrodeposited copper foil market segments across product thickness, end-use industries, manufacturing technologies, and specific applications. Understanding these distinctions is critical for producers to align product development with evolving demand patterns and for end-users to optimize material selection for performance and cost.
Product Thickness:
Segmentation by product thickness highlights the integration depth of copper foil, from ultra-thin sheets embedded in advanced electronics to thicker variants used in more standalone components.
- Ultra-Thin:These foils measure below 6 micrometers, offering minimal weight and volume for high-energy-density applications. Demand from lithium-ion battery manufacturers in South Korea requires these precise specifications for advanced anode designs.
- Thin:Foils ranging from 6 to 12 micrometers provide a balance of electrical performance and mechanical strength for various electronic components. Consumer electronics assembly in China utilizes significant volumes of thin foils for compact device designs.
- Medium:This category includes foils between 12 and 35 micrometers, serving as a standard for general-purpose printed circuit boards.
- Thick:Foils exceeding 35 micrometers are employed in power distribution units and heavy-duty electrical components requiring robust current handling.
- Extra Thick:These specialized foils, often above 70 micrometers, are used in niche applications such as high-current busbars and industrial power electronics.
Ultra-Thin leads volumes today; Thin is gaining share fastest.
End Use Industry:
The end-use industry segmentation reflects the diverse application focus for electrodeposited copper foil, from mature sectors to rapidly expanding new markets.
- Electric Vehicle Battery:This sector consumes high-purity, ultra-thin foils as anode current collectors in lithium-ion cells, driving significant market expansion. Global demand from battery gigafactories in Germany and the United States dictates material specifications.
- Printed Circuit Board Manufacturing:This traditional segment utilizes foils for both rigid and flexible circuit boards, forming the backbone of electronic devices. Consumer electronics production in Taiwan remains a major consumer of these foils.
- Consumer Electronics Assembly:Foils are integrated into various components like flexible circuits, EMI shielding, and internal wiring for smartphones, tablets, and laptops.
- Telecommunications Equipment:High-frequency and high-speed data transmission equipment, including 5G infrastructure, requires specialized copper foils for signal integrity.
- Aerospace Components:Lightweight and high-reliability foils are used in avionics, control systems, and other critical aerospace applications.
Demand for Electric Vehicle Battery applications is shifting market focus away from traditional Printed Circuit Board Manufacturing.
Technology:
The technology segmentation indicates the varying maturity and performance capabilities of different electrodeposition processes for copper foil production.
- High-Current Density Electrodeposition:This advanced process produces ultra-thin foils with superior surface uniformity and mechanical properties. Manufacturers in Japan are pioneering further refinements for next-generation battery anode materials.
- Pulse Electrodeposition:This technique offers enhanced control over grain structure and surface morphology, leading to improved ductility and fatigue resistance. Research institutions in South Korea are exploring its use for advanced packaging substrates.
- Traditional Electrodeposition:This well-established method produces standard-grade copper foils suitable for a broad range of general electronic applications.
- Continuous Electrodeposition:This process focuses on high-volume production of foils with consistent properties, primarily for printed circuit board substrates.
- Acid Copper Plating:Used for specific applications requiring excellent throwing power and deposit uniformity, often in decorative or functional coatings.
High-Current Density Electrodeposition technology drives innovation; Traditional Electrodeposition maintains foundational market presence.
Application:
Segmentation by application highlights the specific functional roles that electrodeposited copper foils play across various end-products, each with distinct performance requirements.
- Lithium-Ion Battery Anodes:Foils serve as the critical current collector for anode materials in electric vehicle and portable electronics batteries. Strict GB standards in China influence the quality requirements for these battery components.
- Rigid Printed Circuits:These foils form the conductive layers on rigid substrates, essential for the functionality of most electronic devices. Automotive electronics production in Germany extensively uses rigid printed circuits.
- Flexible Printed Circuits:Copper foils provide the conductive pathways for flexible electronic devices, enabling compact and pliable designs.
- EMI Shielding:Foils are used to protect sensitive electronic components from electromagnetic interference, ensuring signal integrity.
- Interconnects:These foils form the electrical connections between different components within an electronic system, facilitating signal and power transfer.
Lithium-Ion Battery Anodes hold strategic importance; Rigid Printed Circuits represent a stable, high-volume application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory-arbitrage angle significantly influences the global electrodeposited copper foil market, as production migrates to locations offering favorable policy environments or lower compliance costs. Government incentives and evolving environmental standards in different regions shape investment decisions for new manufacturing capacity. This dynamic encourages localized supply chains to meet specific regional content requirements.
South Korea
Intense demand from battery manufacturers drives the South Korean market for ultra-thin electrodeposited copper foils. The country's MFDS standards for battery safety and performance influence material specifications for domestic production. Key battery production hubs in Ulsan and Cheongju actively seek high-purity foils for advanced lithium-ion cells.
China
China's market for electrodeposited copper foil is propelled by its vast consumer electronics and electric vehicle battery industries. The GB standards for battery components mandate stringent quality for anode materials, favoring premium foil suppliers. Major electronics and EV manufacturing centers in the Yangtze River Delta and Pearl River Delta regions consume significant volumes.
Germany
Electric vehicle battery gigafactories in Germany are accelerating demand for high-performance electrodeposited copper foils. European Union regulations like the EU Green Deal and Critical Raw Materials Act incentivize localized production within the bloc. Automotive manufacturing clusters in Bavaria and Baden-Württemberg require specialized foils for next-generation battery designs.
United States
The US market experiences strong growth due to the Inflation Reduction Act (IRA), which provides substantial subsidies for domestic battery component manufacturing. This policy framework encourages the establishment of new foil production facilities to serve the expanding EV sector. Battery production sites in Michigan and Georgia represent significant demand centers for localized supply.
Japan
Demand for electrodeposited copper foil in Japan stems from both advanced electronics and emerging battery technologies. METI policies support research and development in high-current density electrodeposition for superior foil performance. Electronics and automotive manufacturing in the Kanto and Chubu regions drive continuous innovation in foil applications.
Electrodeposited Copper Foil Market Key Industry Players
Capacity expansion dominates the current landscape, as producers invest heavily to meet the escalating demand from electric vehicle battery manufacturers. The market structure exhibits a tiered consolidation, with a few large-scale global players and numerous specialized regional manufacturers. Strategic archetypes include integrated materials specialists, technology-focused innovators, and broad-portfolio suppliers. Geographic expansion and strategic partnerships with battery makers represent dominant competitive moves.
On the premium-tier vector, Doosan Corporation leverages its scale in producing ultra-thin foils for high-energy-density batteries. Furukawa Electric Co., Ltd. exemplifies specialization, focusing on advanced foils tailored for high-frequency printed circuit boards. Chang Chun Group occupies a position as a broad-portfolio supplier, catering to both consumer electronics and the automotive sectors with diverse offerings.
| Leading Market Players |
|---|
| Doosan Corporation |
| LS Mtron Ltd. |
| Furukawa Electric Co., Ltd. |
| Nan Ya Plastics Corporation |
| Circuit Foil Luxembourg |
| Mitsui Mining & Smelting Co., Ltd. |
| Chang Chun Group |
| Sumitomo Metal Mining Co., Ltd. |
| JX Nippon Mining & Metals Corporation |
Cost & Logistics Intelligence
High-Current Density Electrodeposition technology simultaneously reshapes cost economics and supply concentration in the electrodeposited copper foil market. This advanced production method enables thinner, higher-performance foils, intensifying capital investment and demand in concentrated manufacturing hubs.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for high-performance electrodeposited copper foils, particularly in the electric vehicle battery sector. The prevailing pricing model is contract-based long-term offtake, driven by stringent performance specifications and complex qualification cycles. Price differentiation stems from achieving ultra-thinness, superior surface uniformity, and compliance with standards like China's GB. Pricing softness affects standard-grade foils due to broader supply, while premium battery-grade foils command higher margins.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs and battery manufacturers influence supply chain strategies for electrodeposited copper foil. Geographic supply concentrates in China, South Korea, and Japan, creating vulnerability to geopolitical risks and logistical disruptions. The industry relies on high-purity copper and specialized titanium drums for production. Commodity price volatility for copper presents a significant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrodeposited copper foil market functions as a stable compounder, driven by the global energy transition and its sustained demand for electric vehicle battery components. Strategic investments in advanced manufacturing capabilities will secure long-term growth.
For Market Incumbents:Cement technological leadership in High-Current Density Electrodeposition to produce defect-free foils below 6 micrometers. Secure long-term supply agreements with major EV battery manufacturers to counter emerging competition. Invest in capacity additions within North America and Europe, leveraging incentives like the US Inflation Reduction Act and the EU Critical Raw Materials Act. This strategy mitigates technical production hurdles and localizes supply chains.
For New Entrants and Emerging Players:The US Inflation Reduction Act in the United States opens a window for localized electrodeposited copper foil production. Target specialized foils for solid-state batteries and high-frequency electronics for 6G networks, which represent high-margin growth areas. Establish joint development partnerships with battery manufacturers to accelerate qualification cycles and secure initial market share. Focus on new gigafactories in North America and Europe.
For Investors and Strategic Acquirers:Roll-up economics work for integrated materials specialists because high capital expenditure creates significant barriers to entry and favors scale. The market demonstrates long-term viability over the next decade, driven by the global energy transition. Identify technology-focused innovators with proprietary High-Current Density Electrodeposition processes or specialized talent. A key signal to watch is the successful scaling of defect-free, ultra-thin foil production below 6 micrometers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet escalating demand from electric vehicle battery manufacturers globally. |
| Long-term Supply Agreement | Secure future volume commitments with automotive OEMs and battery makers. |
| Technology Licensing | Accelerate adoption of advanced electrodeposition processes for next-generation foils. |
| Green Manufacturing Transition | Align with EU Green Deal mandates for sustainable production practices. |
| Joint Venture | Share high capital expenditure and technical risks for new regional production facilities. |
Research Approach
Multiple input streams — industry reports, company filings, and primary interviews — were reconciled to construct a comprehensive market view. This involved engaging battery manufacturing executives, electrodeposition process engineers, and procurement managers at automotive OEMs. Secondary validation drew from SEC filings, national statistical databases, and relevant trade association publications. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
The data-stream reconciliation process integrated historical market performance with future projections across the analysis window. Segmentation dimensions modeled included product thickness, end-use industries, manufacturing technologies, and specific applications. Compound annual growth rates were derived through regression analysis, informed by expert consensus. Electric vehicle production forecasts and battery energy density targets served as critical industry-specific forecast inputs.
Revisions become necessary when significant shifts in commodity prices, geopolitical dynamics, or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding current market conditions and regulatory stability. Deviation in raw material supply or EV adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Flat Carbon Steel Market
Metals
Global Copper Cathode Market
Metals
Osmium Market
Metals
Metallurgical Coal Market
Metals
Ferro Aluminum Market
Metals
Global Duplex Stainless Steel Market
Metals
Metal Forging Market
Metals
Neodymium Market
Metals
Hafnium Foil Market
Metals
Copper Foil Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Nickel Oxide Target Market
Metals
Barium Market
Metals
High Purity Aluminium Market
Metals
Stainless Steel Round Bar Market
Metals
Aluminum Welding Market