
 Transition Metals Market | 2026-2036
Transition Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Transition Metals Market Outlook
The capital-intensity divergence between fully integrated miners and downstream refiners is bifurcating competitive returns across the value chain. BHP Group leverages its Pilbara iron ore cash flows to cross-fund copper growth projects in Chile. Vale S.A. anchors its positioning through captive logistics and deepwater port infrastructure in Brazil. Rio Tinto Group differentiates via autonomous haulage systems that compress unit costs at its Oyu Tolgoi copper-gold complex.
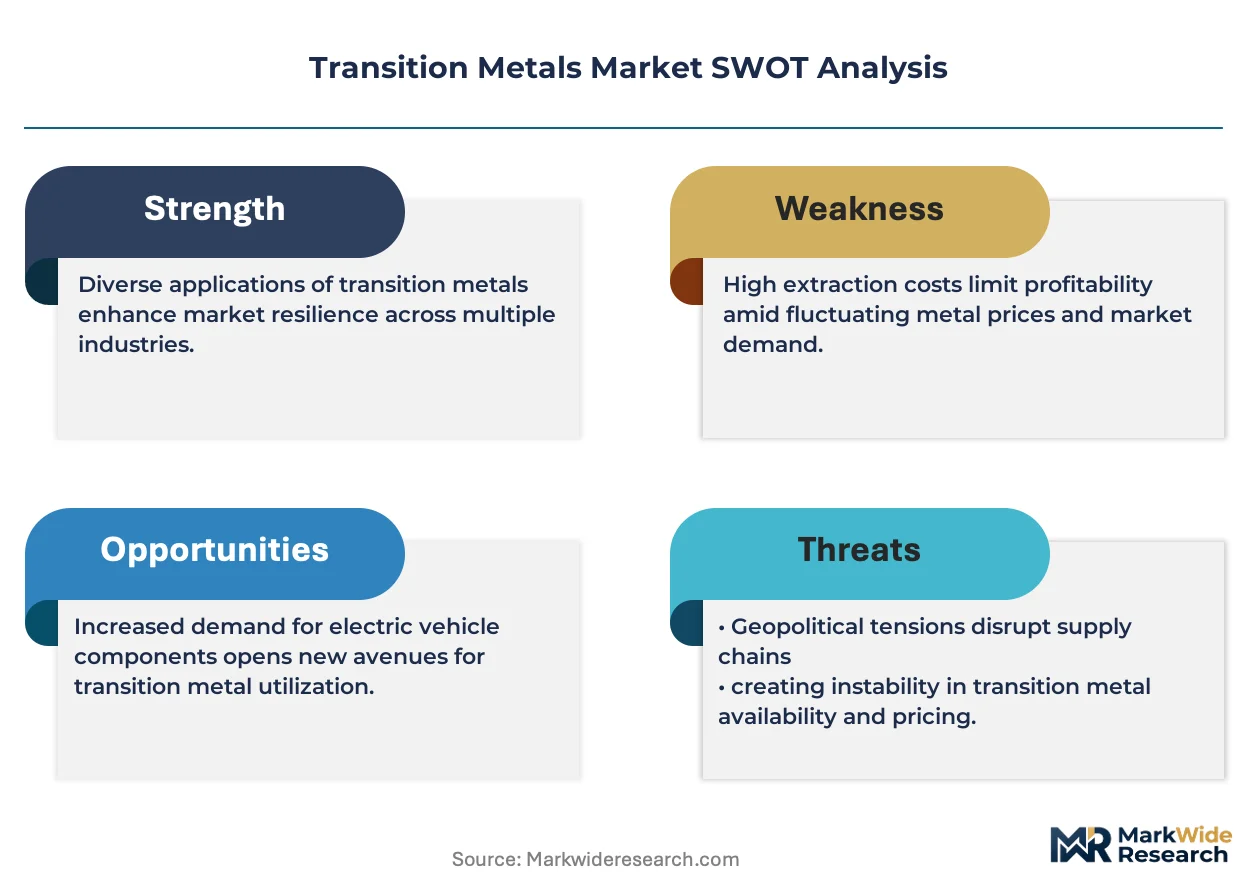
Transition metals comprise elements with partially filled d-orbitals—chiefly iron, cobalt, nickel, copper, zinc, and manganese—valued for catalytic activity, electrical conductivity, and corrosion resistance in alloyed form. These properties make them irreplaceable in electric motor windings, battery electrodes, and structural components subjected to thermal cycling. Copper commands the largest revenue pool among product types due to its ubiquity in power transmission and EV architectures, while cobalt retains premium pricing through supply concentration in the Democratic Republic of Congo. Nickel sulfide and laterite feedstocks split the application landscape, with laterite-derived Class 1 nickel expanding fastest for battery chemistries despite higher processing energy.
EPA tailings standards in the United States, REACH substance restrictions in Europe, and Indonesia's downstream beneficiation mandates are reshaping where refining capacity locates and what process routes qualify for market access. China's MEE emissions caps and GB standards on heavy metal discharge further constrain marginal smelter economics. Stakeholders must monitor regulatory arbitrage between jurisdictions while securing offtake agreements tied to verified low-carbon production certificates.
Market Dynamics
Electric vehicle battery cathode chemistry shifts are redrawing offtake patterns for copper and nickel, while Indonesia's downstream beneficiation mandates and the EU Battery Regulation force smelters to relocate or retrofit processing capacity.
Growth Catalysts
- EU Battery Regulation carbon-intensity thresholds:The framework mandates verified low-carbon production certificates for market access, pushing battery manufacturers toward certified nickel and copper suppliers.
- Indonesia's nickel processing corridor:Downstream beneficiation policies concentrate Class 1 nickel refining capacity near laterite mines, shortening supply chains for battery-grade material.
- High-pressure acid leaching (HPAL):This extraction technology unlocks laterite-derived nickel for EV cathodes despite energy-intensive processing, expanding feedstock options beyond sulfide deposits.
Market Restraints
- Energy cost volatility:Electrowinning and smelting operations face margin compression from power price swings, particularly affecting laterite-to-Class-1 nickel conversion.
- DRC cobalt concentration:Artisanal and small-scale mining dependence in the Democratic Republic of Congo creates supply disruption risk and ethical sourcing verification burdens.
- Iron-silicate slag limitations:Conventional pyrometallurgical routes struggle to achieve battery-grade purity without hydrometallurgical supplementation, raising capital requirements.
Strategic Opportunities
- Chile's copper mining belt expansion:Untapped porphyry deposits in the Atacama region offer sulfide concentrate for low-carbon smelting routes serving North American battery supply chains.
- Solid-state battery electrolyte demand:Next-generation cell architectures require ultra-high-purity nickel and lithium-metal interfaces, opening premium pricing tiers for refined output.
- China's dual carbon goals:MEE emissions caps and GB standards on heavy metal discharge accelerate closure of marginal smelters, creating market share openings for compliant operators.
Industry Challenges
- HPAL engineering talent scarcity:The specialized skill set for high-pressure acid leach plant design and operation concentrates among a limited pool of contractors, delaying project timelines.
- EPA tailings dam certification:New construction standards in the United States extend permitting cycles for greenfield copper projects, compressing development windows against demand curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transition Metals Market |
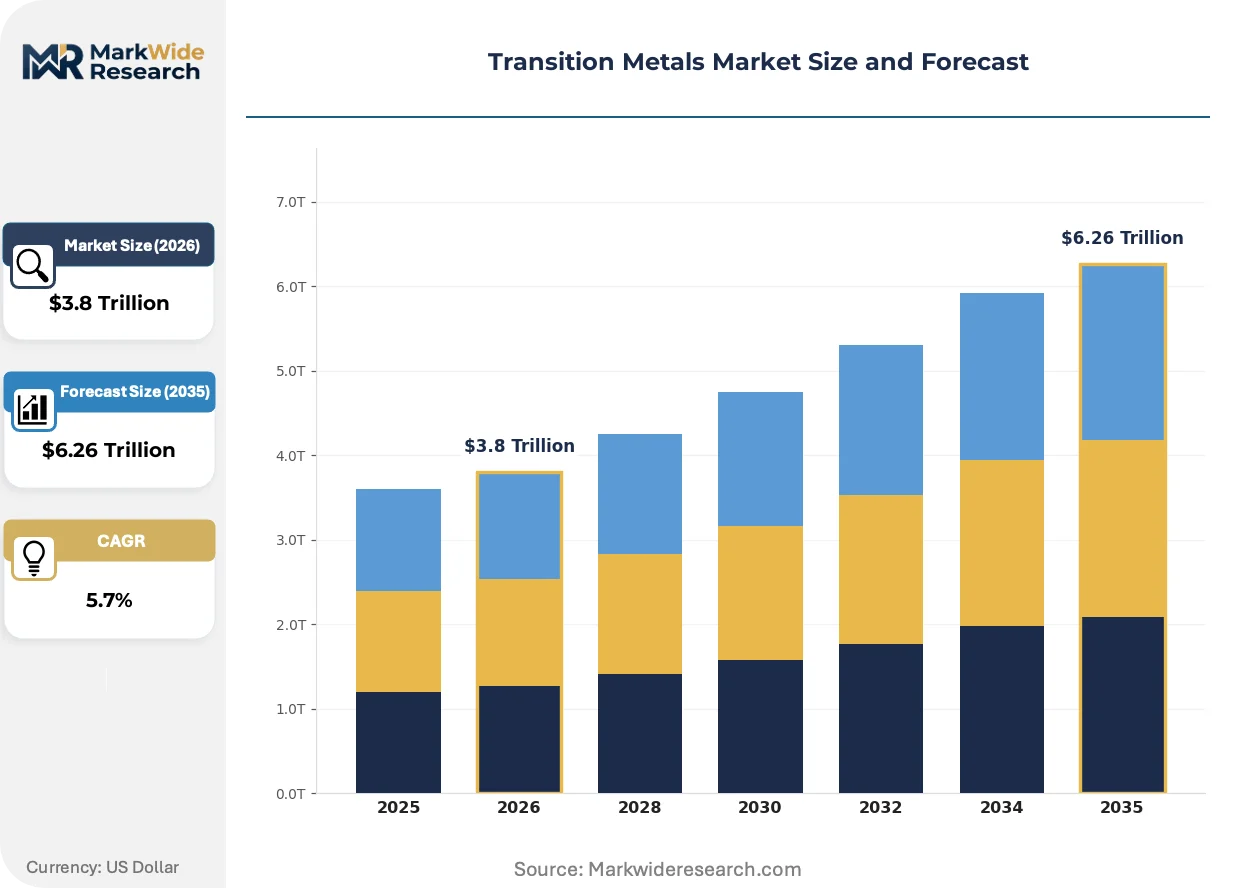
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $6.26 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Nickel, Zinc, Cobalt Application: Aerospace, Electronics, Automotive Manufacturing, Construction End User: Manufacturers, Distributors, OEMs, Fabricators Form: Alloys, Powders, Sheet Metal, Bars |
| Companies Covered | Vale S.A., Vedanta Resources plc, BHP Group, Fortescue Metals Group Limited, Teck Resources Limited, Rio Tinto Group, Norilsk Nickel, KGHM Polska Miedź S.A., Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transition Metals Market Strategic Shifts
Process metallurgy and supply chain verification systems are converging to decarbonize extraction while traceability requirements fragment procurement patterns across battery supply chains.
Direct solvent extraction (SX-EW) circuits for copper is fragmenting the traditional concentrate-smelter-refiner hierarchy. Mining houses in Chile and Peru are installing integrated leach-electrowinning plants that bypass smelting entirely. Battery manufacturers are contracting directly with these operations to secure Scope 3 emissions data for EU Battery Regulation compliance.
REACH substance restrictions in Europe are forcing cobalt refiners to demonstrate conflict-free provenance through blockchain-anchored certificates. The regulation's due diligence obligations cascade downstream to cathode active material producers. German and Polish battery cell plants now require DRC-sourced cobalt to pass third-party audit gates before contract execution.
Automotive OEMs are unbundling cathode material procurement from cell supplier agreements. Tesla, BMW, and Volkswagen Group are negotiating direct offtake with Indonesian nickel processors and Chilean copper miners, disintermediating traditional trading houses. This pattern concentrates most visibly in European and North American EV manufacturing clusters where supply chain transparency carries regulatory weight.
Transition Metals Market Segmentation
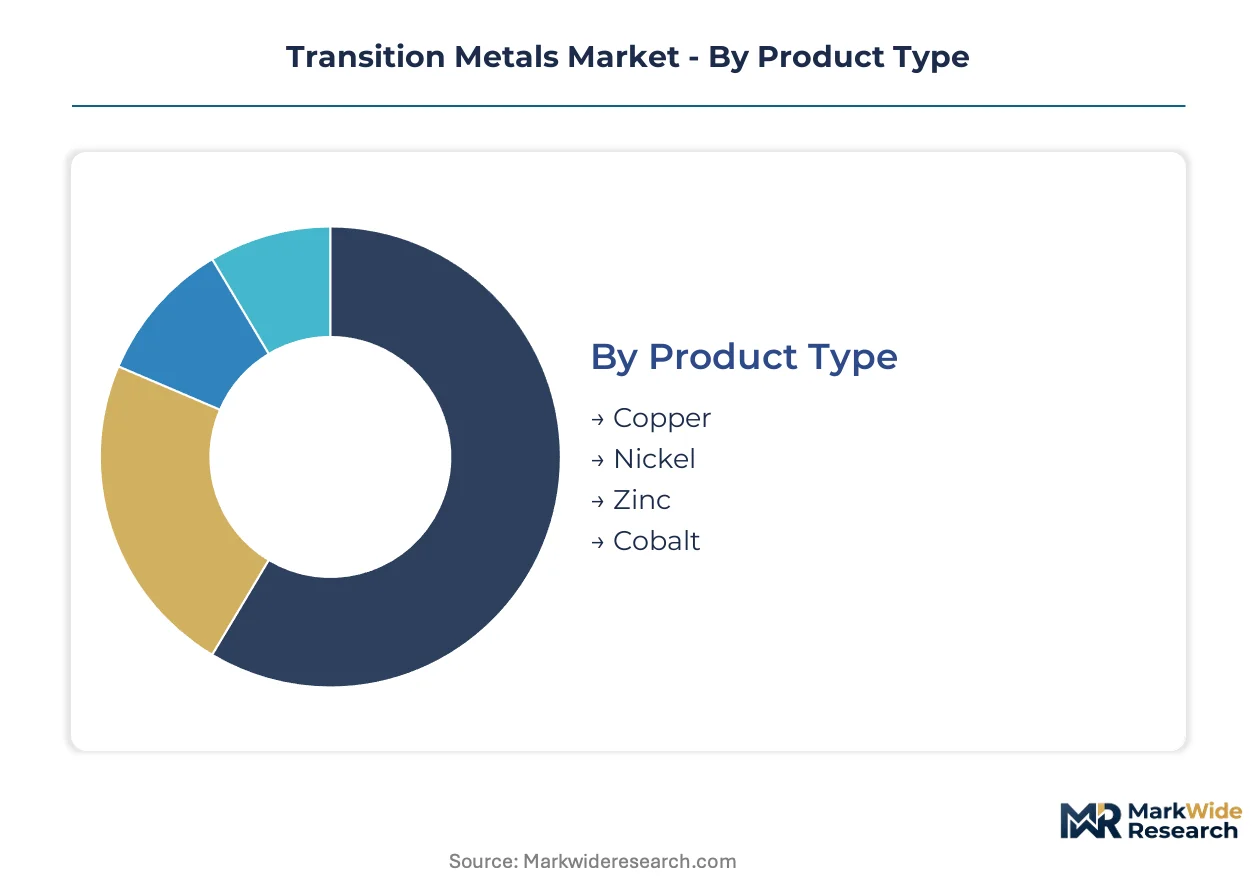
Segmentation in transition metals reveals how battery chemistry shifts and carbon certification requirements are fragmenting procurement patterns across cathode supply chains. Each dimension exposes different margin capture points from mine gate to refined product.
Product Type:
Margin pools concentrate in battery-grade refined outputs where carbon intensity verification commands premium pricing tiers.
- Copper:Cathode-grade copper with maximum 20 ppm silver content serves EV motor windings and power electronics. Demand concentrates in Chilean mining clusters supplying North American battery gigafactories, with Scope 3 emissions data now mandatory for EU Battery Regulation compliance.
- Nickel:Class 1 nickel (minimum 99.8% purity) from laterite HPAL processing dominates EV cathode formulations. Indonesia's Morowali Industrial Park anchors expanding capacity, though energy cost volatility compresses margins at integrated operations.
- Zinc:High-grade zinc ingot protects steel components in EV charging infrastructure through galvanization. Galvanizing-grade demand tracks construction and renewable energy deployment cycles.
- Cobalt:Battery-grade cobalt sulfate requires DRC hydroxide feedstock refined to strict heavy metal specifications. Ethical sourcing verification through blockchain-anchored certificates adds cost layers.
The dominant share belongs to Copper, while Nickel is closing the gap fastest on battery chemistry penetration.
Application:
Application-based demand splits sharply between decarbonization-driven sectors and traditional industrial offtake.
- Aerospace:Superalloy formulations incorporating nickel and cobalt withstand turbine operating temperatures exceeding 1,000°C. Single-crystal casting for jet engine blades demands ultra-high-purity feedstock with trace element control.
- Electronics:High-conductivity copper foil under 6 microns thickness enables printed circuit board miniaturization. Semiconductor packaging applications require oxygen-free grades with thermal expansion matching silicon substrates.
- Automotive Manufacturing:EV battery cathodes consume Class 1 nickel and cobalt in NMC and NCA chemistries. OEMs now contract directly with Indonesian processors and Chilean miners, bypassing traditional trading intermediaries.
- Construction:Structural steel reinforcement and architectural cladding absorb zinc and copper in corrosion-resistant alloys. Green building certification schemes increasingly specify recycled content thresholds.
Automotive Manufacturing commands the largest volume commitment, with Electronics expanding most quickly on semiconductor reshoring initiatives.
End User:
End user categories reflect diverging technical capabilities in metallurgical processing and carbon accounting.
- Manufacturers:Cathode active material producers and alloy fabricators purchase refined metal with certified carbon footprints. German and Polish battery cell plants require third-party audit gates before contract execution.
- Distributors:Metal traders and warehouse operators manage price hedging and just-in-time delivery to fabrication shops. Inventory financing costs have risen with interest rate movements.
- OEMs:Automotive and aerospace original equipment manufacturers negotiate direct offtake agreements with miners. Tesla, BMW, and Volkswagen Group unbundle cathode procurement from cell supplier contracts.
- Fabricators:Wire rod mills, tube producers, and forging operations convert refined metal to semi-finished shapes. Energy-intensive rolling and extrusion operations face margin pressure from power price volatility.
OEMs are gaining procurement leverage fastest, while Distributors retain critical logistics coordination functions.
Form:
Form selection determines downstream processing economics and scrap recovery rates.
- Alloys:Brass (copper-zinc) and bronze (copper-tin) formulations deliver tailored strength and corrosion resistance for marine and architectural applications. Custom melt specifications require precise composition control.
- Powders:Atomized and electrolytic metal powders enable additive manufacturing and powder metallurgy compaction. Particle size distribution specifications vary by sintering process requirements.
- Sheet Metal:Cold-rolled copper and nickel sheets serve electrical busbar and heat exchanger fabrication. Thickness tolerances tighten for EV battery cell terminal applications.
- Bars:Extruded and drawn bar stock feeds CNC machining centers for aerospace fittings and medical implants. Surface finish specifications distinguish aerospace-grade from commercial grades.
Alloys retain the broadest application base, though Powders are climbing the fastest on additive manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing smelter location decisions as battery manufacturers chase verified low-carbon supply chains. Countries with concentrated laterite reserves or sulfide copper deposits now compete on carbon-intensity certification rather than raw tonnage alone.
Indonesia
Class 1 nickel demand from EV cathode manufacturers drives capacity expansion across Sulawesi and Halmahera. Downstream beneficiation mandates require foreign miners to build domestic refining plants before export permits issue. The Morowali Industrial Park hosts integrated HPAL operations supplying battery-grade material directly to Korean and Chinese cell makers.
Chile
Porphyry copper deposits in the Atacama Desert feed low-carbon concentrate to North American battery gigafactories. EPA tailings standards for US-listed miners operating abroad extend compliance burdens to Chilean project finance. Antofagasta and Calama mining clusters anchor expansion of direct solvent extraction circuits bypassing traditional smelting.
China
Domestic smelter closures under MEE emissions caps and GB heavy metal discharge standards are shifting refined metal import dependence. Dual carbon goals accelerate marginal capacity retirement in Hunan and Yunnan provinces. The Yangtze River Delta concentration of cathode active material plants now sources certified Indonesian nickel through long-term offtake contracts.
Democratic Republic of Congo
Artisanal and small-scale mining dominance in cobalt hydroxide feedstock creates supply concentration risk for European battery regulations. Blockchain-anchored provenance certificates are becoming mandatory for market access under REACH due diligence obligations. The Kolwezi and Likasi mining corridors face escalating third-party audit requirements from German and Polish cathode plants.
Australia
Nickel sulfide deposits in Western Australia's Kambalda district offer lower-carbon alternatives to Indonesian laterite processing. BHP Group and others leverage Pilbara iron ore cash flows to cross-fund copper growth projects. Perth-based engineering contractors concentrate scarce HPAL design expertise serving Indonesian project development.
Transition Metals Market Competitive Environment
Concentration sits with diversified mining houses that control captive logistics and cross-fund battery metal expansion from bulk commodity cash flows. The competitive structure splits between integrated majors with autonomous haulage capabilities and mid-tier players dependent on third-party processing. Strategic archetypes include: diversified miners with iron ore cross-subsidization, laterite nickel specialists with Indonesian government partnerships, and copper-focused operators with direct solvent extraction integration. Dominant competitive moves span backward integration into captive refining capacity and geographic expansion toward battery manufacturing clusters.
Among diversified majors, BHP Group exemplifies the cross-funded expansion archetype through its Australian iron ore base and Chilean copper growth pipeline. Vale S.A. represents the captive logistics model with deepwater port infrastructure anchoring Brazilian material flows. Rio Tinto Group occupies a position defined by autonomous haulage systems at its Mongolian copper-gold complex. These three structures illustrate how capital intensity and operational technology differentiate returns across the value chain.
| Leading Market Players |
|---|
| Vale S.A. |
| Vedanta Resources plc |
| BHP Group |
| Fortescue Metals Group Limited |
| Teck Resources Limited |
| Rio Tinto Group |
| Norilsk Nickel |
| KGHM Polska Miedź S.A. |
| Glencore |
| Others |
Value Chain & Pricing Dynamics
Ninety-day cathode-grade nickel inventory cycles at Indonesian HPAL operations concentrate pricing power with integrated processors possessing verified low-carbon certificates, while spot-market buyers face escalating premiums for EU Battery Regulation compliance documentation.
Pricing Analysis
The customization-premium spread between standard LME-grade cathodes and battery-specific material with Scope 3 emissions data spans contract-based long-term offtake structures. Price differentiation hinges on carbon-intensity certification tier and geographic delivery cost to European cell plants. Cost compression in laterite-derived Class 1 nickel is intensifying because Indonesian energy subsidies face phase-out pressures. OEM direct-procurement teams show lowest price sensitivity; trading houses and distributors face highest margin compression.
Supply Chain Analysis
Strategic-stockpile preferences dominate cathode-active-material procurement as battery manufacturers buffer against Indonesian export permit volatility and DRC cobalt disruption risk. Supply concentrates in Indonesia, Chile, and the Democratic Republic of Congo for nickel, copper, and cobalt respectively. Processing draws from sulfuric acid, high-purity oxygen, and electricity inputs. Single-source vulnerability in DRC hydroxide feedstock creates structural exposure. Distribution runs through long-term offtake contracts directly linking miners to cell plants, disintermediating traditional metal traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs unbundling cathode procurement from cell supplier agreements, with Volkswagen Group, BMW, and Tesla collectively commanding expanded leverage over Indonesian nickel processors and Chilean copper miners.
For Market Incumbents: Compound defensive positioning through captive refining capacity in Indonesia's Morowali corridor and backward integration into sulfuric acid production. The threat of solid-state battery electrolyte demand shifting purity specifications demands immediate HPAL engineering talent retention. Certification investment for EU Battery Regulation compliance remains the critical lever for margin defense against trading house disintermediation.
For New Entrants and Emerging Players: Lead with ultra-high-purity nickel sulfate targeting solid-state battery prototypes, the most penetrable segment given incumbent focus on conventional NMC cathode supply. Australian nickel sulfide deposits offer lower-carbon feedstock alternatives to Indonesian laterite dominance. A go-to-market angle anchored to Scope 3 emissions data transparency commands premium positioning with European OEM procurement teams.
For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because verified low-carbon production certificates are becoming non-negotiable for market access rather than optional premiums. Acquisition targets include mid-tier HPAL operators with Indonesian government partnerships and proven engineering execution. The signal to watch is EU Battery Regulation enforcement tightening on imported cathode material carbon intensity thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Capacity Expansion | Unlocks laterite nickel for EV cathodes despite energy-intensive processing requirements. |
| Backward Integration into Captive Sulfuric Acid | Reduces feedstock cost volatility for Indonesian nickel processors facing energy subsidy reform. |
| Carbon Certification Program | Secures EU Battery Regulation compliance for market access to German and Polish cell plants. |
| Direct Solvent Extraction Circuit Installation | Bypasses traditional smelting entirely for Chilean copper concentrate serving North American gigafactories. |
| Long-term Supply Agreement with OEMs | Locks in offtake with Tesla, BMW, and Volkswagen Group disintermediating trading intermediaries. |
Study Parameters
Initial hypotheses were tested against primary input from HPAL plant managers, cathode-active-material procurement leads at Korean and Chinese cell makers, Indonesian mining ministry officials, and Chilean project finance directors and refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation across SEC 10-K filings from diversified mining houses, Indonesian trade ministry export permit databases, EU Battery Regulation implementation guidance, and Chilean environmental impact assessment records. Bottom-up project-level capacity builds and top-down demand-side cathode chemistry forecasts were cross-referenced for convergence.
Variance decomposition across the projection horizon isolates demand sensitivity to EV penetration rates, supply sensitivity to Indonesian energy cost trajectories, and policy sensitivity to EU Battery Regulation enforcement timing. Segmentation dimensions modeled span product type purity grade, application end-use intensity, end user procurement sophistication, and form factor processing economics. CAGRs were derived from installed capacity build schedules weighted by project financing closure probability and cathode chemistry market share evolution. Industry-specific inputs include HPAL engineering contractor availability and DRC artisanal mining disruption frequency.
The analysis sits within stated boundaries; outcomes outside sustained EV sales growth, Indonesian downstream policy continuity, or EU regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions on cathode chemistry market share evolution and Indonesian energy subsidy phase-out trajectories. Revision becomes warranted when DRC supply disruption frequency or EU carbon-intensity threshold stringency crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Hot Rolled Coil Steel Market
Metals
Global Oxygen-Free Copper Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Global Vanadium Market
Metals
Silver-Platinum Paste Market
Metals
Steel Long Products Market
Metals
Medical Metal Tubing Market
Metals
Global Galvanized Steel Wire Market
Metals
Beryllium Copper Plate Market
Metals
United States Metal Casting Market
Metals
GCC Aluminium Powder Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Aluminum Welding Market
Metals
Beryllium Market
Metals
Copper Wire Market
Metals
Global Tool Steel Market