
 Aluminum Flat-Rolled Products Market | 2026-2036
Aluminum Flat-Rolled Products Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Flat-Rolled Products Market Analysis
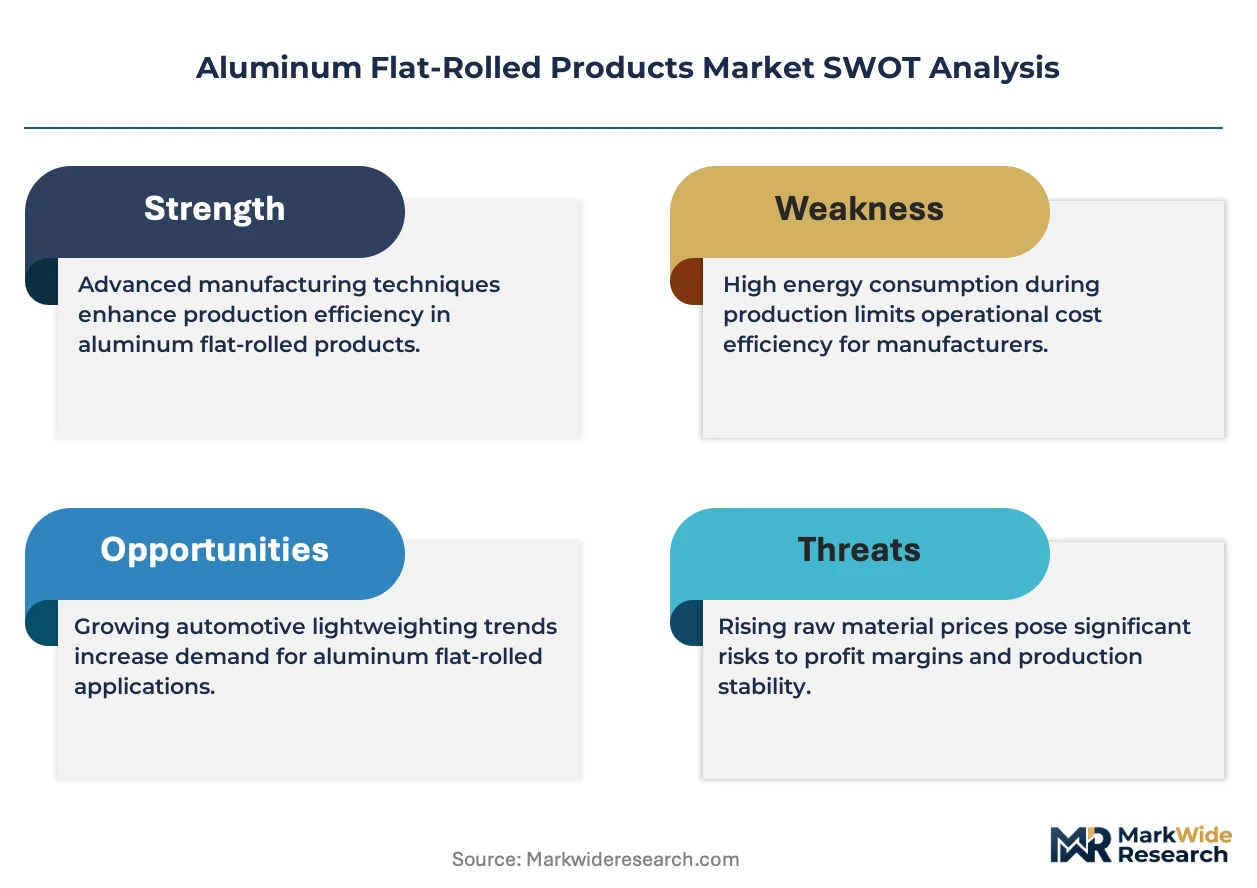
Multi-source supply arrangements for aerospace-grade plate is consolidating around integrated producers with captive melt capacity. Novelis leverages its closed-loop recycling network to secure prime scrap flows for automotive sheet. Hindalco anchors South Asian supply through backward integration into alumina and smelting. Kaiser Aluminum specializes in heat-treatable alloys for defense and commercial aerospace applications.
Aluminum flat-rolled products are semi-finished mill forms produced by continuous casting or direct-chill casting followed by hot and cold rolling, typically ranging from 0.2 mm foil to 150 mm plate depending on gauge requirements, serving primarily as lightweight structural and barrier materials across transport and packaging systems. Sheets dominate value contribution in automotive closure panels and aircraft skins where gauge uniformity and surface quality command premium positioning. Coils represent the fastest-expanding format as EV manufacturers adopt rolled aluminum for battery tray extrusions and cooling plates. Plates retain mature, high-margin positions in aerospace wing rib and bulkhead applications where certification barriers limit supplier entry.
The US FAA and NHTSA enforce alloy traceability and crashworthiness standards that elevate qualification costs for new mill entrants. The EU's REACH framework and F-Gas Regulation constrain rolling lubricant chemistries and annealing atmospheres, favoring capital-intensive abatement investments by incumbent producers. China's GB standards and MIIT energy-intensity mandates accelerate consolidation among smaller rolling mills. Stakeholders must monitor evolving battery-pack architecture standards and carbon-accounting rules that will determine scrap-sourcing economics and regional mill competitiveness.
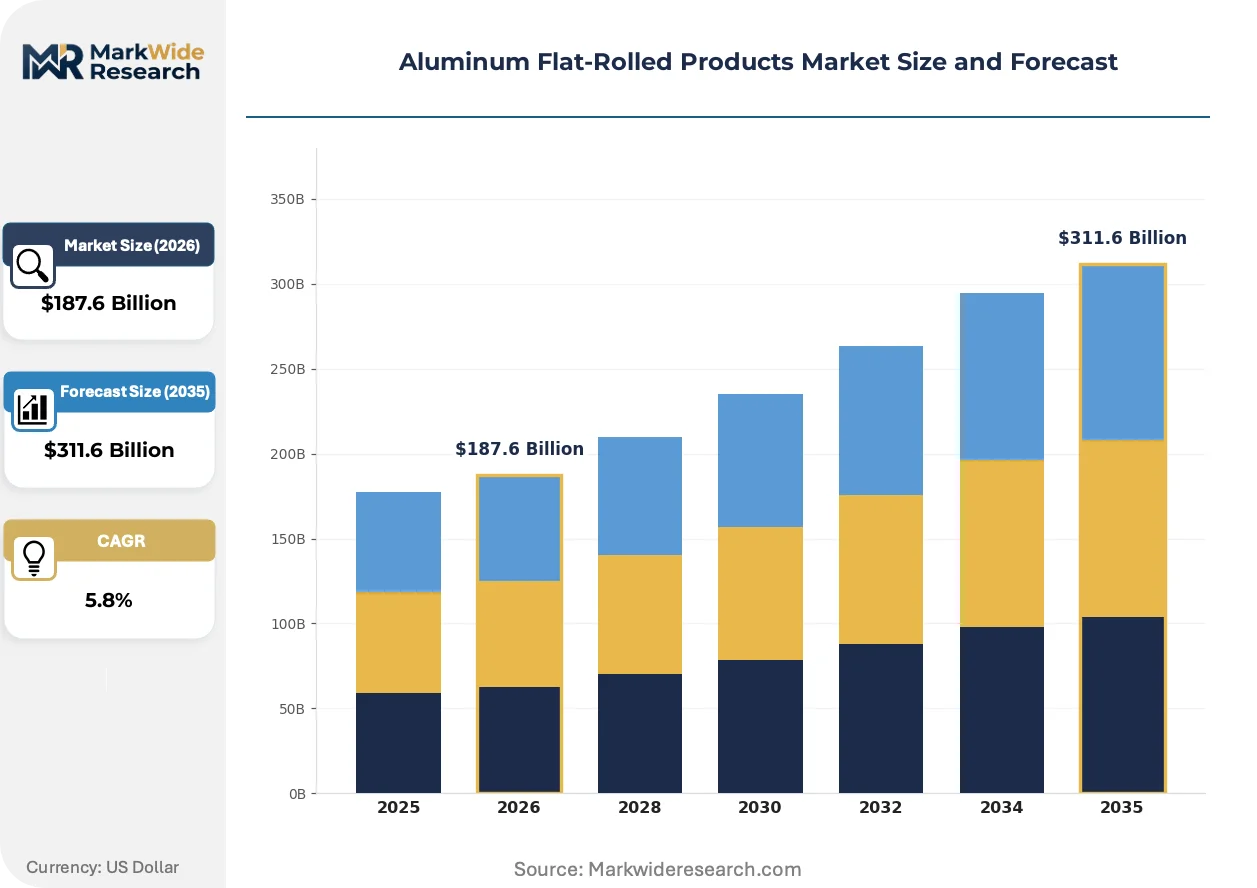
Market Dynamics
Fleet efficiency mandates and battery-pack architecture standardization are compressing qualification timelines for automotive-grade sheet while concentrating supply among mills with captive melt capacity and closed-loop scrap networks.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:European mills are accelerating scrap-recycling investments to preserve export competitiveness against carbon-adjusted imports from third-country suppliers.
- EV thermal management systems:Thin-gauge coil demand from battery housing manufacturers is expanding rolling capacity for high-strength 6xxx series alloys with enhanced formability.
- Automotive OEM body sheet programs:Closure panel specifications are shifting from steel to aluminum-intensive architectures to meet corporate average fuel economy targets.
Market Restraints
- Alumina and primary aluminum price volatility:Input cost swings compress rolling margins and deter long-term contract pricing for non-integrated producers.
- Chinese coil supply concentration:Geographic dependence on single-origin thin-gauge supply creates vulnerability to export duty adjustments and shipping disruptions.
- REACH lubricant constraints:Rolling oil chemistry restrictions under EU F-Gas Regulation require capital-intensive abatement retrofits that disadvantage smaller European mills.
Strategic Opportunities
- Underpenetrated aerospace maintenance:India and Southeast Asian MRO facilities are expanding plate consumption for structural repair programs outside traditional OEM supply chains.
- Regulatory tailwind from IRA domestic content:US clean vehicle tax credits are incentivizing North American melt-and-roll capacity for battery enclosure substrates.
- Closed-loop recycling convergence:Digital scrap tracking and AI-driven alloy sorting are enabling prime-grade recovery rates previously achievable only through primary metal.
Industry Challenges
- Aerospace alloy certification timelines:FAA and EASA qualification protocols for new heat-treatable chemistries extend development cycles beyond typical capital planning horizons.
- Skilled rolling engineer scarcity:Specialized expertise in gauge control and flatness optimization for thin automotive sheet is concentrating at legacy mill sites with apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Flat-Rolled Products Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Sheets, Coils, Foils End User: Aerospace, Automotive, Construction, Packaging Thickness: Thin, Medium, Thick, Extra Thick Finish Type: Brushed, Anodized, Painted, Mill Finish |
| Companies Covered | Constellium SE, UACJ Corporation, Novelis Inc., Kaiser Aluminum Corporation, Arconic Corporation, Hindalco Industries Limited, Norsk Hydro ASA, JW Aluminum, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Flat-Rolled Products Market Emerging Trajectories
Digital process control and alloy design automation are compressing development cycles while regulatory carbon accounting is redefining scrap sourcing economics across integrated mill networks.
Continuous strip casting for automotive body sheet is modularizing production layouts by eliminating ingot casting and hot rolling stages. Tier-1 suppliers in Germany and the US Midwest are piloting these compact lines for just-in-time delivery to stamping plants. The technology is modularizing capital deployment decisions, allowing regional mini-mills to challenge integrated producers on logistics rather than scale.
EU F-Gas Regulation amendments are phasing down hydrofluorocarbon-based rolling lubricants and annealing atmosphere chemistries. European mills are retrofitting vacuum annealing and synthetic lubricant systems at costs exceeding standard maintenance cycles. Heat-treatable plate producers serving aerospace wing rib applications face the steepest compliance burden due to stringent surface cleanliness specifications.
Long-term offtake agreements are displacing spot market purchases among EV battery tray manufacturers seeking alloy traceability for carbon disclosure requirements. Korean and Japanese cell producers are consolidating supplier panels to three qualified mills per region. This concentration is most visible in the US Southeast where new vehicle assembly plants are co-locating with dedicated rolling mill investments.
Aluminum Flat-Rolled Products Market Segmentation
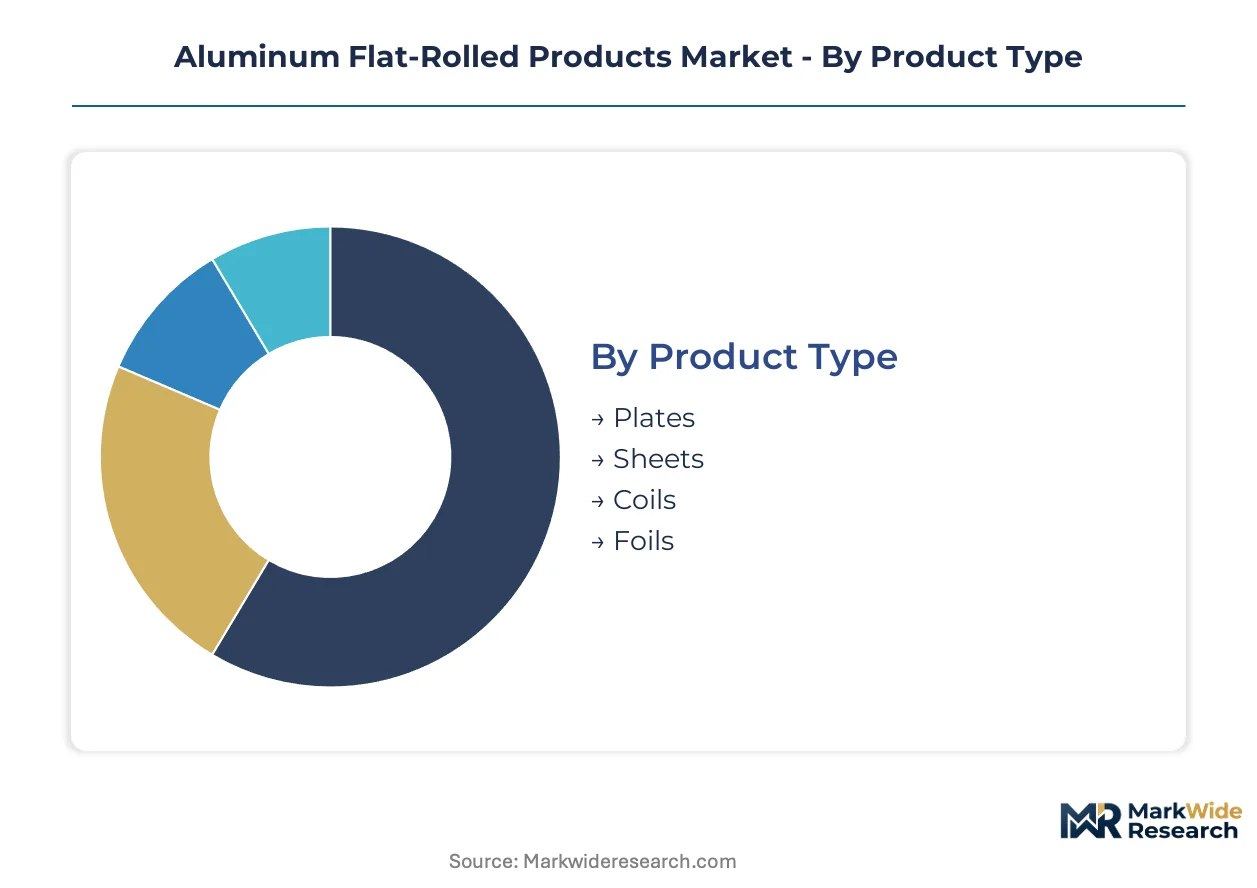
Segmentation in aluminum flat-rolled products reveals how technical specifications and end-use requirements fragment supply chains. Product geometry, customer certification demands, and surface finish standards each create distinct competitive arenas with divergent margin profiles and capital intensity.
Product Type:
Buyers differentiate primarily by downstream forming requirements and structural load-bearing needs.
- Sheets:Flat-rolled products between 0.2 mm and 6.35 mm thickness deliver gauge uniformity critical for automotive closure panels and aircraft skins. OEM body sheet programs in Germany and the US Midwest concentrate demand among mills with continuous annealing lines and surface treatment capability. Premium positioning depends on coil-to-coil consistency for laser-welded blanking operations.
- Coils:Wound continuous strip enables high-speed stamping and roll-forming operations. EV battery tray manufacturers in South Korea and Japan are consolidating supply panels to three qualified mills per region, driving qualification timelines for high-strength 6xxx series alloys with enhanced formability for cooling plate applications.
- Plates:Thick flat-rolled products exceeding 6.35 mm serve wing ribs, bulkheads, and heavy structural applications. FAA and EASA certification barriers limit supplier entry to legacy mills with captive melt capacity and established heat-treatment protocols.
- Foils:Ultra-thin products below 0.2 mm function as barrier materials in pharmaceutical and food packaging. Rolling mills in China dominate thin-gauge supply for thermal management systems and battery separator substrates.
Sheets lead volumes today; coils are gaining share fastest.
End User:
Customer concentration varies sharply by certification burden and contract duration.
- Automotive:Body-in-white and battery enclosure applications demand alloy traceability for carbon disclosure requirements. Fleet efficiency mandates are compressing qualification timelines for closure panel specifications shifting from steel to aluminum-intensive architectures.
- Aerospace:Wing skins, fuselage panels, and structural ribs require heat-treatable alloys with documented pedigree. Long-term offtake agreements predominate given FAA and NHTSA enforcement of crashworthiness standards that elevate qualification costs for new mill entrants.
- Construction:Building facade and roofing applications prioritize cost efficiency over alloy sophistication. Distribution runs through regional service centers with slitting and cut-to-length capability.
- Packaging:Beverage can body stock and end tab stock represent high-volume, thin-gauge consumption. Closed-loop recycling networks secure prime scrap flows to maintain alloy consistency for food-contact applications.
Automotive commands the steepest expansion trajectory; aerospace retains the highest margin position.
Thickness:
Gauge selection determines rolling mill configuration and capital recovery economics.
- Thin:Below 1 mm gauges serve foil laminates and battery separator substrates. Chinese producers dominate this supply tier for EV battery housings where thermal conductivity requirements favor high-purity alloys.
- Medium:1-6 mm range captures automotive body sheet and general fabrication demand. Continuous strip casting technology is modularizing production layouts by eliminating ingot casting stages for just-in-time delivery.
- Thick:6-25 mm plates support structural fabrications and mold tooling. Heat-treatable plate producers face steep EU F-Gas Regulation compliance burdens due to stringent surface cleanliness specifications.
- Extra Thick:Above 25 mm products serve heavy industrial and defense applications. Limited mill capacity and extended lead times create supply bottlenecks during defense procurement cycles.
Medium thickness generates highest throughput today; thin gauges are climbing the fastest.
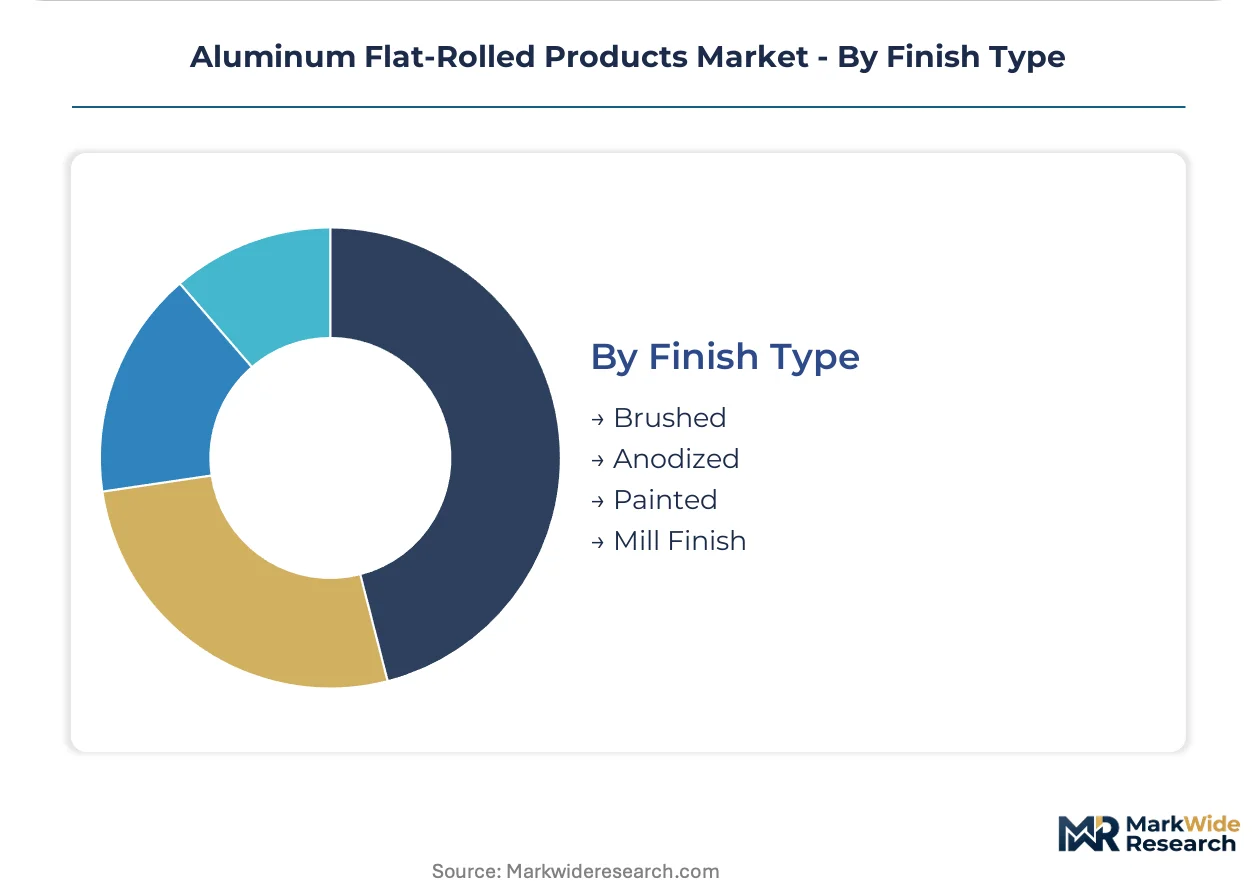
Finish Type:
Surface treatment intensity correlates with aesthetic exposure and corrosion performance requirements.
- Mill Finish:As-rolled surfaces without secondary treatment satisfy internal structural and industrial applications. Lowest cost position supports commodity construction and fabrication segments.
- Anodized:Electrochemical oxide layers enhance corrosion resistance and dye absorption for architectural exposed surfaces. European mills are retrofitting vacuum annealing systems to meet REACH framework constraints on rolling lubricant chemistries.
- Painted:Coil coating lines apply organic finishes for building products and appliance panels. Color consistency requirements favor integrated producers with in-house coating capability.
- Brushed:Mechanical surface texturing creates decorative finishes for consumer electronics and architectural accents. Niche volume commands premium positioning through specialized slitting and handling protocols.
Mill finish dominates tonnage today; anodized treatments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr Valley's integrated aluminum rolling cluster anchors European supply for automotive and aerospace applications, with melt-and-roll capacity concentrated around Duisburg and Essen.
Germany
Automotive OEM body sheet programs in Stuttgart and Munich drive demand for closure panel substrates. The EU F-Gas Regulation forces vacuum annealing retrofits at rolling mills serving wing rib applications. The Ruhr Valley concentration around Duisburg maintains captive melt capacity for just-in-time delivery to stamping plants.
United States
EV battery tray manufacturers in the Southeast are consolidating supply panels to three qualified mills per region. The IRA domestic content provisions incentivize North American melt-and-roll investments for clean vehicle tax credits. The Kentucky-Tennessee corridor hosts new rolling mill investments co-located with vehicle assembly plants.
China
Thin-gauge coil demand from battery housing manufacturers expands rolling capacity for high-strength 6xxx series alloys. MIIT energy-intensity mandates accelerate consolidation among smaller rolling mills in Shandong and Henan provinces. The Yangtze River Delta cluster dominates supply for thermal management systems.
Japan
Heat-treatable plate consumption for commercial aerospace applications concentrates demand among legacy mills with established qualification protocols. METI industrial policy supports closed-loop recycling networks for prime scrap recovery. The Nagoya aerospace cluster maintains specialized gauge control expertise for thin automotive sheet.
India
MRO facilities in Bangalore and Hyderabad expand plate consumption for structural repair programs outside traditional OEM supply chains. BIS standards enforcement elevates qualification barriers for imported coil specifications. Hindalco anchors South Asian supply through backward integration into alumina and smelting operations in Odisha.
Aluminum Flat-Rolled Products Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular strip-casting technology to challenge on logistics rather than scale. The vendor base concentrates among integrated mills with captive melt capacity and closed-loop scrap networks. Three archetypes dominate: aerospace-certified plate specialists, automotive body sheet suppliers with continuous annealing lines, and packaging-focused recyclers with food-contact certification. Competitive moves center on strategic partnerships for battery enclosure offtake agreements and geographic expansion into Southeast Asian MRO markets.
Within the integrated multinational tier, Novelis Inc. and Hindalco Industries Limited exemplify closed-loop recycling convergence, while Kaiser Aluminum Corporation occupies a position among heat-treatable alloy specialists. Constellium SE and Arconic Corporation represent European and North American aerospace certification incumbents respectively. UACJ Corporation anchors Japanese supply for thin-gauge automotive applications. Norsk Hydro ASA exemplifies Nordic renewable-powered primary metal integration.
| Leading Market Players |
|---|
| Constellium SE |
| UACJ Corporation |
| Novelis Inc. |
| Kaiser Aluminum Corporation |
| Arconic Corporation |
| Hindalco Industries Limited |
| Norsk Hydro ASA |
| JW Aluminum |
| Alcoa Corporation |
| Others |
Supply Flow & Price Mechanics
Automotive OEM consolidation of supplier panels to three qualified mills per region is forcing capacity investments that compress rolling margins and elevate contract pricing power among integrated producers with captive melt operations.
Pricing Analysis
Alumina and primary aluminum price volatility passes through to rolling margins via long-term offtake agreements that predominate in automotive and aerospace segments. Three-tier pricing structure across aerospace-certified plate, automotive body sheet, and commodity construction grades reflects certification burden and surface finish intensity. Cost compression in thin-gauge coil runs through Chinese export duty exposure and shipping disruption vulnerability. Packaging recyclers with food-contact certification exhibit lowest price sensitivity; construction distributors through regional service centers show highest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese thin-gauge coil dominance for EV battery housings and thermal management substrates. Primary aluminum smelting concentrates in China, Russia, and the GCC; rolling capacity clusters in Germany, the US, and Japan. The network draws from alumina refineries in Australia and Guinea, rolling lubricant chemistries constrained by EU F-Gas Regulation, and scrap flows captured by closed-loop recycling networks. Tariff exposure on carbon-adjusted imports under the EU Carbon Border Adjustment Mechanism threatens European mill competitiveness. Distribution runs through Tier-1 supplier consolidation and just-in-time delivery to vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon-adjusted import costs and US IRA domestic content incentives for North American melt-and-roll investments.
For Market Incumbents: Anticipate Chinese MIIT consolidation mandates and EU F-Gas retrofit requirements by securing captive scrap networks and vacuum annealing capacity. Defensive moves center on heat-treatable alloy certification deepening at legacy aerospace sites and continuous annealing line expansion in the US Southeast co-located with OEM assembly plants. Vertical integration into alumina refining insulates margin pressure from LME volatility. For New Entrants and Emerging Players: The IRA domestic content provisions in the United States open a window for modular strip-casting technology deployment in the Kentucky-Tennessee corridor. White-space targets include India MRO plate supply outside traditional OEM chains and Southeast Asian battery tray substrate qualification. Go-to-market positioning leverages logistics proximity over scale economics for just-in-time stamping plant delivery. For Investors and Strategic Acquirers: Asymmetric upside sits with closed-loop recycling specialists with prime scrap recovery rates matching primary metal quality. Long-term viability over a decade hinges on carbon-accounting rule convergence determining scrap-sourcing economics. Acquisition targets include heat-treatable plate mills with dormant FAA qualification protocols and automotive sheet producers with underutilized continuous annealing lines. The inflection signal to monitor is battery-pack architecture standardization timelines compressing qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Network Expansion | Novelis leverages captive scrap flows to secure prime-grade automotive sheet supply against primary metal volatility. |
| Continuous Strip Casting Deployment | German and US Midwest Tier-1 suppliers pilot modular lines eliminating ingot casting for just-in-time delivery. |
| Vacuum Annealing Retrofit Investment | European mills serving aerospace wing rib applications absorb F-Gas compliance costs exceeding standard maintenance cycles. |
| Long-Term Offtake Agreement Consolidation | Korean and Japanese cell producers narrow supplier panels to three qualified mills per region for carbon traceability. |
| Backward Integration into Alumina Refining | Hindalco anchors South Asian supply through captive bauxite and smelting operations in Odisha. |
Methodological Framework
Multiple input streams — executive interviews with rolling mill operations directors, procurement leads at automotive OEMs, aerospace certification engineers, and secondary validation against customs trade data, SEC filings from integrated aluminum producers, MIIT energy-intensity disclosures, and FAA qualification registries — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product geometry, end-use certification demands, surface finish standards, and regional production hub economics shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups and value-chain margin analysis. Forecast inputs incorporated EV battery pack architecture adoption curves, EU Carbon Border Adjustment Mechanism implementation phases, and closed-loop recycling penetration rates by region.
Revisions become necessary when battery-pack standardization timelines shift, carbon-accounting methodologies change, or trade policy alters scrap flow economics. Forecasts reflect documented assumptions about qualification protocol durations and OEM body sheet program commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Wire Market
Metals
Potassium Platinochloride Market
Metals
North America Aluminium Powder Market
Metals
Global Tantalum Market
Metals
Copper and Copper Alloy Foil Market
Metals
US Ferrochrome Market
Metals
Metallurgical Coal Market
Metals
North America Electrical Steel Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Global Welding Powder Market
Metals
Precious Metals Wire Market
Metals
Armour Steel Plate Market
Metals
Heat-Treated Steel Plates Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Titanium Market
Metals
Global Ultra Fine Copper Powder Market