
 Ion Implanter Market | 2026-2036
Ion Implanter Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Implanter Market Intelligence
Silicon carbide is consolidating as the substrate material displacing conventional silicon in power semiconductor ion implantation, altering chamber design and beam energy specifications across tool portfolios. Applied Materials Inc leverages vertical integration in ion source manufacturing to control critical component supply. Axcelis Technologies Inc anchors its position through extreme high-energy systems tailored for silicon carbide power device fabrication. Sumitomo Heavy Industries Ltd competes via precision mechanical scanning platforms optimized for compound semiconductor wafer formats.
An ion implanter accelerates dopant ions to precise kinetic energies between 1 keV and several MeV, electrostatically steering them into semiconductor substrates to modify electrical conductivity at controlled depths and concentrations. Medium-energy implanters occupy the largest installed base across mainstream logic foundries, while high-energy systems capture the fastest expansion as silicon carbide and gallium nitride power devices require deep junction formation. Electrostatic implanters dominate technology selection for sub-10nm node precision, whereas plasma immersion systems are gaining traction in memory manufacturers seeking higher throughput for three-dimensional architectures.
The US FDA regulates ion implanter safety through radiation-emitting device standards, while EPA hazardous waste rules govern spent source material disposal protocols. China's NMPA and MIIT jointly enforce domestic equipment certification and GB standards compliance for imported semiconductor capital tools. Japan's METI coordinates JIS standards alignment with export control frameworks affecting ion source technology transfer. Stakeholders must monitor evolving multilateral semiconductor equipment export restrictions and their cascading effects on spare parts logistics and field service accessibility.
Market Dynamics
Node migration below 7nm is compressing doping tolerance windows to atomic-scale precision, forcing simultaneous upgrades to beamline stability, metrology integration, and chamber contamination control across installed tool bases.
Growth Catalysts
- China's MIIT domestic substitution mandates:Procurement quotas redirect capital equipment budgets toward NMPA-certified local vendors, accelerating qualification cycles for indigenous ion implanter platforms.
- Silicon carbide power device fabrication:Electric vehicle traction inverters and renewable energy converters require deep junction formation at 300-500 keV, expanding the addressable tool population for extreme high-energy systems.
- Taiwan's Hsinchu Science Park cluster density:TSMC and United Microelectronics coordinate synchronized capacity expansions, creating concentrated demand spikes for matched beamline configurations.
Market Restraints
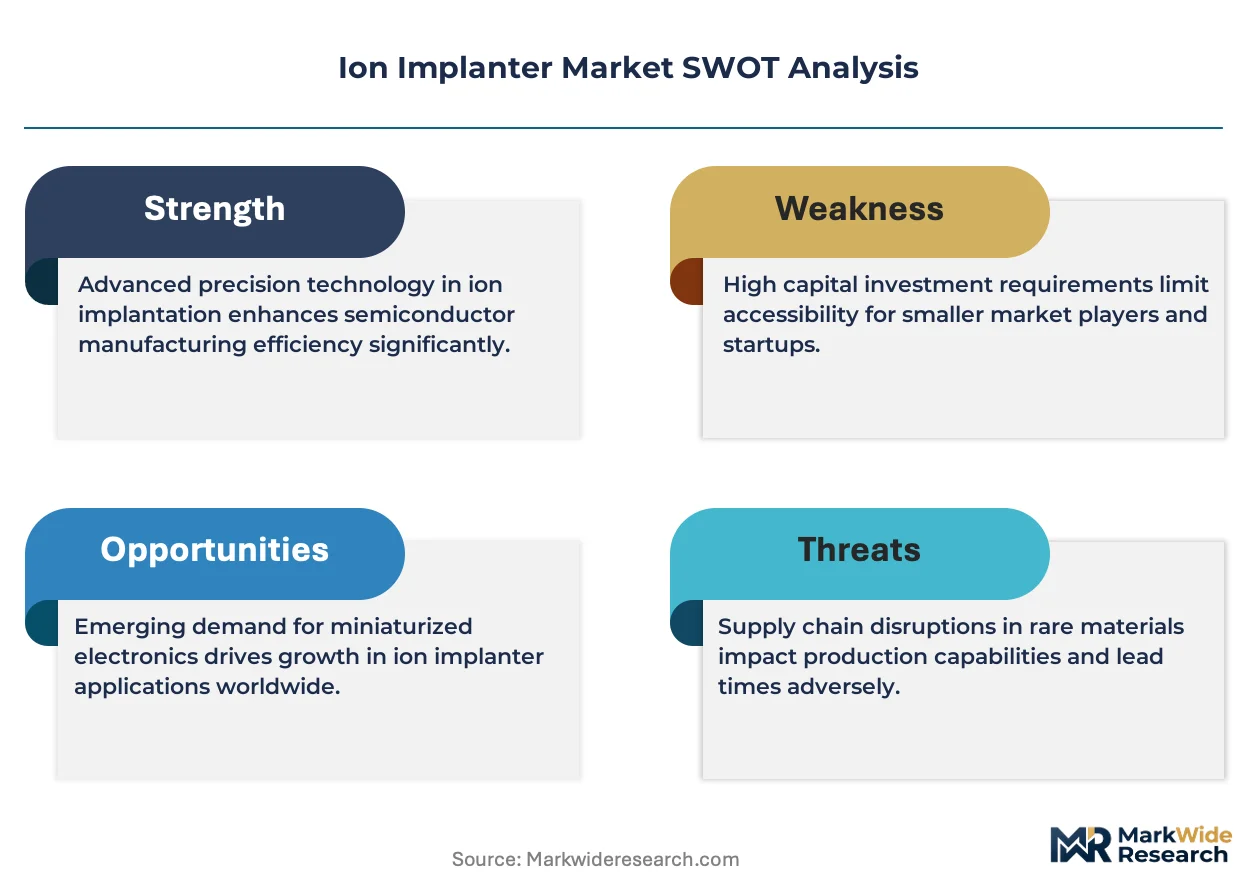
- Tungsten filament supply concentration:Ion source cathode manufacturing clusters in specific East Asian jurisdictions create single-point vulnerability for beam current stability.
- EPA hazardous waste disposal protocols:Spent arsenic and phosphorus source material handling adds recurring compliance overhead and site certification delays.
- Plasma immersion doping substitution:Memory manufacturers evaluating three-dimensional NAND architectures increasingly bypass conventional beamline systems for conformal doping coverage.
Strategic Opportunities
- India's PLI scheme for semiconductor manufacturing:Greenfield fab commitments in Gujarat and Karnataka create first-mover positioning for tool vendors establishing local service infrastructure.
- Gallium nitture RF device integration:5G base station power amplifiers and radar modules require compound semiconductor implantation protocols distinct from silicon-centric tool configurations.
- Outcome-based service contracting:Foundry operators seek guaranteed uptime agreements with predictive maintenance analytics, shifting revenue mix toward recurring service streams.
Industry Challenges
- Ion optics engineering talent scarcity:Beam transport modeling and electrostatic lens design expertise concentrates among retiring cohorts at national laboratories and legacy equipment suppliers.
- Legacy tool integration complexity:Sub-10nm precision requirements expose mechanical scanning platform limitations in 200mm-era installed bases, forcing costly retrofit versus replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Implanter Market |
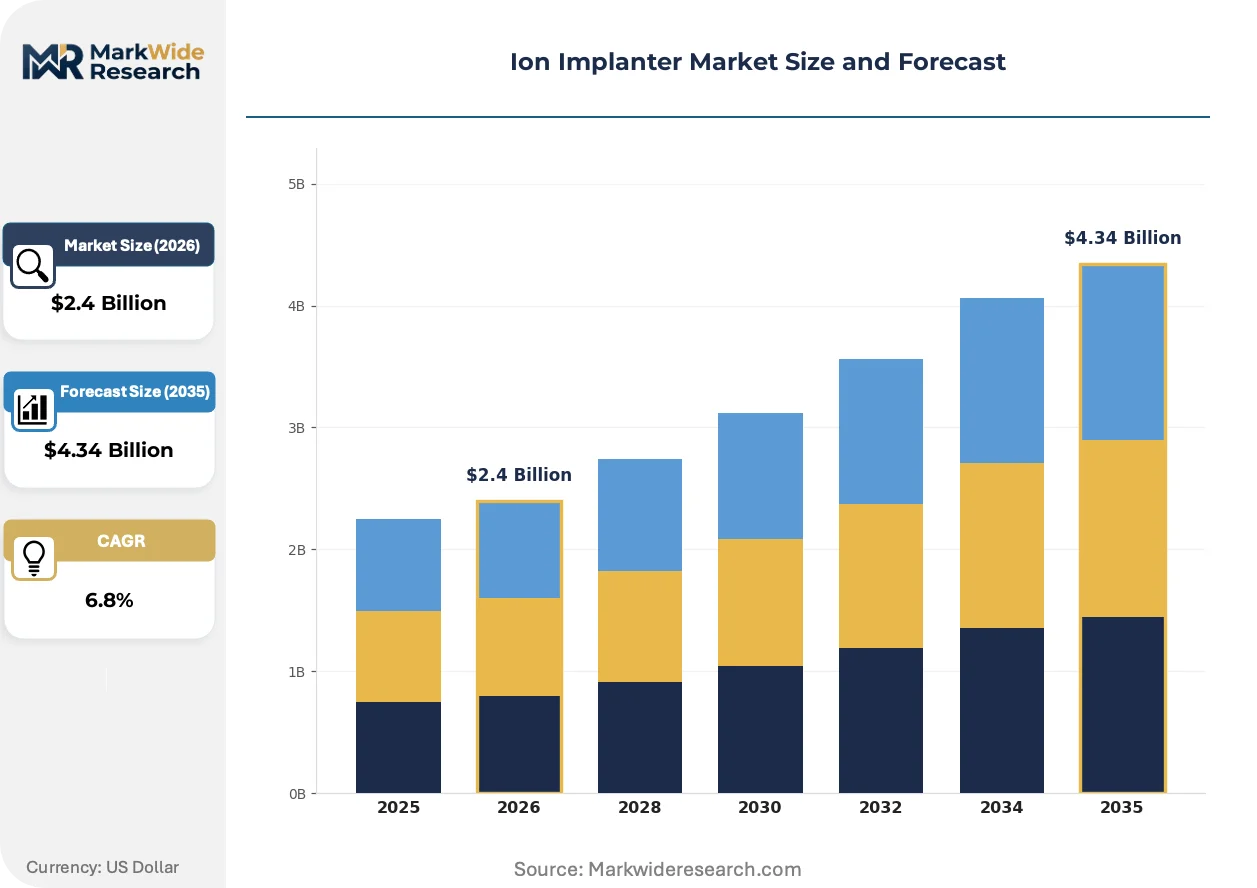
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Energy Implanters, Medium-Energy Implanters, Low-Energy Implanters, Vertical Implanters End User: Semiconductor Manufacturers, Solar Cell Producers, Research Institutions, Electronics Firms Technology: Electrostatic Implanters, Mechanical Implanters, Plasma Immersion Systems, Hybrid Systems Application: Wafer Fabrication, Device Doping, Thin Film Deposition, Substrate Modification |
| Companies Covered | Applied Materials Inc, Axcelis Technologies Inc, Sumitomo Heavy Industries Ltd, Nissin Ion Equipment Co. Ltd, ULVAC Inc, Intevac Inc, Ion Beam Services SA, Advanced Ion Beam Technology Inc, Kingstone Semiconductor Joint Stock Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Implanter Market Strategic Shifts & Innovations
Beamline architectures are fragmenting across application-specific configurations as compound semiconductor substrates diverge from silicon process flows, while regulatory certification frameworks proliferate in parallel with geopolitical equipment trade restrictions.
Single-wafer electrostatic scanning platforms are converging with in-situ angle-resolved mass spectrometry for real-time dose verification. Leading-edge logic foundries deploy these hybrid systems for sub-5nm transistor threshold voltage control. The convergence is compressing process development cycles from months to weeks by eliminating offline metrology bottlenecks.
Japan's METI coordinates JIS standards alignment with export control frameworks affecting ion source technology transfer. Domestic suppliers face expanded documentation requirements for tungsten cathode and arc chamber subassemblies. Equipment vendors are responding by regionalizing component sourcing and accelerating alternative emitter material qualification.
Foundry procurement teams now unbundle after-sales service contracts from capital equipment purchases, competitively tendering maintenance and spare parts logistics separately. Original equipment manufacturers resist margin compression through proprietary diagnostics software lock-in. This tension is most visible in Taiwan's Hsinchu cluster, where multi-vendor tool populations complicate unified fleet management.
Ion Implanter Market Segmentation
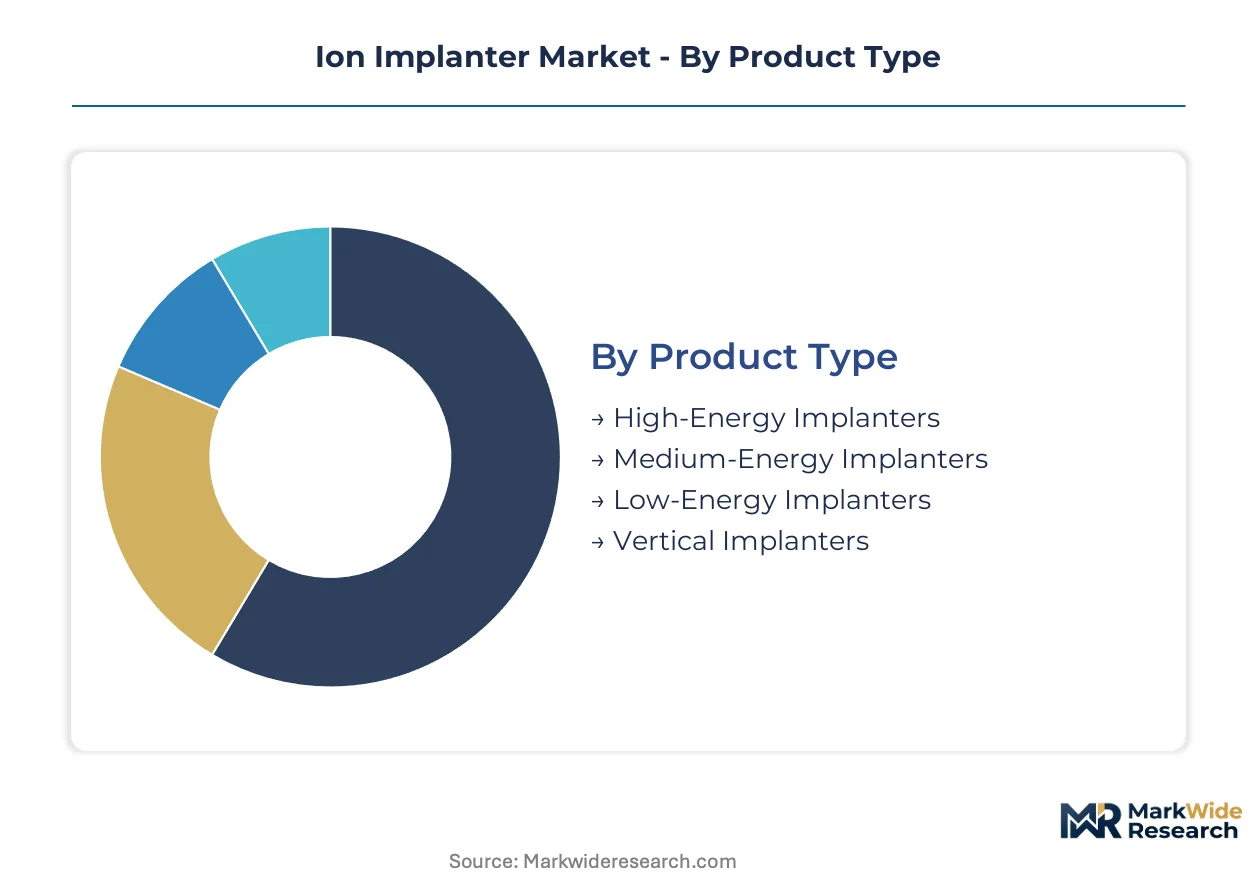
Ion implanter procurement patterns diverge sharply across customer archetypes, with foundry operators prioritizing beamline precision for sub-7nm nodes while power semiconductor fabricators optimize for deep-junction throughput at elevated energies. Technology selection further stratifies the installed base, as electrostatic platforms command premium positioning in leading-edge logic while plasma immersion alternatives capture memory sector volume.
Product Type:
Capital allocation intensity separates buyers in this category, with power device manufacturers committing disproportionately to extreme high-energy systems while mainstream logic foundries balance medium-energy fleet expansion against selective low-energy upgrades.
- High-Energy Implanters:Beamline systems accelerate dopant ions to 300 keV and above, enabling deep junction formation in silicon carbide substrates. Demand concentrates among electric vehicle traction inverter suppliers in Taiwan's Hsinchu cluster, driven by 800V platform proliferation requiring thicker drift layers.
- Medium-Energy Implanters:These platforms operate between 10-200 keV, serving as the workhorse configuration for mainstream CMOS logic fabrication. TSMC and United Microelectronics anchor procurement in this segment, with node migration below 7nm compressing tolerance windows for threshold voltage control.
- Low-Energy Implanters:Sub-10 keV systems address ultra-shallow junction requirements for advanced transistor architectures.
- Vertical Implanters:Compact footprint configurations target research institutions and pilot line operations with constrained cleanroom space.
Medium-energy systems lead volumes today; high-energy platforms are gaining share fastest.
End User:
Volume concentration and technical sophistication create distinct procurement profiles, with semiconductor manufacturers driving specification standards while adjacent sectors adopt trailing-edge configurations.
- Semiconductor Manufacturers:Logic and memory foundries impose the most stringent beam stability and contamination control requirements. Capital equipment budgets from TSMC, Samsung, and Intel dominate order flow, with synchronized capacity expansions creating demand spikes for matched beamline configurations.
- Solar Cell Producers:Crystalline silicon photovoltaic manufacturers deploy medium-energy systems for emitter formation and back surface field doping. Chinese producers under MIIT domestic substitution mandates increasingly source NMPA-certified local platforms.
- Research Institutions:National laboratories and university cleanrooms prioritize flexibility over throughput for process development.
- Electronics Firms:Discrete component and sensor manufacturers represent fragmented, price-sensitive demand.
Semiconductor manufacturers command absolute revenue share; solar cell producers show steepest expansion trajectory.
Technology:
Precision requirements versus throughput economics define competitive positioning, with electrostatic platforms capturing leading-edge logic premiums as mechanical alternatives defend installed base economics.
- Electrostatic Implanters:Electrostatic lens arrays enable sub-nanometer placement accuracy for sub-10nm node fabrication. Logic foundries in Taiwan and South Korea concentrate procurement here, with real-time angle-resolved mass spectrometry integration emerging as a differentiating feature.
- Mechanical Implanters:Precision scanning platforms from Japanese suppliers anchor compound semiconductor wafer processing. Sumitomo Heavy Industries competes via optimized mechanical stages for gallium nitride and silicon carbide formats.
- Plasma Immersion Systems:Conformal doping coverage attracts three-dimensional NAND memory evaluations seeking higher throughput.
- Hybrid Systems:Combined electrostatic-mechanical architectures target mid-range flexibility requirements.
Electrostatic platforms dominate value capture; plasma immersion alternatives are climbing the fastest.
Application:
Process integration depth determines tool configuration complexity, with front-end wafer fabrication demanding the most sophisticated beamline architectures.
- Wafer Fabrication:Front-end doping operations in 300mm logic fabs require the highest beam current stability and metrology integration. Taiwan's Hsinchu Science Park cluster anchors global demand concentration, with TSMC's node roadmaps dictating specification evolution.
- Device Doping:Discrete power semiconductor and RF device fabrication employs specialized protocols for compound substrates. Silicon carbide traction inverter suppliers drive high-energy system requirements for deep junction formation.
- Thin Film Deposition:Ion beam-assisted deposition applications serve optical coating and magnetic storage sectors.
- Substrate Modification:Surface property alteration for MEMS and sensor applications represents niche demand.
Wafer fabrication commands the largest installed base; device doping for power electronics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors the densest ion implanter installed base globally, with synchronized capacity expansions by TSMC and United Microelectronics creating concentrated demand spikes. The United States, South Korea, Japan, and China each host distinct regulatory and procurement ecosystems shaping tool vendor strategies.
Taiwan
TSMC and United Microelectronics drive procurement for sub-7nm logic fabrication, compressing doping tolerance windows to atomic-scale precision. The National Science and Technology Council coordinates domestic equipment qualification programs under the "Five Plus Two" Industrial Innovation Plan. Hsinchu Science Park's cluster density creates matched beamline configuration requirements across simultaneous fab expansions.
United States
Intel and GlobalFoundries sustain demand for leading-edge electrostatic platforms in Arizona and Oregon fabs. The FDA regulates ion implanter safety through radiation-emitting device standards, while the EPA governs spent arsenic and phosphorus source material disposal protocols. Greater Phoenix's emerging semiconductor corridor attracts high-energy system deployments for silicon carbide power device qualification.
South Korea
Samsung Electronics and SK Hynix anchor memory and logic foundry demand, with three-dimensional NAND architectures evaluating plasma immersion alternatives. The Ministry of Trade, Industry and Energy enforces K-BEAT domestic equipment certification frameworks. Pyeongtaek's semiconductor complex hosts synchronized capacity ramps requiring predictive maintenance analytics integration.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor upstream materials supply, while Sony and Toshiba drive discrete device doping requirements. METI coordinates JIS standards alignment with export control frameworks affecting ion source technology transfer. Kyushu's silicon island hosts compound semiconductor pilot lines requiring precision mechanical scanning platforms.
China
Yangtze Memory Technologies and Hua Hong Semiconductor expand 300mm fab capacity despite equipment import restrictions. NMPA and MIIT jointly enforce domestic equipment certification and GB standards compliance for imported capital tools. Shanghai's Lingang Free Trade Zone hosts qualified local ion implanter assembly operations under domestic substitution mandates.
Ion Implanter Market Key Industry Players
Global majors compete with regional champions across beamline precision and service infrastructure dimensions. The vendor base stratifies into three tiers: integrated materials conglomerates controlling ion source supply, specialized high-energy system architects, and emerging domestic platforms capturing procurement quota redirection. Strategic differentiation centers on vertical integration depth versus geographic proximity to Hsinchu and Pyeongtaek clusters. Consolidation pressure intensifies as foundries unbundle after-sales contracts and competitively tender maintenance separately.
Within the integrated tier, Applied Materials Inc exemplifies upstream control over critical component manufacturing. Axcelis Technologies Inc and Sumitomo Heavy Industries Ltd occupy distinct specialization positions—one anchoring extreme high-energy architectures, the other precision mechanical platforms for compound semiconductor formats. These three represent divergent responses to silicon carbide substrate displacement and electrostatic lens precision requirements.
| Leading Market Players |
|---|
| Applied Materials Inc |
| Axcelis Technologies Inc |
| Sumitomo Heavy Industries Ltd |
| Nissin Ion Equipment Co. Ltd |
| ULVAC Inc |
| Intevac Inc |
| Ion Beam Services SA |
| Advanced Ion Beam Technology Inc |
| Kingstone Semiconductor Joint Stock Co. Ltd |
| Others |
Cost & Logistics Intelligence
Family-owned Japanese precision engineering houses anchor tungsten cathode and arc chamber subassembly production, translating concentrated upstream ownership into disciplined pricing power for ion source components while resisting margin compression from foundry procurement teams unbundling after-sales contracts.
Pricing Analysis
Input-cost pass-through from tungsten filament and specialized ceramic insulator suppliers shapes pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on NMPA certification tier and after-sales service bundling, with NMPA-certified domestic platforms commanding modest premiums over uncertified imports. Cost compression in the economy tier intensifies as memory manufacturers evaluate plasma immersion alternatives, bypassing conventional beamline systems. Solar cell producers under MIIT domestic substitution mandates exhibit highest price sensitivity, while sub-7nm logic foundries prioritize beam stability over unit cost.
Supply Chain Analysis
Workforce availability constraints in Japan's Kyushu region and Taiwan's Hsinchu corridor constrain precision mechanical scanning platform output. Manufacturing concentrates in Japan, Taiwan, and the United States, drawing from specialized tungsten mining operations in specific East Asian jurisdictions and high-purity gas suppliers in South Korea. Single-source vulnerability in tungsten cathode supply creates structural risk for beam current stability. Distribution runs through direct OEM-fab relationships with regional service hubs in Pyeongtaek and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion implanter market functions as a regulatory compounder, with China's NMPA semiconductor equipment certification framework and MIIT domestic substitution mandates accelerating qualification cycles and redirecting procurement flows toward locally qualified tool vendors.
For Market Incumbents: Anchor beamline precision leadership through in-house ion source manufacturing and predictive maintenance analytics integration, defending against emerging domestic platforms capturing procurement quota redirection. Prioritize certification investment in China's NMPA framework and India's PLI scheme jurisdictions to maintain access to fastest-expanding demand clusters. Control critical component supply through captive tungsten cathode production or exclusive supplier arrangements. For New Entrants and Emerging Players: Launch via outcome-based service contracting models targeting India's Gujarat and Karnataka greenfield fab commitments, where first-mover positioning in local service infrastructure remains unclaimed. Target gallium nitride RF device integration for 5G base station power amplifiers, a compound semiconductor application with distinct tool configurations from silicon-centric incumbents. Pursue qualification partnerships with Yangtze Memory Technologies and Hua Hong Semiconductor under China's domestic substitution mandates. For Investors and Strategic Acquirers: Semiconductor materials conglomerates seeking beamline precision capabilities represent the most active acquirer in this space, with consolidation pressure intensifying as foundries competitively tender maintenance separately. Over the projection horizon, target electrostatic lens array specialists and ion optics engineering talent pools concentrated at national laboratories. Watch for NMPA certification milestone acceleration as inflection indicator for domestic platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ion Source Manufacturing | Applied Materials controls critical tungsten cathode supply, insulating beam current stability from East Asian single-point vulnerability. |
| NMPA Certification Pathway Acceleration | Domestic qualification unlocks procurement quotas redirecting capital equipment budgets toward locally certified tool vendors in China. |
| Outcome-Based Service Contracting | TSMC and United Microelectronics seek guaranteed uptime agreements, shifting revenue mix toward recurring predictive maintenance streams. |
| Silicon Carbide Power Device Qualification | Axcelis anchors extreme high-energy system positioning for 800V electric vehicle traction inverter deep junction formation. |
| Regional Service Infrastructure Buildout | Local spare parts logistics in India's PLI scheme jurisdictions addresses field service accessibility gaps for greenfield fab commitments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab equipment procurement directors, ion optics engineering leads, aftermarket service heads, and national laboratory research scientists with secondary validation from SEC 10-K filings, customs trade data, NMPA certification registries, and MIIT domestic equipment procurement bulletins. Bottom-up installed base modeling and top-down capital expenditure triangulation anchored market size estimation.
Segment-weighting approaches distributed value across high-energy, medium-energy, low-energy, and vertical implanter configurations, with further stratification by electrostatic, mechanical, plasma immersion, and hybrid technology platforms across the analysis window. CAGRs derived from node migration timelines, silicon carbide substrate displacement curves, and compound semiconductor adoption patterns in power electronics and RF applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under multilateral semiconductor equipment export restriction escalation and tungsten supply disruption scenarios. Forecasts reflect documented assumptions regarding NMPA qualification velocity, MIIT procurement quota enforcement, and plasma immersion substitution rates in three-dimensional NAND architectures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Epitaxial Wafer Market