
 Modular Inverter Market | 2026-2036
Modular Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Inverter Market Foresight
Aftermarket service revenue is tilting from hardware replacement toward predictive analytics and remote diagnostics. Huawei leverages its digital power platform to anchor service contracts across Asia-Pacific utility installations. SMA sustains European market presence through specialized grid-forming firmware and localized technical support networks. Sungrow competes on manufacturing scale, operating gigawatt-class production lines that control cost curves for central and string inverter platforms.
A modular inverter consists of stackable power conversion units, typically rated between 50 kW and 3.3 MW per module, that parallel-connect to achieve variable output capacity while isolating fault conditions to individual sub-units. The architecture employs silicon carbide or IGBT switching topologies to convert DC photovoltaic or battery input into grid-synchronized AC output with efficiency thresholds exceeding 98.5%. String inverter configurations dominate residential and commercial rooftop segments where installation flexibility and rapid commissioning offset premium unit costs. Utility-scale deployments favor central inverter architectures built from modular sub-assemblies that reduce downtime exposure and enable phased capacity expansion. Hybrid inverter demand is accelerating fastest across energy storage-coupled solar installations, particularly where time-shifting and backup power functions command margin premiums over pure grid-tied alternatives.
FERC Order 2023 interconnection reforms in the United States compress queue timelines for inverter-based resources, directly shaping procurement urgency among independent power producers. IEC 62109 and UL 1741-SA certification requirements enforce ride-through and grid-support functionality that filter non-compliant suppliers from utility-tier vendor lists. Stakeholders must monitor evolving IEEE 1547-2018 revision timelines and corresponding state-level implementation gaps that determine product qualification windows across North American territories.
Market Dynamics
Silicon carbide power semiconductors are compressing thermal management costs and enabling higher switching frequencies that redefine modular inverter power density benchmarks across utility-scale solar and storage hybrids.
Growth Catalysts
- FERC Order 2023:Interconnection queue reforms in the United States compress approval timelines for inverter-based resources, accelerating procurement cycles among independent power producers in Texas and California.
- Utility-scale solar farms:Phased capacity expansion models favor stackable architectures that isolate faults to individual sub-units, reducing downtime exposure during maintenance windows.
- Silicon carbide switching topologies:Wide-bandgap devices cut switching losses below IGBT thresholds, enabling compact thermal designs that slash balance-of-system costs for containerized power conversion skids.
Market Restraints
- IGBT supply concentration:Discrete power module fabrication clusters in East Asian foundries expose procurement timelines to geographic concentration risk during capacity allocation cycles.
- UL 1741-SA certification timelines:Extended test protocols for grid-support functionality filter non-compliant suppliers from utility-tier vendor lists, elongating product qualification windows.
- String inverter substitution:Residential and commercial rooftop segments favor fixed-capacity units where installation flexibility offsets modular premiums, capping addressable market expansion below 500 kW.
Strategic Opportunities
- Energy storage hybrids:Bidirectional power conversion for time-shifting and backup functions commands margin premiums over pure grid-tied alternatives in California and Germany.
- IEC 62109-2 safety certifications:Stringent arc fault detection and isolation requirements create compliance moats for certified suppliers targeting European utility procurement frameworks.
- Remote diagnostics platforms:Predictive analytics contracts displace hardware replacement revenue streams, anchoring recurring service relationships across Asia-Pacific installations.
Industry Challenges
- Firmware engineering scarcity:Grid-forming control algorithms require specialized power electronics expertise that concentrates among legacy European and Japanese engineering teams.
- Legacy SCADA integration:Phased inverter replacements must communicate with existing plant control systems through proprietary protocols, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Inverter Market |
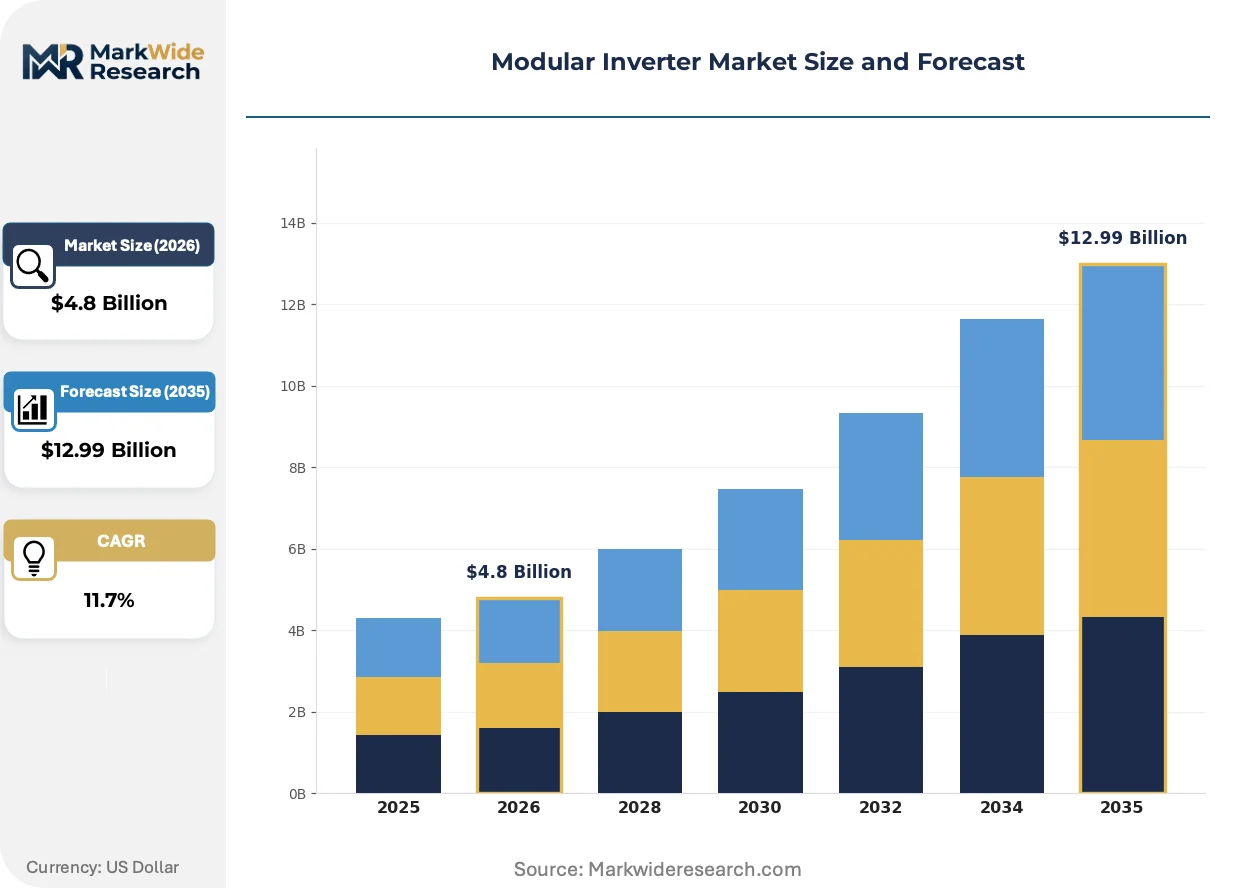
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Inverters, String Inverters, Microinverters, Hybrid Inverters End User: Residential, Commercial, Industrial, Utilities Technology: Solar, Wind, Fuel Cell, Energy Storage Application: Grid-Tied, Off-Grid, Backup Power, Remote Monitoring |
| Companies Covered | Fronius, GoodWe, Sungrow, Enphase, SolarEdge, Huawei, Solis, Gronsol, SMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Inverter Market Shifts & Advancements
Power semiconductor evolution and interconnection standard tightening are compressing product lifecycles while expanding the functional boundary between solar-only and hybrid inverter categories.
Silicon carbide MOSFETs operating above 50 kHz switching frequencies eliminate bulky DC-link capacitors and enable air-cooled thermal designs that previously required liquid cooling loops. Utility-scale developers in Australia and the southwestern United States are specifying SiC-based modular blocks for 1500 VDC string architectures. This transition is rendering obsolete traditional IGBT-based central inverters above 2.5 MW ratings where thermal management costs dominate total installed cost.
IEEE 1547-2018 revision implementation across US state jurisdictions mandates ride-through capabilities and volt-var optimization that legacy grid-tied inverters cannot satisfy. State utility commissions in California, Texas, and New York are enforcing staggered compliance deadlines that filter non-compliant products from interconnection queues. String inverter suppliers targeting residential markets face compressed redesign cycles to maintain eligibility for net metering programs.
Independent power producers are consolidating procurement around vertically integrated suppliers offering bundled hardware, firmware, and long-term service contracts. This concentration displaces component-only vendors who lack commissioning and predictive maintenance capabilities. The shift is most visible in German utility-scale auctions where EPC contractors specify single-source accountability for 20-year performance guarantees.
Modular Inverter Market Segmentation
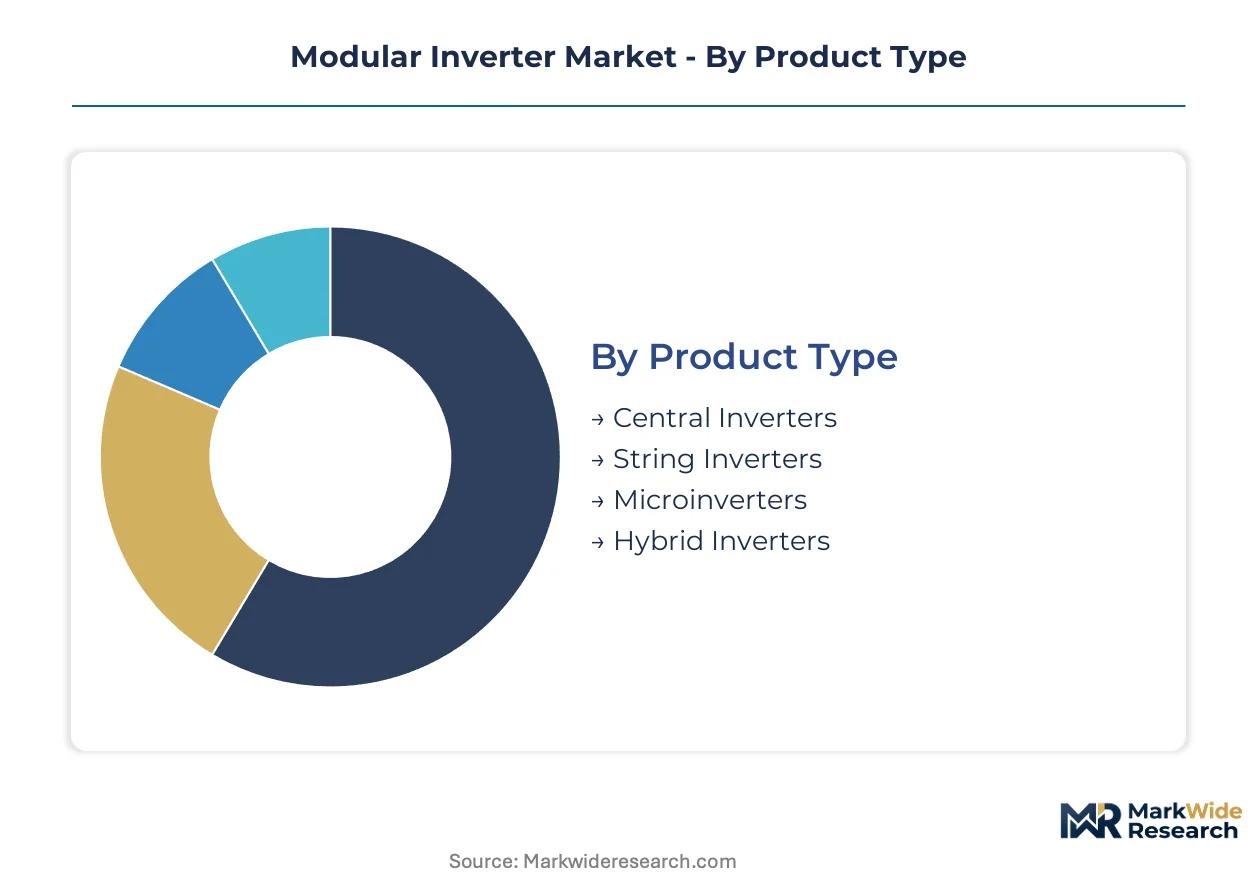
Modular inverter procurement patterns diverge sharply across installation scales and grid interconnection requirements. Segment boundaries increasingly blur as hybrid architectures absorb functions previously split across discrete product categories.
Product Type:
Installations range from rooftop flexibility to utility-scale fault isolation, with power density and thermal architecture driving selection criteria.
- Central Inverters:Built from paralleled sub-assemblies rated 1.5 MW to 6.8 MW, these containerized systems isolate failures to individual modules during maintenance windows. Utility-scale solar farms in Texas and Australia specify central architectures for phased capacity expansion that limits downtime exposure across 20-year asset lifespans.
- String Inverters:Fixed-capacity units between 5 kW and 150 kW deploy across residential and commercial rooftops where rapid commissioning offsets premium per-watt costs. California installers favor string configurations for retrofit projects requiring minimal DC homerun cabling and plug-and-play commissioning protocols.
- Microinverters:Module-level power electronics eliminate string mismatch losses through per-panel maximum power point tracking. Residential markets in Germany adopt microinverters for complex roof geometries where shading patterns degrade centralized inverter performance.
- Hybrid Inverters:Bidirectional DC-AC conversion integrates battery storage with photovoltaic generation for time-shifting and backup functions. German and Californian markets command margin premiums for hybrid platforms that satisfy grid-support requirements under evolving interconnection standards.
Established volume favors central inverters; emerging adoption favors hybrid inverters.
End User:
Procurement authority concentrates differently across customer tiers, from homeowner decision-making to utility engineering specifications.
- Residential:Homeowners prioritize installation speed and monitoring visibility over absolute conversion efficiency. String and microinverter suppliers compete through contractor certification programs that lock in installer loyalty across repeat purchase cycles.
- Commercial:Facility managers balance rooftop structural constraints against energy cost reduction targets. Flat-roof warehouses in the United States specify lightweight string architectures that avoid ballasted racking penalties.
- Industrial:Manufacturing campuses demand power quality and ride-through capabilities that sustain production continuity during grid disturbances. On-site engineering teams specify inverters with IEEE 1547-2018 compliant volt-var functionality.
- Utilities:Independent power producers procure multi-megawatt central inverter blocks with 20-year service contracts and predictive maintenance platforms. Procurement frameworks in Germany and the United States consolidate around single-source accountability for performance guarantees.
Utility procurement concentrates manufacturing scale; commercial installations drive product standardization.
Technology:
Input source characteristics determine switching topology selection and control algorithm complexity.
- Solar:Photovoltaic DC input dominates modular inverter deployment, with silicon carbide MOSFETs enabling 1500 VDC string architectures that slash copper costs. Southwestern United States developers specify wide-bandgap devices for desert thermal conditions.
- Wind:Variable-frequency AC from permanent magnet generators requires rectification stages before DC-AC inversion. Offshore wind projects in the North Sea test modular converter platforms for turbine-scale power conversion.
- Fuel Cell:Low-voltage, high-current DC output demands specialized current-fed inverter topologies. Stationary fuel cell installations in Japan integrate modular conversion for building-scale combined heat and power systems.
- Energy Storage:Bidirectional power flow for charge and discharge cycles commands premium firmware engineering for grid-forming control. California and Germany lead procurement of storage-coupled inverters for frequency regulation services.
Solar dominates installed base; energy storage climbs the fastest.
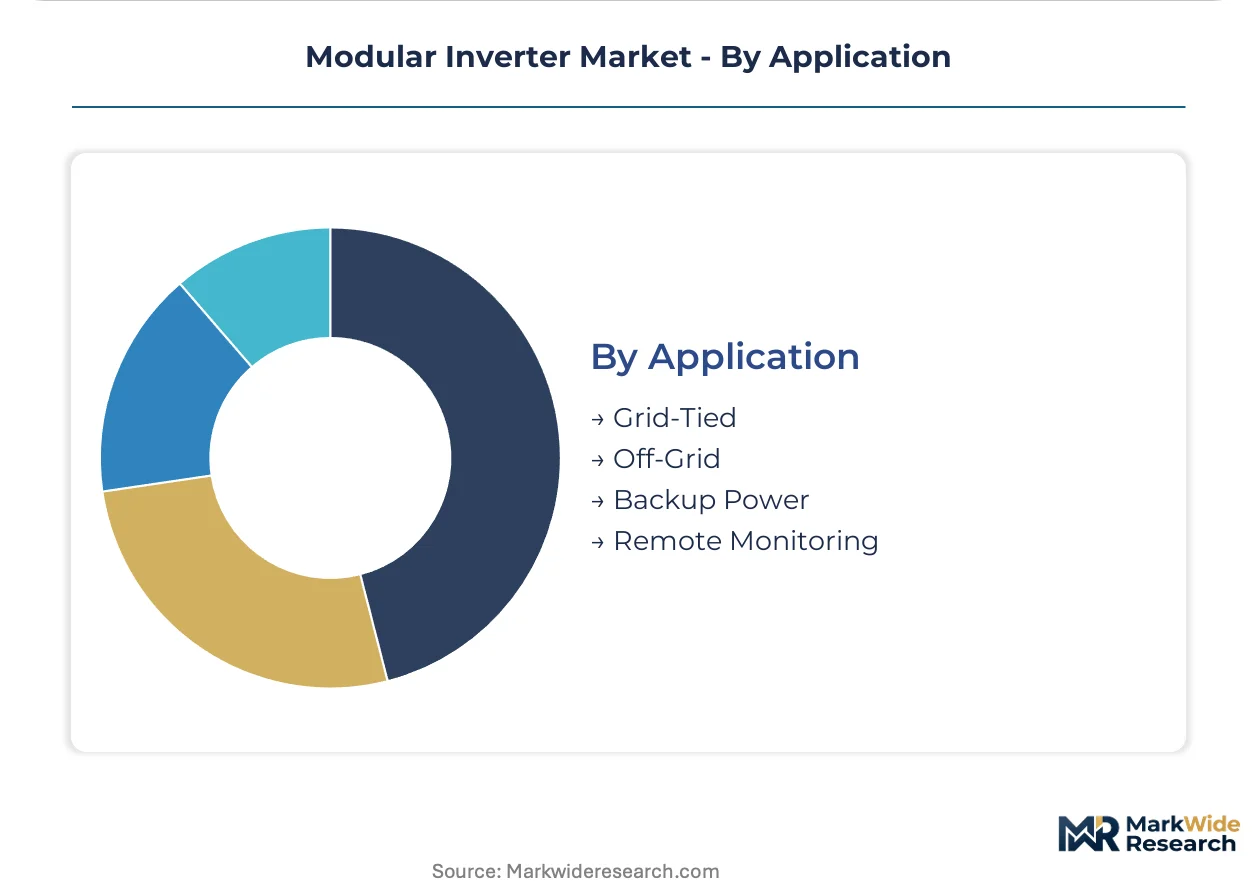
Application:
Grid interconnection status and reliability requirements segment functional specifications and certification obligations.
- Grid-Tied:Synchronized AC output feeds directly into distribution infrastructure under utility interconnection agreements. FERC Order 2023 reforms compress queue timelines for grid-tied resources in Texas and California procurement cycles.
- Off-Grid:Standalone systems operate without utility reference, requiring internal voltage and frequency regulation. Remote mining operations in Australia deploy containerized modular inverters for diesel displacement in islanded microgrids.
- Backup Power:Seamless transfer switching maintains critical loads during grid outages through battery or generator support. Hurricane-prone regions in the southeastern United States specify backup-capable hybrids for resilience compliance.
- Remote Monitoring:Telemetry-enabled diagnostics reduce truck rolls through predictive fault detection and firmware updates. Asia-Pacific utilities anchor long-term service contracts around remote monitoring platforms.
Grid-tied applications concentrate revenue volume; backup power functions gain regulatory traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale buyers in Australia and the southwestern United States absorb price premiums for silicon carbide architectures, while residential segments in Germany and Japan demand cost-competitive string configurations that compress margins.
United States
Texas solar farm developers stack modular units for phased capacity expansion across 1500 VDC architectures. FERC Order 2023 compresses interconnection queues, accelerating procurement urgency among independent power producers. Arizona and Nevada desert installations specify wide-bandgap semiconductors for thermal performance under extreme ambient conditions.
Germany
Utility-scale auctions consolidate procurement around single-source accountability for 20-year performance guarantees. IEC 62109-2 arc fault requirements filter non-compliant suppliers from vendor lists. Bavarian and North Rhine-Westphalian EPC contractors specify hybrid inverters with grid-forming firmware for frequency regulation services.
China
Gigawatt-class manufacturing lines control cost curves for central and string inverter platforms exported to Asia-Pacific utility installations. GB standards and dual carbon goals tighten efficiency thresholds for domestic procurement. Yangtze River Delta production clusters supply stackable power conversion units for Middle East and African markets.
Australia
Remote mining operations deploy containerized modular inverters for diesel displacement in islanded microgrids. Western Australian and Queensland solar farms specify SiC-based modular blocks for 1500 VDC string architectures. The country's national energy regulator enforces ride-through capabilities that legacy grid-tied inverters cannot satisfy.
Japan
Stationary fuel cell installations integrate modular conversion for building-scale combined heat and power systems. METI standards mandate volt-var optimization that shapes product qualification windows. Kanto and Kansai industrial clusters test modular converter platforms for offshore wind turbine-scale power conversion.
Modular Inverter Market Competitive Landscape
Capability concentration sits with European and Japanese engineering teams possessing grid-forming firmware expertise; scale advantage sits with Chinese manufacturers operating gigawatt-class production lines. The vendor base stratifies across three archetypes: vertically integrated technology conglomerates, specialized power electronics fabricators, and contract manufacturers serving private-label brands. Dominant competitive moves include backward integration into silicon carbide semiconductor sourcing and predictive maintenance platform development to anchor recurring service revenue.
Among Asia-Pacific-based technology conglomerates, Huawei and Sungrow occupy positions that exemplify the vertically integrated archetype, combining captive semiconductor procurement with digital service platforms. SMA represents the specialized European fabricator tier, sustaining market presence through localized technical support networks and grid-forming firmware capabilities. Fronius anchors the Austrian-German engineering tradition, sitting within the premium-tier segment where specialized grid-support functionality commands qualification advantages under tightening interconnection standards.
| Leading Market Players |
|---|
| Fronius |
| GoodWe |
| Sungrow |
| Enphase |
| SolarEdge |
| Huawei |
| Solis |
| Gronsol |
| SMA |
| Others |
Supply & Pricing Matrix
IGBT supply concentration in East Asian foundries exposes procurement timelines to geographic concentration risk during capacity allocation cycles, compressing margins for non-vertically integrated vendors while forcing tiered pricing spreads between captive-semiconductor and merchant-component suppliers.
Pricing Analysis
Predictive maintenance contracts and firmware update subscriptions now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates UL 1741-SA certified grid-forming units from basic grid-tied alternatives and white-label merchant products. Price differentiation rests on certification grade and after-sales bundling, with utility-scale EPCs least sensitive due to 20-year performance guarantee requirements while residential installers face acute pressure from string inverter substitution.
Supply Chain Analysis
Silicon carbide wafer feedstock draws from Japan, Germany, and United States substrate manufacturers before fabrication in Taiwan and South Korea power semiconductor foundries. Raw material dependencies span high-purity silicon, rare earth dopants, and ceramic substrate materials. Single-source vulnerability concentrates in 150mm SiC wafer supply, with distribution running through direct OEM contracts for utility-scale blocks and distributor networks for commercial-residential string units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility procurement consolidation around single-source accountability for 20-year performance guarantees has shifted bargaining power toward EPC contractors and independent power producers, fragmenting vendor influence.
For Market Incumbents: Entrench grid-forming firmware capabilities through specialized engineering hires in European and Japanese talent pools, defending against Chinese manufacturers acquiring SiC semiconductor sourcing. Prioritize UL 1741-SA and IEC 62109-2 certification maintenance to retain utility-tier vendor list eligibility as interconnection standards tighten.
For New Entrants and Emerging Players: Build out remote diagnostics platforms targeting Asia-Pacific utility installations where predictive analytics contracts displace hardware replacement revenue. White-space exists in hybrid inverter retrofit markets across California and Germany, with go-to-market through EPC contractor certification programs offering commissioning support.
For Investors and Strategic Acquirers: IEEE 1547-2018 revision implementation across US state jurisdictions reshapes the acquisition landscape toward vertically integrated suppliers with captive semiconductor procurement and digital service platforms. Target archetypes combine SiC switching topology expertise with predictive maintenance software stacks. Watch FERC Order 2023 queue compression velocity as inflection indicator for procurement urgency cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Semiconductor Sourcing | Captive wafer supply insulates margin compression from East Asian foundry allocation cycles. |
| Predictive Maintenance Platform Development | Huawei's digital power platform anchors recurring service contracts across Asia-Pacific installations. |
| Grid-Forming Firmware Engineering Investment | SMA sustains European presence through specialized control algorithms for frequency regulation services. |
| UL 1741-SA Certification Acceleration | Extended test protocols filter non-compliant suppliers from utility-tier vendor lists in Texas and California. |
| Gigawatt-Class Manufacturing Scale-Up | Sungrow operates production lines controlling cost curves for central and string inverter platforms. |
Research Methodology
The analysis maps central inverter, string inverter, microinverter, and hybrid inverter sub-sectors, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary interviews with inverter procurement leads and aftermarket service heads combined with secondary validation against FERC filings, EIA project databases, IEC certification registries, and IEA technology roadmaps. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Assumptions held fixed include IEEE 1547-2018 state-level implementation timelines, SiC MOSFET cost reduction curves, and utility-scale solar capacity expansion patterns across the projection horizon. Segmentation dimensions modeled span product architecture, end-user tier, switching topology technology, and grid interconnection application. CAGRs derived from regression against historical deployment trajectories and regulatory queue velocity, with specific inputs including interconnection reform implementation schedules and wide-bandgap semiconductor adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese technology conglomerates acquiring European firmware engineering teams would shift outcomes. Material shifts in FERC Order 2023 enforcement intensity or IEEE 1547 revision timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Power Diode Market
Power Systems
PV Micro Inverters Market
Power Systems
Space DC-DC Converters Market
Power Systems
DC Power Supplies Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Shunt Capacitor Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Global Battery Thermal Management System Market