
 Physical Vapor Deposition (PVD) Market | 2026-2036
Physical Vapor Deposition (PVD) Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Vapor Deposition (PVD) Market Intelligence
Modular tool configurations that separate deposition chambers from load-lock systems is recalibrating how fabs evaluate total cost of ownership. Oerlikon Balzers Coating AG leverages its vertical integration in Switzerland to control coating quality from target production to final tool delivery. Applied Materials, Inc. dominates semiconductor PVD with integrated end-to-end wafer processing platforms. ULVAC, Inc. anchors Asian supply chains through localized manufacturing and service networks in Japan and Taiwan.
Physical Vapor Deposition encompasses vacuum-based thin-film deposition methods where solid material vaporizes in a controlled environment and condenses onto substrates, typically operating at pressures below 10^-3 Torr with film thickness precision reaching atomic-layer scales. Sputtering technology leads semiconductor metallization for copper barrier and seed layers, while thermal evaporation occupies mature optical coating segments with slower growth but stable margin pools. Electron beam vaporization differentiates in aerospace turbine blade coatings where superalloy thermal barrier deposition demands extreme temperature tolerance.
EPA air toxics standards and OSHA hexavalent chromium exposure limits constrain traditional electroplating alternatives, redirecting demand toward PVD's cleaner coating pathways. REACH substance restrictions in Europe and China's MEE emissions enforcement collectively raise compliance costs for wet chemical processes, advantaging vacuum deposition adoption. Stakeholders must monitor evolving PFAS regulations and rare earth target supply security as these factors reshape equipment sourcing and material qualification timelines.
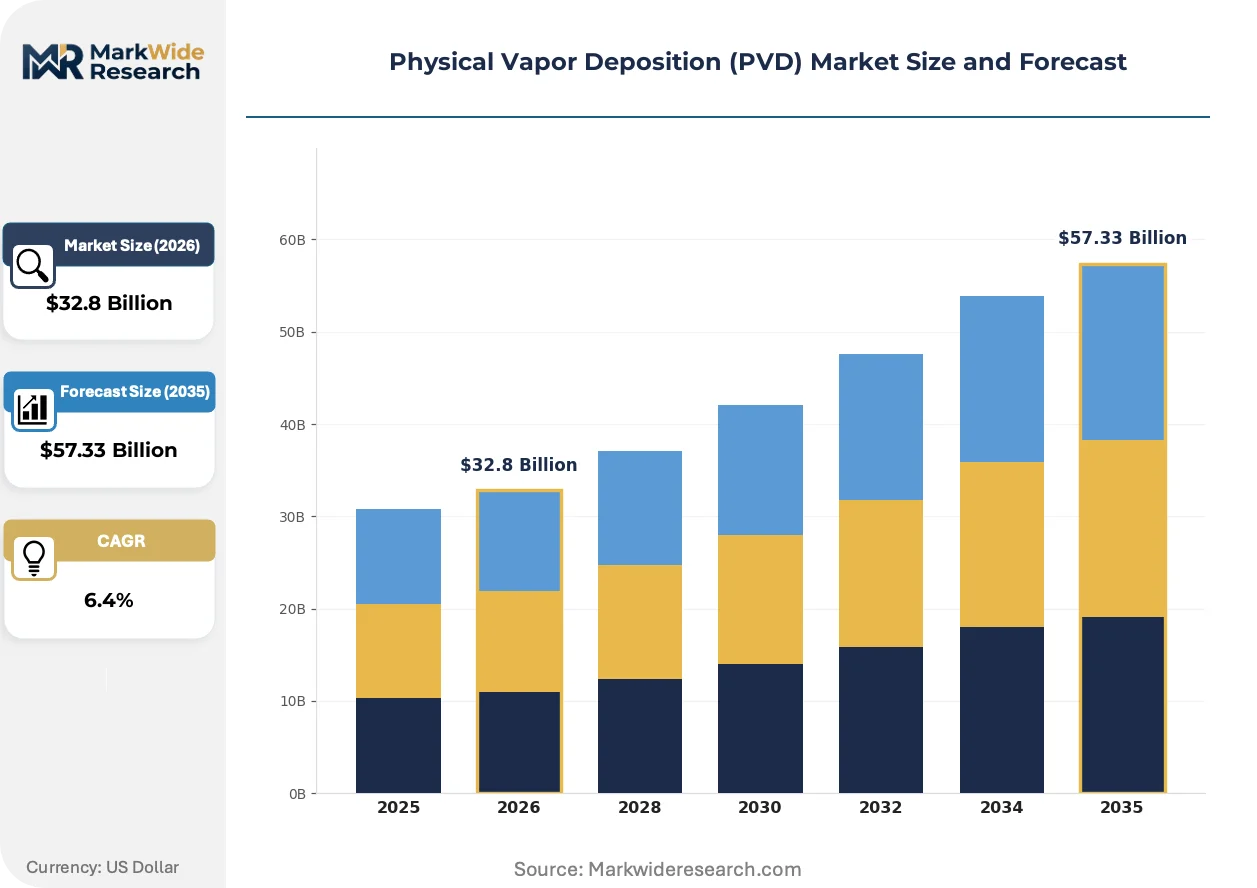
Market Dynamics
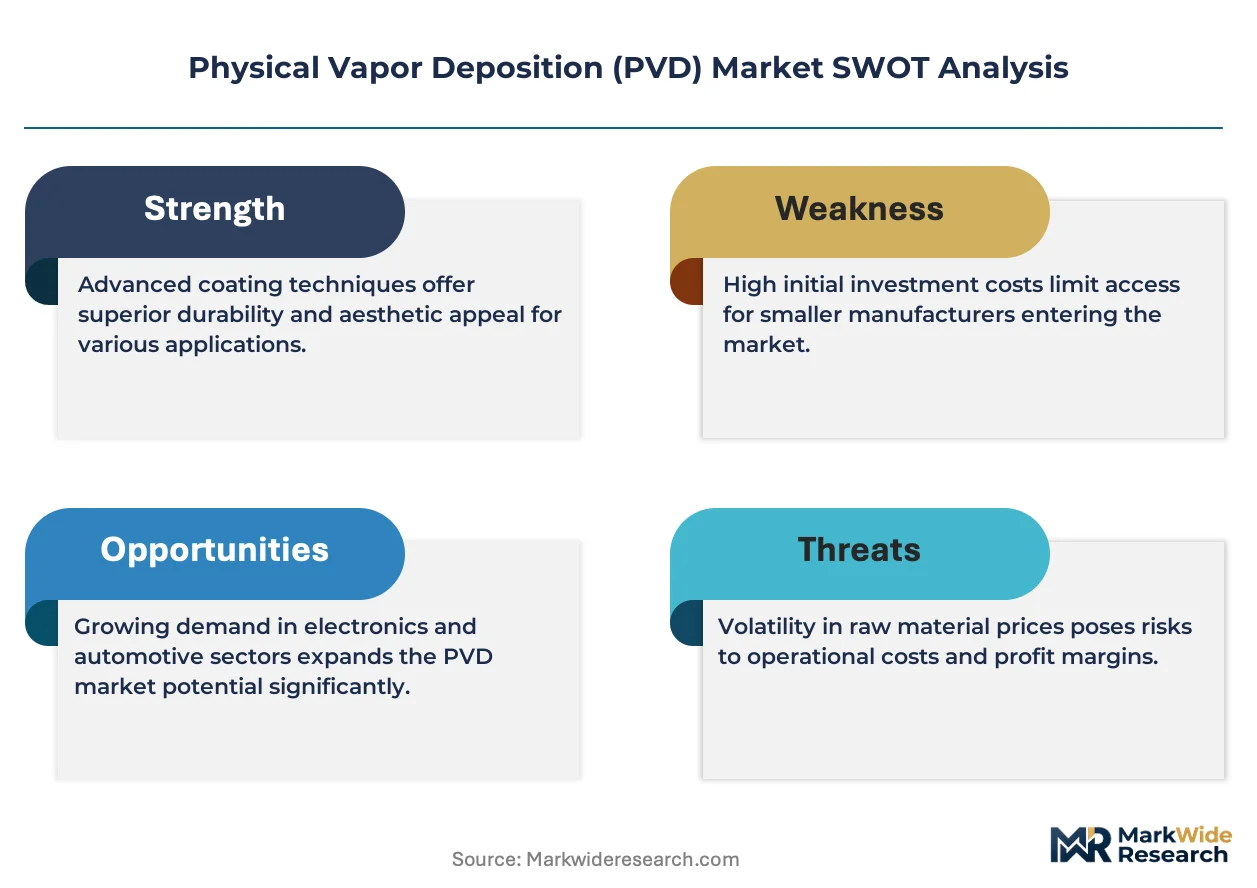
EUV lithography node advancement below 3nm is compressing PVD tool qualification timelines while simultaneously expanding chamber count per fab, creating a structural capacity squeeze that favors suppliers with captive target manufacturing.
Growth Catalysts
- Semiconductor node migration:Copper barrier and seed layer deposition requirements multiply as Taiwan and South Korea fabs advance to angstrom-scale features. Each node shrink adds 20-30% more PVD steps per wafer.
- MEE emissions enforcement:China's Ministry of Ecology and Environment is tightening volatile organic compound limits on wet chemical coating alternatives, redirecting automotive and electronics manufacturers toward vacuum-based deposition pathways.
- Superalloy thermal barrier demand:Aerospace turbine OEMs are specifying electron beam PVD for thermal barrier coatings as operating temperatures exceed 1,100°C in next-generation engines.
Market Restraints
- High-purity target supply concentration:Rare earth and refractory metal sputtering target production concentrates in Chinese state-controlled enterprises, creating single-source vulnerability for non-Chinese tool builders.
- PFAS regulatory uncertainty:REACH substance restrictions and emerging US state-level PFAS bans threaten fluoropolymer-based chamber components and process gases, forcing material requalification cycles.
- Technical limitation in conformal coverage:PVD's line-of-sight deposition physics creates coverage gaps in high-aspect-ratio 3D NAND structures above 200:1, ceding some applications to ALD alternatives.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication create greenfield PVD tool demand as Foxconn and Tata Group establish domestic assembly capacity.
- Battery electrode metallization:Solid-state lithium-metal anode manufacturing is adopting PVD for thin-film lithium deposition, opening a process chemistry distinct from semiconductor applications.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms and ETS expansion are advantaging PVD over electroplating in automotive and construction hardware supply chains.
Industry Challenges
- Vacuum technician scarcity:Semiconductor fabs in Germany and Japan report 18-month lead times for qualified PVD chamber maintenance specialists, constraining tool utilization rates.
- Legacy system integration:200mm fabs upgrading to 300mm platforms face incompatible wafer handling robotics and control architectures, requiring custom engineering for mixed-tool environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Vapor Deposition (PVD) Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Evaporation, Sputtering, Electron Beam Vaporization, Pulsed Laser Deposition Application: Semiconductors, Optical Coatings, Decorative Finishes, Tool Coatings End User: Aerospace, Automotive, Electronics, Healthcare Material: Metals, Alloys, Ceramics, Compounds |
| Companies Covered | Oerlikon Balzers Coating AG, Denton Vacuum, LLC, Applied Materials, Inc., Kurt J. Lesker Company, Angstrom Engineering, Inc., ULVAC, Inc., IHI Corporation, Advanced Energy Industries, Inc., Veeco Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Vapor Deposition (PVD) Market Strategic Shifts & Innovations
Process-tool integration is compressing the boundary between deposition and metrology, with real-time film thickness monitoring becoming standard rather than optional. This convergence is redrawing supplier relationships and qualification protocols.
Cluster tool architectures with unified process modules are unifying sputtering, etch, and clean steps within single vacuum envelopes. Memory manufacturers in South Korea are adopting these configurations to reduce wafer queue time and particle contamination. The technology is unifying what were previously separate equipment categories into single-vendor procurement decisions.
REACH substance restrictions on hexavalent chromium and cadmium compounds are eliminating electroplated hard chrome from aerospace landing gear and hydraulic rod specifications. European MRO facilities are certifying HVOF and PVD alternatives to maintain airworthiness compliance. Defense and commercial aviation supply chains are most affected, with Tier-1 suppliers accelerating coating line conversions ahead of 2027 enforcement deadlines.
Equipment-as-a-service contracting is displacing capital purchase models for mid-size optical coating operations. German automotive lighting suppliers now subscribe to PVD capacity rather than owning depreciating assets, transferring uptime risk to Applied Materials and Oerlikon Balzers. This shift concentrates most visibly in Bavaria's automotive cluster, where OEMs are pushing coating cost variability onto their supply base.
Physical Vapor Deposition (PVD) Market Segmentation
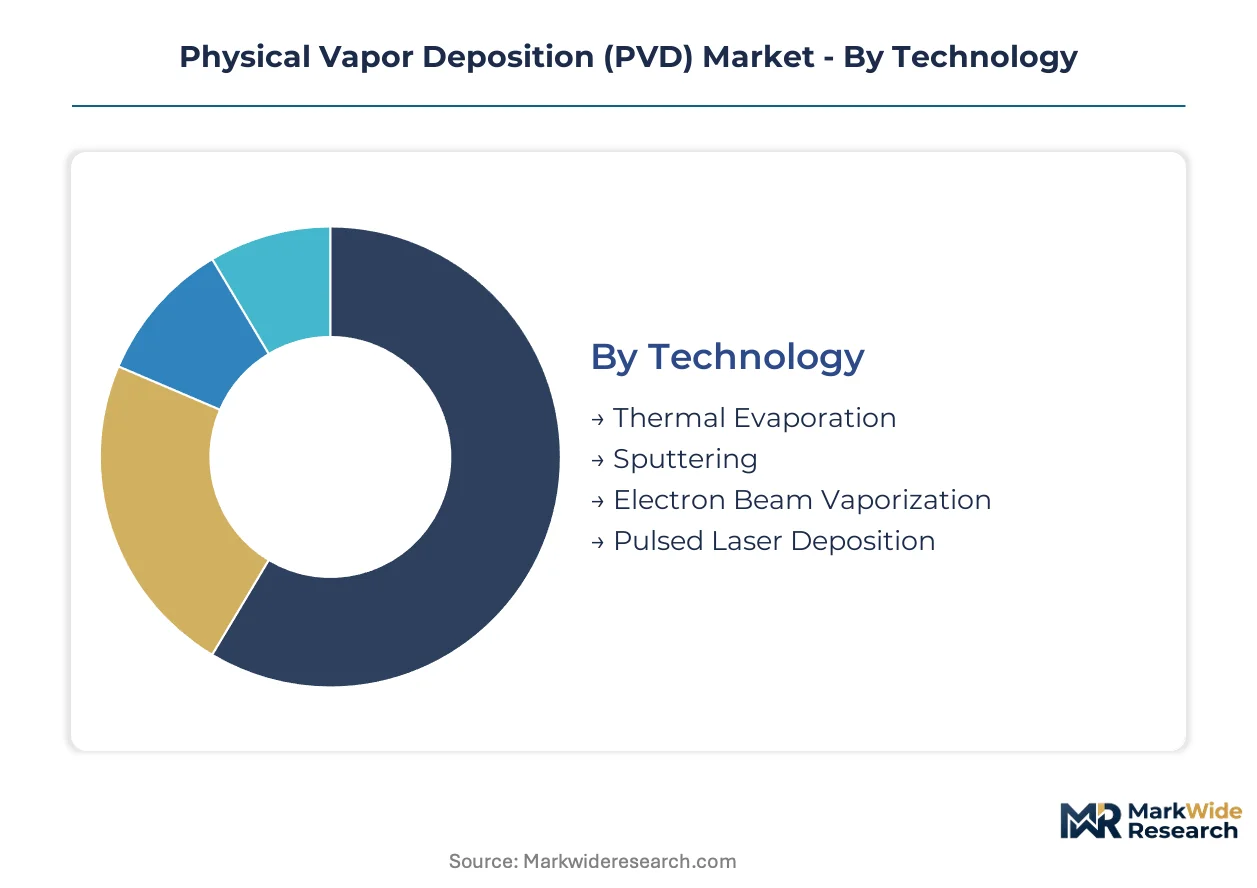
PVD equipment purchasing decisions diverge sharply across technology types and end-use requirements. Tool specifications, target materials, and chamber configurations must align with substrate sensitivity, film thickness tolerances, and production throughput demands.
Technology:
Equipment upgrade cycles now center on chamber modularity and process integration rather than standalone deposition performance.
- Sputtering:Magnetron configurations dominate semiconductor metallization, depositing copper barrier and seed layers with angstrom-level thickness control. Taiwan and South Korea fabs are expanding chamber counts as EUV lithography nodes advance below 3nm, each shrink adding 20-30% more PVD steps per wafer.
- Thermal Evaporation:Resistive heating vaporizes metals in high-vacuum environments for optical coating applications where cost sensitivity outweighs precision requirements. Mature segments in architectural glass and consumer eyewear sustain stable margin pools despite slower expansion.
- Electron Beam Vaporization:Focused electron beams melt refractory metals and ceramics at extreme temperatures for aerospace turbine blade thermal barrier coatings. Next-generation engines exceeding 1,100°C operating temperatures are specifying this technology for superalloy deposition.
- Pulsed Laser Deposition:High-energy laser pulses ablate target material for complex oxide thin films in research and specialty electronics settings.
Volume placements concentrate in sputtering; the faster expansion belongs to electron beam vaporization.
Application:
Application selection tracks substrate value and defect tolerance, with high-value wafers demanding closed-loop process control.
- Semiconductors:Front-end metallization for logic and memory devices requires ultra-high vacuum base pressures below 10^-9 Torr. Copper interconnects, tungsten vias, and cobalt liners each need dedicated chamber configurations with minimal cross-contamination.
- Tool Coatings:Cutting inserts and forming dies receive titanium aluminum nitride and diamond-like carbon layers to extend service life. Automotive powertrain manufacturers in Germany are converting from wet chemical plating to PVD for regulatory compliance.
- Optical Coatings:Anti-reflective and filter layers for lenses, mirrors, and display panels occupy mature equipment installed bases with longer replacement cycles.
- Decorative Finishes:Architectural hardware and consumer electronics casings use titanium nitride and zirconium nitride for wear resistance and aesthetic appeal.
Semiconductors command the dominant equipment spend; tool coatings are climbing the fastest as industrial regulations tighten.
End User:
End-user procurement patterns split between fabs with captive engineering staff and contract coaters serving fragmented industrial demand.
- Electronics:Memory and logic manufacturers in East Asia operate the largest installed bases, with cluster tool architectures unifying sputtering, etch, and clean steps within single vacuum envelopes.
- Aerospace:Engine OEMs and MRO facilities specify electron beam PVD for thermal barrier coatings on turbine blades, with European facilities certifying alternatives ahead of REACH enforcement deadlines.
- Automotive:Lighting suppliers and powertrain component manufacturers are adopting equipment-as-a-service models to transfer uptime risk to tool vendors.
- Healthcare:Surgical instruments and implantable devices require biocompatible coatings with documented traceability for FDA and CE marking submissions.
Electronics generates the highest chamber shipments; aerospace is expanding most quickly on engine program ramp-ups.
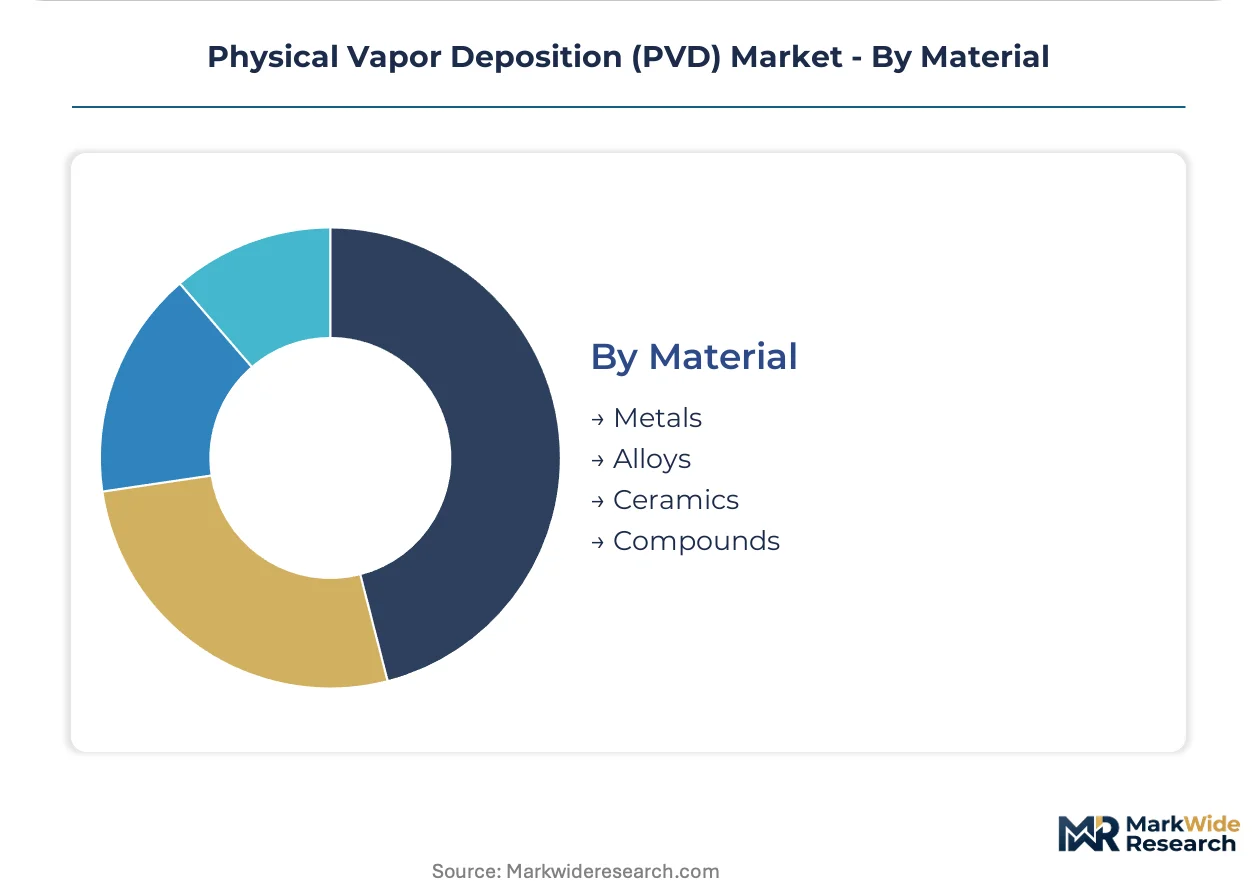
Material:
Material qualification timelines stretch when supply concentration conflicts with dual-source procurement policies.
- Metals:Aluminum, titanium, copper, and tungsten targets serve the broadest application range across semiconductor and industrial coating segments.
- Alloys:Titanium aluminum nitride and chromium nitride compositions dominate tool coating specifications for hardness and oxidation resistance.
- Ceramics:Yttria-stabilized zirconia thermal barrier coatings for aerospace applications require electron beam vaporization due to high melting points.
- Compounds:Indium tin oxide and specialized transparent conductive oxides serve display and photovoltaic applications with distinct electrical conductivity requirements.
Metals anchor the largest target consumption; ceramics are gaining share fastest on aerospace thermal management demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics clusters consume the majority of PVD equipment output, while European aerospace and automotive demand drives specialized tool configurations. North American semiconductor fabs concentrate in specific metropolitan corridors with distinct regulatory pressures.
China
MEE emissions enforcement is redirecting automotive and electronics manufacturers from wet chemical plating toward vacuum deposition. Dual carbon goals and NMPA process standards are tightening coating emissions limits across manufacturing zones. Yangtze River Delta fabs in Shanghai and Suzhou are expanding PVD capacity for domestic semiconductor self-sufficiency programs.
Taiwan
TSMC and UMC are multiplying PVD chamber counts as EUV nodes advance below 3nm, each shrink adding 20-30% more deposition steps per wafer. The island's EPA enforces volatile organic compound limits that advantage vacuum processes over electroplating alternatives. Hsinchu Science Park and Tainan cluster fabs are qualifying modular tool configurations that separate deposition chambers from load-lock systems.
South Korea
Samsung and SK Hynix memory manufacturers are adopting cluster tool architectures unifying sputtering, etch, and clean steps within single vacuum envelopes. MFDS medical device regulations and national green growth targets are tightening coating process standards. Pyeongtaek and Yongin semiconductor complexes are driving tool orders for angstrom-scale copper barrier and seed layer deposition.
United States
EPA air toxics standards and OSHA hexavalent chromium exposure limits are constraining traditional electroplating alternatives in aerospace and defense supply chains. IRA clean manufacturing incentives are supporting domestic semiconductor fab construction with PVD tool procurement. Phoenix and Austin metropolitan corridors are attracting Intel and TSMC fabs with captive PVD equipment requirements.
Germany
REACH substance restrictions on hexavalent chromium are eliminating electroplated hard chrome from aerospace landing gear specifications ahead of 2027 enforcement. KBA automotive regulations and EU Green Deal carbon border adjustments are advantaging PVD over wet plating in powertrain manufacturing. Bavaria's automotive lighting cluster is adopting equipment-as-a-service contracting models from tool vendors.
Physical Vapor Deposition (PVD) Market Key Industry Players
The competitive structure tilts toward integrated platform providers with captive target manufacturing capabilities. Market concentration favors suppliers controlling coating quality from raw material production through final tool delivery. Two strategic archetypes dominate: diversified industrial conglomerates with vertical integration into sputtering target production, and specialized equipment builders with localized service networks. Competitive moves center on modular chamber architectures and outcome-based contracting models that transfer uptime risk to vendors.
Among Swiss and US-based platform providers, Oerlikon Balzers Coating AG and Applied Materials, Inc. exemplify the integrated-systems archetype with upstream control over target production. Japanese specialists ULVAC, Inc. and IHI Corporation occupy positions anchored in East Asian supply chains through localized manufacturing footprints. Kurt J. Lesker Company represents the mid-scale equipment builder segment serving research and specialty industrial applications with configurable chamber designs.
| Leading Market Players |
|---|
| Oerlikon Balzers Coating AG |
| Denton Vacuum, LLC |
| Applied Materials, Inc. |
| Kurt J. Lesker Company |
| Angstrom Engineering, Inc. |
| ULVAC, Inc. |
| IHI Corporation |
| Advanced Energy Industries, Inc. |
| Veeco Instruments, Inc. |
| Others |
Cost & Logistics Intelligence
Vacuum technician scarcity in Germany and Japan widens pricing-tier spreads between premium tool vendors with captive service networks and mid-scale equipment builders dependent on third-party maintenance labor. Labor-cost differentials of 40-60% between Swiss-integrated platform providers and regional assemblers translate directly into three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Cost-down pressure on mid-scale sputtering tools accelerates because Chinese state-owned enterprises are flooding refractory metal target supply, compressing margins for non-integrated tool builders. Three-tier pricing structure across premium, standard, and economy levels separates Applied Materials' integrated wafer-processing platforms from ULVAC's localized Asian service networks and Kurt J. Lesker's configurable research-grade chambers. Price differentiation hinges on ISO 14644 cleanroom certification tier and after-sales uptime guarantees. Memory manufacturers in South Korea exhibit lowest price sensitivity due to yield-loss costs dwarfing equipment premiums, while Indian contract coaters under PLI schemes face acute capital constraints.
Supply Chain Analysis
High-purity sputtering target supply rests on Chinese state-controlled rare earth processors, Japanese specialty metal refiners, and Austrian tungsten-carbide producers. PVD equipment production draws from German vacuum pump manufacturers, Swiss precision-machined chamber component suppliers, and Taiwanese robotic wafer-handling subsystems. Single-source vulnerability concentrates in yttria-stabilized zirconia thermal barrier ceramics for aerospace applications. Distribution runs through direct fab-equipment procurement teams for semiconductor front-end tools, contrasted with distributor-mediated sales for industrial cutting-insert coaters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is supply-constrained by qualified vacuum technician availability, with 18-month lead times for chamber maintenance specialists propping pricing power for vendors with captive service networks.
For Market Incumbents: Anticipate atomic layer deposition substitution in high-aspect-ratio 3D NAND above 200:1 by deepening backward integration into sputtering target production in Switzerland and Austria. Defend against Chinese state-owned target suppliers by securing dual-source qualification timelines with European refractory metal refiners. Certification investment in REACH-compliant fluoropolymer alternatives represents the critical defensive lever. For New Entrants and Emerging Players: Begin with India's PLI-scheme electronics manufacturing clusters where Foxconn and Tata Group are greenfielding capacity without legacy tool vendor relationships. Solid-state battery electrode metallization for lithium-metal anodes offers the most penetrable white-space application distinct from semiconductor process chemistry. Equipment-as-a-service contracting models transfer uptime risk and lower capital barriers for entry. For Investors and Strategic Acquirers: The window for entry favors mid-scale equipment builders with configurable chamber designs serving research and specialty industrial applications. Long-term viability centers on captive target manufacturing capabilities and localized Asian service footprints. Watch PFAS regulatory enforcement timelines in US states and EU REACH amendments as the inflection signal for material requalification cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Target Production | Oerlikon Balzers controls coating quality from Austrian tungsten refining through final Swiss tool delivery. |
| Cluster Tool Architecture Unification | Samsung and SK Hynix reduce wafer queue time by integrating sputtering, etch, and clean in single vacuum envelopes. |
| Equipment-as-a-Service Contracting | Bavarian automotive lighting suppliers subscribe to PVD capacity from Applied Materials rather than owning depreciating assets. |
| REACH-Compliant Material Requalification | European MRO facilities certify HVOF and PVD alternatives ahead of 2027 hexavalent chromium enforcement deadlines. |
| Localized Manufacturing Footprint Expansion | ULVAC anchors East Asian supply chains through captive production and service networks in Japan and Taiwan. |
Research Approach
Multi-period observation of EUV lithography node advancement rates, MEE emissions enforcement intensity, and aerospace engine program ramp schedules anchored the trend analysis, supplemented by interviews with semiconductor fab equipment procurement directors, vacuum chamber maintenance specialists, and sputtering target metallurgists. Secondary validation drew from SEC 10-K filings of listed equipment manufacturers, EPA air toxics standard dockets, and customs data on high-purity metal target trade flows. Bottom-up equipment shipment tallies by technology type and top-down semiconductor capital expenditure forecasts were triangulated against each other.
Segment-weighting across technology types, application requirements, and end-user procurement patterns structured the analytical framework throughout the projection horizon. Sputtering, thermal evaporation, electron beam vaporization, and pulsed laser deposition were modeled separately with distinct input assumptions for chamber modularity adoption and process integration depth. CAGRs were derived from regression analysis of historical equipment order backlogs against semiconductor node migration timelines and industrial regulatory phase-in schedules. Forecast inputs included EUV lithography roadmaps from TSMC and Samsung, and China's dual carbon policy implementation rates.
PFAS regulatory uncertainty, rare earth target export restriction scenarios, and vacuum technician training pipeline constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about node shrink cadence and emissions enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market