
 Gan Substrate and Gan Wafer Market | 2026-2036
Gan Substrate and Gan Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Gan Substrate and Gan Wafer Market Analysis
Silicon carbide substrate integration into RF power amplifiers is tilting the compound semiconductor technology stack toward wide-bandgap architectures. Wolfspeed leverages captive SiC crystal growth to control substrate supply from boule to epi-ready wafer. Sumitomo Electric Industries anchors high-purity GaN substrate production for defense and satellite communications. Infineon Technologies competes through vertical integration into power device packaging that reduces thermal impedance.
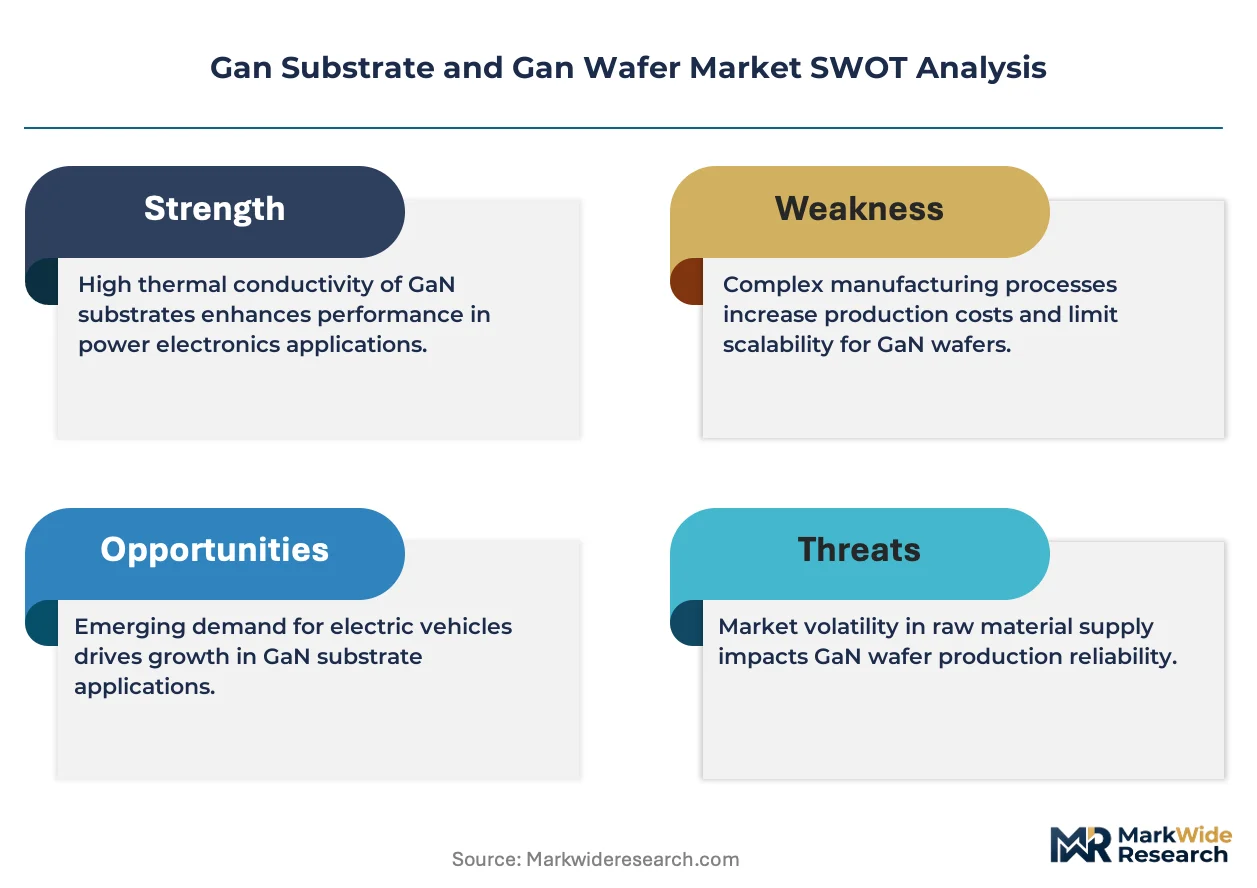
Gan substrates and Gan wafers are single-crystal or epitaxial semiconductor platforms grown on SiC, sapphire, or bulk GaN templates via MOCVD or HVPE processes, engineered for bandgap voltages above 3.4 eV that enable high-frequency switching and power conversion. The product type dimension shows SiC-based substrates capturing premium margin pools in military and telecom applications, while sapphire-backed configurations serve cost-sensitive LED volume production. MOCVD technology leads manufacturing scale for LED and power device epitaxy, whereas HVPE commands specialist RF and laser diode segments where thicker GaN layers improve breakdown voltage.
FCC Part 27 spectrum rules in the United States mandate efficiency thresholds that favor GaN RF devices in C-band and mmWave infrastructure. ECHA REACH restrictions on gallium and rare earth processing chemicals shape European substrate sourcing compliance costs. The EU Green Deal carbon border adjustments will test Chinese and Japanese wafer exporters' embodied energy accounting. Stakeholders must monitor how substrate diameter transitions from 150mm to 200mm reshape equipment amortization and yield economics.
Market Dynamics
Substrate diameter migration from 150mm to 200mm is compressing equipment amortization schedules and forcing foundries to recalibrate yield models before process maturity. This transition dominates capital allocation decisions across the value chain.
Growth Catalysts
- FCC Part 27 spectrum efficiency mandates:United States infrastructure rules favor GaN RF power amplifiers in C-band and mmWave base stations, accelerating substrate qualification timelines.
- Defense radar modernization:Military electronic warfare systems in Taiwan and South Korea specify GaN-on-SiC for phased-array transmitters, locking in multi-year substrate supply agreements.
- Electric vehicle traction inverters:Automotive OEMs in Germany and Japan specify 650V GaN devices for onboard chargers, pulling wafer demand from LED-centric supply chains.
Market Restraints
- High-purity SiC boule scarcity:Defect-free 6-inch SiC substrates concentrate with Japanese and American crystal growers, creating allocation bottlenecks for RF device foundries.
- ECHA REACH compliance costs:European gallium and rare earth processing restrictions add documentation burden to substrate importers, lengthening qualification cycles.
- Silicon superjunction MOSFET persistence:Mature silicon power devices below 200V retain cost advantage in consumer adapters, capping GaN penetration in price-sensitive segments.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentives for compound semiconductor fabs create first-mover substrate sourcing advantages for GaN device entrants.
- EU Green Deal carbon border adjustments:Embodied energy accounting requirements favor European and Japanese wafer exporters with verified low-crystal-growth footprints.
- Micro-LED display manufacturing:Sapphire-backed GaN wafers for sub-10 micron LED chips open volume demand outside traditional lighting applications.
Industry Challenges
- MOCVD reactor operator scarcity:Specialized epitaxy technicians with GaN-on-SiC process experience command premium wages, constraining foundry expansion timelines.
- Device-package thermal interface qualification:Matching GaN HEMT junction temperatures to sintered silver or transient liquid phase bonding processes delays automotive Tier 1 approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan Substrate and Gan Wafer Market |
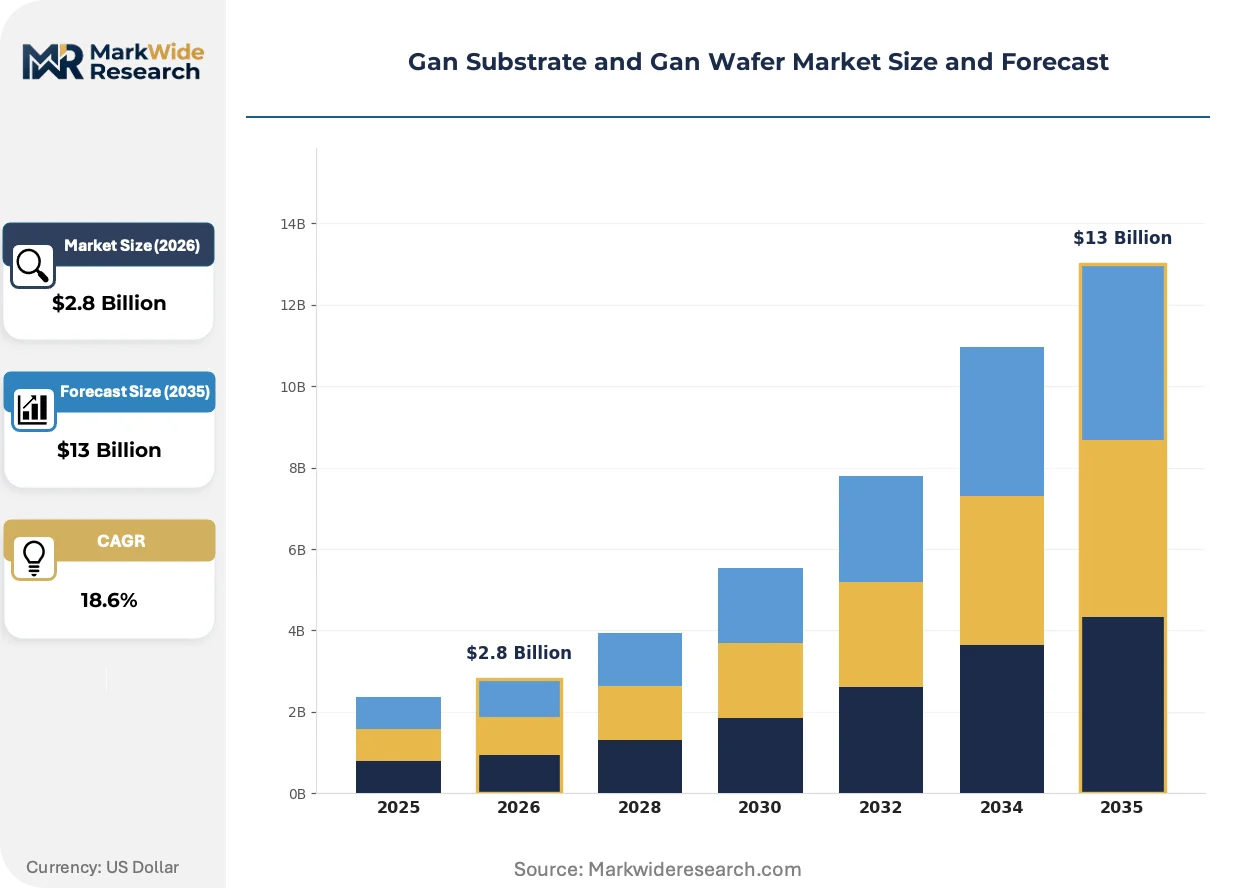
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NiO, SiC, Sapphire, Bulk GaN Technology: MOCVD, HVPE, LPE, Epitaxy End User: Telecommunications, Automotive, Consumer Electronics, Aerospace Application: LEDs, Power Devices, RF Devices, Laser Diodes |
| Companies Covered | Wolfspeed, Sumitomo Electric Industries, Cree, GaN Systems, Infineon Technologies, Mitsubishi Electric, STMicroelectronics, Six Point Materials, Sino Nitride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan Substrate and Gan Wafer Market Emerging Trajectories
Wafer fabrication technology is bifurcating between high-volume silicon-compatible GaN and performance-optimized SiC-native architectures. This divergence is reshaping equipment vendor roadmaps and foundry partnership structures.
GaN-on-Si epitaxy using strained-layer superlattice buffer architectures is rendering obsolete sapphire-based templates for sub-100W power adapters. Consumer electronics OEMs in Shenzhen and Taipei are qualifying these wafers for 65W USB-C charger ramps. The shift compresses substrate costs toward silicon economies while preserving switching efficiency.
ECHA REACH Annex XIV candidate list expansion for gallium compounds is forcing substrate importers to submit substitution dossiers or secure authorization. German and French compound semiconductor traders are consolidating supply chains to reduce chemical registration duplication. RF device manufacturers are accelerating bulk GaN substrate programs to bypass SiC precursor dependencies.
Defense procurement offices in the United States and Japan are unbundling substrate qualification from device-level contracts, creating direct purchasing relationships with crystal growers. This disintermediation bypasses traditional foundry distribution channels. Long-term supply agreements now specify boule provenance and epi-ready surface specifications independently of device fabrication.
Gan Substrate and Gan Wafer Market Segmentation
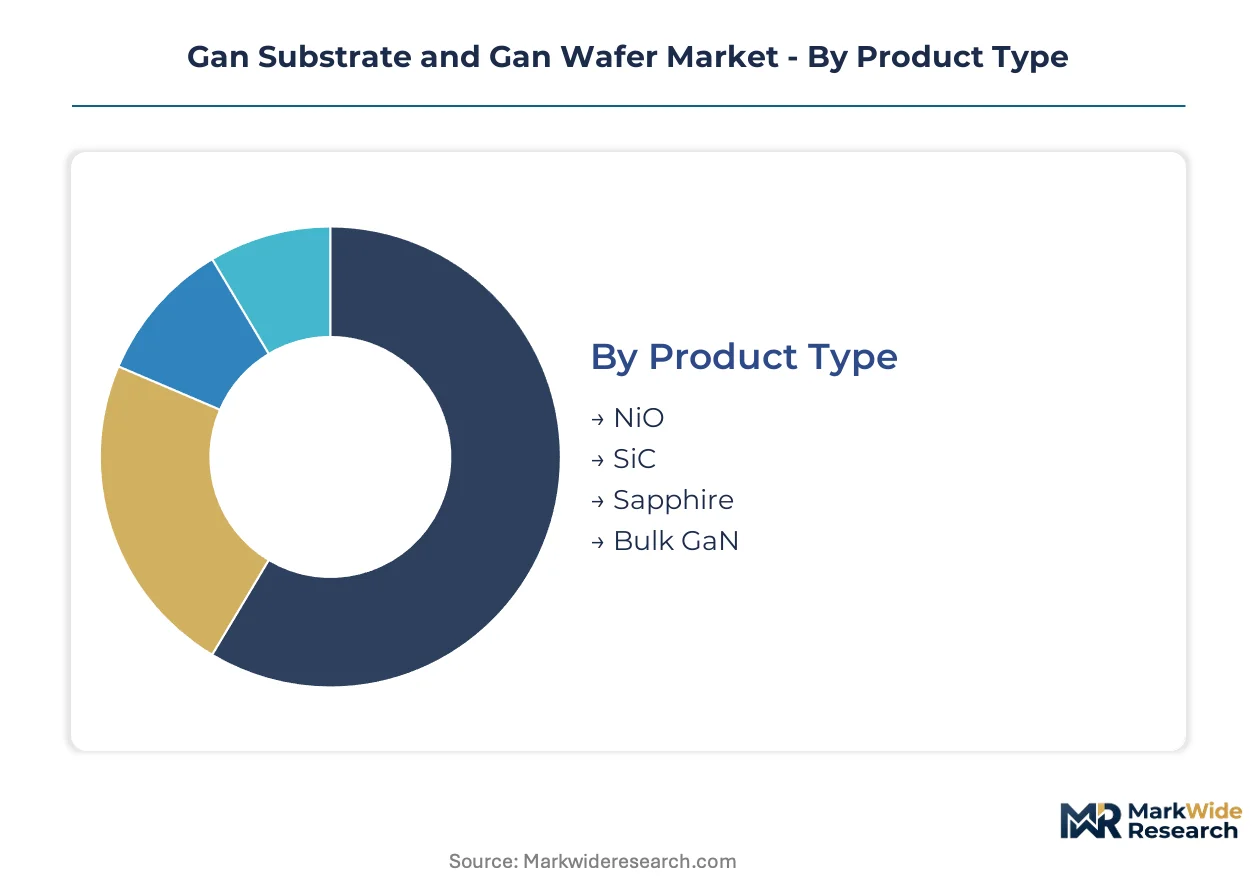
GaN substrate and wafer procurement cycles vary dramatically across end-use applications, from quarterly LED volume contracts to multi-year defense supply agreements. Understanding these velocity differentials helps suppliers align inventory positioning with customer qualification timelines.
Product Type:
Cycle times stretch from weeks for sapphire-backed LED substrates to 18-month qualification periods for bulk GaN templates in satellite communications.
- SiC:Silicon carbide substrates deliver the thermal conductivity and lattice matching required for high-frequency RF power amplifiers. Defense radar programs in the United States and phased-array systems in Taiwan specify SiC-native architectures, locking in long-term supply commitments with Japanese crystal growers.
- Sapphire:Alumina templates dominate LED volume manufacturing through established MOCVD infrastructure and sub-$100 wafer pricing. Display panel manufacturers in South Korea and Taiwan rotate sapphire inventory rapidly, with monthly procurement cycles tied to backlighting and micro-LED pilot lines.
- NiO:Nickel oxide buffer layers on silicon substrates enable low-cost GaN epitaxy for consumer power adapters below 100W. Shenzhen-based charger OEMs qualify NiO-backed wafers for 65W USB-C ramps, compressing substrate costs toward silicon economies.
- Bulk GaN:Native gallium nitride substrates eliminate lattice mismatch defects for laser diodes and high-reliability space electronics. Defense procurement offices in Japan and the United States unbundle bulk GaN qualification from device contracts, creating direct purchasing relationships with specialized crystal growers.
Sapphire anchors the volume base while bulk GaN gains share at the steepest rate.
Technology:
Capital intensity separates batch-process techniques from continuous-flow manufacturing, with equipment utilization rates determining foundry gate fees.
- MOCVD:Metal-organic chemical vapor deposition commands manufacturing scale for LED and power device epitaxy through multi-wafer reactor configurations. Foundries in Taiwan and South Korea operate MOCVD clusters at 90% utilization, with reactor operator scarcity constraining expansion timelines.
- HVPE:Hydride vapor phase epitaxy produces thicker GaN layers for RF and laser diode segments where breakdown voltage requirements exceed MOCVD capabilities. Specialist producers in Japan and Germany maintain HVPE capacity for defense and telecommunications qualification programs.
- LPE:Liquid phase epitaxy serves niche optoelectronic applications requiring ultra-low defect densities. Japanese substrate vendors deploy LPE for high-brightness laser diodes in automotive lidar systems.
- Epitaxy:Generic epitaxial growth services encompass MBE and other specialized techniques for research and prototype volumes. European compound semiconductor traders consolidate epitaxy supply chains to reduce ECHA REACH registration duplication.
MOCVD captures the revenue concentration while HVPE commands the premium pricing tier.
End User:
Automotive qualification cycles stretch 36 months for traction inverters, while consumer electronics turns inventory quarterly.
- Telecommunications:5G base station deployments in the United States drive FCC Part 27-compliant GaN RF amplifier demand, with infrastructure OEMs specifying SiC substrates for C-band and mmWave power stages. Equipment vendors in South Korea and Taiwan lock in multi-year substrate agreements.
- Automotive:German and Japanese OEMs specify 650V GaN devices for onboard chargers and traction inverters, pulling wafer demand from LED-centric supply chains. Device-package thermal interface qualification with sintered silver bonding processes delays Tier 1 approvals.
- Consumer Electronics:Smartphone and laptop charger manufacturers in Shenzhen and Taipei qualify GaN-on-Si substrates for sub-100W adapters. The segment rotates inventory fastest, with monthly procurement cycles tied to seasonal device launches.
- Aerospace:Satellite communications and electronic warfare systems specify GaN-on-SiC for phased-array transmitters. Defense procurement offices unbundle substrate qualification from device fabrication, creating direct relationships with crystal growers.
Telecommunications provides the demand foundation while automotive expands most quickly.
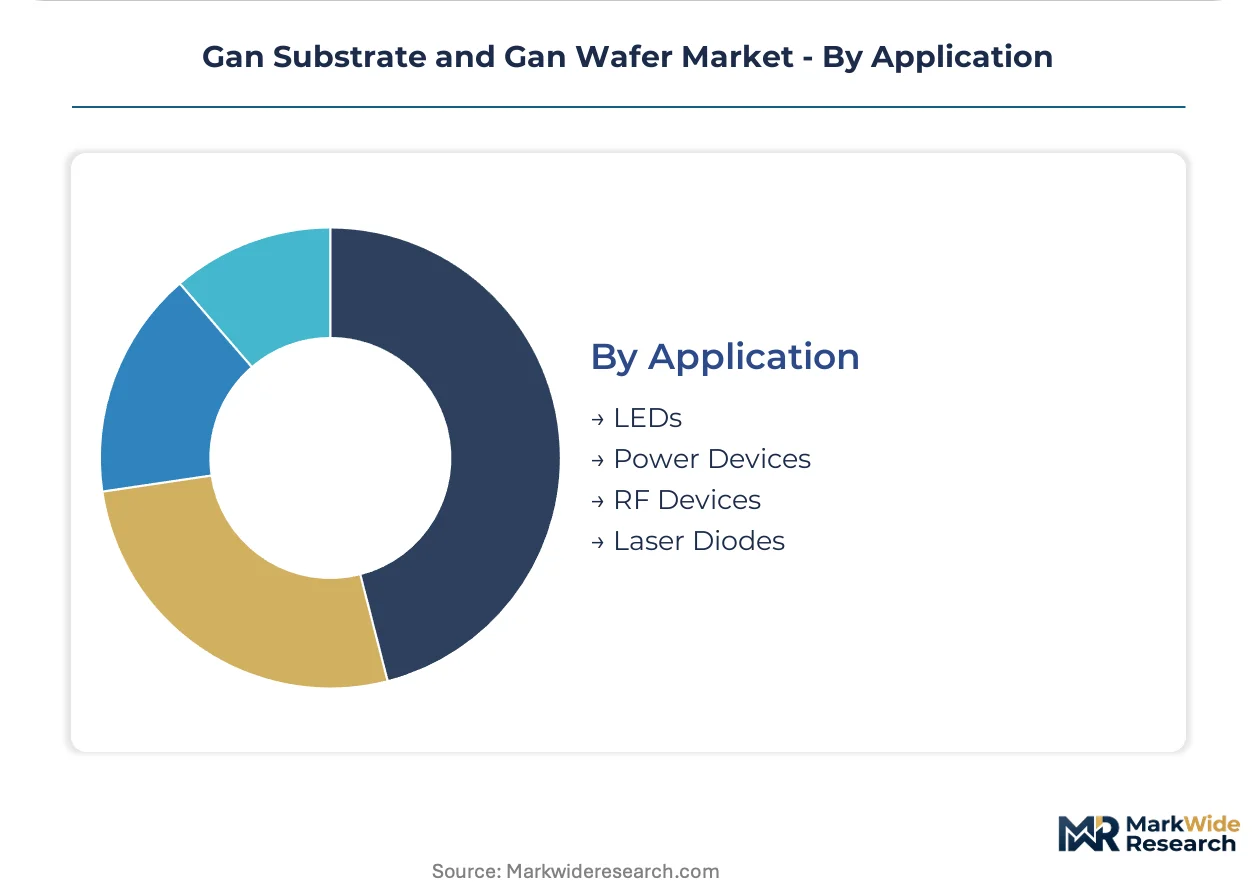
Application:
LED manufacturing consumes substrate area at the highest velocity, while RF device qualification extends across years.
- Power Devices:650V GaN HEMTs displace silicon superjunction MOSFETs in automotive onboard chargers and industrial motor drives. German and Japanese automotive OEMs specify these devices, pulling wafer demand from established LED supply chains.
- RF Devices:High-frequency power amplifiers for 5G infrastructure and defense radar require SiC-native substrates for thermal management. FCC Part 27 spectrum efficiency mandates in the United States accelerate substrate qualification timelines for C-band and mmWave base stations.
- LEDs:General lighting and display backlighting consume the highest substrate volume through sapphire-backed configurations. South Korean and Taiwanese display panel manufacturers rotate LED wafer inventory monthly.
- Laser Diodes:Optical data transmission and automotive lidar specify thicker GaN layers through HVPE growth. Japanese producers dominate specialist supply for telecommunications and sensing applications.
LEDs anchor the volume base while power devices climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese crystal growers export high-purity SiC boules to Taiwanese foundries and Korean device manufacturers, forming the dominant trade corridor in GaN substrate supply chains.
United States
FCC Part 27 spectrum efficiency mandates accelerate GaN RF amplifier deployment in C-band and mmWave base stations. Defense procurement offices unbundle substrate qualification from device contracts, creating direct purchasing relationships with specialized crystal growers. Wolfspeed leverages captive SiC crystal growth in North Carolina to control supply from boule to epi-ready wafer.
Japan
METI-backed compound semiconductor initiatives support domestic substrate production for defense and satellite communications. Sumitomo Electric Industries anchors high-purity GaN substrate supply for phased-array transmitters. Tokyo-Osaka industrial corridors concentrate HVPE specialist capacity for telecommunications qualification programs.
Taiwan
Foundries in Hsinchu Science Park operate MOCVD clusters at 90% utilization for LED and power device epitaxy. Defense radar modernization programs specify GaN-on-SiC for military electronic warfare systems, locking in multi-year substrate supply agreements. Reactor operator scarcity constrains expansion timelines despite capital availability.
South Korea
Display panel manufacturers in Seoul-Busan corridors rotate sapphire-backed LED wafer inventory monthly for backlighting and micro-LED pilot lines. 5G infrastructure OEMs specify SiC substrates for C-band power stages, securing long-term agreements with Japanese crystal growers. Samsung and SK hynix anchor demand for 200mm diameter transitions.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify 650V GaN devices for onboard chargers and traction inverters. ECHA REACH restrictions on gallium processing chemicals add documentation burden to substrate importers, lengthening qualification cycles. EU Green Deal carbon border adjustments favor wafer exporters with verified low-crystal-growth footprints.
Gan Substrate and Gan Wafer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Japanese and American crystal growers dominate high-purity SiC boule supply, while Taiwanese and Korean foundries control epitaxy capacity. Three archetypes emerge: captive-integrated substrate producers, independent epi-foundries, and defense-focused bulk GaN specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as diameter transitions from 150mm to 200mm reshape equipment economics.
Among American substrate producers, Wolfspeed and Cree exemplify the captive-integrated archetype through upstream control over SiC crystal growth. Sumitomo Electric Industries anchors the Japanese specialist tier. These three companies represent distinct strategic positions: Wolfspeed and Cree occupy scale-driven, vertically integrated roles, while Sumitomo Electric Industries exemplifies the high-purity, defense-oriented specialist model.
| Leading Market Players |
|---|
| Wolfspeed |
| Sumitomo Electric Industries |
| Cree |
| GaN Systems |
| Infineon Technologies |
| Mitsubishi Electric |
| STMicroelectronics |
| Six Point Materials |
| Sino Nitride |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Japanese SiC boule suppliers compresses pricing tier spreads while forcing foundries into long-term offtake commitments that lock in cost structures. FCC Part 27 qualification requirements and ECHA REACH compliance costs simultaneously widen premiums for certified substrates and reshape procurement toward vertically integrated crystal growers.
Pricing Analysis
150mm-to-200mm diameter transition pricing gaps separate mature-node substrates from next-generation wafer economics. Three-tier pricing structure across defense-qualified, automotive-certified, and consumer-grade tiers reflects FCC certification timelines and thermal performance specifications. Cost compression in sapphire-backed LED substrates intensifies because Chinese capacity expansion outpaces display panel demand growth. Consumer electronics OEMs in Shenzhen exhibit highest price sensitivity, while defense procurement offices accept 40-60% premiums for boule-provenance documentation.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries to Japanese crystal growers now stretch 90-120 days, straining working capital for independent boule producers. Supply concentrates in Japan, Taiwan, and the United States for SiC crystal growth, with South Korean display manufacturers drawing from sapphire substrate networks anchored in China. High-purity gallium and rare earth processing chemicals rest on Chinese and Kazakh mining outputs. Single-source vulnerability persists for 6-inch defect-free SiC substrates qualified for phased-array radar. Distribution runs through foundry-direct contracts for RF device tiers and spot-market procurement for LED volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FCC Part 27 qualification timelines creates switching costs that cement incumbent positions. Device OEMs cannot substitute qualified substrate suppliers without restarting 18-month certification cycles.
For Market Incumbents: Pre-empt emerging GaN-on-Si epitaxy challengers by accelerating 200mm SiC capacity additions in North Carolina and Aichi Prefecture. Lock in multi-year supply agreements with Taiwanese foundries before India's PLI scheme matures domestic substrate alternatives. Prioritize captive crystal growth investments to defend margin position against independent boule traders. For New Entrants and Emerging Players: India's compound semiconductor fabrication incentives represent the most penetrable geographic entry point for GaN device qualification programs. Target automotive onboard charger segments where thermal interface qualification delays create windows for new substrate suppliers. Pursue joint qualification partnerships with German Tier 1 suppliers seeking second-source diversification for 650V device supply chains. For Investors and Strategic Acquirers: Bulk GaN crystal specialists with defense procurement relationships offer the strongest acquisition target archetype for long-term viability across the next decade. Monitor FCC Part 27 enforcement intensity and mmWave infrastructure deployment velocity as inflection indicators for RF substrate demand acceleration. Watch for Japanese METI subsidy expansions that would signal state-backed consolidation of domestic substrate capacity.| Strategic Initiative | Industry Significance |
|---|---|
| 200mm Diameter Transition | Equipment amortization compression at Wolfspeed and Sumitomo reshapes foundry gate economics. |
| Defense Procurement Unbundling | Direct substrate qualification contracts bypass traditional distribution channels for phased-array systems. |
| India PLI Scheme Entry | Production-linked incentives create first-mover sourcing advantages for GaN device fabrication. |
| ECHA REACH Compliance Consolidation | German and French traders reduce chemical registration duplication through supply chain integration. |
| Micro-LED Pilot Line Expansion | South Korean display manufacturers accelerate sapphire-backed wafer demand outside lighting applications. |
Methodological Framework
The analysis maps SiC-native, sapphire-backed, NiO-buffered, and bulk GaN substrate sub-sectors, each validated through substrate procurement managers at Taiwanese foundries, epitaxy reactor operators, defense contract officers, and automotive Tier 1 qualification engineers. Primary interview data triangulates against SEC 10-K filings from crystal growth equipment vendors, Japanese METI compound semiconductor initiative disclosures, FCC Part 27 regulatory dockets, and customs trade records for high-purity gallium imports. Bottom-up wafer demand modeling cross-checks against top-down RF amplifier and LED market sizing.
Assumption sets held substrate diameter transition timelines and FCC enforcement intensity fixed while varying India's PLI scheme uptake rates and EU carbon border adjustment implementation scope across the projection horizon. Segmentation dimensions include product type, growth technology, end-use vertical, and regional fabrication cluster. CAGRs derive from equipment vendor shipment backlogs and foundry utilization rate trajectories. Forecast inputs incorporate MOCVD reactor operator wage inflation and SiC boule defect density improvement curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed substrate entrants or accelerated EU REACH authorization withdrawals would shift outcomes. Macroeconomic contraction in 5G infrastructure capex, regulatory relaxation of silicon superjunction efficiency thresholds, or breakthroughs in GaN-on-Si buffer architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Mask Alignment Lithography Market