
 Global Broad Ion Beam Technology Market | 2026-2036
Global Broad Ion Beam Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Broad Ion Beam Technology Market Intelligence
The European Union's RoHS directive, which restricts hazardous substances in electronic equipment, is repositioning the material selection criteria for thin film deposition and etching processes. Veeco Instruments Inc. specializes in deposition and etching systems critical for these compliant manufacturing lines. Oxford Instruments leverages its expertise in plasma processing to offer solutions for advanced materials research. JEOL Ltd. competes with a strong focus on electron optics and analytical instrumentation for semiconductor inspection.
Broad ion beam technology involves directing a large-diameter, collimated stream of energetic ions, typically inert gases like Argon, onto a substrate. This process enables uniform surface modification, etching, or thin film deposition over wide areas, essential for high-throughput manufacturing. Ion beam etching systems represent a dominant product category, driven by their precision in patterning microelectronic circuits. Within applications, semiconductor fabrication holds the largest share, while data storage manufacturing presents a significant secondary market.
Compliance with standards from bodies like the US Environmental Protection Agency (EPA) on process chemicals and the EU's CE marking for machinery safety governs equipment design. In China, Ministry of Industry and Information Technology (MIIT) directives on semiconductor manufacturing influence technology adoption. Equipment manufacturers must navigate these divergent regional standards while balancing performance requirements for next-generation device architectures.
Market Dynamics
The primary force shaping the market is the semiconductor industry's inexorable push toward sub-7 nanometer process nodes. This transition makes the high-precision material modification capabilities of broad ion beams an essential, rather than optional, technology for fabricating advanced logic and memory devices.
Growth Catalysts
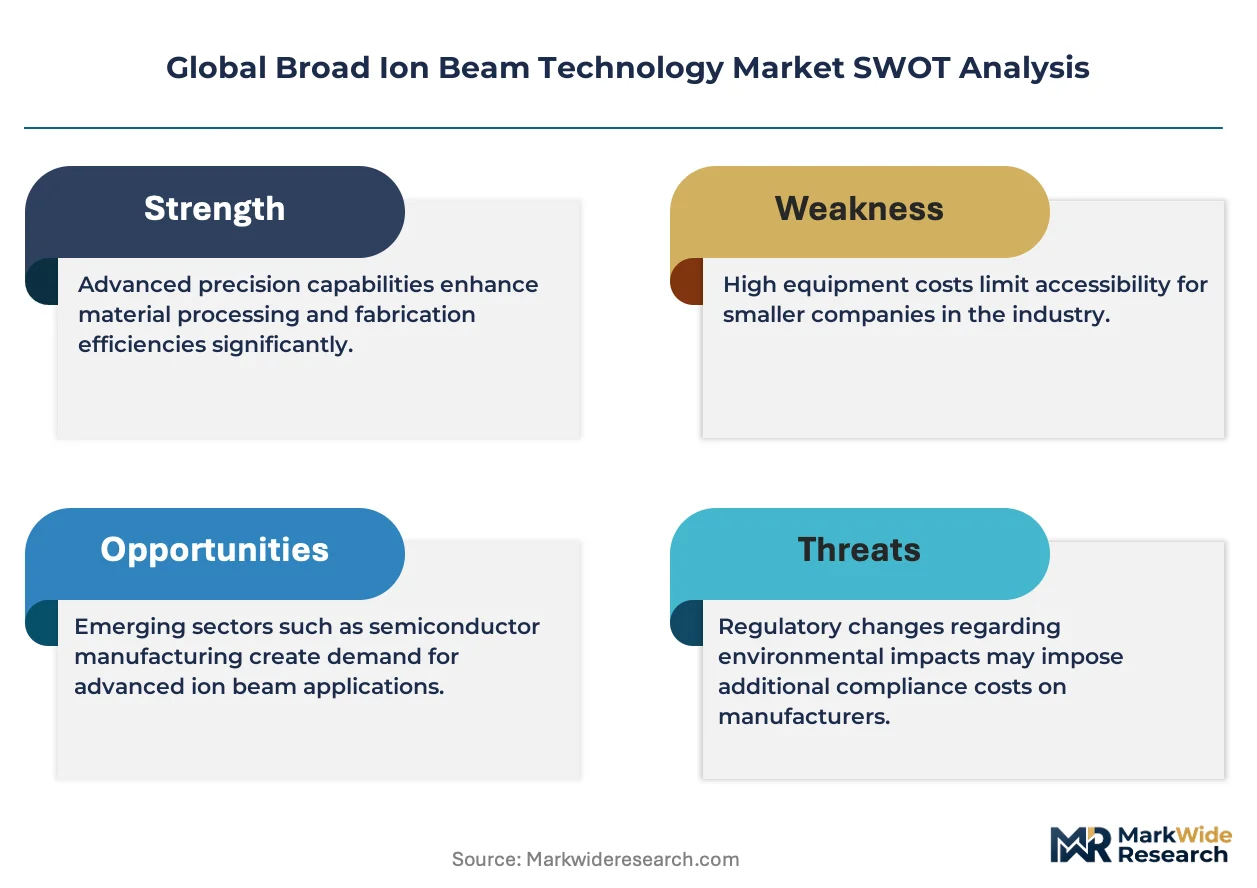
- Advanced Device Architectures:The fabrication of 3D NAND memory and gate-all-around transistors requires exceptional uniformity in etching and deposition over large wafer areas, a core capability of broad ion beam systems.
- Geographic Concentration of Fabrication:Massive capital investment in new semiconductor foundries, particularly in Taiwan and South Korea, directly translates into concentrated demand for high-throughput ion beam equipment.
- Regulatory Material Shifts:The EU's RoHS directive is forcing a transition to new, compliant materials for thin film deposition, creating demand for ion beam processes to qualify and control these novel layers in manufacturing.
Market Restraints
- High Capital and Operating Costs:The initial acquisition cost of broad ion beam systems is substantial, and operating expenses are impacted by the price of high-purity inert gases like Argon and Xenon.
- Substrate Damage Potential:Energetic ions can cause unintended damage or charging effects on sensitive semiconductor substrates, necessitating complex process control and optimization to maintain device yield.
- Competition from Plasma Etching:For certain less critical applications, advanced plasma etching technologies can offer higher material removal rates, presenting a viable substitute that challenges broad ion beam adoption.
Strategic Opportunities
- Emerging Display Technologies:Fabricating next-generation micro-LED displays requires uniform processing over very large areas, presenting a significant new application for broad ion beam deposition and etching systems.
- National Semiconductor Initiatives:Government-backed programs, such as India's PLI scheme for electronics, create opportunities to supply equipment to new, state-supported semiconductor manufacturing ecosystems.
- Process Control Integration:There is an opportunity to combine ion beam systems with in-situ metrology and AI-driven feedback loops, creating intelligent modules that optimize process parameters in real-time.
Industry Challenges
- Specialized Talent Scarcity:A shortage of process engineers and technicians with deep expertise in ion beam physics and equipment operation for sub-10nm nodes hinders technology adoption and optimization.
- Divergent Regulatory Compliance:Equipment manufacturers face complexity in designing systems that comply with a patchwork of regional standards, including US EPA chemical rules and China's MIIT manufacturing directives.
- Cleanroom Integration Hurdles:Integrating large, modern ion beam tools into existing, highly optimized cleanroom layouts without disrupting established wafer fabrication workflows presents a significant logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Broad Ion Beam Technology Market |
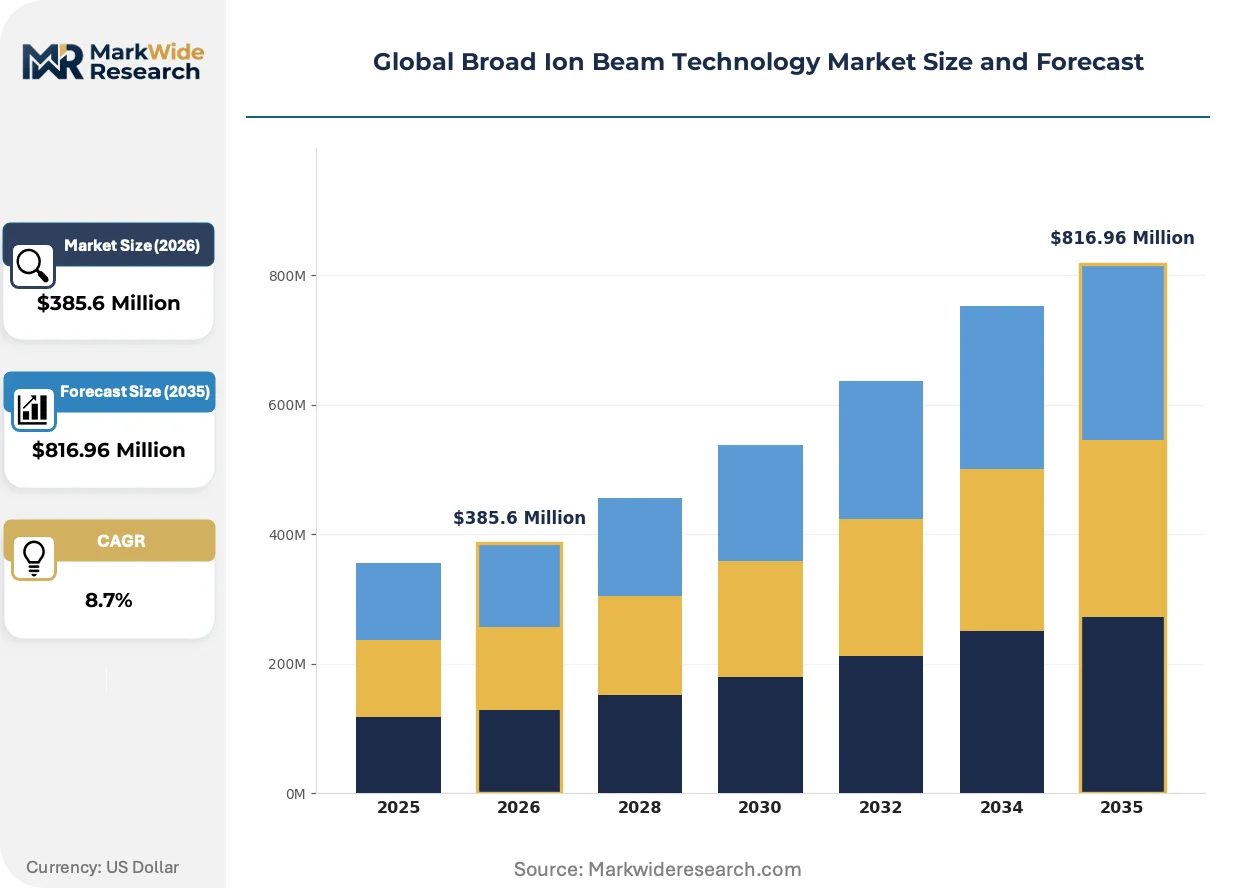
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broad Ion Beam Sources, Ion Beam Etching Systems, Deposition Tools, Ion Implantation Equipment, Surface Modification Devices Technology: Inductively Coupled Plasma, Radio Frequency, Electron Cyclotron Resonance, Microwave Plasma, Magnetron Sputtering Application: Semiconductor Fabrication, Data Storage Manufacturing, Thin Film Coating, Optical Component Processing, MEMS Production End User Industry: Microelectronics Manufacturers, Research Laboratories, Photonics Companies, Nanotechnology Firms, Surface Engineering Providers |
| Companies Covered | Oxford Instruments, Thermo Fisher Scientific Inc., Veeco Instruments Inc., Nordiko Technical Services Ltd., JEOL Ltd., Hitachi High-Technologies Corporation, Raith GmbH, Scia Systems GmbH, Canon Anelva Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Broad Ion Beam Technology Market Strategic Shifts & Innovations
Material diversification and atomic-scale process control are defining the next generation of broad ion beam technology. The development of new device architectures in the semiconductor industry is accelerating the need for systems that can handle novel materials with extreme precision.
Cluster tool configurations, which integrate multiple process chambers around a central automated transfer module, are gaining traction. Semiconductor fabs are adopting these integrated platforms to minimize wafer exposure to ambient conditions and prevent cross-contamination between etching and deposition steps. This integrated approach is overtaking the use of standalone, single-process tools for high-volume manufacturing of complex, multi-layered devices.
The European Union's RoHS directive continues to influence material selection in the electronics supply chain. This regulation forces manufacturers to qualify new, compliant materials for applications like thin film deposition and etching. The semiconductor fabrication segment is most impacted, requiring precise process control from ion beam systems to ensure the performance and reliability of these alternative material layers.
A notable shift from simple equipment sales to collaborative process development partnerships is altering commercial relationships. This model disrupts the traditional transactional dynamic, embedding equipment suppliers more deeply into the R&D activities of leading chipmakers. This trend is most prominent in the advanced logic and data storage sectors, particularly in Taiwan, where co-development accelerates the deployment of new process nodes.
Global Broad Ion Beam Technology Market Segmentation
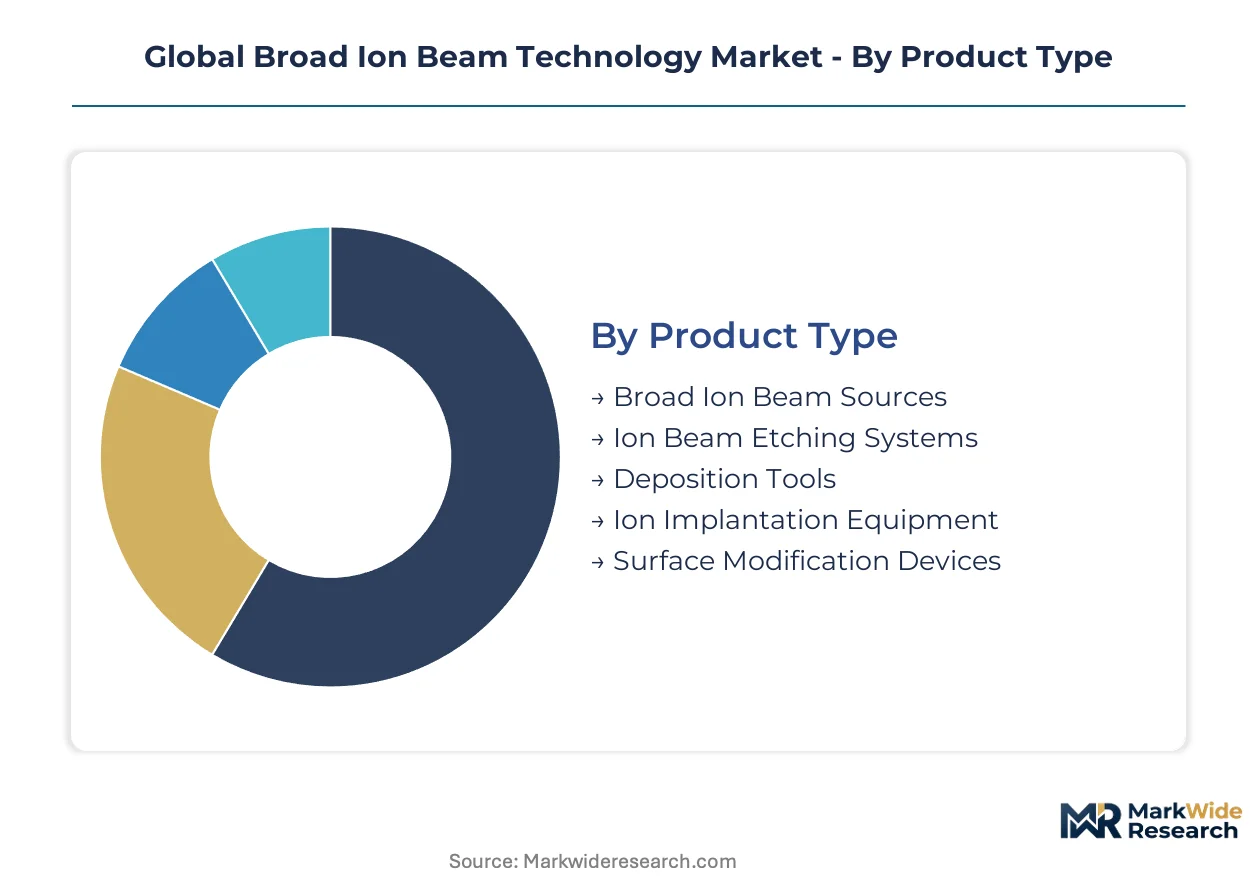
The broad ion beam technology market's segmentation reveals how specialized solutions address the evolving demands of advanced manufacturing. Analyzing these distinct categories helps stakeholders understand where technological upgrades are most critical for next-generation device fabrication.
Product Type:
The upgrade cycle for broad ion beam systems often revolves around enhancing precision and throughput for smaller process nodes.
- Ion Beam Etching Systems:These systems precisely remove material at the atomic level, crucial for patterning sub-7 nanometer microelectronic circuits. Demand concentrates in semiconductor manufacturing hubs like Taiwan, where advanced logic and memory production dominates.
- Deposition Tools:Broad ion beam deposition systems create uniform thin films with controlled material properties, essential for compliant manufacturing lines adopting new materials under directives like the EU's RoHS. These tools are critical for creating novel material layers in advanced semiconductor devices.
- Broad Ion Beam Sources:These components generate the energetic ion streams used in various processing applications, supporting the core function of all ion beam systems.
- Ion Implantation Equipment:This equipment introduces dopants into semiconductor wafers to alter electrical properties, a fundamental step in device manufacturing.
- Surface Modification Devices:These tools alter the physical or chemical properties of material surfaces, improving adhesion, hardness, or biocompatibility across various industries.
Volume placements concentrate in Ion Beam Etching Systems; the faster expansion belongs to Deposition Tools.
Technology:
The application focus for broad ion beam technologies dictates the selection of specific plasma generation methods, each offering distinct advantages in process control and material compatibility.
- Inductively Coupled Plasma:This technology generates high-density plasma with independent control over ion energy and flux, providing superior process control for etching and deposition of complex materials. Microelectronics manufacturers widely adopt this for critical processing steps.
- Radio Frequency:RF plasma systems are versatile, offering a balance of performance and cost-effectiveness for various material processing applications, including surface cleaning and thin film growth. Research laboratories frequently employ these systems for material science studies.
- Electron Cyclotron Resonance:ECR sources produce very high-density, low-energy plasma, minimizing substrate damage during delicate etching or deposition processes.
- Microwave Plasma:Microwave-generated plasma offers high process rates and efficient gas dissociation, suitable for specific surface treatment and film deposition tasks.
- Magnetron Sputtering:This physical vapor deposition technique uses magnetic fields to confine plasma, enabling efficient deposition of thin films with excellent adhesion and uniformity.
The most significant market volume is driven by Inductively Coupled Plasma, while Electron Cyclotron Resonance technology is gaining share fastest.
Application:
The volume concentration within broad ion beam technology applications is heavily skewed towards high-precision manufacturing sectors requiring atomic-scale control over materials.
- Semiconductor Fabrication:This application holds the largest market share, using broad ion beams for critical etching, deposition, and surface preparation steps in advanced logic and memory device production. The inexorable push toward sub-7 nanometer process nodes drives demand here.
- Data Storage Manufacturing:Broad ion beam technology is vital for producing high-density magnetic recording heads and media, ensuring precise material modification for increased storage capacity. This segment represents a significant secondary market for ion beam equipment.
- Thin Film Coating:Ion beam deposition techniques create high-quality, dense, and adherent thin films for various optical, protective, and functional coatings.
- Optical Component Processing:Broad ion beams enable precise surface finishing and etching of lenses, mirrors, and waveguides for high-performance optical devices.
- MEMS Production:Micro-electromechanical systems fabrication relies on broad ion beam etching for creating intricate 3D structures with high aspect ratios.
The largest application volume resides in Semiconductor Fabrication, with Data Storage Manufacturing exhibiting the steepest expansion trajectory.
End User Industry:
Customer type defines the specific requirements for broad ion beam systems, ranging from high-volume production capabilities to flexible research tools.
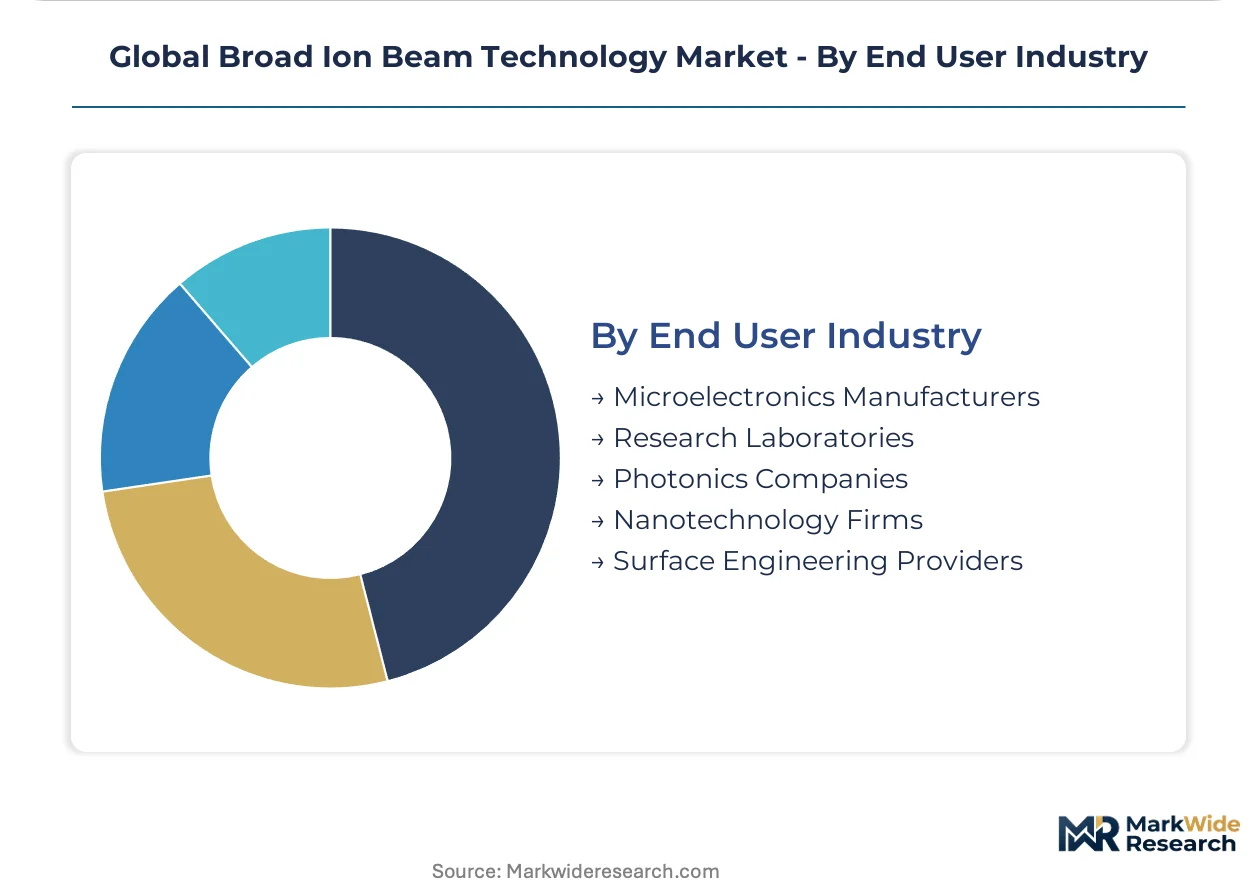
- Microelectronics Manufacturers:These firms are the primary end-users, integrating ion beam systems into their fabrication lines for advanced semiconductor devices. Their demand is driven by the need for high-throughput, high-precision processing for chips.
- Research Laboratories:Academic and industrial research facilities utilize broad ion beam tools for materials science, nanotechnology development, and process optimization. These labs require versatile systems for diverse experimental needs.
- Photonics Companies:Businesses involved in optical components and integrated photonics leverage ion beam technology for precise etching and deposition of optical films.
- Nanotechnology Firms:Companies operating at the nanoscale use broad ion beam systems for fabricating novel nanomaterials and nanodevices.
- Surface Engineering Providers:These specialists apply ion beam techniques to modify material surfaces for enhanced performance in various industrial contexts.
The largest customer base is Microelectronics Manufacturers, while Nanotechnology Firms are accelerating their adoption of these advanced systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park, a prominent tax-incentive zone, drives concentrated demand for broad ion beam technology. This park, along with other global semiconductor manufacturing hubs, fuels the expansion of advanced fabrication capabilities. These regions necessitate high-precision material modification for next-generation device architectures.
Taiwan
Massive capital investment in new semiconductor foundries drives demand for high-throughput ion beam equipment. The Taiwanese government's initiatives support advanced process technology development. Hsinchu Science Park remains a crucial center for TSMC's leading-edge logic and memory production.
South Korea
The fabrication of 3D NAND memory and gate-all-around transistors requires exceptional uniformity in etching and deposition. South Korea's K-Semiconductor Strategy promotes domestic chip manufacturing capabilities. Pyeongtaek and Cheonan facilities expand for major players like Samsung and SK Hynix.
United States
High-precision material modification capabilities are essential for advanced logic and memory device production. The US CHIPS Act provides significant funding to bolster domestic semiconductor manufacturing. Arizona and Texas are seeing substantial new foundry investments from leading chipmakers.
China
The push for domestic semiconductor self-sufficiency stimulates demand for ion beam systems. Ministry of Industry and Information Technology (MIIT) directives influence technology adoption in chip fabrication. Shanghai and Beijing serve as key centers for indigenous chip production and R&D.
Japan
Advanced materials research and electron optics applications create specific demand for broad ion beam systems. METI initiatives support the development of semiconductor equipment and materials. Kyushu and Tohoku regions focus on advanced device manufacturing and specialized materials processing.
Global Broad Ion Beam Technology Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the broad ion beam technology market. The market exhibits a tiered structure, with established players offering comprehensive solutions alongside niche providers. Strategic archetypes include integrated system manufacturers, component suppliers, and service-oriented firms. Competitive moves often involve strategic partnerships for process development and targeted acquisitions to expand technological capabilities.
Among the specialized equipment providers, Veeco Instruments Inc. and Oxford Instruments exemplify companies with strong positions in deposition and etching systems. Veeco Instruments Inc. focuses on critical manufacturing lines, while Oxford Instruments leverages plasma processing expertise for advanced materials research. JEOL Ltd. represents a significant player in electron optics and analytical instrumentation for semiconductor inspection, anchoring the high-precision metrology segment.
| Leading Market Players |
|---|
| Oxford Instruments |
| Thermo Fisher Scientific Inc. |
| Veeco Instruments Inc. |
| Nordiko Technical Services Ltd. |
| JEOL Ltd. |
| Hitachi High-Technologies Corporation |
| Raith GmbH |
| Scia Systems GmbH |
| Canon Anelva Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration into process development by equipment manufacturers anchors their supply position and enhances pricing power for advanced broad ion beam systems. This strategic alignment ensures premium valuation for solutions critical to sub-7 nanometer fabrication.
Pricing Analysis
Premium pricing for short lead times reflects the urgent demand for broad ion beam systems in advanced semiconductor fabrication. Transactional models, often bundled with long-term service contracts, define the pricing structure. Price differentiation stems from customization for specific process nodes and comprehensive after-sales support. Pricing pressure remains upward, driven by intense R&D investments; Microelectronics Manufacturers prioritize performance, while research laboratories show higher price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in the broad ion beam technology supply chain. Supply concentration for highly specialized sub-components remains high, primarily in Japan, the United States, and Germany. The industry relies on high-purity inert gases like Argon and Xenon, along with precision vacuum components; single-source vulnerability for certain niche optics presents a structural risk. Direct sales channels to Microelectronics Manufacturers and research institutions define the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The broad ion beam technology market is navigating a critical technology-transition phase, with advanced plasma etching technologies challenging traditional ion beam adoption for less critical applications. This shift necessitates strategic repositioning for all market participants.
For Market Incumbents: To counter competition from plasma etching technologies, incumbents must deepen vertical integration into advanced process control software. Strategic partnerships with leading chipmakers for co-development of next-generation sub-7 nanometer solutions will solidify market position. Investing in R&D for ECR technology offers a lever to minimize substrate damage. Capacity additions in Taiwan will also support high-volume manufacturing demands.
For New Entrants and Emerging Players: Capture emerging opportunities in micro-LED display fabrication, which demands uniform processing over very large areas. Targeting national semiconductor initiatives, such as India's PLI scheme, offers a penetrable segment for new equipment suppliers. Focusing on process control integration with AI-driven feedback loops provides a strong go-to-market angle. Nanotechnology firms represent a white space for specialized surface modification devices.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by larger diversified conglomerates seeking to expand their high-precision manufacturing portfolios. The market demonstrates long-term viability, driven by the semiconductor industry's continuous demand for advanced process nodes over the next decade. Acquisition targets should be pure-play specialists with proprietary ECR or ICP technology. A signal to watch is the increasing patent activity in atomic-scale process control.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Process Control Integration | Integrating in-situ metrology with AI optimizes process parameters for sub-7 nanometer device fabrication. |
| Micro-LED Display Application Development | Expanding broad ion beam capabilities for uniform processing addresses next-generation display technology requirements. |
| Geographic Foundry Expansion Partnerships | Collaborating with new semiconductor foundries in Taiwan and South Korea secures equipment demand. |
| High-Purity Gas Supply Chain Optimization | Securing reliable sources of Argon and Xenon mitigates operating cost volatility for manufacturers. |
| ECR Technology R&D Investment | Developing Electron Cyclotron Resonance systems minimizes substrate damage during delicate etching processes. |
Research Approach
Industry reports, academic journals, and company filings formed the secondary backbone for this analysis, providing foundational market data. Primary interviews with semiconductor fabrication executives, process engineers, and equipment procurement managers offered qualitative insights. This approach combined top-down market sizing with bottom-up validation, ensuring comprehensive data triangulation. Regulatory documents from the US EPA and EU RoHS directive further informed the market landscape.
Historical trendline analysis provided the basis for projecting market evolution across the analysis window. The forecast framework modeled market segments by product type, technology, application, and end-user industry. Compound annual growth rates were derived from a multi-variable regression model, incorporating technological advancements and capital expenditure plans. Semiconductor manufacturing capacity expansions and global economic indicators served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and rapid technological breakthroughs. Projections reflect current assumptions regarding semiconductor demand and regulatory stability. Deviation in global trade policies or the pace of sub-7 nanometer adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market