
 Silicon Tuners Market | 2026-2036
Silicon Tuners Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Tuners Market Analytics
Multi-source procurement among broadcast equipment OEMs is rebalancing toward qualified second-source silicon tuner suppliers. NXP Semiconductors leverages its RF portfolio breadth to sustain design wins across terrestrial and cable segments. STMicroelectronics anchors European supply through vertically integrated fabrication in France and Italy. MaxLinear competes aggressively in the North American cable and satellite tuner segment with high-integration system-on-chip architectures.
A silicon tuner is a monolithic integrated circuit that performs frequency selection, demodulation, and channel filtering for broadcast and communication signals, typically fabricated on CMOS or BiCMOS processes operating across VHF through microwave bands. These devices replace discrete ceramic and SAW filter assemblies, enabling cost reduction and footprint miniaturization in television sets, set-top boxes, and automotive receivers. Integrated tuners command the largest volume share as TV manufacturers prioritize single-chip solutions that combine RF front-end with digital demodulation. Digital technology segments are expanding fastest as ATSC 3.0, DVB-T2, and ISDB-T standards mandate digital signal processing architectures. Software-defined technology is capturing margin pools in professional broadcast and test equipment where reconfigurability offsets higher unit costs.
FCC Part 15 emissions rules in the United States constrain spurious output and shape tuner shielding and filtering requirements. ETSI EN 303 340 and RED compliance in Europe mandate interoperability across digital terrestrial television platforms. CE marking under the EU Radio Equipment Directive gates market access for tuner modules sold into consumer and automotive channels. Stakeholders must monitor spectrum reallocation decisions by national regulators and the pace of ATSC 3.0 rollout to calibrate product roadmaps and inventory positions.
Market Dynamics
Broadcast infrastructure operators are consolidating RF front-end procurement around software-defined architectures that decouple hardware from modulation standards, compressing product lifecycles and forcing silicon tuner vendors to restructure R&D roadmaps around firmware upgradeability rather than discrete hardware refreshes.
Growth Catalysts
- ATSC 3.0 deployment:Next-generation terrestrial broadcasting standards in the United States mandate digital signal processing capabilities that obsolete legacy analog tuner architectures and necessitate single-chip digital integration.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases accelerate migration from discrete filter assemblies toward monolithic silicon solutions that eliminate hermetic packaging requirements.
- Automotive receiver integration:Connected vehicle platforms in Germany and South Korea embed silicon tuners for terrestrial and satellite reception, creating incremental volume pools outside traditional consumer electronics channels.
Market Restraints
- Advanced CMOS node dependence:High-frequency RF performance requires access to 28nm and smaller fabrication processes concentrated among Taiwan-based foundries, exposing supply chains to geographic concentration risk.
- REACH compliance burden:European chemical substance restrictions increase qualification timelines and testing costs for BiCMOS process variants used in automotive-grade tuners.
- Discrete SAW filter substitution:Ceramic and surface acoustic wave filter technologies retain cost advantages in ultra-low-cost television sets, limiting silicon tuner penetration in price-sensitive emerging markets.
Strategic Opportunities
- Professional broadcast equipment:Software-defined tuner modules enable field reconfigurability across DVB-T2, ISDB-T, and ATSC 3.0 standards, commanding premium pricing in test and measurement applications.
- India broadcast digitization:Phase IV cable and terrestrial digitization mandates create first-time demand for integrated digital tuners in set-top boxes as analog switch-off deadlines approach.
- AI-driven spectrum management:Machine learning algorithms embedded in tuner firmware enable dynamic interference mitigation, opening adjacent markets in cognitive radio and dynamic spectrum access systems.
Industry Challenges
- RF analog design talent scarcity:Deep submicron CMOS RF circuit expertise concentrates among senior engineering populations in France, Germany, and the United States, constraining expansion capacity for emerging suppliers.
- Multi-standard certification complexity:Simultaneous CE marking under RED, FCC Part 15 emissions testing, and country-specific broadcast logo approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Tuners Market |
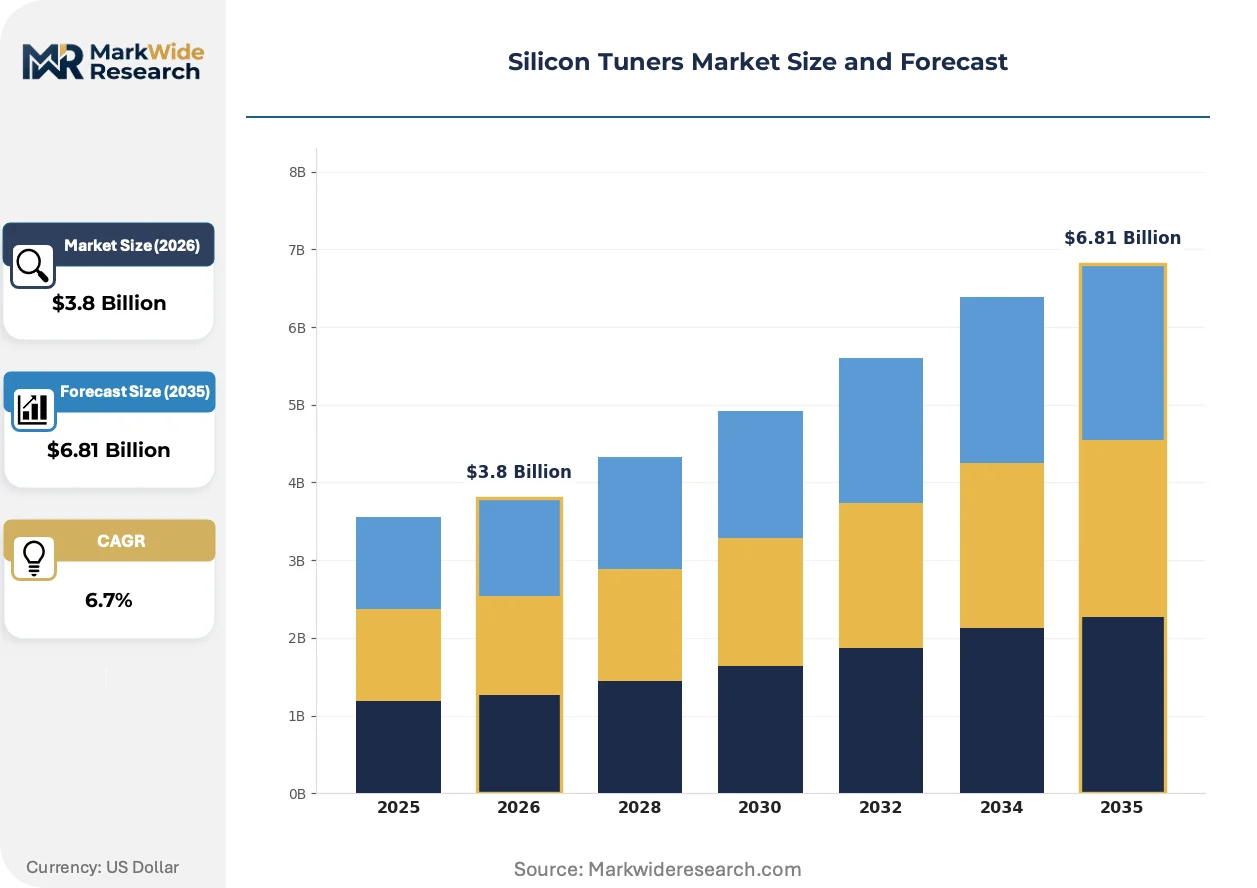
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Tuners, Integrated Tuners, Hybrid Tuners, Multi-band Tuners Technology: Analog Technology, Digital Technology, Software-Defined Technology, AI-Driven Technology End User: Consumer Electronics, Automotive Infotainment, Broadcast Systems, Telecommunications Application: TV Broadcasting, Radio Broadcasting, Satellite Communication, Internet Streaming |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Silicon Laboratories, MaxLinear, Maxim Integrated, Sony, RF Magic, Samsung Electronics, Global Silicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Tuners Market Evolving Landscape
Silicon tuner architectures are bifurcating between ultra-integrated system-on-chip solutions for high-volume consumer applications and modular software-defined platforms for professional and automotive segments requiring field upgradeability.
RF-CMOS processes operating at 28nm and below are overtaking legacy BiCMOS implementations for terrestrial and cable reception. Television OEMs in South Korea and Taiwan have completed platform transitions to CMOS-only tuner-demodulator integration. This compression of process technology is overtaking the historical cost-performance tradeoffs that previously favored mixed-signal bipolar architectures.
REACH substance restrictions and EU F-Gas phase-down schedules are forcing elimination of hermetic ceramic packages and noble metal plating in tuner modules. Module suppliers serving European consumer and automotive channels are redesigning shielding and thermal management around halogen-free substrates. German broadcast equipment manufacturers report qualification delays of 6-9 months as they validate alternative material sets against ETSI EN 303 340 interoperability requirements.
Broadcast equipment OEMs are unbundling tuner module procurement from set-top box and television platform sourcing, establishing direct relationships with qualified second-source silicon suppliers. This disintermediation of traditional EMS channel relationships is most visible in North American cable operator procurement, where MSOs now specify tuner performance requirements directly and qualify multiple silicon vendors independently of finished goods assemblers.
Silicon Tuners Market Segmentation
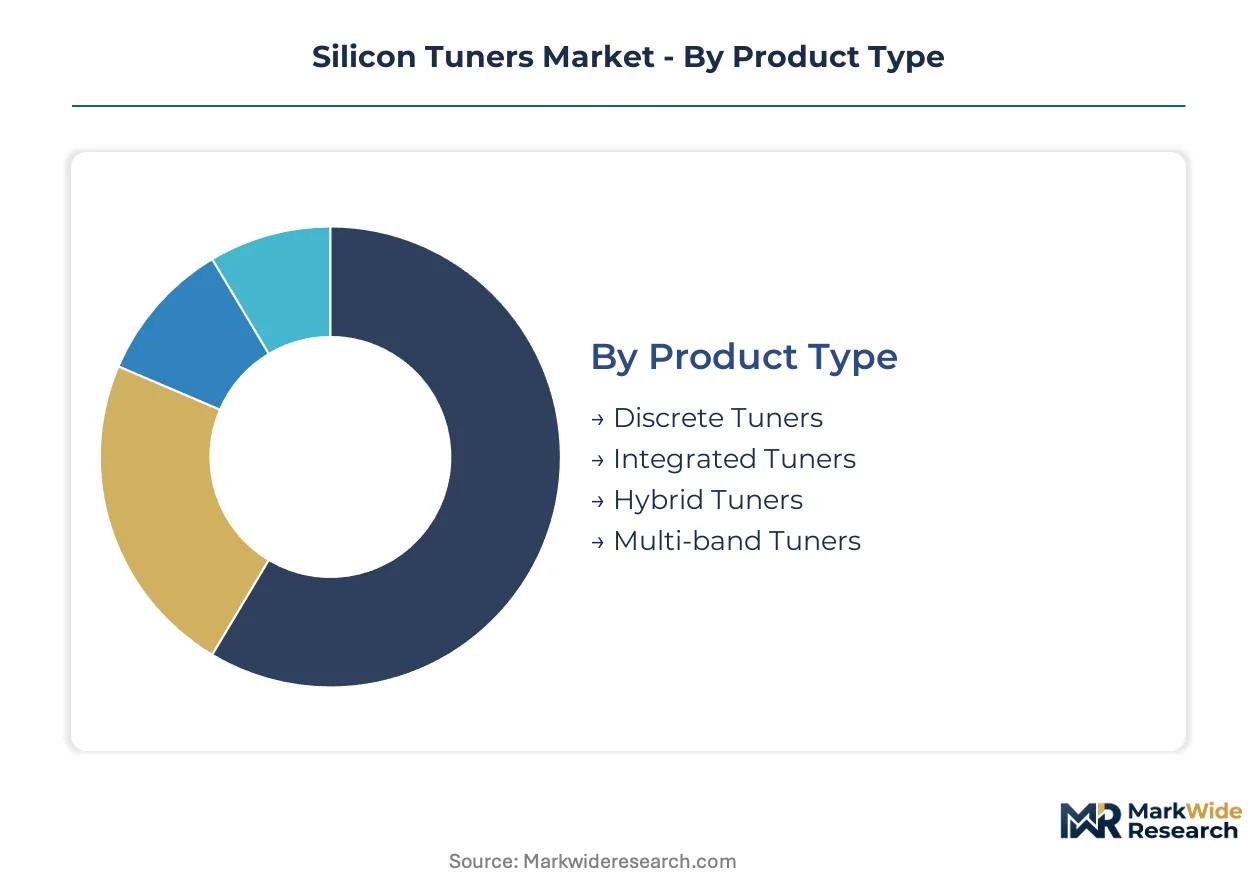
Silicon tuner procurement patterns diverge sharply between cost-driven consumer electronics and specification-critical automotive and broadcast applications. Understanding these segment boundaries clarifies where integration pressure concentrates versus where modular flexibility commands premium positioning.
Product Type:
Volume concentration favors single-chip integration, while premium pricing attaches to specialized multi-band and hybrid architectures.
- Integrated Tuners:Monolithic RF front-end with digital demodulation on single die, fabricated on 28nm CMOS. Television OEMs in South Korea and Taiwan have completed platform transitions to these solutions for terrestrial and cable reception, driven by FCC Part 15 emissions constraints on spurious output that favor consolidated shielding.
- Multi-band Tuners:Architectures spanning VHF through microwave with programmable filtering, enabling simultaneous terrestrial and satellite reception. Automotive OEMs in Germany embed these for connected vehicle platforms where field reconfigurability offsets higher unit costs against qualification timeline compression.
- Discrete Tuners:Separate RF amplification and filtering stages for cost-sensitive applications.
- Hybrid Tuners:Mixed-signal BiCMOS implementations retaining analog signal paths for legacy compatibility.
Mature deployment sits with Integrated Tuners. Newer deployment is concentrated in Multi-band Tuners.
Technology:
Process node compression is displacing legacy mixed-signal implementations, with firmware-defined architectures capturing margin in professional equipment.
- Digital Technology:Fully digital signal processing architectures compliant with ATSC 3.0, DVB-T2, and ISDB-T standards. Broadcast infrastructure operators in the United States are mandating these capabilities for next-generation terrestrial deployment, rendering analog architectures obsolete through regulatory standard rather than market preference alone.
- Software-Defined Technology:Field-programmable modulation and demodulation via firmware upgrade. Professional broadcast equipment manufacturers in Europe specify these modules for test and measurement applications where ETSI EN 303 340 interoperability testing requires rapid reconfiguration across regional standards.
- Analog Technology:Legacy bipolar implementations for cost-constrained emerging market television sets.
- AI-Driven Technology:Embedded machine learning for dynamic interference mitigation in cognitive radio applications.
Digital Technology anchors current volume. AI-Driven Technology is climbing the fastest as spectrum management automation penetrates adjacent markets.
End User:
Automotive qualification requirements create the steepest barriers to entry, while consumer electronics channels concentrate procurement leverage among EMS partners.
- Consumer Electronics:Television set and set-top box integration, representing the foundational volume pool for silicon tuner demand.
- Automotive Infotainment:Connected vehicle platforms with terrestrial and satellite reception requirements, subject to extended temperature range and vibration specifications that extend qualification timelines.
- Broadcast Systems:Professional transmission and reception equipment with field-upgradeable firmware requirements.
- Telecommunications:Base station and backhaul applications leveraging tuner architectures for signal monitoring.
Consumer Electronics maintains installed base dominance. Automotive Infotainment is gaining share fastest as embedded connectivity becomes standard specification.
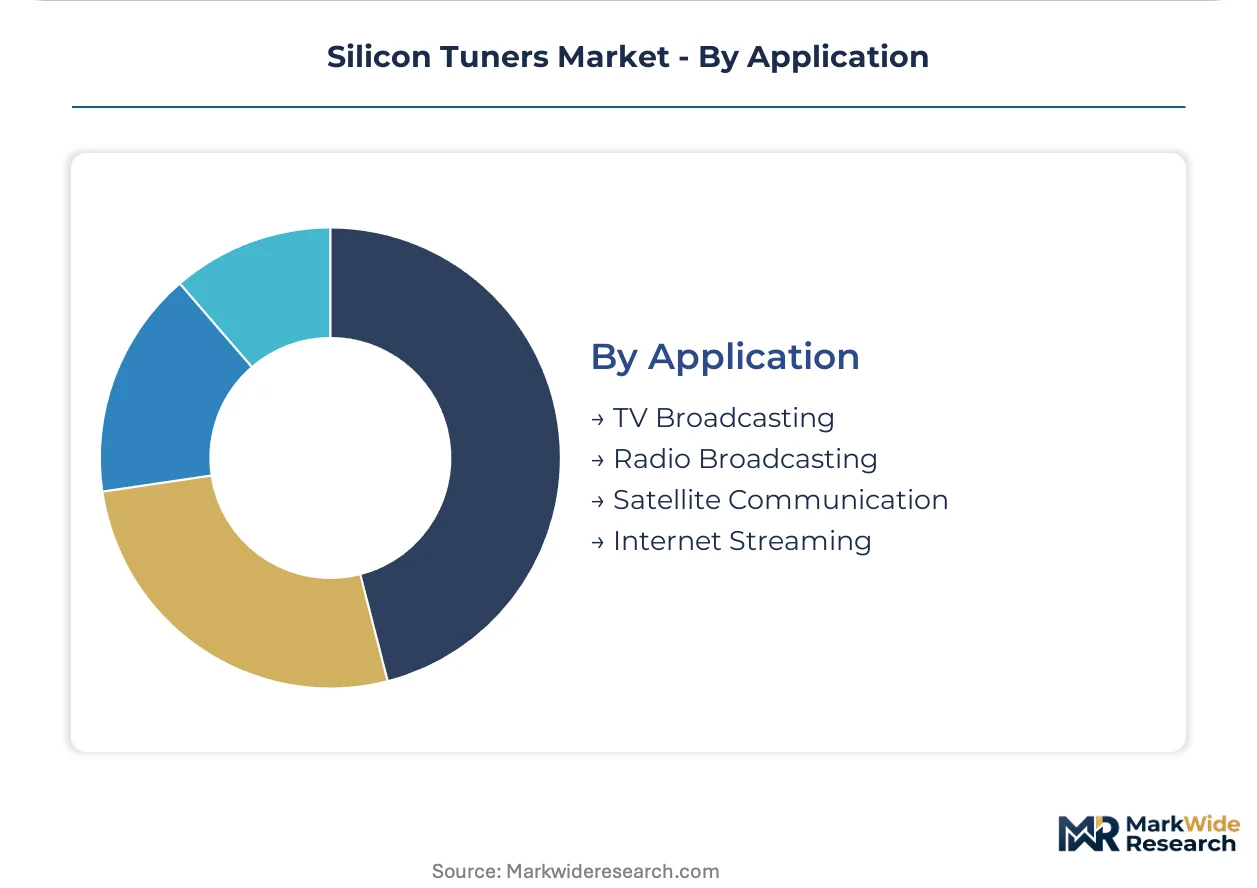
Application:
Standard evolution timing varies by geography, with ATSC 3.0 rollout in the United States running ahead of DVB-T2 migration patterns in Europe.
- TV Broadcasting:Terrestrial and cable reception for residential display devices, the original and still-dominant application category.
- Satellite Communication:Direct broadcast satellite reception with specialized low-noise block downconverter interfaces.
- Radio Broadcasting:AM/FM and digital audio broadcasting, retaining niche volume in automotive channels.
- Internet Streaming:Hybrid tuner-plus-IP architectures enabling broadcast-broadband convergence services.
TV Broadcasting represents mature deployment. Internet Streaming is expanding most quickly as hybrid service models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for silicon tuners concentrates in Germany, South Korea, and the United States, where broadcast infrastructure upgrades and semiconductor fabrication clusters intersect. These three countries anchor procurement volume for integrated tuner modules across terrestrial, cable, and automotive applications.
United States
ATSC 3.0 deployment mandates from the FCC are accelerating replacement of legacy analog tuner architectures with single-chip digital solutions. Cable operators and broadcast stations in major metropolitan markets face compliance deadlines that compress procurement timelines. Design activity clusters around Silicon Valley RF engineering centers and Austin semiconductor development corridors.
Germany
Automotive OEMs in Stuttgart and Munich embed multi-band silicon tuners for connected vehicle platforms requiring terrestrial and satellite reception. EU F-Gas Regulation and REACH compliance timelines force elimination of hermetic ceramic packages from tuner modules. Bavarian broadcast equipment manufacturers report qualification delays as they validate halogen-free substrate alternatives against ETSI EN 303 340 requirements.
South Korea
Television OEMs in Seoul and Suwon have completed platform transitions to 28nm CMOS tuner-demodulator integration for cost and footprint reduction. The country's national broadcast regulator has aligned terrestrial transmission standards with DVB-T2 specifications that mandate digital signal processing capabilities. Samsung Electronics and LG Electronics manufacturing complexes in Gyeonggi Province drive volume procurement of integrated tuner solutions.
Japan
ISDB-T standard compliance requirements shape tuner specifications for domestic television and automotive receiver markets. METI spectrum reallocation decisions influence product roadmaps for broadcast equipment manufacturers in Tokyo and Osaka. Nagoya-area automotive suppliers integrate silicon tuners for terrestrial and satellite reception in next-generation infotainment systems.
India
Phase IV cable and terrestrial digitization mandates from TRAI create first-time demand for integrated digital tuners as analog switch-off deadlines approach. Set-top box assemblers in Delhi-NCR and Mumbai qualify silicon tuner modules for cost-sensitive volume deployment. BIS certification requirements extend product launch timelines for foreign suppliers entering the market.
Silicon Tuners Market Competitive Landscape
Multi-source procurement dominates the current landscape as broadcast equipment OEMs rebalance supplier relationships toward qualified second-source silicon vendors. The vendor base concentrates around three tiers: diversified semiconductor conglomerates with RF portfolio breadth, vertically integrated European fabricators with captive production, and fabless specialists competing on high-integration system-on-chip architectures. Strategic archetypes include scale-driven volume suppliers serving consumer electronics channels, specification-critical automotive-grade specialists, and professional broadcast equipment vendors commanding premium pricing for field-upgradeable modules. Competitive moves center on foundry partnerships for advanced CMOS node access and direct qualification relationships with cable operators bypassing traditional EMS channels.
Within the diversified semiconductor tier, NXP Semiconductors and STMicroelectronics exemplify contrasting geographic and integration strategies. NXP leverages its Netherlands-based RF heritage across terrestrial and cable segments. STMicroelectronics anchors European supply security through vertically integrated fabrication in France and Italy. MaxLinear occupies a position at the fabless specialist end, competing aggressively in North American cable and satellite tuner segments with high-integration architectures. These three companies represent the structural fault lines between captive fabrication, foundry-dependent scaling, and regional market focus that define competitive positioning in this market.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Silicon Laboratories |
| MaxLinear |
| Maxim Integrated |
| Sony |
| RF Magic |
| Samsung Electronics |
| Global Silicon |
| Others |
Value Network & Pricing Analysis
Captive fabrication in France and Italy anchors STMicroelectronics' supply position and pricing power against foundry-dependent competitors. This backward integration shields margin structures from Taiwan foundry concentration risk while enabling premium positioning for automotive-grade qualification tiers. Broadcast equipment OEMs negotiate from a position of consolidated procurement leverage as direct qualification relationships replace traditional EMS channel intermediation.
Pricing Analysis
Warranty and field-upgrade service bundling separates professional broadcast module pricing from unbundled consumer electronics procurement. Three-tier pricing structure across automotive-grade, industrial-specification, and consumer-tier certification levels reflects REACH compliance testing costs and extended temperature range qualification timelines. Cost compression in consumer-tier integrated tuners is intensifying because television OEMs in South Korea and Taiwan have completed platform transitions to 28nm CMOS. Set-top box assemblers in India exhibit highest price sensitivity due to Phase IV digitization mandate cost ceilings, while German automotive OEMs accept premium positioning for multi-band architectures with satellite-terrestrial convergence.
Supply Chain Analysis
CE marking under RED and FCC Part 15 emissions certification gate market access for tuner modules sold into consumer and automotive channels. Fabrication concentrates in Taiwan, South Korea, and the United States, with 28nm and smaller CMOS processes feeding from concentrated foundry capacity. Raw material dependencies include high-purity silicon wafers, noble metal plating for legacy hermetic packages, and halogen-free substrate laminates for REACH-compliant redesigns. Single-source vulnerability around Taiwan-based advanced node access exposes supply chains to geographic concentration risk. Distribution runs through direct qualification relationships with cable operators and broadcast infrastructure operators, bypassing traditional EMS aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where foundry partnerships and captive fabrication capacity determine competitive survival. Players pursue upstream control over 28nm RF-CMOS process development as the decisive lever.
For Market Incumbents: Acquire fabless RF design teams with ATSC 3.0 and DVB-T2 firmware expertise to consolidate software-defined architecture roadmaps. Defensive moves must address discrete SAW filter substitution threats in emerging market television sets by accelerating cost-down roadmaps for integrated CMOS alternatives. Capacity addition in European fabrication nodes insulates against Taiwan foundry concentration risk while satisfying EU F-Gas Regulation compliance timelines for hermetic package elimination.
For New Entrants and Emerging Players: AI-driven spectrum management algorithms offer technology-first entry into cognitive radio and dynamic spectrum access adjacent markets. White-space targets include professional broadcast test equipment requiring field reconfigurability across regional standards, and Indian set-top box digitization procurement where BIS certification barriers filter incumbent competition. A direct qualification relationship with North American cable MSOs bypasses EMS channel control and captures specification influence.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified semiconductor conglomerates seeking RF portfolio breadth. Long-term viability over the next decade hinges on software-defined firmware upgradeability rather than discrete hardware refresh cycles. Acquisition target archetypes include fabless specialists with high-integration system-on-chip architectures and established FCC Part 15 emissions compliance records. The signal to watch is ATSC 3.0 rollout pace in United States metropolitan markets, which dictates replacement cycle timing for legacy analog tuner installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Advanced Node Access | 28nm RF-CMOS capacity at Taiwan-based foundries secures terrestrial and cable tuner performance leadership. |
| Direct MSO Qualification Relationship | North American cable operator procurement specifications bypass EMS intermediaries and capture design-win influence. |
| REACH-Compliant Material Redesign | Halogen-free substrate validation against ETSI EN 303 340 gates European automotive and consumer channel access. |
| Firmware-Defined Architecture Investment | Field-upgradeable modulation standards extend product lifecycles in professional broadcast equipment segments. |
| Automotive Grade Qualification Pathway | Extended temperature range and vibration specifications unlock connected vehicle platform integration in Germany and South Korea. |
Research Methodology
Independent corroboration across primary interviews with RF analog design directors, broadcast equipment procurement managers, and automotive Tier 1 supplier engineers underwrites the qualitative findings. Secondary validation draws from FCC equipment authorization databases, ETSI deliverable listings for EN 303 340 compliance, and SEC 10-K disclosures from diversified semiconductor suppliers. Bottom-up triangulation against top-down market sizing ensures segmentation integrity across integrated, multi-band, and software-defined tuner architectures.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window. The analytical framework models product type segmentation by integration level, technology segmentation by signal processing architecture, and end-user segmentation by qualification tier. CAGRs derive from shipment trajectory analysis against standard deployment timelines for ATSC 3.0, DVB-T2, and ISDB-T compliance mandates. Industry-specific forecast inputs include foundry capacity allocation disclosures and national regulator spectrum reallocation decisions.
Several conditions sit outside the modeled scope, including unforeseen raw material disruptions in noble metal supply chains and abrupt foundry node allocation shifts. Forecasts reflect assumptions about regulatory standard deployment pacing and automotive platform integration timelines. A model refresh is warranted upon material change in ATSC 3.0 compliance deadline enforcement or Taiwan semiconductor export control policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Gaas RF Switch Market
RF Components
Radio Frequency Front End Market
RF Components
Small Signal Mosfets Market
RF Components
Americas Small Signal Transistor Market
RF Components
Phase Shifters Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Z-Wave Products Market
RF Components
Noise Suppression Components Market
RF Components
RF Acoustic Wave Filters Market
RF Components
433MHz Active RFID Reader Market
RF Components
Wireless Module Market
RF Components
RF Spectrum Analyzer Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Digital Phase Shifter Market
RF Components
Global RF Power Semiconductor Market
RF Components
Radio Frequency Counter Market