
 Global Dielectric Etchers Market | 2026-2036
Global Dielectric Etchers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dielectric Etchers Market Foresight
Japan is reconfiguring its semiconductor equipment supply chain through renewed foundry investments in Kumamoto and Hokkaido. Applied Materials leverages extensive process libraries to sustain technology leadership in high-aspect-ratio dielectric etch applications. Lam Research anchors North American supply security through its Oregon manufacturing base and service infrastructure. Tokyo Electron competes aggressively on platform modularity across 300mm and 200mm process nodes.
Dielectric etchers remove insulating oxide and nitride films from wafer surfaces using fluorocarbon-based chemistries in plasma environments, achieving critical dimension control below 10 nanometers for multilayer interconnect structures. These systems enable precise pattern transfer in back-end-of-line dual damascene and through-silicon via processes essential to advanced logic and memory fabrication. Inductively coupled plasma etchers dominate capital allocation due to superior uniformity at high wafer throughput, while atomic layer etching gains traction for atomic-scale precision in 3D NAND string stacking. Semiconductor fabrication absorbs the majority of installed base demand, with chip foundries representing the most concentrated buyer segment.
The EPA regulates fluorinated greenhouse gas emissions from etch process chemistries in the United States, compelling equipment suppliers to develop abatement-integrated platforms. Japan's METI coordinates equipment standards through JIS frameworks that align with domestic foundry build-outs. The EU Chips Act and REACH chemical restrictions collectively shape product roadmaps and market access conditions for non-European vendors. Stakeholders must monitor subsidy disbursement timelines and local content thresholds as governments compete to onshore critical fabrication capacity.
Market Dynamics
Capital allocation in dielectric etch tools is bifurcating between high-volume logic foundries and memory-specific configurations, with fluorocarbon chemistry abatement emerging as the decisive compliance threshold for equipment qualification.
Growth Catalysts
- Subsidized Fab Construction:The EU Chips Act and comparable frameworks in Japan and the United States are accelerating domestic fabrication capacity build-outs. Equipment orders from these greenfield sites concentrate demand for multi-chamber etch platforms.
- 3D NAND String Stacking:Memory manufacturers are driving atomic layer etch adoption for vertical channel hole profile control. This process requirement expands the addressable tool base beyond conventional inductively coupled plasma systems.
- East Asian Cluster Expansion:Logic chip foundries in Taiwan and South Korea are expanding capital expenditure on dielectric etch tools. Their procurement volumes set pricing benchmarks and technology roadmaps for the broader equipment ecosystem.
Market Restraints
- Fluorinated Gas Abatement Costs:The EPA's fluorinated greenhouse gas emission regulations in the United States compel integrated abatement systems. These additions raise tool capital intensity by fifteen to twenty-five percent at the point of sale.
- Critical Component Concentration:High-purity ceramic chamber components and specialized radio-frequency power supplies concentrate among Japanese and German suppliers. Geographic concentration creates vulnerability to trade policy disruption.
- Technical Limitation at Atomic Scale:Conventional plasma etch chemistries face selectivity constraints below five nanometer critical dimensions. Atomic layer etch throughput remains insufficient for high-volume manufacturing ramps.
Strategic Opportunities
- Arizona and Saxony Build-outs:Emerging fabrication clusters in these regions are procuring etch tools without legacy platform entrenchment. Equipment vendors can establish greenfield service relationships and process library dominance.
- Through-Silicon Via Expansion:Advanced packaging applications for high-bandwidth memory and chiplet integration are creating demand for dielectric etch in back-end-of-line contexts previously served by wet processing.
- Japan's Equipment Standards Coordination:METI's JIS framework alignment with domestic foundry investments in Kumamoto and Hokkaido creates regulatory tailwinds for compliant platform architectures.
Industry Challenges
- Plasma Physics Expertise Scarcity:The intersection of surface chemistry, radio-frequency engineering, and semiconductor process control requires specialized talent. Foundry tool engineering teams face recruitment competition from adjacent technology sectors.
- Legacy Tool Integration Complexity:New etch platforms must interface with existing factory automation systems and metrology databases. Retrofit compatibility extends qualification timelines and strains vendor field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dielectric Etchers Market |
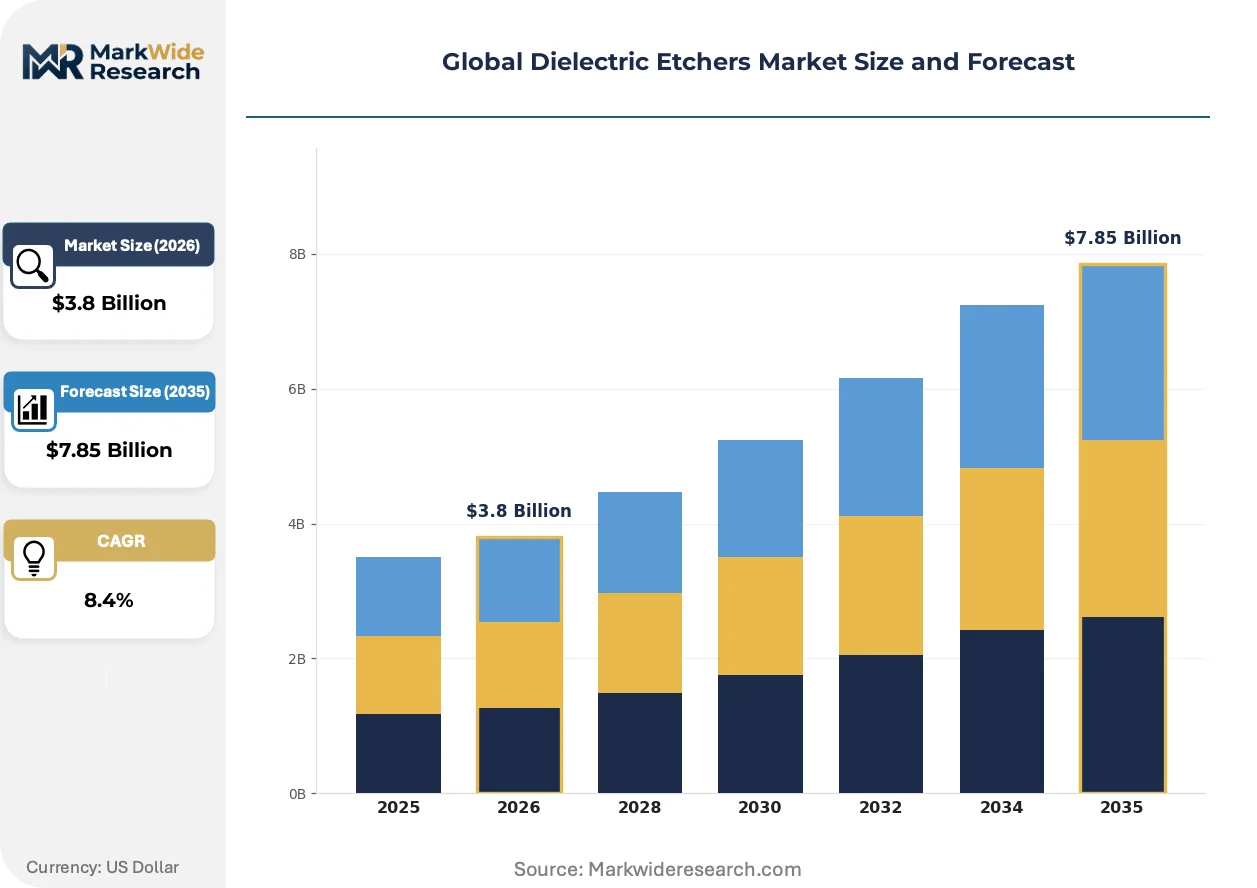
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Ion Etcher, Plasma Etcher, Inductively Coupled Plasma Etcher, Deep Reactive Ion Etcher Technology: Dry Etching, Wet Etching, Atomic Layer Etching, Ion Beam Etching, Laser Etching Application: Semiconductor Fabrication, Display Manufacturing, Microelectromechanical Systems, Photonic Devices, Printed Circuit Boards End User: Chip Foundries, Fabless IC Companies, Assembly & Packaging Firms, Research Laboratories |
| Companies Covered | Applied Materials, Lam Research, Tokyo Electron, Hitachi High-Tech, Advanced Micro-Fabrication Equipment, Mattson Technology, ULVAC, Oxford Instruments, SPTS Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dielectric Etchers Market Shifts & Advancements
Plasma process control is migrating from hardware-centric to software-defined architectures, compressing recipe development cycles and enabling remote optimization across geographically distributed fabrication sites.
Atomic layer etch technology is virtualizing the boundary between deposition and removal processes in 3D NAND fabrication. Memory manufacturers in South Korea and Japan are piloting these systems for vertical channel etch applications. The technology is virtualizing traditional process development by enabling deterministic removal rates independent of underlying film variations.
The EU F-Gas Regulation and REACH chemical restrictions are collectively constraining fluorocarbon process gas formulations available to equipment suppliers. Industrial consequence includes accelerated development of alternative chemistries and abatement-integrated platform designs. Non-European vendors are responding by pre-certifying tool configurations for European market access ahead of subsidy-driven fab ramp schedules.
Buyer concentration among the three largest foundry operators has compressed equipment evaluation cycles and intensified co-development requirements. Direct engagement between tool engineering teams and process integration groups is displacing traditional distributor-led sales models. This pattern is most visible in Taiwan and South Korea, where procurement decisions consolidate at the corporate technology committee level.
Global Dielectric Etchers Market Segmentation
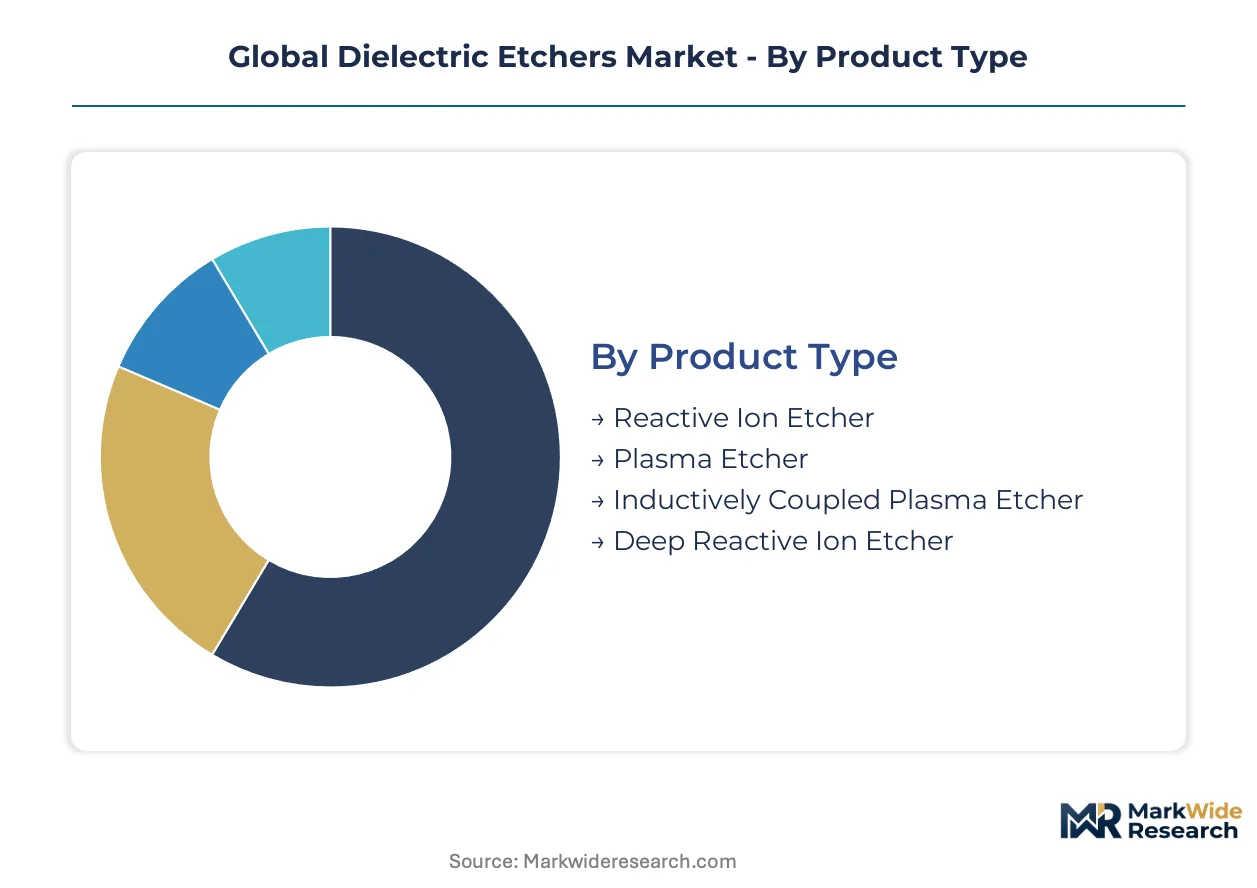
Dielectric etcher segmentation reveals distinct replacement cycles across product architectures, with plasma-based systems turning over faster than legacy platforms. Technology and application boundaries are blurring as atomic layer precision migrates from R&D into production environments.
Product Type:
Replacement velocity varies dramatically across etcher architectures, with high-throughput plasma systems cycling every 4-5 years while reactive ion platforms persist for 8-10 years in trailing-edge fabs.
- Reactive Ion Etcher:Mature capacitively coupled technology using parallel-plate electrode configurations for anisotropic dielectric removal. Demand concentrates in university cleanrooms and legacy 200mm fabs in Germany and Texas where capital constraints favor refurbished equipment over new platform acquisition.
- Plasma Etcher:Workhorse platform employing high-density fluorocarbon discharges for oxide and nitride film patterning. Taiwan Semiconductor Manufacturing Company and Samsung Foundry procurement volumes drive configuration standardization across the supplier ecosystem, with chamber modularity enabling rapid chemistry switches between process nodes.
- Inductively Coupled Plasma Etcher:Dominant architecture for sub-7nm critical dimension control with independent plasma density and ion energy tuning.
- Deep Reactive Ion Etcher:Specialized for high-aspect-ratio through-silicon via and MEMS cavity formation using Bosch process alternation.
Inductively coupled plasma etchers dominate installed base. Deep reactive ion etchers are where expansion concentrates for advanced packaging applications.
Technology:
Cost stratification separates billion-dollar wafer fabrication facilities from research laboratories and packaging houses, with dry etching occupying premium tiers and wet processing serving cost-sensitive volume applications.
- Dry Etching:Plasma-based removal using chemically reactive radicals and ion bombardment for vertical profile control. Logic foundries in South Korea and Taiwan absorb the majority of system output, with fluorocarbon abatement integration now mandatory for EPA compliance in Arizona fabs.
- Wet Etching:Liquid-phase chemical dissolution using buffered hydrofluoric acid and phosphoric acid formulations for blanket film removal. Display manufacturers in China and Vietnam deploy these systems for large-area substrate processing where plasma uniformity proves economically prohibitive.
- Atomic Layer Etching:Cyclical self-limited removal achieving angstrom-scale precision for 3D NAND string stacking.
- Ion Beam Etching:Physical sputtering using directed ion sources for hard-mask patterning in photonic device fabrication.
- Laser Etching:Ablation-based material removal for repair and prototyping applications in research settings.
Dry etching commands the majority of capital expenditure. Atomic layer etching is climbing the fastest as memory manufacturers scale vertical channel hole processing.
Application:
Customer maturity determines specification intensity, with semiconductor fabrication demanding sub-nanometer uniformity while printed circuit board processing tolerates micrometer-scale variation.
- Semiconductor Fabrication:Critical back-end-of-line dual damascene and front-end-of-line shallow trench isolation patterning. Intel, TSMC, and Samsung technology roadmaps drive etch chemistry development, with each process node transition triggering coordinated equipment refresh cycles across their manufacturing networks.
- Display Manufacturing:Large-area oxide semiconductor etching for thin-film transistor backplanes in OLED and microLED panels. BOE and LG Display operations in China and South Korea represent concentrated demand for specialized chamber geometries accommodating Gen 8.5+ substrate dimensions.
- Microelectromechanical Systems:Silicon and glass etching for accelerometers, gyroscopes, and pressure sensors.
- Photonic Devices:Precision patterning of silicon nitride and lithium niobate waveguide structures.
- Printed Circuit Boards:Through-hole and microvia drilling using plasma desmear and etchback processes.
Semiconductor fabrication anchors equipment revenue. Microelectromechanical systems are gaining share fastest as automotive sensor demand multiplies.
End User:
Procurement concentration creates divergent commercial dynamics, with chip foundries negotiating enterprise-wide framework agreements while research laboratories purchase through single-transaction capital budgets.
- Chip Foundries:High-volume manufacturing operations including TSMC, GlobalFoundries, and SMIC that standardize on multi-chamber cluster platforms. Their consolidated procurement power compresses supplier margins while accelerating co-development roadmaps for next-node etch chemistries.
- Fabless IC Companies:Design houses including Qualcomm and NVIDIA that access etch capacity through foundry partnerships rather than direct equipment ownership, influencing technology selection through process design kit requirements rather than capital allocation.
- Assembly & Packaging Firms:OSATs including ASE and Amkor deploying dielectric etch for emerging fan-out and chiplet integration processes.
- Research Laboratories:University and government facilities including IMEC and CNSE pursuing pre-competitive process development.
Chip foundries dominate installed base. Assembly and packaging firms are where expansion concentrates as advanced packaging penetrates high-performance computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment supply chains concentrate in Japanese and German component clusters, while foundry demand drives procurement decisions in Taiwan and South Korea. Subsidy programs in the United States and European Union are redistributing fabrication capacity across new geographic nodes. Local content requirements and chemical regulations are reshaping vendor qualification pathways in each jurisdiction.
United States
Intel and GlobalFoundries are expanding Arizona and New York fabrication complexes, driving multi-billion-dollar equipment procurement cycles. The EPA mandates fluorinated greenhouse gas abatement systems under Section 608 of the Clean Air Act, adding compliance costs to tool qualification. Phoenix-Tucson corridor fabs are negotiating greenfield service contracts without legacy platform entrenchment.
Taiwan
TSMC's capital expenditure programs set technology roadmaps and pricing benchmarks for dielectric etch platforms industry-wide. The National Development Council coordinates domestic content incentives aligned with foundry expansion schedules. Hsinchu Science Park and Southern Taiwan Science Park clusters concentrate the majority of global logic chip foundry capacity.
South Korea
Samsung Foundry and SK Hynix are scaling atomic layer etch adoption for 3D NAND string stacking and advanced logic nodes. The Ministry of Trade, Industry and Energy administers K-Semiconductor Belt subsidies supporting Pyeongtaek and Yongin fab complexes. Memory manufacturers here pilot vertical channel hole etch processes before global deployment.
Japan
Tokyo Electron and Hitachi High-Tech anchor domestic equipment supply, with renewed foundry investments in Kumamoto and Hokkaido reshaping demand patterns. METI coordinates JIS standards alignment with Rapidus and Kioxia manufacturing timelines. Kyushu region fabs are procuring multi-chamber platforms under government-backed reshoring initiatives.
Germany
Infineon and Bosch are expanding Dresden and Reutlingen facilities under EU Chips Act disbursement schedules. The EU F-Gas Regulation and REACH chemical restrictions constrain fluorocarbon process gas formulations available to equipment suppliers. Saxony cluster fabs are qualifying abatement-integrated platforms ahead of subsidy-driven production ramps.
Global Dielectric Etchers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in chamber ceramics and radio-frequency power supplies. The vendor base stratifies between billion-dollar integrated equipment suppliers and sub-scale technology licensors. Two archetypes dominate: chemistry-agnostic platform architects and process-specific application specialists. Consolidation pressures are intensifying through co-development partnerships and captive component sourcing arrangements.
Among North American integrated equipment suppliers, Applied Materials and Lam Research exemplify platform-scale archetypes with extensive process libraries. Tokyo Electron occupies a position bridging Japanese domestic coordination and global foundry standard-setting. These three anchors represent contrasting geographic bases—Santa Clara-based, Fremont-based, and Tokyo-based—each aligned with distinct regulatory and subsidy frameworks.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research |
| Tokyo Electron |
| Hitachi High-Tech |
| Advanced Micro-Fabrication Equipment |
| Mattson Technology |
| ULVAC |
| Oxford Instruments |
| SPTS Technologies |
| Others |
Supply & Pricing Matrix
Japanese and German suppliers of high-purity ceramic chamber components and specialized radio-frequency power supplies capture disproportionate margin pools downstream, with their geographic concentration translating directly into pricing power over integrated equipment vendors. Fluorocarbon chemistry abatement requirements add compliance premiums that concentrate in the system tier, compressing margins for buyers lacking scale to negotiate enterprise-wide frameworks.
Pricing Analysis
EPA fluorinated greenhouse gas regulations dictate the pricing tier structure by mandating integrated abatement systems that stratify equipment offerings. Pricing stratifies across premium abatement-integrated platforms, standard compliance-ready configurations, and economy-tier refurbished systems for trailing-edge fabs. Cost compression in the standard tier is intensifying because foundry procurement consolidation compresses supplier margins. Chip foundries exhibit the lowest price sensitivity due to co-development roadmaps, while research laboratories face acute budget constraints favoring refurbished reactive ion platforms.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese ceramic component suppliers anchor working capital structures for equipment assemblers. Manufacturing concentration in Japan, Germany, and the United States draws from specialized inputs including high-purity alumina ceramics, precision-machined quartz, and solid-state RF generators. Single-source vulnerability in ceramic chamber components creates exposure to trade policy disruption. Distribution runs through direct engagement between tool engineering teams and foundry process integration groups, displacing traditional distributor-led models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three dominant foundry operators, with procurement decisions consolidating at corporate technology committee levels and compressing equipment evaluation cycles across the supplier ecosystem.
For Market Incumbents: Entrench process library dominance in high-aspect-ratio dielectric etch applications through captive sourcing of ceramic chamber components from Kyushu-based suppliers. Expand Oregon and Arizona service infrastructure to anchor greenfield relationships at Intel and GlobalFoundries expansion sites. Atomic layer etch throughput limitations present the most acute substitution threat requiring R&D prioritization. For New Entrants and Emerging Players: Pursue white-space opportunities in advanced packaging dielectric etch for through-silicon via applications, where back-end-of-line demand is displacing wet processing and legacy platform entrenchment remains shallow. Arizona and Saxony build-outs offer the most penetrable geography given absence of incumbent service relationships. Lead with abatement-integrated platform architectures to satisfy EPA qualification requirements without retrofit burden. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with captive supply relationships to Japanese ceramic foundries and RF power supply engineering depth. Long-term viability hinges on exposure to atomic layer etch scaling curves and 3D NAND string stacking roadmaps. The signal to watch is qualification timelines for EU Chips Act subsidy-driven fabs in Dresden and subsidy disbursement velocity for Kumamoto reshoring initiatives.| Strategic Initiative | Industry Significance |
|---|---|
| Abatement-Integrated Platform Launch | EPA Section 608 compliance positions vendors for Arizona and New York procurement cycles at Intel and GlobalFoundries. |
| Ceramic Component Backward Integration | Kyushu supplier relationships reduce exposure to METI export coordination and JIS standard alignment costs. |
| Atomic Layer Etch R&D Partnership | Samsung and SK Hynix co-development roadmaps accelerate vertical channel hole etch qualification for 3D NAND scaling. |
| Greenfield Service Infrastructure | Phoenix-Tucson and Saxony presence enables process library dominance without legacy tool integration complexity. |
| Fluorocarbon Chemistry Alternative Development | EU F-Gas Regulation and REACH constraints demand pre-certified formulations for European market access ahead of subsidy ramps. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with foundry process integration engineers, equipment procurement directors at TSMC and Samsung, EPA compliance officers, and ceramic component sourcing managers at Applied Materials and Lam Research. Secondary validation drew from SEC 10-K equipment revenue disclosures, METI JIS standard publications, EU Chips Act disbursement schedules, and EPA Clean Air Act enforcement data. Bottom-up equipment shipment tallies triangulated against top-down fab capex allocation models across the analysis window.
Calibration against historical replacement cycles and node transition timelines anchored the projection framework. Segmentation dimensions modeled include etcher architecture, technology precision tier, application criticality, and end-user procurement concentration. CAGRs were derived from equipment shipment run-rates correlated with foundry capacity expansion schedules and memory manufacturer 3D NAND layer count roadmaps. Fluorocarbon gas regulatory stringency indices and subsidy disbursement velocity served as scenario-weighting inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, yen-euro exchange rate volatility affecting Japanese component costs, or trade policy disruption in ceramic supply chains would shift the trajectory. Forecasts reflect assumptions regarding EU Chips Act implementation pace and EPA enforcement consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Epitaxial Wafer Market