
 Solar Ingot Wafer Market | 2026-2036
Solar Ingot Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Ingot Wafer Market Intelligence
Vietnam is rewriting regional supply dynamics as new ingot pulling and wafer slicing facilities come online near Ho Chi Minh City industrial corridors. LONGi Solar Technology Co., Ltd. leverages its integrated polysilicon-to-module footprint to control cost curves across monocrystalline value chains. JA Solar Technology Co., Ltd. sustains aggressive capacity scaling in Southeast Asian hubs to serve North American and European offtake agreements. Shin-Etsu Chemical Co., Ltd. anchors semiconductor-grade silicon expertise that differentiates its feedstock purity for next-generation cell architectures.
A solar ingot wafer is a thin, circular semiconductor substrate sliced from a solidified silicon crystal boule, typically measuring 150–210 mm in diameter and 130–180 micrometers in thickness, serving as the foundational light-absorbing layer in photovoltaic cell fabrication. Monocrystalline wafers dominate installed capacity due to superior conversion efficiency and declining cost parity with polycrystalline alternatives. Utility-scale projects absorb the largest volume share as developers prioritize high-efficiency cell architectures to maximize energy yield per hectare. Czochralski-grown ingots command premium positioning in residential and commercial segments where space constraints elevate efficiency premiums over upfront module cost.
China's MIIT enforces GB/T 25076 wafer dimensional and resistivity standards that filter subscale producers from national procurement pools. India's BIS certification mandates and PLI scheme domestic-content thresholds are redirecting capacity investment toward ingot and wafer stages previously imported from East Asian suppliers. The EU Green Deal's embodied-carbon tracking requirements for solar imports are elevating transparency demands across polysilicon provenance and ingot energy intensity. Stakeholders must weigh regulatory compliance costs against tariff and incentive arbitrage when siting new crystallization and slicing capacity.
Market Dynamics
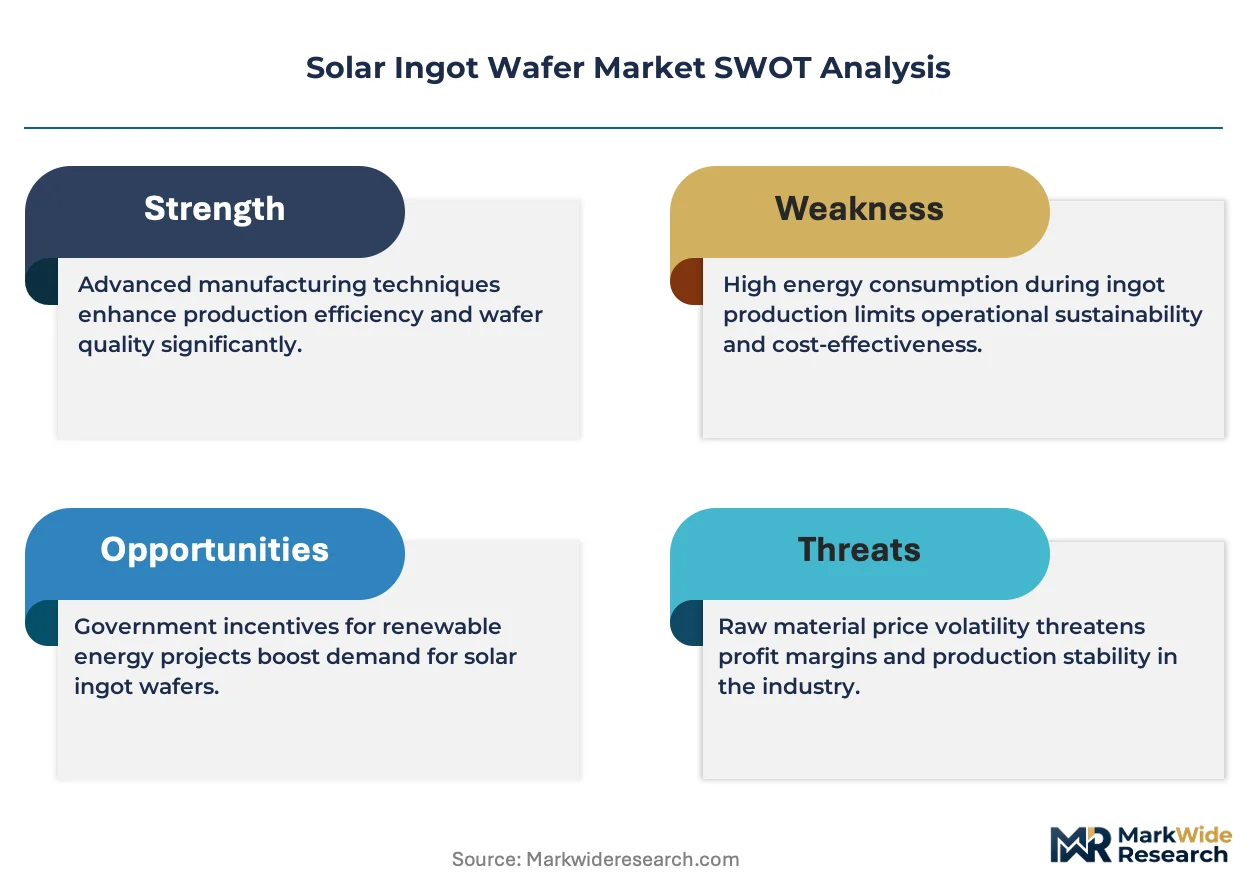
Wafer thickness reduction mandates under China's MIIT GB/T 25076 standards are compressing crystallization yields and forcing ingot producers to retool pulling furnaces for sub-150-micron architectures.
Growth Catalysts
- India's PLI scheme domestic-content thresholds:Cell manufacturers must source ingots and wafers from local facilities to qualify for production-linked incentives, redirecting capital toward crystallization and slicing capacity previously concentrated in East Asia.
- Utility-scale photovoltaic deployment:Developers prioritize high-efficiency monocrystalline architectures to maximize energy yield per hectare, pulling procurement volumes for large-diameter wafers upward across procurement pools.
- Czochralski process optimization:Advanced thermal gradient control and continuous pulling techniques are reducing kerf loss and energy consumption per ingot, narrowing cost gaps with cast-mono alternatives.
Market Restraints
- Polysilicon feedstock price volatility:Metallurgical-grade silicon purification capacity bottlenecks and energy cost spikes at polysilicon facilities transmit directly to ingot production economics.
- Wafer slicing diamond wire supply concentration:Synthetic diamond wire manufacturing clusters in specific East Asian jurisdictions create single-source vulnerability for high-precision kerf reduction.
- GB/T 25076 dimensional compliance:China's resistivity and thickness standards filter subscale crystallization facilities from national procurement pools, raising barrier-to-entry for new market entrants.
Strategic Opportunities
- Vietnam's industrial corridor expansion:New ingot pulling and wafer slicing facilities near Ho Chi Minh City are capturing redirected investment from tariff-exposed Chinese capacity, serving North American offtake agreements.
- EU Green Deal embodied-carbon tracking:Transparency requirements for solar imports are elevating demand for polysilicon provenance documentation and low-energy-intensity crystallization processes.
- Topcon and heterojunction cell architectures:N-type wafer demand is accelerating as next-generation cell technologies require higher minority carrier lifetime substrates than standard PERC designs.
Industry Challenges
- Crystallization engineer talent scarcity:Deep expertise in thermal gradient management and defect engineering for large-diameter ingots concentrates at established facilities, constraining new entrant scale-up timelines.
- Multi-gigawatt slicing capex intensity:Diamond wire saw installations and automated handling systems require substantial capital deployment before revenue generation, stretching balance sheets during polysilicon price troughs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Ingot Wafer Market |
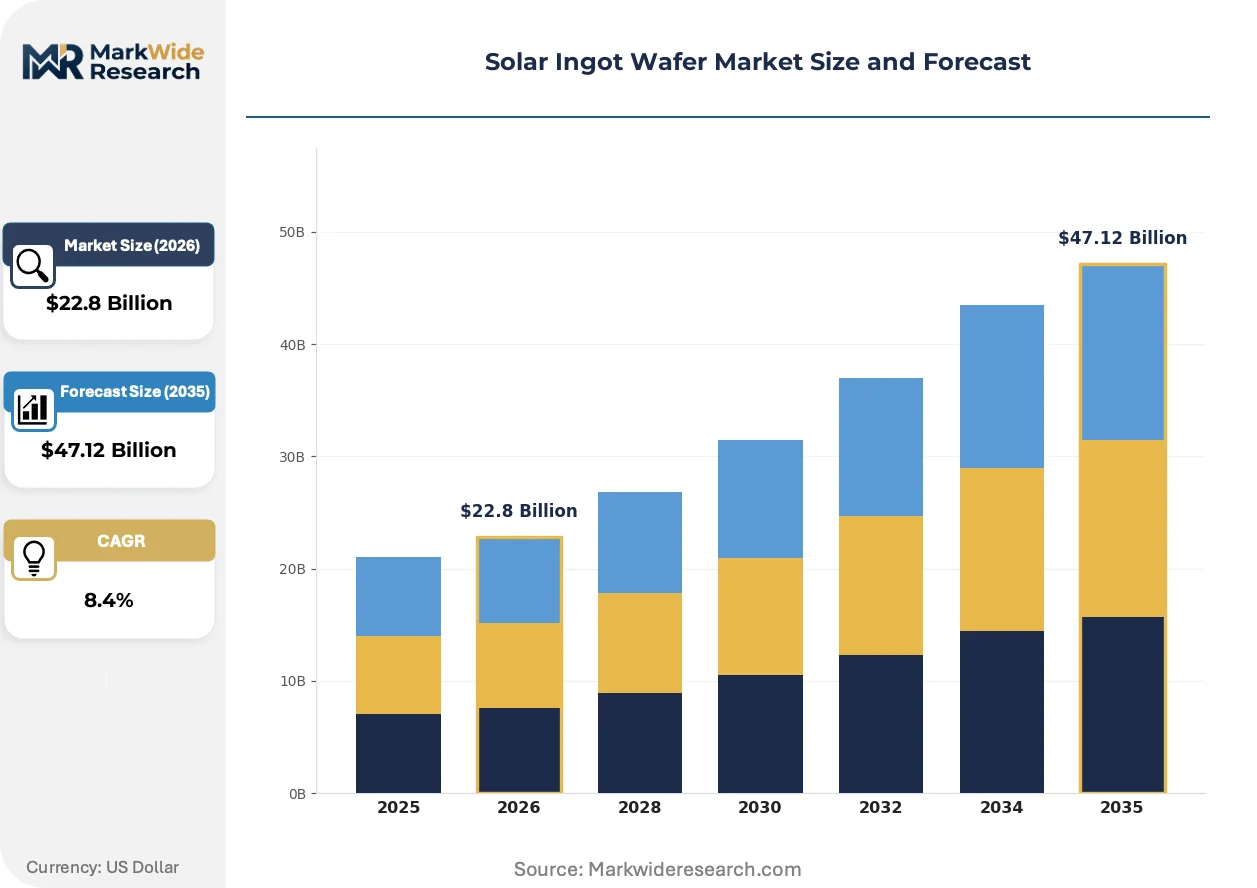
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Ribbon, Amorphous, Multi-crystalline Technology: Czochralski, Directional Solidification, Bridgman, Float Zone, Edge-defined Film-fed Growth Application: Residential Power Generation, Commercial Energy Systems, Utility-Scale Projects, Remote Power Supply, Off-grid Solutions End User: Solar Module Manufacturers, Photovoltaic Plants, Electric Power Providers, Renewable Energy Developers, EPC Contractors |
| Companies Covered | LONGi Solar Technology Co., Ltd., CETC Solar Energy Holdings Co., Ltd., Shin-Etsu Chemical Co., Ltd., Sumco Corporation, JA Solar Technology Co., Ltd., REC Silicon, Targray, DCH Group, Konca Solar Cell Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Ingot Wafer Market Strategic Shifts & Innovations
Silicon crystallization and wafer processing are converging toward thinner, larger-diameter formats under efficiency and material cost pressures, with regulatory carbon tracking and cell architecture evolution steering investment priorities.
Gallium-doped p-type silicon is migrating from conventional boron-doped feedstock for photovoltaic applications. Utility-scale developers are specifying gallium-doped wafers to mitigate light-induced degradation in PERC cells. This dopant substitution is compressing boron-doped wafer premiums and reshaping feedstock procurement specifications across crystallization facilities.
The EU Green Deal's embodied-carbon tracking requirements for solar imports are elevating transparency demands across polysilicon provenance and ingot energy intensity. Module importers must document crystallization electricity sources and carbon footprints, favoring facilities with renewable-powered pulling furnaces. European offtakers are now screening suppliers on lifecycle emissions metrics before contract execution.
Long-term supply agreements are displacing spot-market wafer procurement among integrated cell manufacturers. Tier-one producers are locking multi-year ingot supply contracts to secure volume certainty amid polysilicon price volatility. This contracting pattern is most visible in India where PLI scheme compliance requires demonstrated domestic-content sourcing across extended production timelines.
Solar Ingot Wafer Market Segmentation
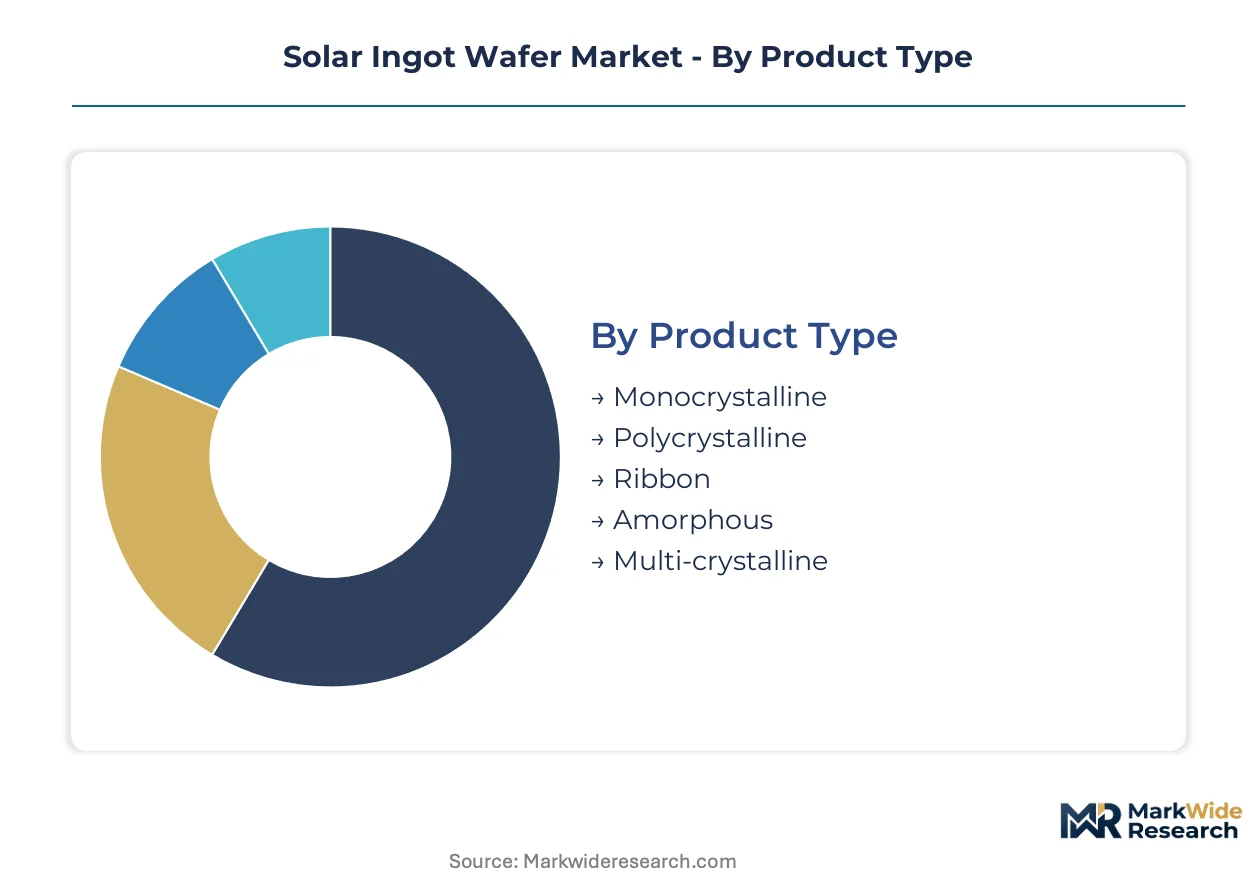
Solar ingot wafer segmentation reveals how crystallization method, cell architecture, and procurement scale dictate margin structures and capital intensity across the value chain. Procurement managers use these categories to align supplier qualification with project-specific efficiency and cost thresholds.
Product Type:
After-sales service intensity varies sharply by wafer crystallinity, with monocrystalline suppliers fielding technical support teams for cell efficiency optimization while polycrystalline vendors compete on volume logistics.
- Monocrystalline:Single-crystal silicon wafers sliced from Czochralski-grown ingots exhibit superior electron mobility and conversion efficiency. Utility-scale developers in India specify these for PLI-compliant domestic-content projects where space constraints elevate efficiency premiums.
- Polycrystalline:Multi-crystal structures formed through directional solidification offer lower production costs but reduced efficiency. Demand concentrates in price-sensitive distributed installations across Southeast Asian markets where module cost dominates procurement decisions.
- Ribbon:Silicon sheets formed directly from molten feedstock without ingot slicing reduce kerf loss dramatically. EPC contractors specify ribbon substrates for remote power supply installations where logistics weight drives system economics.
- Amorphous:Non-crystalline silicon deposited on flexible substrates serves niche thin-film applications requiring conformal mounting surfaces.
- Multi-crystalline:Cast silicon blocks with controlled grain boundaries bridge cost-efficiency tradeoffs for mid-tier commercial energy systems.
Monocrystalline holds the largest share; momentum sits with ribbon formats as kerf reduction targets tighten.
Technology:
Capital deployment patterns differentiate crystallization technologies, with Czochralski furnaces demanding longer depreciation schedules than directional solidification equipment.
- Czochralski:Crystal pulling from molten silicon crucibles produces highest-purity monocrystalline ingots. Residential and commercial segments absorb these wafers where China's MIIT GB/T 25076 standards enforce resistivity uniformity.
- Directional Solidification:Controlled cooling of silicon melts in quartz crucibles yields polycrystalline blocks with lower capital intensity. Polysilicon price volatility compresses margins for operators lacking backward integration into metallurgical-grade feedstock.
- Bridgman:Vertical gradient freeze methods produce specialized substrates for laboratory and space photovoltaic applications requiring radiation hardness.
- Float Zone:Contactless melting eliminates crucible contamination for ultra-high-purity semiconductor-grade silicon serving next-generation heterojunction cell architectures.
- Edge-defined Film-fed Growth:Capillary-fed ribbon formation reduces material waste for thin-wafer production targeting sub-150-micron thickness mandates.
Directional solidification dominates volume; float zone commands the steepest expansion trajectory as N-type cell architectures proliferate.
Application:
Project scale determines wafer diameter and thickness specifications, with utility-scale procurement pooling volumes that justify automated slicing investments.
- Utility-Scale Projects:Centralized photovoltaic plants exceeding 50 MW capacity specify large-diameter wafers for high-efficiency bifacial modules. Developers in Vietnam prioritize these formats to maximize energy yield per hectare under North American offtake agreements.
- Commercial Energy Systems:Rooftop and distributed generation installations balance efficiency against installation labor costs. India's CEA grid-interconnection standards shape procurement specifications for commercial segment suppliers.
- Residential Power Generation:Behind-the-meter installations favor standard-format wafers compatible with established module assembly lines.
- Remote Power Supply:Off-grid telecommunications and rural electrification projects prioritize logistics-optimized wafer formats.
- Off-grid Solutions:Standalone systems with battery storage integrate lower-grade wafers where cost-per-watt thresholds override efficiency optimization.
Utility-scale projects hold the largest share; commercial energy systems are gaining share fastest as distributed generation incentives expand.
End User:
Procurement sophistication varies by end-user technical depth, with solar module manufacturers conducting incoming quality audits that EPC contractors delegate to tier-one supplier certifications.
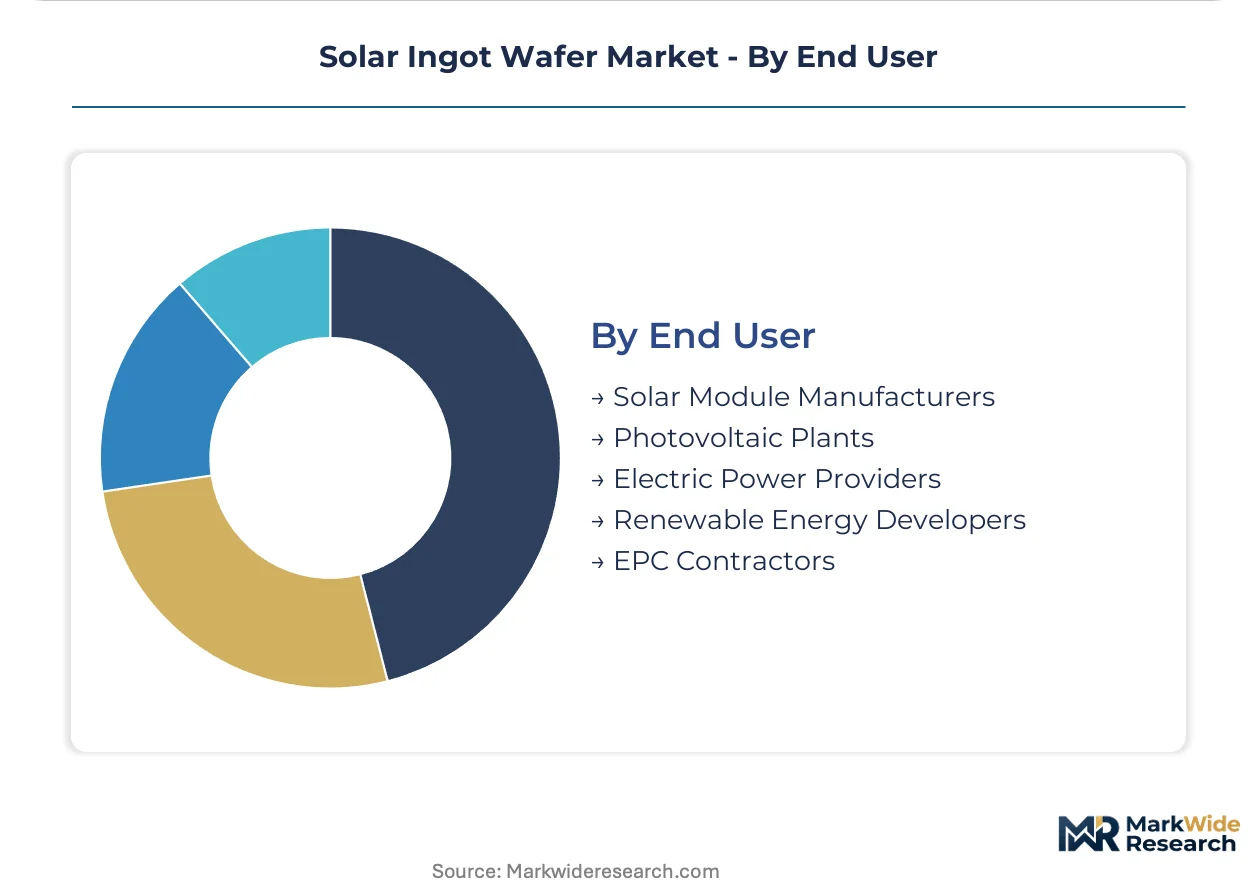
- Solar Module Manufacturers:Integrated cell and module producers specify wafer minority carrier lifetime and resistivity tolerances. LONGi and JA Solar lock multi-year ingot supply contracts to secure volume certainty for PERC and TOPCon cell lines.
- Photovoltaic Plants:Asset owners and operators procure wafers through module OEMs but increasingly specify crystallization energy source for EU Green Deal carbon documentation compliance.
- Electric Power Providers:Utility procurement departments integrate wafer sourcing into renewable portfolio standard compliance strategies.
- Renewable Energy Developers:Project sponsors underwrite wafer supply agreements to secure financing for greenfield installations.
- EPC Contractors:Engineering-procurement-construction firms aggregate module procurement without direct wafer specification, relying on module manufacturer quality systems.
Solar module manufacturers hold the largest share; photovoltaic plants are climbing the fastest as direct procurement models emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB/T 25076 standards anchor crystallization investment patterns across East Asia, while India's PLI scheme and the EU Green Deal's embodied-carbon rules redirect capacity toward domestic-content compliance and renewable-powered pulling furnaces.
China
NEEA efficiency mandates and dual carbon goals compress wafer thickness tolerances below 150 microns. MIIT enforces resistivity uniformity standards that filter subscale crystallization facilities from national procurement pools. Xuzhou and Ningbo industrial clusters host retooling campaigns for large-diameter Czochralski furnaces serving domestic cell manufacturers.
India
BIS certification requirements and PLI scheme domestic-content thresholds accelerate ingot-to-module capacity builds previously imported from East Asian suppliers. CEA grid-interconnection standards shape procurement specifications for commercial segment suppliers. Gujarat and Tamil Nadu industrial corridors capture redirected capital toward crystallization and slicing facilities.
Vietnam
Tariff-exposed Chinese capacity redirects toward Ho Chi Minh City industrial corridors to serve North American offtake agreements. Developers specify large-diameter wafers for high-efficiency bifacial modules under long-term supply contracts. Binh Duong Province hosts new ingot pulling and wafer slicing facilities coming online.
United States
IRA domestic-content bonus credits elevate demand for crystallization facilities with documented polysilicon provenance. FERC interconnection queue reforms compress project development timelines for utility-scale photovoltaic deployment. Texas and Arizona industrial zones attract diamond wire saw investments for automated slicing operations.
Germany
EU Green Deal embodied-carbon tracking requirements elevate transparency demands across polysilicon provenance and ingot energy intensity. REACH compliance and CSRD reporting obligations shape supplier qualification protocols for module importers. Saxony and Bavaria host specialized facilities targeting semiconductor-grade silicon for next-generation cell architectures.
Solar Ingot Wafer Market Key Industry Players
Integrated polysilicon-to-module conglomerates and specialized crystallization houses split the market between cost-curve control and technical differentiation. The vendor base concentrates around three strategic archetypes: backward-integrated energy conglomerates with captive polysilicon supply, pure-play wafer specialists scaling automated slicing capacity, and semiconductor-grade silicon houses leveraging feedstock purity for premium substrates. Capacity expansion and multi-year supply contracting dominate competitive moves as polysilicon price volatility elevates volume certainty premiums.
Among East Asian integrated producers, LONGi Solar Technology Co., Ltd. and JA Solar Technology Co., Ltd. occupy positions spanning crystallization through module assembly, while Shin-Etsu Chemical Co., Ltd. anchors the semiconductor-grade feedstock tier with expertise in ultra-high-purity silicon for next-generation cell architectures.
| Leading Market Players |
|---|
| LONGi Solar Technology Co., Ltd. |
| CETC Solar Energy Holdings Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Sumco Corporation |
| JA Solar Technology Co., Ltd. |
| REC Silicon |
| Targray |
| DCH Group |
| Konca Solar Cell Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Xuzhou and Ningbo crystallization clusters compresses spot pricing for standard-format monocrystalline wafers while elevating contract premiums for GB/T 25076-compliant suppliers. This utilization asymmetry rewards integrated producers with captive polysilicon and filters subscale participants from national procurement pools.
Pricing Analysis
Price spreads between China-origin wafers and Vietnam-finished equivalents widen during polysilicon price troughs as tariff-exposed capacity redirects toward Ho Chi Minh City corridors. Contract-based long-term offtake agreements dominate utility-scale procurement, with price differentiation resting on resistivity uniformity and carbon-footprint documentation for EU Green Deal compliance. Cost compression in standard p-type wafers intensifies as gallium-doped alternatives displace boron-doped feedstock. EPC contractors exhibit highest price sensitivity, while integrated cell manufacturers prioritize lifetime yield over upfront wafer cost.
Supply Chain Analysis
Tariff exposure between China and North American offtake markets dominates supply chain risk calculus, redirecting ingot pulling investments toward Vietnam's Binh Duong Province. Manufacturing concentrates in China, Vietnam, and India as India's PLI scheme domestic-content thresholds accelerate local crystallization builds. Raw material dependencies center on metallurgical-grade silicon purification capacity, synthetic diamond wire supply, and quartz crucible manufacturing. Single-source vulnerability in diamond wire production clusters creates procurement chokepoints. Distribution runs through module OEMs and direct long-term supply contracts with integrated cell producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar ingot wafer demand sits in early-cycle expansion as India's PLI scheme and Vietnam's tariff-advantaged capacity builds accelerate crystallization investment previously concentrated in East Asian supply bases.
For Market Incumbents: Harden cost-curve positioning through backward integration into polysilicon purification and automated diamond wire saw capacity in Vietnam's industrial corridors. Defend against emerging ribbon-format specialists by locking multi-year supply contracts with Indian cell manufacturers facing PLI compliance deadlines. Prioritize GB/T 25076 certification maintenance to retain access to China's national procurement pools as thickness mandates tighten below 150 microns. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City industrial corridors to capture redirected investment from tariff-exposed Chinese capacity. Target the commercial energy systems segment in India where BIS certification requirements and distributed generation incentives create procurement openings for new crystallization facilities. Lead with carbon-footprint documentation capabilities to qualify for EU Green Deal embodied-carbon tracking requirements among European offtakers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because polysilicon price volatility and multi-gigawatt slicing capex intensity favor scaled integrated producers over pure-play wafer specialists. Acquisition targets should demonstrate demonstrated supply contracts with Indian PLI beneficiaries or Vietnam-based capacity with documented North American offtake agreements. Monitor diamond wire supply concentration as the inflection signal for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive metallurgical-grade silicon supply insulates margin structures from feedstock price volatility at Chinese purification facilities. |
| Vietnam Capacity Buildout | Ho Chi Minh City industrial corridors capture redirected investment from tariff-exposed Chinese crystallization operations. |
| Long-term Supply Contracting | Multi-year ingot agreements with Indian cell manufacturers secure volume certainty under PLI scheme domestic-content thresholds. |
| GB/T 25076 Compliance Investment | Resistivity uniformity certification maintains access to China's national procurement pools as MIIT standards tighten. |
| Carbon Documentation Capability | Polysilicon provenance tracking qualifies suppliers for EU Green Deal embodied-carbon requirements among European module importers. |
Research Approach
Desk research of customs trade data, SEC filings from integrated solar producers, and MIIT regulatory bulletins preceded structured interviews with crystallization plant managers, cell manufacturer procurement leads, EPC contractor technical directors, and diamond wire supply specialists. Primary fieldwork validated capacity utilization rates and polysilicon contract pricing dynamics. Secondary sources included EIA photovoltaic deployment data, IEA renewable energy investment reports, and BIS certification registries. Bottom-up crystallization capacity estimates triangulated against top-down module production forecasts.
Assumptions held fixed include China's dual carbon policy trajectory and India's PLI scheme domestic-content thresholds, while polysilicon price volatility and tariff rate scenarios varied across sensitivity runs. The analytical framework modeled crystallization technology, wafer diameter format, cell architecture compatibility, and regional regulatory cluster across the projection horizon. CAGRs derived from installed capacity build schedules and module efficiency improvement curves. Forecast inputs incorporated diamond wire kerf reduction trends and gallium-doped p-type migration timelines.
Sensitivities concentrate around polysilicon feedstock price spikes, diamond wire supply disruptions, and MIIT thickness mandate acceleration beyond 150 microns. Forecasts reflect documented assumptions on capacity expansion timelines and regulatory compliance cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market