
 Mask Alignment Lithography Market | 2026-2036
Mask Alignment Lithography Market Size, Share, and Industry Trends Forecast 2026-2036
Mask Alignment Lithography Market Foresight
The EU Green Deal is pivoting semiconductor equipment procurement toward lower-carbon manufacturing footprints across European fabs. ASML Holding N.V. leverages its monopoly in extreme ultraviolet systems to command pricing power in advanced node production. Canon Inc. anchors its position through proprietary i-line and KrF stepper platforms serving mature process nodes. Nikon Corporation competes in deep ultraviolet lithography for memory and logic applications where cost efficiency matters.
Mask alignment lithography refers to the precision optical process of transferring circuit patterns from photomasks onto semiconductor wafers using step-and-repeat or step-and-scan exposure systems with sub-nanometer overlay accuracy. The technique enables fabrication of integrated circuits with feature resolutions below 7 nanometers in leading-edge production. Stepper systems dominate installed base revenue due to their critical role in multi-patterning workflows at advanced nodes. Deep Ultraviolet Lithography retains the largest share of operational fab equipment, while Extreme Ultraviolet Lithography captures the fastest expansion as foundries transition below 5 nanometer geometries. Foundries represent the most concentrated end user segment, with integrated device manufacturers trailing in capital intensity per wafer start.
The EPA regulates perfluorinated compound emissions from semiconductor fabrication under the Clean Air Act, pushing equipment vendors to develop closed-loop chemical recovery systems. REACH and RoHS constrain hazardous substance use in lithography tool manufacturing, affecting component sourcing across European supply chains. ISO 14644 cleanroom standards govern particle contamination limits that directly determine mask alignment yield rates. Stakeholders must track how the EU AI Act's chip sovereignty provisions redirect public funding toward domestic lithography capacity.
Market Dynamics
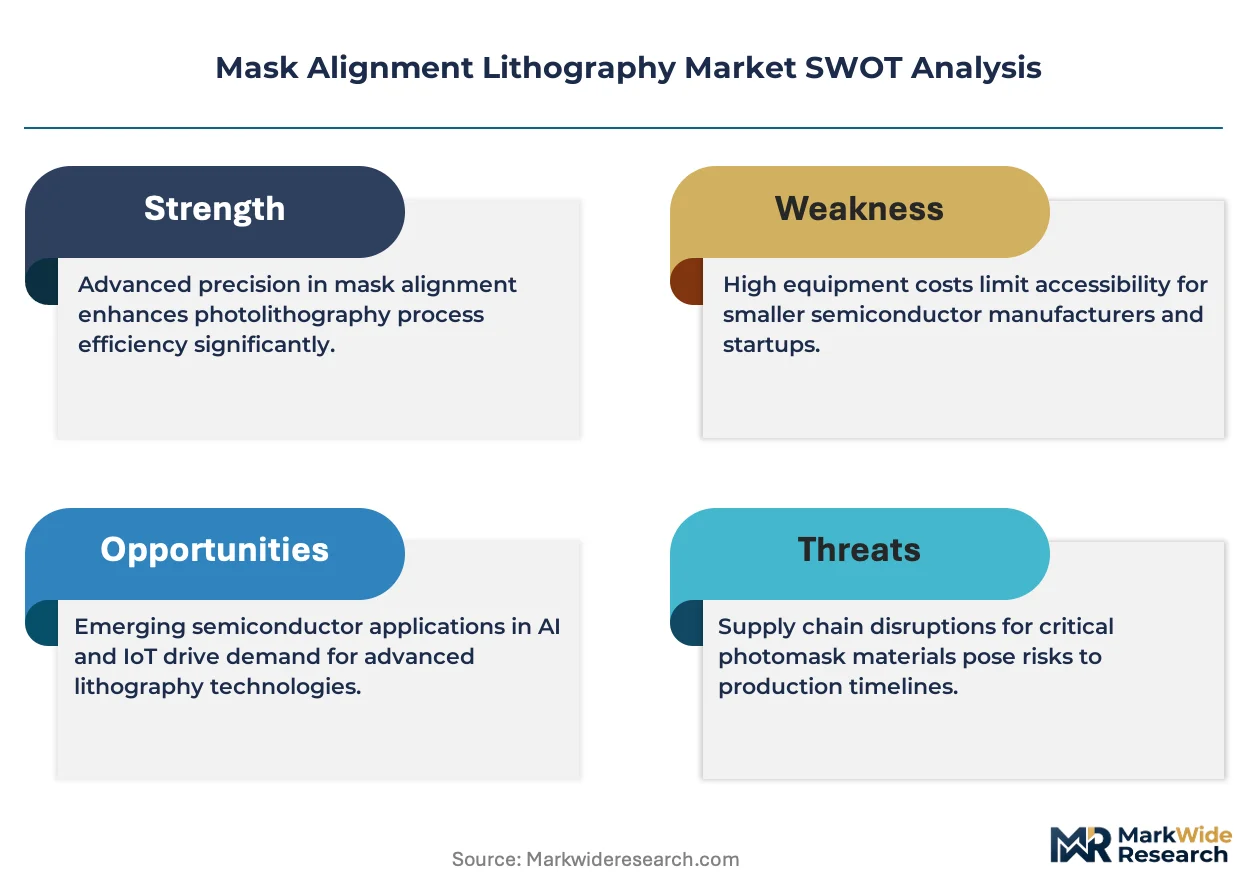
The transition to sub-3 nanometer nodes is compressing overlay tolerances below 0.5 nanometers, forcing equipment vendors to rebuild metrology architectures around real-time adaptive correction systems.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon coolants in lithography tools is accelerating closed-loop thermal management retrofits across European fabs, creating replacement demand for legacy stepper installations.
- Multi-patterning workflows:Self-aligned quadruple patterning at 5nm nodes quadruples mask layer counts per wafer, expanding the installed base of alignment systems per fab line.
- Hsinchu cluster concentration:TSMC and UMC procurement cycles in Taiwan's science parks synchronize equipment refresh waves, amplifying order visibility for mask alignment vendors.
Market Restraints
- Zeiss substrate monopoly:Single-source dependency for calcium fluoride lens blanks creates supply vulnerability for deep ultraviolet optical trains.
- Technical limitation:Current actinic inspection systems cannot resolve stochastic defects below 10 nanometers on EUV masks, forcing slower electron-beam verification cycles.
- Input cost volatility:High-purity neon gas pricing fluctuates with Ukrainian production disruptions, destabilizing excimer laser operating costs.
Strategic Opportunities
- India PLI scheme:Semiconductor fabrication incentives under the country's production-linked incentive framework are attracting first-mover lithography deployments in Gujarat and Karnataka.
- Photonics packaging:Silicon photonics chiplets for datacenter interconnects require coarse alignment tolerances that mature i-line steppers can serve at margin-accretive price points.
- AI-driven predictive maintenance:Machine learning overlay correction is automating calibration cycles, opening software-subscription revenue streams alongside hardware sales.
Industry Challenges
- Metrology engineer scarcity:The specialized skillset combining interferometry, computational lithography, and cleanroom protocols faces acute shortages across all major fab clusters.
- ISO 14644 certification timelines:Cleanroom qualification for new alignment tool installations extends 18-24 months, delaying revenue recognition and capacity ramps.
- Legacy system integration:Brownfield fabs must bridge proprietary communication protocols between 200mm-era steppers and modern factory automation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mask Alignment Lithography Market |
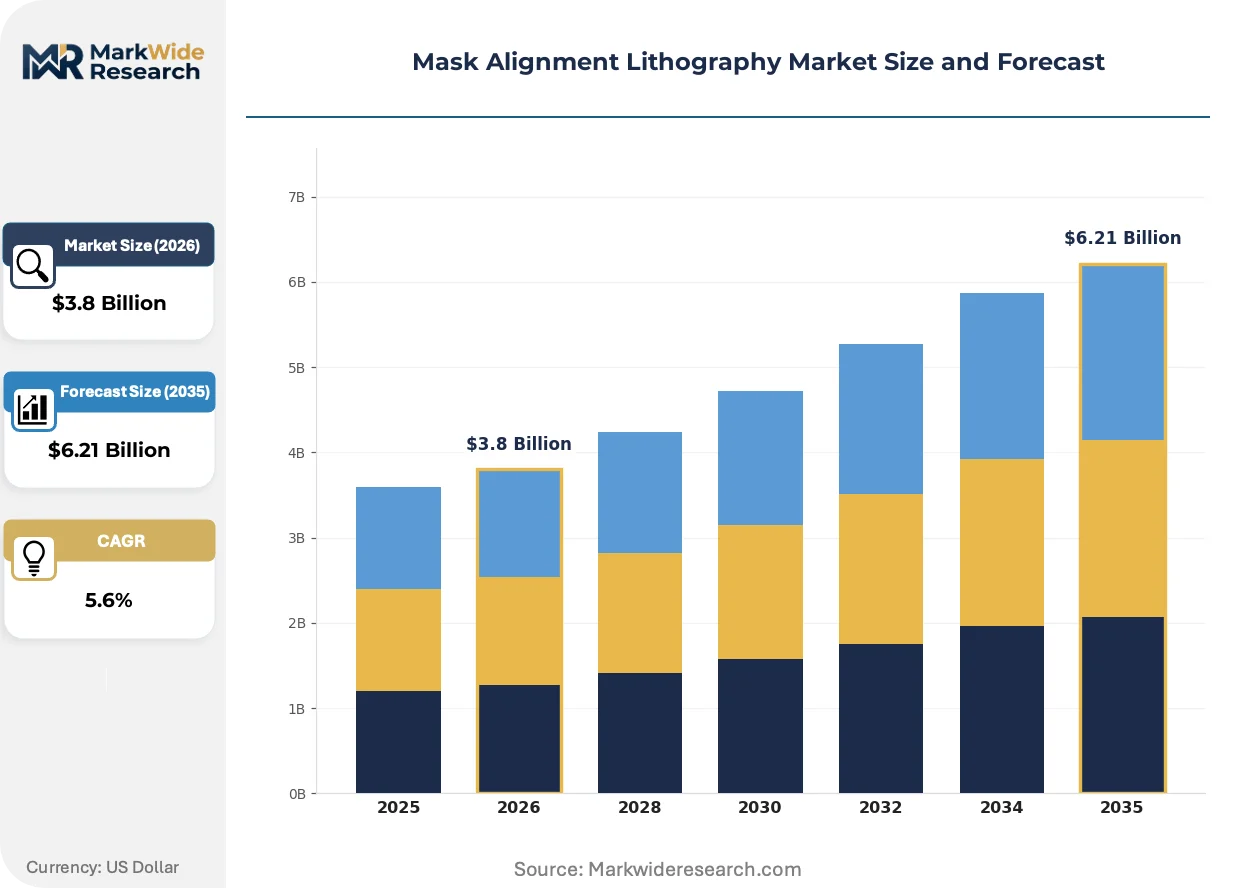
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stepper, Imprint Lithography, Exposure System, Production Equipment Application: Semiconductor Fabrication, MEMS Manufacturing, Photonic Devices, Nanotechnology End User: Foundries, Integrated Device Manufacturers, Research Institutions, OEMs Technology: Extreme Ultraviolet Lithography, Deep Ultraviolet Lithography, Maskless Lithography, Nanoimprint Lithography |
| Companies Covered | ASML Holding N.V., Canon Inc., Nikon Corporation, EV Group, SUSS MicroTec SE, Ultratech Inc., Rudolph Technologies, Neutronix Quintel, KLA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mask Alignment Lithography Market Shifts & Advancements
Computational lithography and real-time process control are converging to compress development cycles for advanced nodes. Equipment vendors now compete on software-enabled overlay stability rather than hardware specifications alone.
Machine learning-based overlay correction is automating the feedback loop between exposure and metrology. Leading foundries deploy neural networks that predict thermal drift and lens heating effects before they manifest on wafers. This compression of the control loop is automating what previously required hours of engineer intervention, shrinking the time from first silicon to yield maturity.
REACH substance restrictions are forcing redesigns of photoresist chemistries and containment materials. The European Chemicals Agency's authorization requirements for per- and polyfluoroalkyl substances now cover fluoropolymers used in chamber seals and wafer handling components. Photoresist suppliers are reformulating platforms to eliminate long-chain fluorinated surfactants, with qualification timelines extending 12-18 months for each node transition.
Consolidated procurement consortia are displacing individual fab purchasing decisions. Memory and logic manufacturers in South Korea and Taiwan now coordinate equipment specifications through shared technical working groups, standardizing overlay requirements across corporate boundaries. This concentration of buyer power is most visible in HBM3E and advanced packaging capacity expansions, where consortium-defined roadmaps dictate vendor development priorities.
Mask Alignment Lithography Market Segmentation
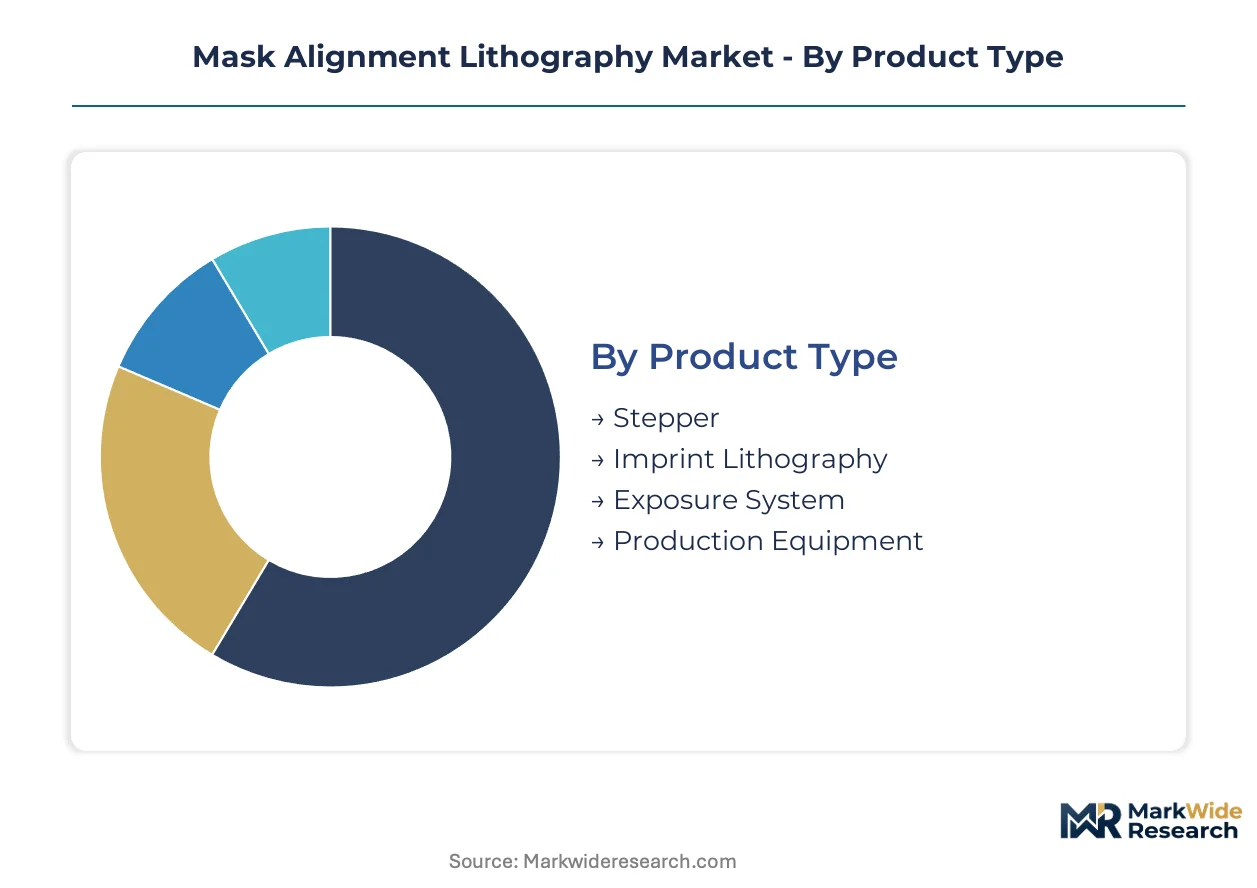
Mask alignment lithography equipment serves divergent process requirements across node generations and substrate materials. Equipment configurations vary sharply between standalone production tools and integrated cluster systems. Understanding these segment boundaries clarifies procurement patterns and technology refresh cycles across the installed base.
Product Type:
Stepper systems operate as standalone exposure platforms or embed within larger lithography clusters depending on fab automation architecture.
- Stepper:Step-and-repeat optical systems project reticle patterns onto wafers with sub-nanometer overlay precision. Foundries in Taiwan's Hsinchu cluster deploy these as the workhorse platform for multi-patterning at 7nm and 5nm nodes, where layer-to-layer registration tolerance now compresses below 0.5 nanometers.
- Imprint Lithography:Mechanical pattern transfer using master templates achieves resolution without complex optical trains. The technology addresses photonics packaging applications in datacenter interconnects where coarse alignment tolerances match mature process capabilities.
- Exposure System:Scanning projection tools with programmable illumination serve R&D prototyping and pilot lines. Research institutions in Japan leverage these for exploratory node development before process transfer to production.
- Production Equipment:Fully automated cluster configurations integrate coat, expose, and develop modules. OEMs serving the European automotive sensor market specify these for high-volume MEMS fabrication.
Stepper systems lead volumes today; imprint lithography is gaining share fastest in packaging applications.
Application:
Application segments map directly to substrate material complexity and pattern density requirements, with cost tiers separating leading-edge logic from specialty devices.
- Semiconductor Fabrication:Logic and memory production demands the tightest overlay budgets and drives equipment specification roadmaps. TSMC and Samsung foundries in Taiwan and South Korea anchor procurement for sub-5nm node ramps.
- MEMS Manufacturing:Microelectromechanical systems require thick photoresist processing and relaxed alignment tolerances. Automotive pressure sensor fabs in Germany's Saxony region favor refurbished i-line steppers for cost efficiency.
- Photonic Devices:Silicon photonics waveguides and modulators need precise sidewall definition but permit larger feature sizes. Datacenter interconnect suppliers in the United States are expanding capacity for 800G optical transceivers.
- Nanotechnology:Research-scale patterning for quantum devices and metamaterials operates at low volumes with maximum flexibility. University cleanrooms across India source second-hand equipment under the PLI scheme's research provisions.
Semiconductor fabrication commands the highest equipment ASPs; photonic devices are expanding most quickly as datacenter buildouts accelerate.
End User:
End user categories separate by capital intensity per wafer start and internal technology development capability.
- Foundries:Pure-play manufacturers serving fabless design houses concentrate the largest equipment procurement volumes. UMC and GlobalFoundries facilities anchor regional demand clusters in Taiwan and Singapore.
- Integrated Device Manufacturers:Vertically integrated producers combine design and fabrication under single corporate control. Intel's manufacturing expansion in Arizona and Ohio is reshaping North American equipment deployment patterns.
- Research Institutions:University and national laboratory cleanrooms prioritize flexibility over throughput for exploratory process development. CEA-Leti in France coordinates EU-wide lithography research consortia under Horizon Europe funding.
- OEMs:Original equipment manufacturers producing discrete components and subsystems operate captive fabs with specialized requirements. Bosch's sensor fabrication in Germany runs dedicated stepper lines for automotive qualification.
Foundries lead volumes today; research institutions are climbing the fastest as sovereign chip initiatives expand public R&D funding.
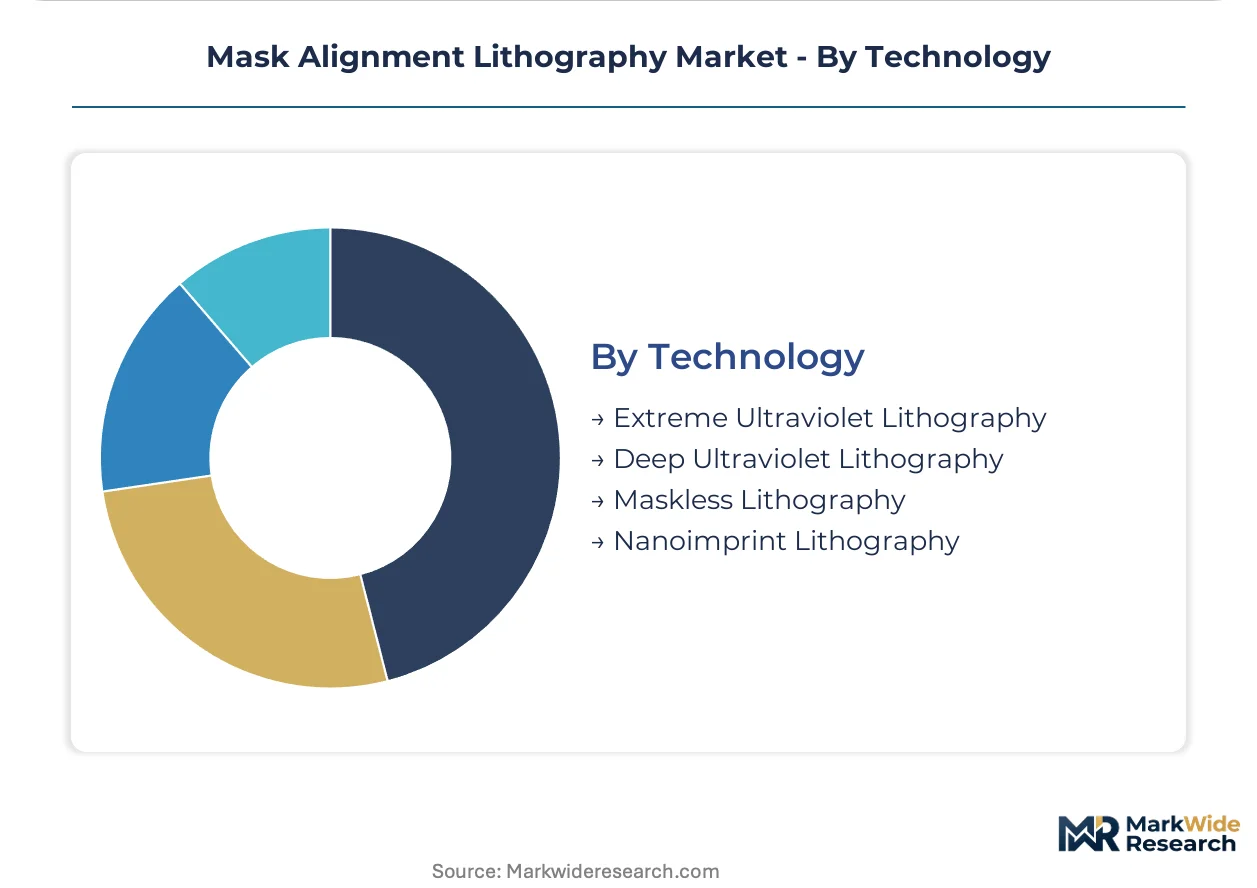
Technology:
Technology segments align with wavelength and patterning strategy, with maturity curves separating volume production from emerging alternatives.
- Extreme Ultraviolet Lithography:13.5nm wavelength exposure enables single-patterning at 3nm nodes where optical proximity correction fails. ASML's monopoly position in EUV systems concentrates supply chain leverage in the Netherlands and its key component suppliers.
- Deep Ultraviolet Lithography:193nm immersion and dry systems retain the largest installed base across mature and advanced nodes. Multiple patterning workflows at Samsung and SK Hynix memory fabs in South Korea sustain DUV equipment refresh cycles.
- Maskless Lithography:Electron-beam direct write eliminates reticle costs for low-volume prototyping and security applications. Military-qualified component suppliers in the United States adopt these for trusted foundry requirements.
- Nanoimprint Lithography:Template-based mechanical patterning targets display and photonics applications where defect tolerance permits. Canon's proprietary platforms serve LED and optical component manufacturers in Japan.
Deep ultraviolet lithography leads volumes today; extreme ultraviolet lithography shows the steepest expansion trajectory as node transitions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mask alignment lithography industry traces its commercial origins to post-war precision optics manufacturing in Germany and Japan, with subsequent scaling driven by American semiconductor pioneers and the rise of Asian foundry clusters over the past four decades.
Taiwan
TSMC and UMC procurement cycles dominate global equipment volumes, with Hsinchu Science Park anchoring the densest concentration of advanced lithography installations worldwide. The National Development Council's chip sovereignty provisions under the Asia Silicon Valley Development Plan direct public R&D funding toward domestic metrology capabilities. Tainan's Southern Taiwan Science Park is absorbing the newest EUV cluster expansions as foundries transition below 3 nanometer production.
United States
Intel's manufacturing expansion in Arizona and Ohio is reshaping North American deployment patterns for deep ultraviolet and extreme ultraviolet systems. EPA regulations under the Clean Air Act constrain perfluorinated compound emissions from fabrication facilities, pushing equipment vendors toward closed-loop chemical recovery architectures. The Albany Nanotech Complex in New York coordinates EUV research consortia linking IBM, Applied Materials, and SUNY Polytechnic.
South Korea
Samsung Electronics and SK Hynix memory fabs sustain aggressive refresh cycles for multi-patterning stepper installations at nodes between 10 and 20 nanometers. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative subsidizes domestic lithography component supply chains around Pyeongtaek and Yongin. Seoul's Pangyo Techno Valley hosts emerging overlay correction software ventures serving foundry automation layers.
Netherlands
ASML's Veldhoven headquarters concentrates extreme ultraviolet system design and integration, with single-source leverage over the global installed base for sub-7 nanometer production. The Dutch government's National Technology Strategy designates semiconductor equipment as a strategic sector eligible for accelerated permitting and R&D tax credits. Eindhoven's Brainport region anchors the High Tech Campus ecosystem linking lithography component suppliers.
Japan
Canon and Nikon retain substantial positions in i-line, KrF, and deep ultraviolet platforms serving mature node and specialty device manufacturers. METI's semiconductor revitalization framework directs subsidies toward domestic 2 nanometer pilot line development in collaboration with IBM and Rapidus. Kyushu's Kumamoto Prefecture is attracting TSMC joint-venture fab investments that will drive localized stepper procurement for automotive and industrial chip production.
Mask Alignment Lithography Market Competitive Landscape
Premium-margin players sit above commodity-margin players across wavelength capability and overlay precision tiers. The market structure concentrates extreme ultraviolet supply around a single Dutch system integrator, while deep ultraviolet and legacy optical segments sustain multiple viable competitors. Three archetypes define competitive positioning: wavelength-specialized equipment vendors, precision optics component monopolists, and process control software integrators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as foundries accelerate node transitions.
Within the wavelength-specialized tier, ASML Holding N.V. and Canon Inc. occupy positions reflecting divergent strategic bets on extreme ultraviolet versus mature optical platforms. Nikon Corporation sits within the deep ultraviolet segment where cost efficiency and memory fab relationships determine competitive standing. These three equipment vendors exemplify how technology roadmaps and foundry procurement cycles concentrate market leverage.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Canon Inc. |
| Nikon Corporation |
| EV Group |
| SUSS MicroTec SE |
| Ultratech Inc. |
| Rudolph Technologies |
| Neutronix Quintel |
| KLA Corporation |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power for lithography equipment vendors, as closed-loop thermal management retrofits become mandatory for European fab installations and carbon footprint disclosure requirements reshape procurement scorecards across foundry clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EUV systems from DUV immersion platforms and refurbished i-line steppers, with price differentiation anchored in overlay precision certification and after-sales service bundling. Cost compression in the standard tier is intensifying because foundry consortiums consolidate procurement specifications across corporate boundaries. IDMs exhibit the highest price sensitivity due to captive fab utilization rates, while pure-play foundries prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale buyer demand from TSMC and Samsung, while distributor-mediated sales serve research institutions and specialty device manufacturers. Optical component production concentrates in the Netherlands, Germany, and Japan, with calcium fluoride lens blanks and high-purity neon gas drawing from geographically concentrated suppliers. Single-source vulnerability for Zeiss substrate qualification creates structural risk for DUV optical train assembly. Distribution runs through lithography OEM direct sales organizations for production equipment and specialized resellers for R&D-scale tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mask alignment lithography market functions as a stable compounder, with node transition cycles below 5 nanometers driving steady equipment refresh demand across foundry and memory fab installations.
For Market Incumbents: Hedge against ASML's EUV monopoly by deepening proprietary positions in multi-patterning DUV workflows and nanoimprint lithography for photonics packaging applications. Invest in captive metrology software development to capture recurring revenue streams alongside hardware sales. Secure certification for REACH-compliant photoresist containment systems before European authorization timelines tighten.
For New Entrants and Emerging Players: AI-driven predictive maintenance algorithms offer a technology-first wedge into the aftermarket service layer currently dominated by OEM captive organizations. Target India's PLI scheme beneficiary fabs in Gujarat and Karnataka for first-mover lithography deployments. Pursue partnership-based go-to-market structures with established Japanese optical component suppliers to bypass cleanroom qualification timeline barriers.
For Investors and Strategic Acquirers: Roll-up economics work for overlay correction software specialists because foundry automation layers increasingly demand interoperable metrology platforms across multi-vendor equipment bases. Focus acquisition screening on firms with ISO 14644 cleanroom certification and established relationships with TSMC or Samsung procurement committees. Watch for inflection signals in HBM3E capacity expansion announcements as indicators of stepper procurement wave timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Chemical Recovery Deployment | EPA Clean Air Act compliance secures operating permits for Intel's Arizona and Ohio fab expansions. |
| EUV Research Consortium Participation | Albany Nanotech Complex coordination accelerates IBM's process development for sub-3 nanometer nodes. |
| Photonics Packaging Stepper Qualification | Canon i-line platforms capture margin-accretive demand from 800G optical transceiver manufacturers. |
| AI Overlay Correction Software Licensing | Machine learning calibration automation reduces engineer intervention hours at Samsung Pyeongtaek memory fabs. |
| India PLI Scheme Fab Equipment Supply | First-mover lithography deployments in Gujarat establish long-term service relationships with emerging foundries. |
Research Methodology
Bottom-up foundry capacity modeling reconciled against top-down lithography equipment shipment tracking forms the analytical core of this study. Primary interviews with fab operations directors, lithography tool procurement managers, metrology engineers, and cleanroom qualification specialists combined with secondary validation from SEMI equipment market data, EPA emission disclosure filings, EU REACH substance authorization registers, and foundry capital expenditure announcements. Triangulation between equipment vendor order backlogs and end-user installation timelines ensures volume estimates align with actual fab ramp schedules.
Input-output matrices connect node transition roadmaps to stepper system requirements across technology segments, with expansion trajectories derived from foundry announced capacity additions and memory manufacturer multi-patterning layer counts throughout the projection horizon. Segmentation dimensions include wavelength technology, overlay precision tier, fab automation architecture, and regional regulatory cluster. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and sovereign chip initiative funding disbursement patterns.
The model holds under stable foundry utilization rates and continued node scaling roadmaps; deviation in memory capital expenditure cycles or export control expansion would shift equipment demand trajectories. Periodic stress-testing of base assumptions against quarterly foundry utilization reports and lithography OEM order intake disclosures is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Holmium Sputtering Target Market