
 Epitaxial Wafer Market | 2026-2036
Epitaxial Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Epitaxial Wafer Market Intelligence
The EU Green Deal's semiconductor sovereignty targets is hardening demand for regional epitaxial wafer supply chains. Siltronic AG leverages its Dresden manufacturing complex to sustain polysilicon-to-epitaxial wafer integration. IQE PLC anchors compound semiconductor epitaxy leadership through its Cardiff and Massachusetts operations. Shin-Etsu Chemical dominates silicon epitaxial substrate supply with integrated crystal pulling and polishing capabilities.
An epitaxial wafer consists of a crystalline substrate upon which a thin film of identical or compatible crystal structure grows via controlled deposition, with layer thickness precision typically reaching single-atom scale for advanced RF and photonic applications. Metal-Organic Chemical Vapor Deposition produces the majority of GaN and InP epitaxial structures for LED and laser applications, while Molecular Beam Epitaxy commands premium positioning for aerospace-grade RF devices requiring atomic-layer abruptness. Gallium Nitride wafers for RF and power electronics represent the fastest-expanding product category, whereas silicon epitaxy retains volume leadership in automotive sensor and telecommunications markets.
The EPA enforces hazardous substance reporting for gallium and indium precursors used in epitaxial deposition, raising compliance costs for U.S.-based metal-organic chemical vapor deposition facilities. REACH and RoHS frameworks in Europe restrict cadmium and lead content in epitaxial process chemistries, pushing suppliers toward alternative precursor formulations. Stakeholders must monitor how the EU AI Act's chip performance thresholds redirect epitaxial specifications for edge-computing accelerators.
Market Dynamics
Power electronics manufacturers are consolidating silicon carbide and gallium nitride epitaxial wafer procurement around electric vehicle inverter programs, compressing supplier qualification timelines and concentrating volume commitments among vertically integrated substrate producers.
Growth Catalysts
- EU Green Deal semiconductor sovereignty targets:Regional capacity mandates are redirecting capital toward Dresden and Leuven epitaxial clusters, hardening demand for localized supply chains.
- Electric vehicle powertrain electrification:Tier-1 automotive suppliers are scaling silicon carbide epitaxial wafer orders for 800V inverter architectures.
- Metal-Organic Chemical Vapor Deposition throughput gains:Reactor productivity improvements are lowering gallium nitride epitaxy costs for LED and laser applications.
Market Restraints
- Precursor cost volatility:Trimethylgallium and trimethylindium prices fluctuate with rare earth refining capacity concentrated in China.
- Substrate supply concentration:Silicon carbide crystal growth expertise clusters in Japan and the United States, creating single-source risk for 150mm+ diameter substrates.
- Atomic-layer deposition technical limits:Molecular Beam Epitaxy throughput constraints cap volume scaling for aerospace-grade RF devices.
Strategic Opportunities
- India PLI scheme for compound semiconductors:Domestic epitaxial capacity incentives are attracting gallium nitride and silicon carbide investments for defense and telecommunications.
- Edge-computing accelerator specifications:The EU AI Act's chip performance thresholds are redirecting epitaxial specifications toward low-power, high-frequency compound semiconductor architectures.
- Photonic integrated circuit convergence:Indium phosphide epitaxy is merging with silicon photonics for datacenter interconnect applications.
Industry Challenges
- Crystallography and reactor engineering talent scarcity:Epitaxial growth specialists with MOCVD and MBE operational expertise command premium compensation.
- Automotive AEC-Q100 qualification timelines:Silicon carbide epitaxial wafer certification for traction inverters requires 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epitaxial Wafer Market |
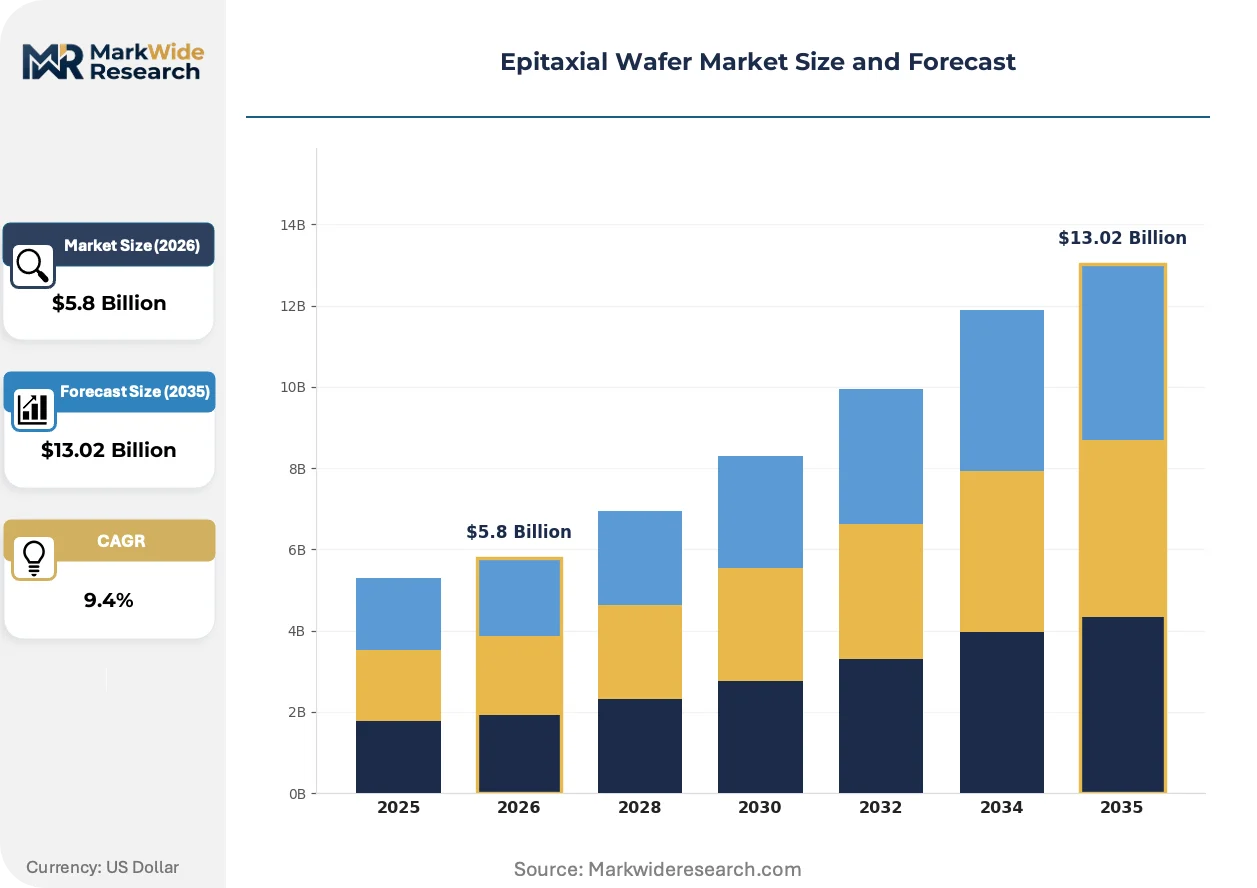
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Gallium Nitride, Indium Phosphide, Gallium Arsenide Application: LEDs, RF Devices, Solar Cells, Lasers End User: Consumer Electronics, Telecommunications, Automotive, Aerospace Technology: Molecular Beam Epitaxy, Metal-Organic Chemical Vapor Deposition, Liquid Phase Epitaxy, Chemical Vapor Deposition |
| Companies Covered | Siltronic AG, IQE PLC, Shin-Etsu Chemical Co., Ltd., Nichia Corporation, II-VI Incorporated, SUMCO Corporation, SK Siltron Co., Ltd., SHOWA DENKO K.K., GlobalWafers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epitaxial Wafer Market Strategic Shifts & Innovations
Gallium nitride epitaxy is penetrating power electronics faster than prior substrate transitions, compressing silicon's historical dominance in high-frequency switching applications.
GaN-on-silicon epitaxial structures handle 650V power conversion for consumer adapters and server power supplies. Data center operators and smartphone OEMs are adopting these wafers at twice the pace of previous wide-bandgap transitions. The technology is expanding into electric vehicle onboard chargers, displacing silicon superjunction MOSFETs in 3-6kW applications.
REACH and RoHS frameworks in Europe restrict cadmium and lead content in epitaxial process chemistries. Suppliers are reformulating metal-organic precursors to eliminate restricted substances ahead of 2026 sunset dates. Photonic device manufacturers face the steepest reformulation costs due to indium phosphide deposition chemistries.
Automotive power electronics buyers are consolidating silicon carbide epitaxial wafer contracts around multi-year supply agreements. Direct OEM-substrate supplier relationships are displacing distributor channels for 150mm and 200mm diameter specifications. Germany's Saxony cluster exhibits the most pronounced concentration of these bilateral procurement arrangements.
Epitaxial Wafer Market Segmentation
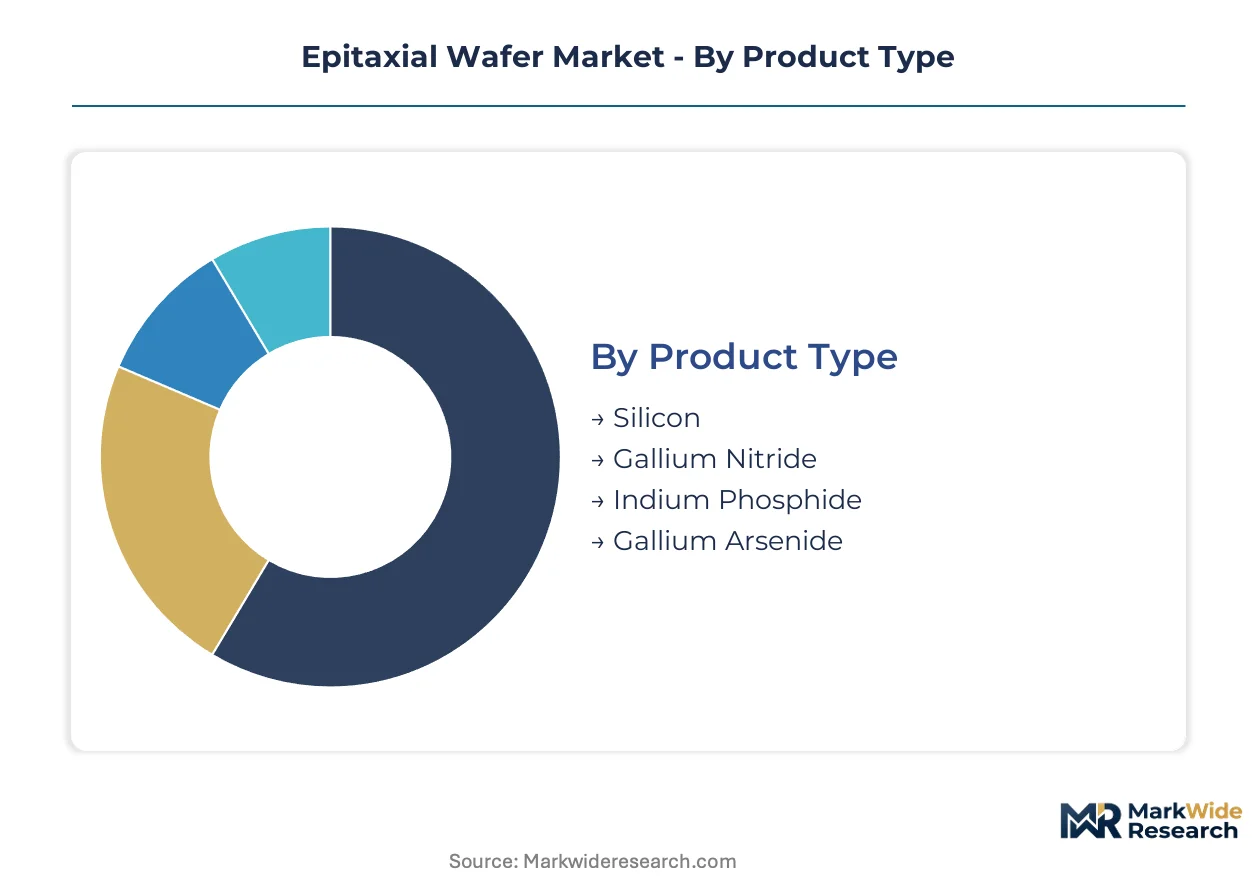
Epitaxial wafer procurement patterns diverge sharply between high-volume silicon substrates for automotive sensors and premium compound semiconductors for RF power amplifiers. Understanding these segment boundaries clarifies where reactor technology investments and qualification timelines concentrate.
Product Type:
Silicon epitaxy commands volume leadership while compound semiconductors capture value concentration in advanced applications.
- Silicon:Crystalline silicon layers deposited on silicon substrates serve automotive sensor arrays and telecommunications infrastructure. German automotive suppliers in Saxony and Bavaria anchor procurement for radar and lidar systems, with AEC-Q100 qualification timelines extending 18-24 months.
- Gallium Nitride:Wide-bandgap epitaxial structures enable 650V-1200V power switching with superior thermal performance. RF and power electronics manufacturers are scaling procurement fastest for electric vehicle inverters and 5G base station amplifiers.
- Indium Phosphide:Lattice-matched epitaxy for photonic integrated circuits and high-frequency RF devices.
- Gallium Arsenide:Legacy substrate for microwave and millimeter-wave applications in defense communications.
Today's leader: Silicon. Tomorrow's challenger: Gallium Nitride.
Application:
End-use requirements split between illumination-scale volumes and precision-device premiums.
- RF Devices:Epitaxial structures for radar, satellite communications, and cellular infrastructure demand atomic-layer thickness control. Aerospace-grade specifications from the FAA and EASA drive Molecular Beam Epitaxy adoption for phased-array antennas.
- LEDs:Gallium nitride epitaxy on sapphire or silicon substrates dominates solid-state lighting and display backlights. Metal-Organic Chemical Vapor Deposition reactor throughput gains are lowering costs for general illumination in India and Southeast Asia.
- Lasers:Edge-emitting and vertical-cavity surface-emitting structures for datacenter interconnects and sensing.
- Solar Cells:III-V multi-junction epitaxy for concentrated photovoltaics in satellite and terrestrial utility installations.
LEDs ship the most wafers. RF Devices extract the most value per square centimeter.
End User:
Customer sophistication ranges from consumer electronics price sensitivity to aerospace traceability mandates.
- Automotive:Tier-1 suppliers are consolidating silicon carbide and gallium nitride epitaxial contracts around 800V inverter platforms. Germany's KBA and U.S. NHTSA safety certifications require extended validation cycles that favor established substrate suppliers.
- Telecommunications:5G infrastructure deployment and fiber-optic backhaul drive indium phosphide and gallium arsenide demand for high-frequency signal processing.
- Consumer Electronics:Smartphone OEMs and laptop manufacturers adopt GaN-on-silicon power adapters for miniaturization.
- Aerospace:Satellite manufacturers specify radiation-hardened epitaxial structures with full lot traceability and extended temperature ranges.
Automotive buyers are tightening supplier qualification. Telecommunications buyers are expanding volume commitments.
Technology:
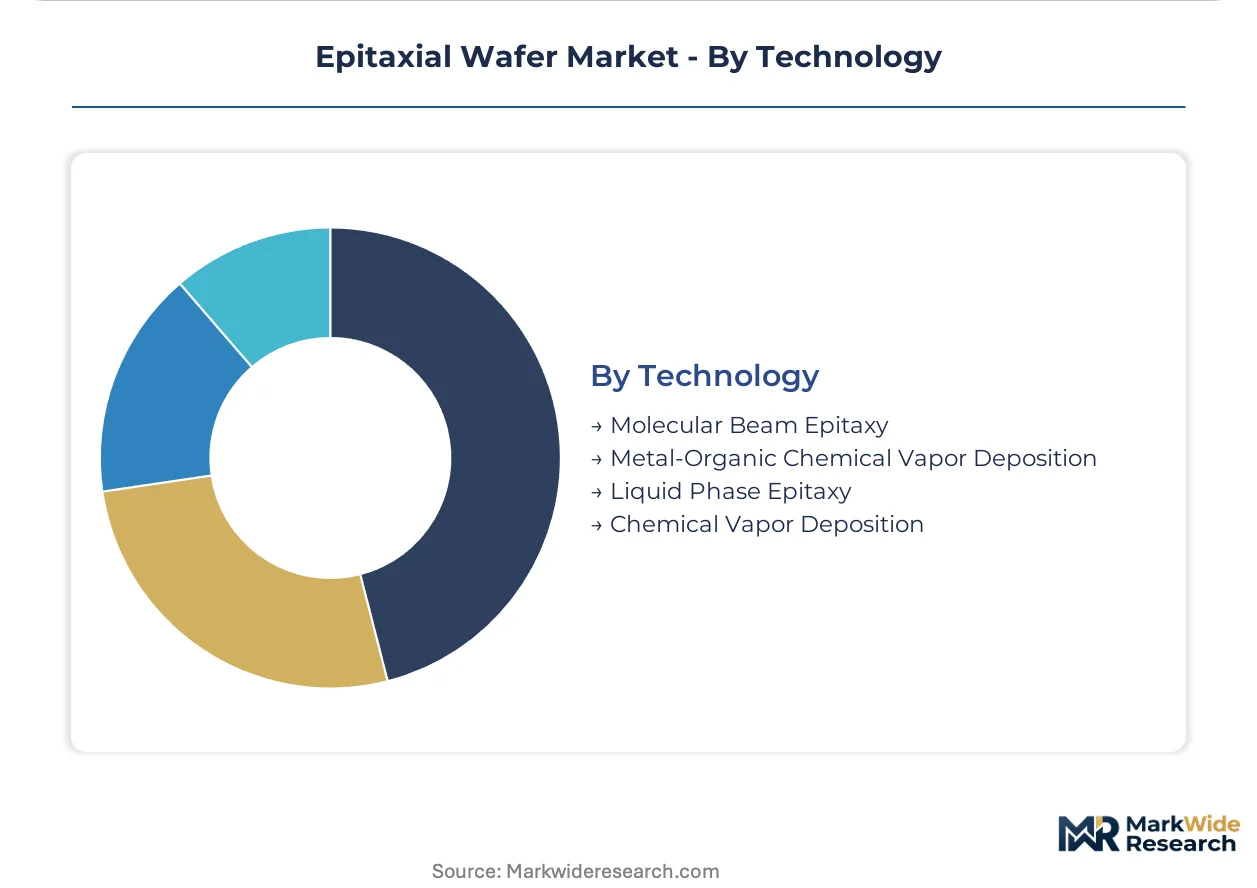
Deposition method selection trades throughput against atomic precision for each application class.
- Metal-Organic Chemical Vapor Deposition:Trimethylgallium and trimethylaluminum precursors enable high-throughput GaN and InP growth for LED and laser manufacturing. Reactor productivity improvements are expanding cost-competitive applications into consumer power electronics.
- Molecular Beam Epitaxy:Ultrahigh-vacuum deposition achieves single-atom layer abruptness for aerospace RF and quantum devices. Throughput constraints limit deployment to premium military and satellite communications markets.
- Chemical Vapor Deposition:Silane and dichlorosilane processes dominate silicon epitaxy for automotive and industrial sensors.
- Liquid Phase Epitaxy:Melt-based growth for specialized magneto-optic and mid-infrared detector applications.
MOCVD owns the volume frontier. MBE guards the precision frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epitaxial wafer manufacturing originated in German and Japanese industrial laboratories during the 1960s, establishing crystalline growth techniques that spread to U.S. defense contractors and later to Asian electronics manufacturing hubs. Dresden's Fraunhofer institutes and Tokyo's NTT laboratories seeded the process knowledge now diffusing through commercial foundries worldwide.
Germany
Automotive power electronics buyers in Saxony and Bavaria are consolidating silicon carbide epitaxial contracts around 800V inverter platforms. The EU Green Deal's semiconductor sovereignty targets redirect capital toward Dresden's epitaxial clusters, hardening demand for localized supply chains. Fraunhofer IPMS anchors applied research in Leuben while Siltronic AG leverages its integrated polysilicon-to-epitaxial complex.
United States
Defense contractors and satellite manufacturers specify radiation-hardened epitaxial structures with full lot traceability. The EPA enforces hazardous substance reporting for gallium and indium precursors, raising compliance costs for metal-organic chemical vapor deposition facilities. Greater Boston and the Research Triangle concentrate molecular beam epitaxy expertise for aerospace-grade RF devices.
Japan
Silicon carbide crystal growth expertise clusters in Kyushu and Kansai, creating concentrated substrate supply for power electronics manufacturers. METI's semiconductor revitalization policies support domestic epitaxial capacity expansion against import dependency. Shin-Etsu Chemical and SUMCO Corporation anchor integrated crystal pulling and polishing capabilities in the Tokyo metropolitan area.
China
Rare earth refining capacity for trimethylgallium and trimethylindium precursors concentrates in Inner Mongolia and Jiangxi, influencing global epitaxial deposition costs. MIIT's dual carbon goals accelerate silicon carbide and gallium nitride investments for electric vehicle and renewable energy applications. Yangtze River Delta foundries scale metal-organic chemical vapor deposition throughput for LED and consumer power electronics.
South Korea
Memory and display manufacturers drive demand for silicon epitaxy in sensor arrays and driver integrated circuits. The country's national semiconductor regulator coordinates with chaebol-led investments in compound semiconductor foundries. SK Siltron anchors substrate production in Gumi while Seoul Capital Area packaging houses handle backend integration for automotive qualification.
Epitaxial Wafer Market Key Industry Players
Capital-heavy producers compete with asset-light designers across deposition technology boundaries. The market structures around three tiers: integrated substrate-to-epitaxial manufacturers commanding automotive qualification timelines, pure-play epitaxial foundries serving RF and photonic device makers, and captive semiconductor divisions of vertically integrated electronics conglomerates. Strategic moves concentrate on multi-year supply agreements with automotive OEMs and reactor productivity investments for gallium nitride cost reduction.
Among European-anchored producers, Siltronic AG and IQE PLC occupy distinct archetype positions. Siltronic exemplifies the integrated substrate producer with backward control over polysilicon supply. IQE represents the pure-play compound semiconductor foundry model with distributed manufacturing footprints. Japanese incumbents including Shin-Etsu Chemical and SUMCO Corporation sit within the materials-integrated tier, leveraging crystal growth expertise that predates commercial epitaxial markets.
| Leading Market Players |
|---|
| Siltronic AG |
| IQE PLC |
| Shin-Etsu Chemical Co., Ltd. |
| Nichia Corporation |
| II-VI Incorporated |
| SUMCO Corporation |
| SK Siltron Co., Ltd. |
| SHOWA DENKO K.K. |
| GlobalWafers |
| Others |
Cost & Logistics Intelligence
Crystallography and reactor engineering talent scarcity in Germany's Saxony cluster widens labor-cost differentials between precision-tier Molecular Beam Epitaxy operations and volume-tier Metal-Organic Chemical Vapor Deposition facilities, compressing pricing spreads for commodity silicon epitaxy while sustaining premiums for aerospace-grade RF specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade MBE wafers with full lot traceability from automotive-qualified silicon carbide epitaxy and consumer-grade LED substrates. Price differentiation rests on AEC-Q100 certification tier and volume scale, with automotive buyers consolidating multi-year contracts around 800V inverter platforms. Cost compression in GaN-on-silicon consumer adapters intensifies as reactor throughput gains lower unit economics. Consumer electronics OEMs exhibit highest price sensitivity; satellite manufacturers show least.
Supply Chain Analysis
Dual-sourcing requirements from automotive Tier-1 suppliers mandate multi-supplier qualification for silicon carbide epitaxial wafers, dispersing procurement across Japan's Kyushu cluster, Germany's Dresden complex, and U.S. Research Triangle facilities. Raw material dependencies center on trimethylgallium and trimethylindium precursors from China's Inner Mongolia refining capacity, plus 150mm+ silicon carbide substrates from Japanese crystal growers. Single-source vulnerability concentrates in rare earth precursor supply. Distribution runs through direct OEM-substrate supplier relationships displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as electric vehicle powertrain electrification shifts procurement specifications toward automotive-qualified silicon carbide and gallium nitride epitaxy with extended validation cycles.
For Market Incumbents: Hedge against emerging Chinese compound semiconductor foundries by securing AEC-Q100 certification ahead of 18-24 month validation windows and anchoring multi-year supply agreements with Germany's KBA-regulated automotive OEMs. Backward integration into polysilicon supply sustains margin control against precursor cost volatility. For New Entrants and Emerging Players: Enter via India's PLI scheme for compound semiconductors, targeting defense and telecommunications applications with lower qualification barriers than automotive traction inverters. White-space concentrates in gallium nitride epitaxy for 3-6kW electric vehicle onboard chargers displacing silicon superjunction MOSFETs. For Investors and Strategic Acquirers: Automotive power electronics manufacturers are the most active acquirer in this space, consolidating substrate-to-epitaxial capabilities to secure 800V inverter supply chains. Long-term viability favors integrated producers with captive crystal growth and reactor engineering talent pipelines. Watch for MIIT policy acceleration on dual carbon goals as inflection signal for Chinese capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Supply Agreement | Automotive OEMs in Germany's Saxony cluster lock in 150mm silicon carbide epitaxy volumes ahead of capacity constraints. |
| Reactor Productivity Investment | MOCVD throughput gains lower gallium nitride epitaxy costs for LED and consumer power electronics applications. |
| Backward Integration | Siltronic AG's Dresden complex controls polysilicon-to-epitaxial wafer production against precursor price volatility. |
| Certification Pre-Investment | Early AEC-Q100 qualification captures Tier-1 automotive procurement consolidation around 800V inverter platforms. |
| Regional Capacity Expansion | EU Green Deal semiconductor sovereignty targets redirect capital toward Dresden and Leuven epitaxial clusters. |
Research Approach
Coverage spans Germany, United States, Japan, China, and South Korea, with primary inputs from each combining interviews with epitaxial reactor operators, automotive Tier-1 procurement leads, compound semiconductor R&D directors, and regulatory affairs specialists with secondary validation. Secondary sources include EPA hazardous substance filings, ECHA REACH registration databases, METI semiconductor policy documents, and SEC 10-K disclosures from substrate manufacturers. Bottom-up wafer shipment tallies triangulate against top-down power electronics demand estimates.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type, application, end user, and technology dimensions, with additional segmentation by regional regulatory cluster and qualification tier. CAGRs derive from fitted growth curves calibrated to electric vehicle penetration rates and 5G infrastructure deployment trajectories. Industry-specific inputs include MOCVD reactor utilization rates and silicon carbide crystal growth yield assumptions.
Inputs from automotive OEM procurement committees and epitaxial foundry operations directors were available through the study window; gaps in real-time precursor inventory data from Chinese rare earth refiners introduce uncertainty bands around cost projections. Deviation in EU AI Act chip performance thresholds or EPA enforcement intensity on gallium precursor reporting would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market