
 300mm Silicon Wafers Market | 2026-2036
300mm Silicon Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
300mm Silicon Wafers Market Insights
Multi-source procurement for 300mm silicon wafers is hardening as semiconductor manufacturers reduce dependence on single-geo supply chains. Shin-Etsu Chemical anchors its position through captive polysilicon refining and crystal pulling capacity in Japan. SUMCO competes via epitaxial wafer specialization for automotive-grade chips. SK Siltron leverages South Korean fab proximity to secure binding supply agreements with memory producers.
300mm silicon wafers are single-crystal silicon substrates measuring 300 millimeters in diameter, polished to atomic flatness via chemical mechanical planarization for photolithography compatibility. These wafers serve as the foundational platform for fabricating integrated circuits with nanometer-scale feature densities. Epi wafers command premium positioning due to defect-free epitaxial layers required for power devices and RF applications. N-type wafers represent the fastest-growing product category as silicon carbide-competing MOSFET architectures shift doping polarity. Semiconductor manufacturers absorb the majority of volume, though automotive suppliers are accelerating qualification timelines for wafer-level reliability standards.
Japan's METI coordinates domestic silicon supply security through critical material designation and stockpiling directives. REACH and RoHS frameworks in Europe restrict trace metal contamination thresholds for wafers entering automotive and medical device supply chains. EPA hazardous waste rules in the United States govern slurry disposal from CMP and wafer thinning operations. Stakeholders must monitor how export control expansions on crystal growing equipment reshape manufacturing geography decisions.
Market Dynamics
The 300mm silicon wafer market pivots on foundry capex cycles and geopolitical reshoring mandates, with subsidy regimes in the United States, European Union, and Japan now dictating where new crystal pulling capacity materializes.
Growth Catalysts
- US CHIPS and Science Act:Direct funding and tax credits for domestic 300mm substrate production are pulling Shin-Etsu Chemical and GlobalWafers toward greenfield expansions in Texas and Oregon.
- Automotive power semiconductor qualification:Tier-1 suppliers are accelerating wafer-level reliability testing for silicon carbide-competing MOSFET architectures on n-type 300mm substrates.
- Advanced node logic migration:Taiwan and South Korea foundries are binding multi-year supply agreements for epi-ready 300mm wafers at 3nm and 2nm process nodes.
Market Restraints
- Polysilicon input volatility:Energy-intensive metallurgical-grade silicon refining exposes wafer manufacturers to European natural gas price swings and Chinese electricity rationing.
- Equipment export controls:US Bureau of Industry and Security restrictions on crystal growing furnaces and Czochralski pullers constrain capacity expansion in mainland China.
- Silicon carbide substrate substitution:Wolfspeed and Coherent are qualifying 200mm SiC wafers for high-voltage power modules, compressing addressable silicon wafer demand in traction inverters.
Strategic Opportunities
- India semiconductor mission:The country's production-linked incentive scheme for fabs is creating first-mover advantage for wafer suppliers establishing local polishing and epitaxy operations.
- EU Chips Act sovereignty mandates:Brussels targets 20% of global 300mm wafer supply from European sources by 2030, opening public procurement channels for SUMCO and Siltronic expansions.
- Photonics-silicon convergence:Silicon photonics foundries require specialized 300mm SOI wafers with thick buried oxide layers for co-packaged optical interconnects in data centers.
Industry Challenges
- Crystal defect engineering talent scarcity:The intersection of materials science and semiconductor process engineering lacks sufficient practitioners to staff new pulling and epitaxy facilities in Arizona and Dresden.
- Automotive AEC-Q100 qualification timelines:Wafer suppliers face 18-to-24-month validation cycles for zero-defect epitaxial layers in advanced driver-assistance system chips.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 300mm Silicon Wafers Market |
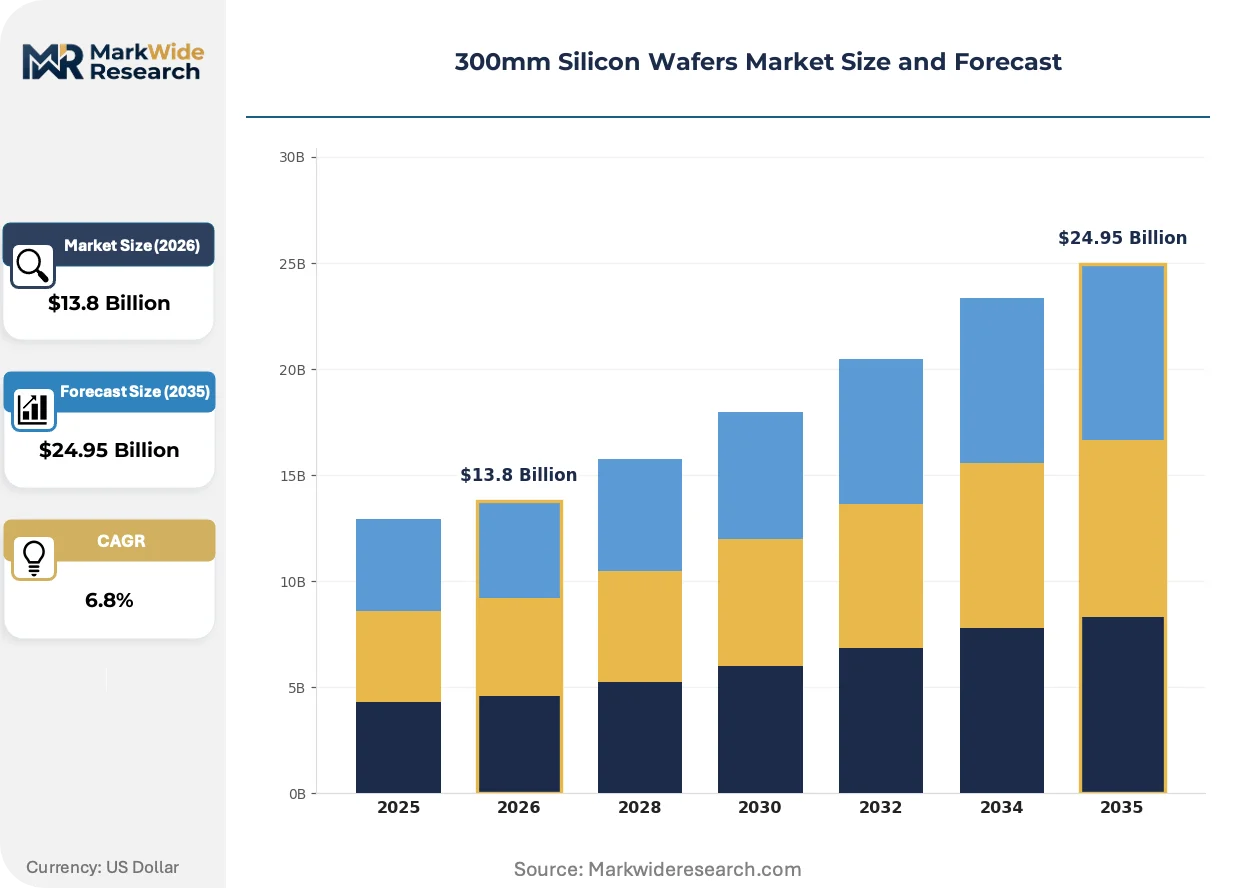
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SOI Wafers, Epi Wafers, P-type Wafers, N-type Wafers End User: Semiconductor Manufacturers, Electronics Firms, Researchers, Automotive Suppliers Application: Integrated Circuits, MEMS, Solar Cells, Sensors Technology: CVD, CMP, Ion Implantation, Lithography |
| Companies Covered | Shin-Etsu Chemical, SUMCO, GlobalWafers, Siltronic, SK Siltron, NSIG, TCL Zhonghuan, Hangzhou Lion, Wafer Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
300mm Silicon Wafers Market Trends and Innovations
Wafer manufacturing is bifurcating between commodity polishing operations and captive epitaxy services, with equipment automation and regulatory traceability emerging as the primary axes of differentiation.
Smart cutting wire technologies are expanding into 300mm wafer manufacturing as diamond-coated wires replace slurry-based silicon ingot slicing. Shin-Etsu Chemical and SK Siltron are retrofitting multi-wire saws with real-time tension monitoring to reduce kerf loss below 180 microns. This precision is expanding into thinner wafer architectures for 3D stacking applications, compressing raw silicon consumption per die output.
Japan's METI has designated 300mm silicon wafers as critical materials under its economic security legislation, triggering mandatory six-month inventory stockpiling for domestic semiconductor manufacturers. The framework requires suppliers to report monthly polysilicon and ingot reserves to prevent supply chain disruption. Japanese foundry customers are now prioritizing domestic wafer sources over price-competitive imports to satisfy METI audit requirements.
Binding long-term supply agreements are displacing spot-market purchasing as the dominant procurement modality for 300mm wafers. Memory producers in South Korea and logic foundries in Taiwan are negotiating five-to-seven-year take-or-pay contracts with fixed volume floors and price reopener clauses tied to polysilicon indices. This contractual shift is most visible in Hsinchu and Pyeongtaek, where fabs are securing wafer supply security ahead of EUV lithography ramp schedules.
300mm Silicon Wafers Market Segmentation
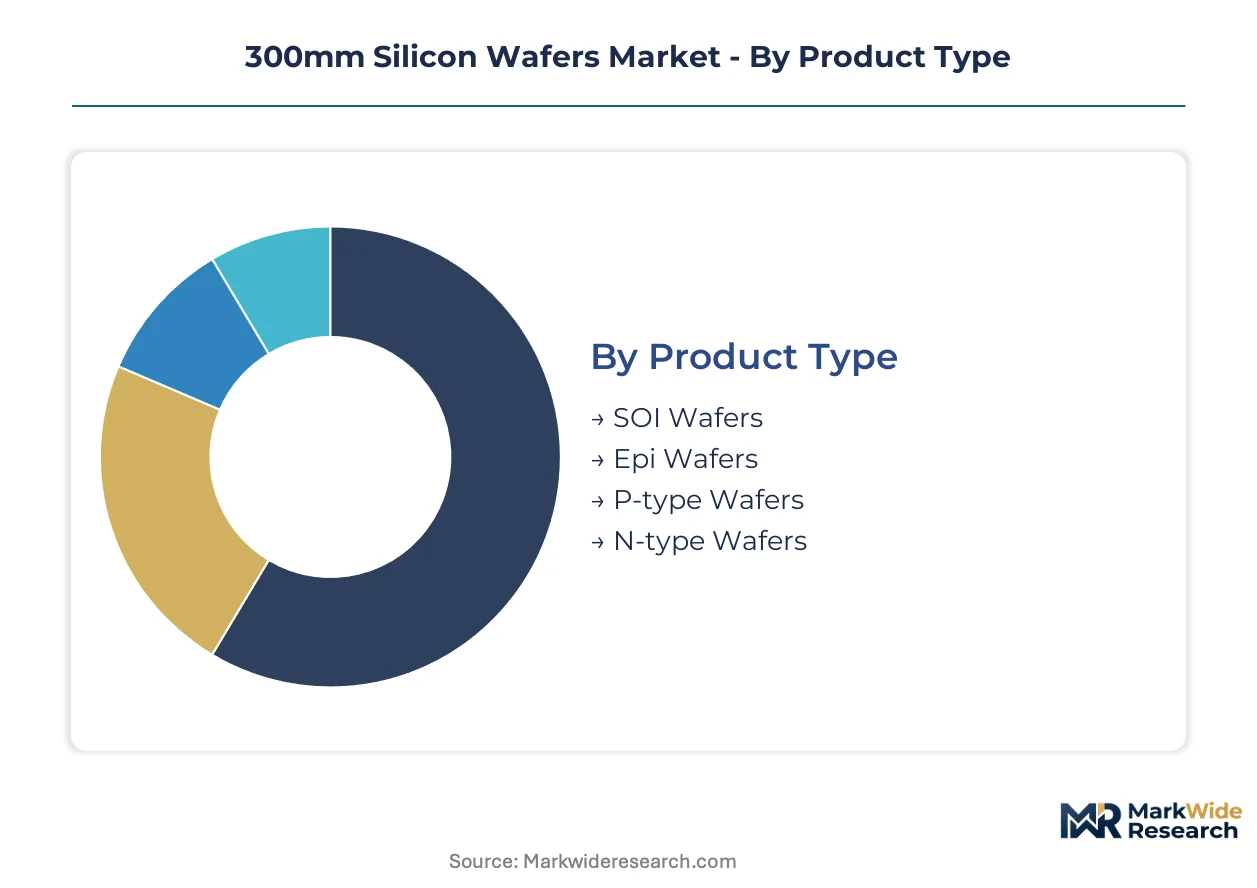
300mm silicon wafer purchasing decisions split between performance-critical specifications and cost-optimized volumes. Procurement patterns diverge sharply across product types and end-use applications, with automotive qualification timelines reshaping supplier selection criteria.
Product Type:
Volume concentrates in polished substrates while premium pricing attaches to engineered layers and specialized doping profiles.
- Epi Wafers:Defect-free crystalline silicon layers grown via chemical vapor deposition on polished substrates enable power MOSFETs and RF front-end modules. Taiwan foundries and South Korean memory houses bind multi-year supply agreements for 3nm-class epitaxial stacks, with automotive suppliers accelerating qualification for traction inverter applications.
- N-type Wafers:Phosphorus-doped substrates with electron majority carriers suit silicon carbide-competing MOSFET architectures and high-efficiency solar cells. European power semiconductor specialists and Chinese photovoltaic ingot pullers are expanding n-type purchasing commitments as device architectures shift doping polarity for breakdown voltage optimization.
- SOI Wafers:Silicon-on-insulator structures with buried oxide layers enable low-power logic and RF isolation for 5G baseband processors.
- P-type Wafers:Boron-doped substrates remain the workhorse for commodity CMOS logic and mainstream memory fabrication.
Today's leader: Epi wafers. Tomorrow's challenger: N-type wafers.
End User:
Customer type determines contract structure, with foundries demanding binding long-term agreements and research buyers tolerating spot-market volatility.
- Semiconductor Manufacturers:Integrated device foundries and memory houses consume the majority of 300mm wafer output, negotiating take-or-pay contracts with polysilicon price reopeners. TSMC, Samsung Foundry, and SK Hynix operate dedicated supplier qualification programs that lock in crystal pulling capacity eighteen months ahead of EUV lithography ramps.
- Automotive Suppliers:Tier-1 power module manufacturers impose AEC-Q100 wafer-level reliability standards with zero-defect epitaxial layer requirements. Infineon, STMicroelectronics, and Bosch are compressing qualification timelines from thirty-six to twenty-four months as electric vehicle production schedules accelerate.
- Electronics Firms:Discrete component and analog semiconductor producers purchase smaller lots with less stringent crystal orientation tolerances.
- Researchers:National laboratories and university cleanrooms acquire experimental quantities for process development and materials characterization.
Foundry procurement dominates contract value. Automotive qualification is climbing the fastest as a demand driver.
Application:
Feature density requirements and thermal budgets segment the addressable market between leading-edge logic and mature-node specialty devices.
- Integrated Circuits:Microprocessors, GPUs, and AI accelerators fabricated at 5nm and below demand the tightest crystal defect specifications and lowest metal contamination levels. Taiwan and South Korea foundries specify epitaxial surface preparation compatible with EUV lithography double-patterning schemes.
- MEMS:Micro-electromechanical systems for inertial sensors, microphones, and pressure transducers tolerate higher surface roughness in exchange for specialized wafer thinning and through-silicon via preparation.
- Sensors:Image sensors and environmental detectors utilize 300mm wafers for die-size economics at moderate feature densities.
- Solar Cells:High-efficiency n-type heterojunction and TOPCon architectures are migrating to 300mm pseudo-square formats for equipment compatibility with semiconductor fabs.
Logic ICs command premium positioning. MEMS applications are expanding most quickly as automotive and consumer sensor fusion multiplies die counts per vehicle.
Technology:
Process equipment selection determines surface preparation quality and layer engineering capabilities across the manufacturing flow.
- CMP:Chemical mechanical planarization delivers atomic-scale flatness via abrasive slurry polishing, enabling sub-7nm lithography depth-of-field requirements. Tokyo Electron and Applied Materials dominate equipment supply for 300mm wafer polishing stations.
- CVD:Chemical vapor deposition grows epitaxial silicon layers with precise doping control for power and RF devices.
- Ion Implantation:Accelerated dopant species enable ultra-shallow junction formation for advanced logic transistors.
- Lithography:Photoresist coating and patterning compatibility requirements drive wafer edge profile and flatness specifications.
CMP anchors surface preparation economics. CVD epitaxy is gaining share fastest as wide-bandgap-competing silicon devices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hsinchu Science Park anchors global 300mm wafer consumption through TSMC's leading-edge foundry complex. Manufacturing geography is shifting as subsidy regimes in the United States, European Union, and Japan pull new crystal pulling capacity away from traditional Asian clusters.
Taiwan
TSMC and United Microelectronics Corporation consume the majority of global epi-ready 300mm supply for 3nm and 2nm process ramps. The National Science and Technology Council coordinates domestic material security through critical supply chain designation. Hsinchu and Tainan Science Parks concentrate binding long-term supply agreements with Japanese wafer suppliers.
United States
Intel, Samsung Austin, and emerging foundries drive demand for AEC-Q100 qualified wafers for automotive power semiconductors. The CHIPS and Science Act directs funding and tax credits toward domestic 300mm substrate production. Arizona and Texas host greenfield expansions by Shin-Etsu Chemical and GlobalWafers to serve Intel's advanced packaging roadmaps.
Japan
Tokyo Electron, Shin-Etsu Chemical, and Renesas anchor demand for specialized SOI wafers and photonics substrates. METI designates 300mm silicon wafers as critical materials under economic security legislation, triggering mandatory six-month inventory stockpiling. The Kyushu and Tohoku regions concentrate crystal pulling and epitaxy capacity serving domestic and export markets.
South Korea
Samsung Foundry and SK Hynix bind multi-year take-or-pay contracts for memory-grade and logic-grade 300mm wafers. The Ministry of Trade, Industry and Energy coordinates supply security through semiconductor material stockpiling directives. Pyeongtaek and Yongin cluster the majority of domestic fab capacity, with SK Siltron leveraging geographic proximity for binding supply agreements.
Germany
Bosch, Infineon, and STMicroelectronics' local operations accelerate qualification timelines for automotive power device wafers. The EU Chips Act targets 20% of global 300mm wafer supply from European sources by 2030, opening public procurement channels. Dresden and Bavaria concentrate silicon carbide-competing MOSFET development, compressing traditional silicon wafer demand in traction inverters.
300mm Silicon Wafers Market Competitive Landscape
Global majors compete with regional champions across captive supply integration and geographic proximity to foundry clusters. The vendor base concentrates around Japanese and South Korean incumbents with deep backward integration into polysilicon refining, while Taiwanese and Chinese challengers expand through cost-optimized polishing capacity. Three archetypes dominate: integrated chemical conglomerates with captive polysilicon supply, pure-play wafer specialists with epitaxy differentiation, and memory-proximate fabricators leveraging foundry co-location. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with subsidy access determining greenfield location decisions.
Among Japanese chemical conglomerates, Shin-Etsu Chemical and SUMCO exemplify integrated archetypes with upstream control over polysilicon refining and crystal pulling. SK Siltron occupies a position within the memory-proximate tier, leveraging South Korean fab concentration for binding supply security. GlobalWafers and Siltronic represent European-headquartered specialists navigating EU Chips Act sovereignty mandates for regional capacity expansion.
| Leading Market Players |
|---|
| Shin-Etsu Chemical |
| SUMCO |
| GlobalWafers |
| Siltronic |
| SK Siltron |
| NSIG |
| TCL Zhonghuan |
| Hangzhou Lion |
| Wafer Works |
| Others |
Pricing and Supply Chain Analysis
Metallurgical-grade polysilicon refining costs cascade through 300mm wafer pricing tiers, with energy-intensive crystal pulling operations in Japan and South Korea feeding premium epi-ready substrates to Taiwan foundries while commodity polished wafers face margin compression from Chinese polishing capacity expansion.
Pricing Analysis
Input-cost pass-through from polysilicon spot indices governs contract reopener clauses in multi-year offtake agreements between Japanese suppliers and Taiwan foundries. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 qualified automotive epi wafers from commodity memory-grade substrates. Cost compression in polished wafer tiers is intensifying because Chinese manufacturers are scaling 300mm capacity with government subsidy support. Memory producers exhibit highest price sensitivity due to cyclical bit-demand volatility, while automotive power semiconductor buyers accept premium positioning for zero-defect epitaxial layer guarantees.
Supply Chain Analysis
AEC-Q100 and automotive IATF 16949 certification gates constrain qualified supplier pools to Japanese and South Korean incumbents with proven crystal defect engineering track records. Manufacturing concentrates in Japan, South Korea, and Taiwan, with raw material dependencies spanning metallurgical-grade silicon from China, high-purity polysilicon from Germany and the United States, and Czochralski furnace components subject to US Bureau of Industry and Security export controls. Single-source vulnerability in crystal growing equipment creates supply chain risk for capacity expansion timelines. Distribution runs through direct binding long-term agreements rather than spot-market channels, with foundries locking pulling capacity eighteen months ahead of EUV lithography ramps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in 300mm silicon wafers rests on defect-free epitaxial layer premiums and polysilicon cost-down from smart cutting wire adoption, with automotive qualification timelines compressing from thirty-six to twenty-four months as electric vehicle production schedules accelerate.
For Market Incumbents: Deploy backward integration into captive polysilicon refining to defend margin position against Chinese polishing capacity entrants. Shin-Etsu Chemical and SUMCO should expand crystal pulling capacity in Texas and Oregon under CHIPS Act subsidy coverage, while accelerating AEC-Q100 qualification pipelines for automotive power device customers facing silicon carbide substitution threats.
For New Entrants and Emerging Players: Photonics-silicon convergence buyers represent underserved white-space demand for thick buried oxide SOI wafers in data center co-packaged optical interconnects. India's production-linked incentive scheme for fabs creates geographic entry opportunity for polishing and epitaxy operations, with first-mover advantage accruing to suppliers establishing local presence before EUV lithography capacity materializes.
For Investors and Strategic Acquirers: Consolidation pressure builds where crystal defect engineering talent scarcity constrains new facility staffing in Arizona and Dresden. Long-term viability favors integrated chemical conglomerates with upstream polysilicon control and proven automotive qualification track records. Watch for binding supply agreement announcement velocity from Taiwan foundries as inflection indicator for capacity tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Refining | Shin-Etsu Chemical's captive supply secures margin insulation against Chinese electricity rationing volatility. |
| Automotive AEC-Q100 Qualification Acceleration | Infineon and STMicroelectronics compression of validation timelines opens premium tier access for qualified suppliers. |
| Smart Cutting Wire Technology Deployment | Diamond-coated wire retrofit reduces kerf loss below 180 microns, compressing raw silicon consumption per die output. |
| India Local Polishing and Epitaxy Establishment | Production-linked incentive scheme creates first-mover positioning ahead of domestic EUV lithography ramp schedules. |
| Photonics-Silicon SOI Wafer Specialization | Thick buried oxide layers enable silicon photonics foundry demand for data center optical interconnect applications. |
Research Methodology
Multiple input streams — primary interviews with crystal growth engineers and foundry procurement directors, secondary validation through SEMI silicon shipment statistics and METI critical material stockpile reports, trade data from Japan Customs and Korea Customs Service — were reconciled through bottom-up capacity modeling and top-down demand triangulation across semiconductor manufacturers, automotive Tier 1 suppliers, and research institution buyers.
Historical capacity utilization patterns were cross-referenced against panel input from epitaxy equipment vendors and polysilicon producers to construct the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, application technology node, and regional fab cluster. CAGRs were derived from wafer area demand projections tied to foundry capex disclosure patterns and memory bit-growth trajectories, with EUV lithography ramp schedules and automotive power semiconductor content per vehicle serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; epi wafer and n-type categories carry tighter precision than commodity p-type polished substrates due to binding contract visibility. Forecasts reflect assumptions on subsidy regime continuity, export control enforcement intensity, and silicon carbide substitution velocity. Deviation in CHIPS Act funding disbursement timelines or EU Chips Act sovereignty mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market