
 Global Atomic Layer Deposition Market | 2026-2036
Global Atomic Layer Deposition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atomic Layer Deposition Market Intelligence
Equipment leasing and project-based financing is tilting competitive dynamics toward capital-light entrants who previously faced barriers to procuring multi-million dollar deposition systems. ASM International N.V. leverages its thermal ALD leadership to anchor long-term service contracts with memory chip producers. Oxford Instruments plc specializes in research-scale systems that occupy the pilot-line segment where universities and national labs drive early-stage process validation. Tokyo Electron Limited dominates integrated facility deployments through its broad semiconductor equipment portfolio and captive supply of adjacent process tools.
Atomic layer deposition constitutes a sequential, self-limiting gas-phase process that deposits films one atomic layer per cycle with sub-angstrom thickness precision, typically operating at temperatures between 150°C and 350°C depending on precursor chemistry and substrate requirements. The technique enables conformal coating of high-aspect-ratio structures critical for advanced semiconductor nodes, including gate-all-around transistors and 3D NAND memory stacks. Thermal ALD commands the largest installed base among technology segments, while plasma-enhanced ALD grows fastest as chipmakers adopt lower-temperature processes compatible with sensitive materials. Semiconductor fabrication absorbs the majority of system shipments, though photovoltaic cell producers represent an expanding application as perovskite tandem architectures mature toward commercial scale.
The U.S. FDA regulates ALD-coated medical devices where biocompatible barrier layers contact tissue or blood, while the EPA governs precursor chemical handling and emissions during manufacturing operations. China's MIIT enforces GB standards for semiconductor equipment imports that shape qualification timelines for foreign tool vendors. Japan's METI coordinates national R&D consortia that influence deposition technology roadmaps through JIS standards alignment. Stakeholders must monitor how divergent precursor substance regulations across these jurisdictions affect supply chain configurations and equipment certification pathways.
Market Dynamics
The transition to gate-all-around transistor architectures at sub-3nm nodes is compressing deposition tolerances to atomic-scale precision, forcing equipment vendors to recalibrate thermal budgets and precursor delivery systems for high-volume manufacturing.
Growth Catalysts
- EU Chips Act capital subsidies:Foundry buildouts across Germany, France, and Spain are accelerating procurement cycles for precision deposition tools as member states compete for sovereign semiconductor capacity.
- 3D NAND stacking progression:Memory producers now exceed 200-layer architectures, multiplying ALD cycle counts per wafer and expanding installed base requirements for conformal barrier deposition.
- Perovskite tandem commercialization:Photovoltaic manufacturers are qualifying ALD-grown electron transport layers for next-generation solar cells, opening a non-semiconductor demand vertical with distinct equipment specifications.
Market Restraints
- Precursor supply concentration:Organometallic precursor synthesis concentrates among German and Japanese specialty chemical suppliers, creating vulnerability to export licensing delays.
- Extreme ultraviolet lithography co-dependency:ALD patterning fidelity assumes EUV-resist compatibility, tying deposition tool validation to scanner availability timelines at leading-edge foundries.
- Plasma-enhanced ALD temperature floors:Damage-sensitive materials including certain high-k dielectrics constrain plasma power ranges, limiting throughput gains versus thermal alternatives.
Strategic Opportunities
- India's semiconductor manufacturing incentives:The country's PLI scheme for fabs and ATMP facilities is attracting deposition equipment vendors to establish local service infrastructure ahead of projected demand.
- Spatial ALD for roll-to-roll processing:Flexible electronics and battery separator coating applications are emerging as volume outlets for atmospheric-pressure deposition architectures distinct from vacuum batch systems.
- EU F-Gas Regulation phase-down:The mandated reduction in fluorinated greenhouse gases is accelerating adoption of precursor recovery and abatement systems as a bundled equipment feature.
Industry Challenges
- Process engineer scarcity:The intersection of surface chemistry, vacuum science, and semiconductor physics required for ALD recipe development outpaces university pipeline output.
- Multi-year qualification protocols:Fab integration of new deposition tools requires 18-24 month validation cycles against existing process-of-record equipment, compressing vendor revenue recognition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atomic Layer Deposition Market |
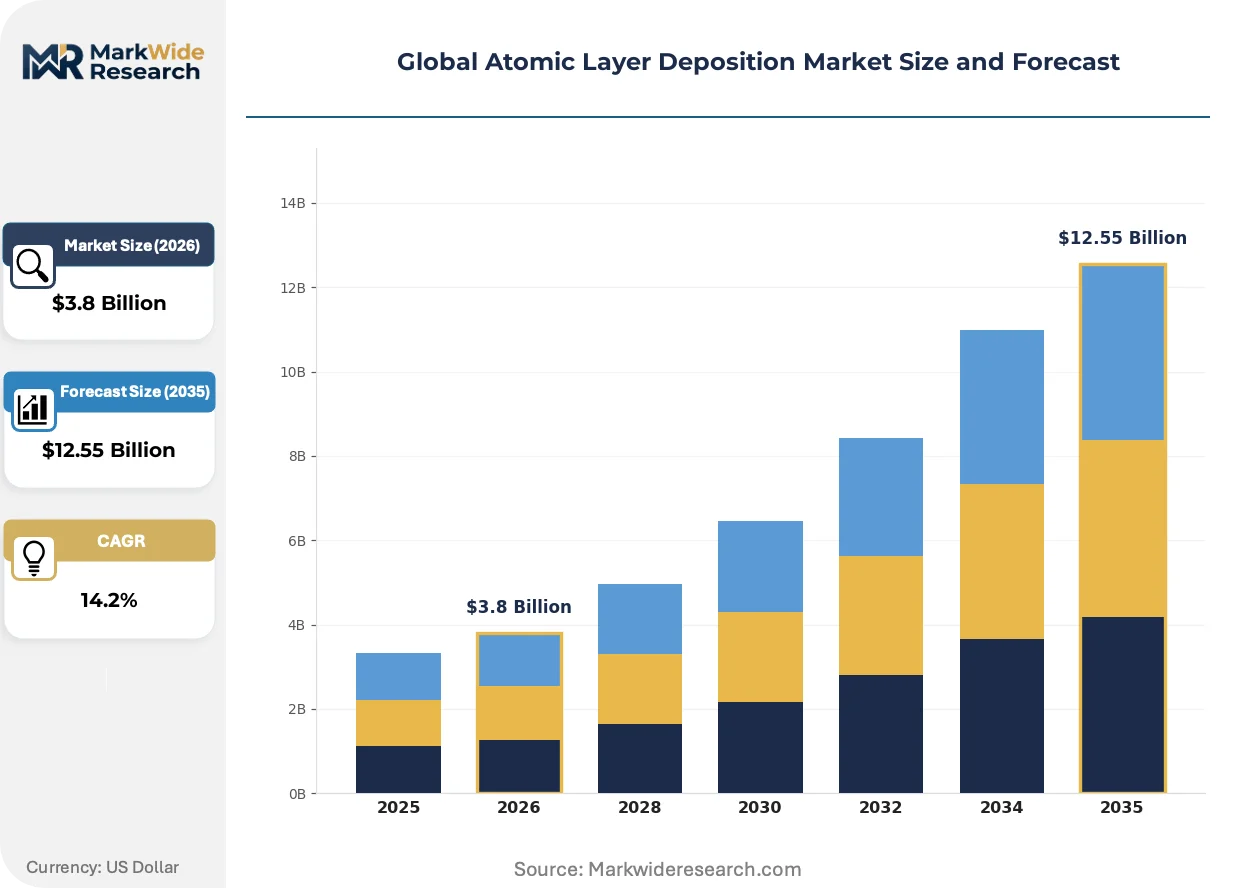
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
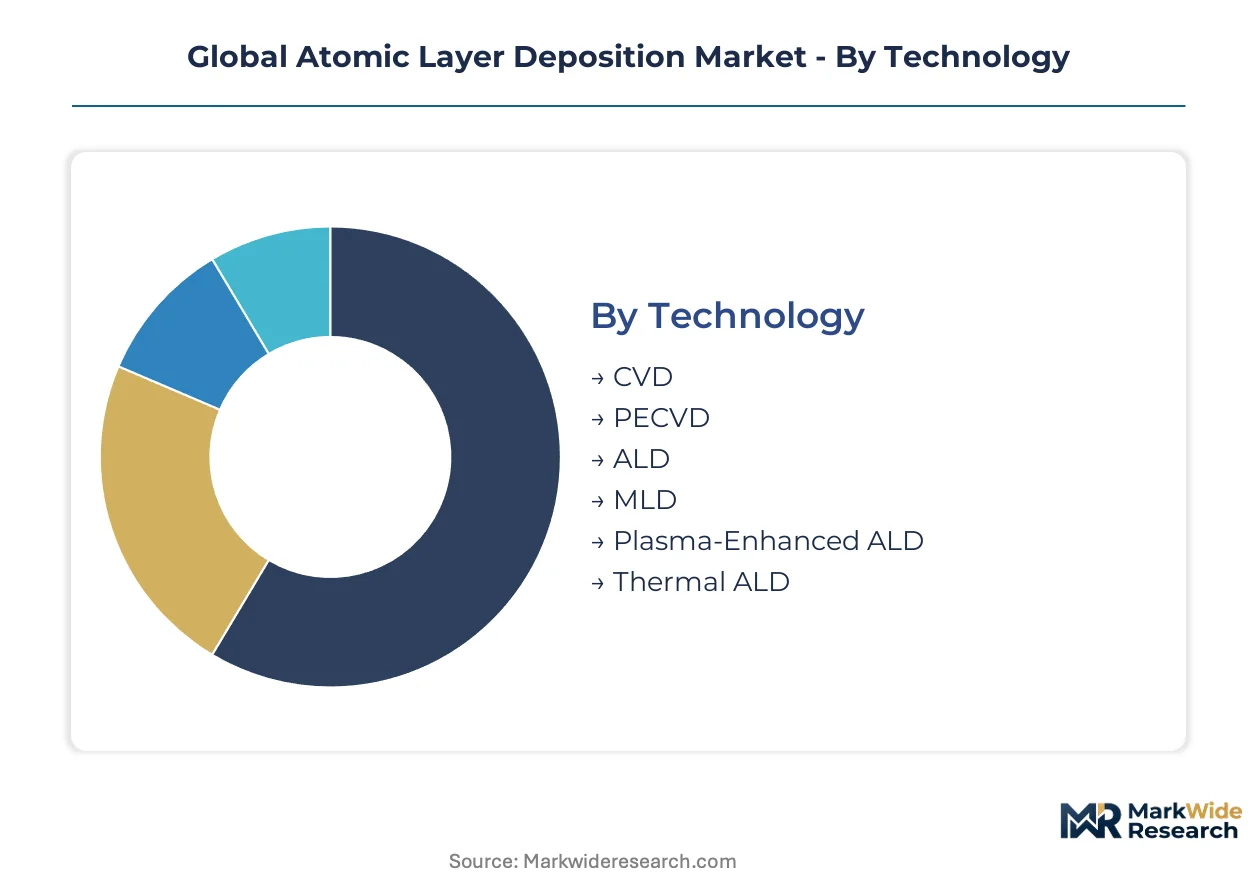
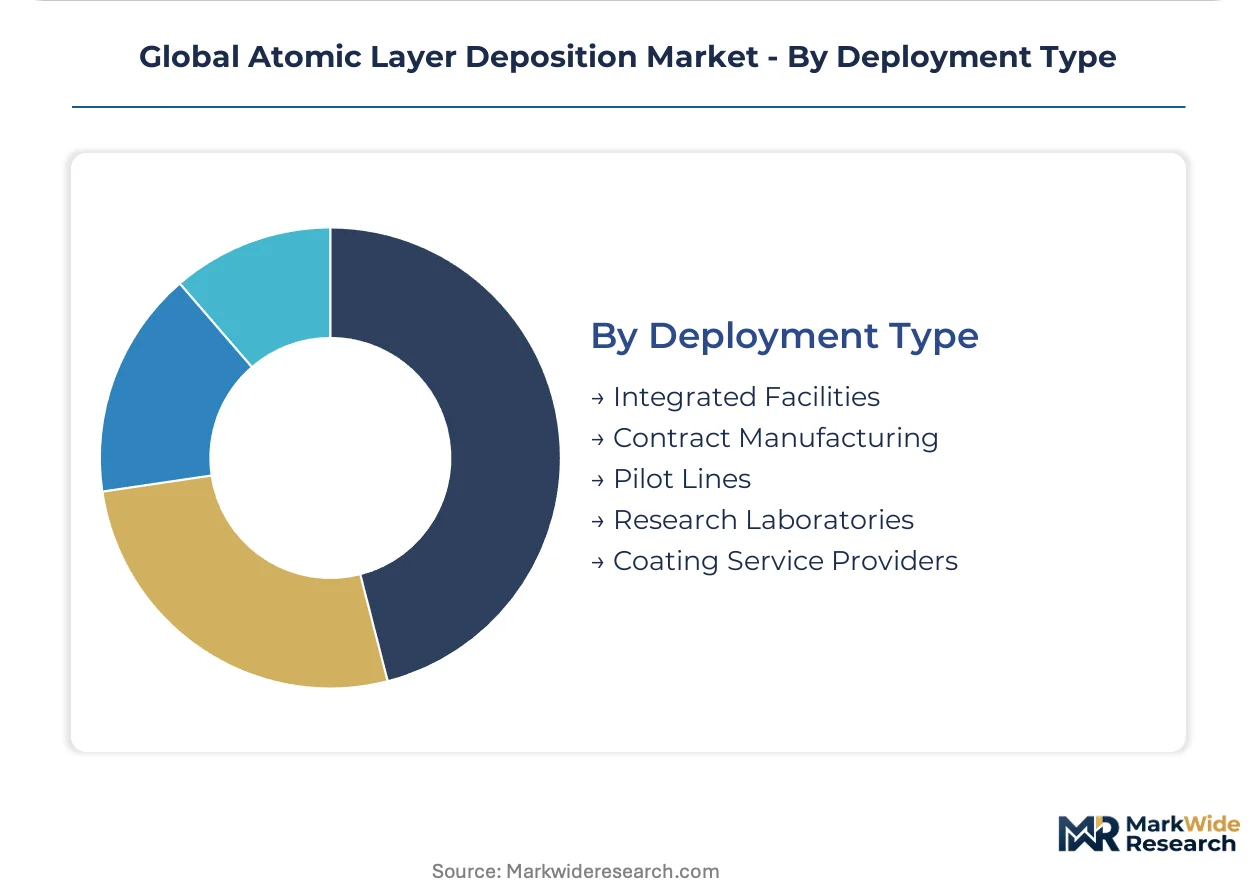
| Segmentation | Technology: CVD, PECVD, ALD, MLD, Plasma-Enhanced ALD, Thermal ALD Application: Semiconductor Fabrication, Memory Devices, Display Panels, Photovoltaic Cells, Microelectromechanical Systems, Sensor Devices End User Industry: Microelectronics Manufacturers, Solar Cell Producers, Display Panel Makers, Sensor Developers, Data Storage Specialists, MEMS Fabricators Deployment Type: Integrated Facilities, Contract Manufacturing, Pilot Lines, Research Laboratories, Coating Service Providers |
| Companies Covered | Lam Research Corporation, ULVAC, Inc., ASM International N.V., Beneq Oy, Oxford Instruments plc, Applied Materials, Inc., Veeco Instruments Inc., Picosun Oy, Tokyo Electron Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atomic Layer Deposition Market Strategic Shifts & Innovations
Deposition technology roadmaps are converging on lower-temperature processing windows as device thermal budgets tighten and novel materials enter production flows.
Thermal ALD is migrating from batch furnace architectures toward single-wafer cluster tools as logic foundries prioritize wafer-level uniformity over throughput. Leading-edge producers in Taiwan and South Korea are retrofitting existing platforms with advanced temperature control modules. This migration is compressing the addressable market for traditional batch systems while expanding service revenue attached to cluster tool upgrades.
Japan's METI has coordinated national consortia to align JIS standards with emerging deposition chemistries for beyond-silicon devices. The standardization push is accelerating equipment certification timelines for domestic tool vendors. Memory producers in Yokkaichi and Kitakami are prioritizing JIS-compliant systems to streamline regulatory alignment across their fabrication networks.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-size foundries seeking to conserve balance sheet capacity. Leasing providers now bundle preventive maintenance and precursor logistics into per-wafer pricing structures. This shift is most visible among emerging fabs in the United States where project financing constraints favor operational expenditure treatment of deposition tools.
Global Atomic Layer Deposition Market Segmentation
Atomic layer deposition equipment serves heterogeneous customer requirements spanning high-volume semiconductor fabs, emerging solar manufacturers, and academic research consortia. Segmentation reveals how deposition technology specifications diverge across thermal budgets, throughput demands, and contamination sensitivity. Understanding these divides enables vendors to align product roadmaps with distinct procurement criteria and qualification timelines.
Technology:
Mature thermal processes anchor the installed base while plasma-enhanced variants emerge as the frontier for temperature-constrained applications.
- Thermal ALD:Sequential surface reactions driven by thermal energy input deposit films at 150-350°C with self-limiting monolayer precision. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy thermal systems for high-k gate dielectrics and 3D NAND wordline stacks where established precursor chemistries deliver proven reliability.
- Plasma-Enhanced ALD:Radical species generated by RF or microwave excitation enable sub-100°C processing windows critical for flexible substrates and damage-sensitive polymers. South Korean display panel producers are qualifying plasma systems for OLED encapsulation layers where thermal budget constraints exclude conventional alternatives.
- CVD:Conventional chemical vapor deposition operates via simultaneous precursor introduction without self-limiting surface reactions, sacrificing conformality for throughput in non-critical interconnect layers.
- PECVD:Plasma-activated CVD variants deposit silicon nitride passivation at moderate temperatures for backend-of-line applications where conformality requirements are relaxed.
- MLD:Molecular layer deposition extends atomic precision to organic-inorganic hybrid films for sensing membranes and biocompatible coatings.
- ALD:Standard atomic layer deposition encompasses both thermal and plasma modalities without process-specific differentiation.
Thermal ALD retains volume leadership; Plasma-Enhanced ALD holds the steepest expansion curve.
Application:
Application segmentation tracks how deposition precision requirements scale with device architecture complexity and feature density.
- Semiconductor Fabrication:Gate-all-around transistors at sub-3nm nodes demand atomic-scale thickness uniformity across 300mm wafers. Taiwan and South Korea foundries specify sub-angstrom variation for channel dielectrics where interface trap density directly impacts transistor mobility.
- Memory Devices:3D NAND architectures exceeding 200 layers multiply ALD cycle counts for conformal charge trap layers and vertical channel formation. Yokkaichi and Kitakami fabrication complexes in Japan drive sustained equipment demand for string stacking processes.
- Display Panels:Flexible OLED manufacturing requires low-temperature barrier films against moisture and oxygen ingress. Chinese display panel producers are expanding ALD capacity for foldable device substrates.
- Photovoltaic Cells:Perovskite tandem architectures employ ALD-grown electron transport layers with precise band alignment. European solar research institutes validate processes for eventual manufacturing scale-up.
- Microelectromechanical Systems:MEMS fabrication applies conformal coatings to high-aspect-ratio release structures and hermetic sealing surfaces.
- Sensor Devices:Gas and biosensors utilize ALD for functionalized surface layers with controlled porosity and selectivity.
Semiconductor Fabrication commands revenue concentration; Memory Devices generate the densest equipment utilization intensity per wafer.
End User Industry:
End user segmentation distinguishes between captive fabrication operations and merchant equipment purchasers with divergent service requirements.
- Microelectronics Manufacturers:Integrated device manufacturers and foundries operate captive deposition capacity with dedicated process engineering teams. Intel, TSMC, and Samsung maintain internal ALD expertise for proprietary recipe development.
- Solar Cell Producers:Photovoltaic manufacturers prioritize throughput and precursor cost efficiency over ultimate precision. European perovskite startups represent emerging demand with distinct equipment specifications.
- Display Panel Makers:Korean and Chinese OLED producers require large-area uniformity across Gen 8.5+ substrates.
- Sensor Developers:Automotive and industrial sensor specialists apply ALD for functional coatings with environmental stability requirements.
- Data Storage Specialists:Hard disk drive manufacturers deposit carbon overcoats with picometer thickness control for magnetic recording media.
- MEMS Fabricators:Specialized foundries serving automotive and consumer electronics combine ALD with release etch processes.
Microelectronics Manufacturers dominate procurement volume; Solar Cell Producers are expanding most quickly as tandem cell architectures mature.
Deployment Type:
Deployment segmentation reveals how capital constraints and technical risk tolerance shape equipment acquisition strategies.
- Integrated Facilities:Leading-edge fabs deploy cluster tools within unified manufacturing flows where ALD modules interface with etch and metrology systems. United States-based foundry projects under the CHIPS Act favor integrated configurations for sovereign capacity.
- Research Laboratories:University and national lab facilities prioritize process flexibility and multi-precursor compatibility over throughput. Germany's Fraunhofer institutes and Japan's AIST operate research-scale systems for pre-competitive materials development.
- Contract Manufacturing:Merchant foundries and assembly-test facilities offer ALD as a service to fabless design houses.
- Pilot Lines:Process development centers bridge research and manufacturing with semi-automated systems for recipe transfer.
- Coating Service Providers:Specialized vendors apply ALD coatings to customer-supplied substrates for medical devices and optical components.
Integrated Facilities retain volume leadership; Research Laboratories hold the steepest expansion curve as national semiconductor initiatives expand basic research capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atomic layer deposition equipment flows disproportionately toward fabrication clusters with sovereign capacity mandates. Import intensity runs highest in emerging fab zones where domestic tool production remains underdeveloped. Export competitiveness concentrates among Japanese, Dutch, and American equipment houses with established precursor supply chains.
United States
CHIPS Act subsidies are accelerating foundry buildouts in Arizona and Texas that require precision deposition tools for sub-3nm node qualification. The EPA governs precursor chemical handling under TSCA while the FDA oversees ALD-coated medical device approvals. Intel's expansion in Chandler and TSMC's Phoenix facility are driving concentrated procurement cycles for cluster tool configurations.
Taiwan
Leading-edge foundry operations at Taiwan Semiconductor Manufacturing consume the densest ALD equipment utilization per wafer globally. The National Science and Technology Council coordinates domestic equipment qualification protocols alongside industrial technology research programs. Hsinchu Science Park anchors the world's most advanced deposition tool deployment density for gate-all-around transistor manufacturing.
South Korea
Samsung Foundry and SK Hynix are expanding 3D NAND stacking beyond 200 layers, multiplying ALD cycle counts per wafer. The Ministry of Trade, Industry and Energy administers K-Chips Act incentives for domestic equipment supply chain development. Pyeongtaek and Yongin fabrication complexes are qualifying next-generation plasma-enhanced systems for low-temperature OLED encapsulation.
Japan
Memory producers in Yokkaichi and Kitakami maintain sustained demand for conformal barrier deposition in string stacking processes. METI coordinates national R&D consortia that align JIS standards with emerging deposition chemistries. Tokyo Electron's domestic installed base creates captive service revenue streams across the archipelago's fabrication network.
Germany
Fraunhofer institutes and Max Planck facilities operate research-scale systems for pre-competitive materials development in oxide electronics. The EU F-Gas Regulation mandates precursor recovery systems that German equipment vendors are bundling as standard features. Dresden's Silicon Saxony cluster is attracting deposition tool qualification programs for automotive sensor applications.
Global Atomic Layer Deposition Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in precursor delivery and temperature control subsystems. The vendor structure concentrates around three to four integrated equipment houses with captive supply of adjacent process tools, while niche players occupy research-scale and pilot-line segments. Strategic archetypes include thermal ALD purists, plasma-enhanced innovators, and atmospheric-pressure spatial ALD entrants. Competitive moves center on equipment-as-a-service contracting and geographic service infrastructure pre-positioning ahead of fab construction timelines.
Among Dutch-headquartered specialists, ASM International N.V. and Beneq Oy occupy distinct positions within the technology spectrum. ASM International N.V. exemplifies the thermal ALD incumbent archetype with long-term service contract anchoring. Beneq Oy represents the research-to-production bridge segment with convertible platform architectures. Oxford Instruments plc, a UK-based plc, sits within the pilot-line and academic research tier where process flexibility commands premium positioning. Tokyo Electron Limited, the Japanese integrated equipment house, anchors the broadest semiconductor equipment portfolio that bundles deposition with etch and metrology modules.
| Leading Market Players |
|---|
| Lam Research Corporation |
| ULVAC, Inc. |
| ASM International N.V. |
| Beneq Oy |
| Oxford Instruments plc |
| Applied Materials, Inc. |
| Veeco Instruments Inc. |
| Picosun Oy |
| Tokyo Electron Limited |
| Others |
Cost & Logistics Intelligence
Shanghai-to-Rotterdam container rates shape equipment landed costs for European foundry projects, compressing margins on thermal ALD systems while amplifying price premiums for plasma-enhanced variants with faster qualification timelines. Precursor logistics from German and Japanese specialty chemical suppliers concentrate supply-side leverage, forcing equipment vendors to absorb freight volatility or pass through to capital-constrained buyers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where cluster tool procurement bundles preventive maintenance and precursor logistics into per-wafer pricing. Price differentiation rests on certification level—JIS-compliant systems command premiums against generic alternatives—and volume scale, with multi-fab agreements securing steeper discounts. Cost compression in thermal ALD batch systems is intensifying because single-wafer cluster migration erodes addressable demand for legacy furnace architectures. Merchant foundries exhibit highest price sensitivity due to project financing constraints, while integrated IDMs prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Leading-edge foundry capacity concentrates at Taiwan Semiconductor Manufacturing, Samsung Foundry in South Korea, and Intel's Arizona operations, with each site demanding localized service infrastructure. Organometallic precursor synthesis draws from German and Japanese specialty chemical houses, while quartz chamber components and RF power modules source from domestic Japanese and American suppliers. Single-source vulnerability in EUV-resist-compatible precursor formulations threatens deposition tool validation timelines at sub-3nm nodes. Distribution runs through direct vendor-fab relationships with captive field service teams, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atomic layer deposition market sits in early-cycle expansion as gate-all-around transistor adoption at sub-3nm nodes multiplies ALD cycle counts per wafer beyond historical benchmarks. EU Chips Act capital deployment and comparable sovereign semiconductor initiatives across multiple geographies are accelerating equipment procurement cycles ahead of traditional replacement schedules.
For Market Incumbents: Build switching-cost moats through long-term service contracts that bundle precursor logistics, preventive maintenance, and recipe optimization into multi-year agreements. ASM International N.V. anchors thermal ALD leadership via this model. Deepen backward integration into temperature control subsystems to defend margin position against modular component specialists. Threats from plasma-enhanced ALD innovators and atmospheric-pressure spatial ALD entrants demand accelerated R&D in low-temperature processing windows. For New Entrants and Emerging Players: Pursue India's PLI scheme for fabs and ATMP facilities as the most penetrable geography, where local service infrastructure gaps create white-space for deposition equipment vendors ahead of projected demand. Target research-scale and pilot-line segments where process flexibility commands premium positioning against volume-optimized incumbents. Oxford Instruments plc occupies this tier with convertible platform architectures. A go-to-market angle emphasizing equipment-as-a-service contracting aligns with mid-size foundry balance sheet constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming deposition equipment divisions or captive semiconductor tool operations lacking scale. Long-term viability hinges on vendor ability to secure JIS, CE, and FDA certifications across multiple regulatory jurisdictions. Monitor qualification timeline compression at leading-edge foundries as the inflection signal—vendors demonstrating 12-18 month fab integration cycles versus 24-month industry norms will capture disproportionate share expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Mid-size foundries in the United States favor operational expenditure treatment of deposition tools. |
| Precursor Recovery System Integration | EU F-Gas Regulation compliance bundles abatement technology as standard equipment feature. |
| Plasma-Enhanced ALD Platform Launch | South Korean display panel producers qualify low-temperature systems for OLED encapsulation layers. |
| Geographic Service Infrastructure Pre-Positioning | CHIPS Act fab buildouts in Arizona and Texas require localized field engineering capacity. |
| Joint Venture with Specialty Chemical Suppliers | German and Japanese precursor houses seek captive offtake agreements to secure synthesis capacity. |
Research Approach
Initial hypotheses were tested against primary input from fab process engineers, equipment procurement managers, precursor supply specialists, and national lab research directors, then refined through secondary validation against SEC 10-K filings, METI technology roadmaps, EU Chips Act implementation reports, and JIS standards documentation. Bottom-up triangulation across equipment shipment records and top-down reconciliation with foundry capex disclosures anchored volume estimates. Primary interviews explored thermal budget constraints, qualification protocol durations, and service contract structuring across Taiwan, South Korea, the United States, Japan, and Germany.
Demand-supply balance modeling across the analysis window segmented by technology type, application node, end-user industry, and deployment configuration. Plasma-enhanced versus thermal ALD adoption curves, 3D NAND layer stacking progression, and perovskite tandem cell commercialization timelines served as industry-specific forecast inputs. CAGRs were derived from installed base expansion rates, replacement cycle compression, and emerging application penetration assumptions without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, export licensing delays for organometallic precursors, or EUV scanner availability at leading-edge foundries would shift the trajectory. Quarterly review of fab construction permitting timelines, precursor substance regulatory amendments, and national semiconductor initiative funding disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market