
 Semiconductor Etching Cleaner Market | 2026-2036
Semiconductor Etching Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Etching Cleaner Market Insights
Taiwan is fragmenting as new 3nm and 2nm fabs multiply solvent and acidic cleaner procurement channels. Entegris leverages its fluid handling integration to control high-purity chemical delivery systems for etch clean steps. DuPont anchors North American supply through its specialty fluoropolymer and solvent portfolios. Mitsubishi Gas Chemical dominates ultra-high purity hydrogen peroxide supply chains serving Korean and Japanese memory fabs.
Semiconductor etching cleaners are formulated chemical solutions designed to remove photoresist residues, metallic contaminants, and etch byproducts from wafer surfaces, typically operating at purity levels below 100 parts per trillion for critical metal ions. Acidic cleaners containing hydrofluoric or sulfuric acid blends target post-etch oxide removal, while solvent cleaners dissolve organic photoresist residues through N-methyl-2-pyrrolidone or proprietary glycol ether formulations. Wafer cleaning applications command the largest value pool given their direct impact on die yield, whereas biodegradable cleaners represent the fastest-expanding product type as foundries face Scope 3 emissions accounting and zero-liquid-discharge mandates. Equipment cleaning trails in growth rate but sustains margin stability through long-term service contracts tied to tool uptime guarantees.
EPA hazardous air pollutant standards and OSHA permissible exposure limits constrain solvent cleaner formulations in the United States, while REACH registration and the EU Green Deal chemicals strategy restrict fluorinated compound use across European semiconductor supply chains. Japan's METI enforces JIS standards for chemical impurity thresholds that effectively gate non-domestic suppliers from its leading-edge memory sector. Korea's MFDS and environmental ministry jointly regulate effluent chemistry from cleaner rinse cycles, creating compliance barriers for imported formulations. Stakeholders must monitor regulatory divergence between East Asian export markets and Western chemical restriction frameworks when standardizing product platforms across geographies.
Market Dynamics
Node shrinkage below 5nm is fragmenting procurement channels as foundries diversify solvent and acidic cleaner suppliers to mitigate concentration risk in Taiwan's Hsinchu corridor. This structural dispersion is rewriting qualification protocols and regional supply strategies.
Growth Catalysts
- Advanced node proliferation:3nm and 2nm logic production ramps in Taiwan and South Korea multiply etch clean steps per wafer, expanding solvent consumption volumes.
- REACH chemical registration:European semiconductor supply chains face reformulation mandates under evolving EU Green Deal chemicals strategy, opening demand for compliant alternatives.
- Memory fab expansion:Korean and Japanese NAND and DRAM producers are scaling hydrogen peroxide-intensive cleaning protocols for 3D stacking architectures.
Market Restraints
- Ultra-high purity input concentration:Hydrogen peroxide and N-methyl-2-pyrrolidone supply chains cluster among Japanese and Korean chemical conglomerates, creating chokepoint vulnerability.
- EPA hazardous air pollutant standards:OSHA permissible exposure limits constrain solvent cleaner formulations in United States manufacturing, raising compliance costs for glycol ether blends.
- Fluorinated compound substitution:Per- and polyfluoroalkyl substance restrictions under EU F-Gas Regulation and state-level US bans threaten incumbent post-etch cleaners.
Strategic Opportunities
- Biodegradable formulation white space:Zero-liquid-discharge mandates in Taiwan and Korea create procurement preference for cleaners meeting Scope 3 emissions accounting standards.
- Equipment cleaning service contracts:Long-term uptime guarantees tied to tool maintenance generate recurring revenue pools distinct from wafer cleaning chemical sales.
- Fluid handling integration:Captive control over high-purity chemical delivery systems adjacent to etch clean steps enables margin capture beyond bulk chemical supply.
Industry Challenges
- Parts-per-trillion contamination control:Critical metal ion thresholds below 100 ppt demand specialized analytical chemistry talent scarce outside East Asian manufacturing clusters.
- Multi-jurisdiction qualification timelines:Divergent JIS, REACH, and EPA testing protocols force redundant certification cycles for standardized product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Etching Cleaner Market |
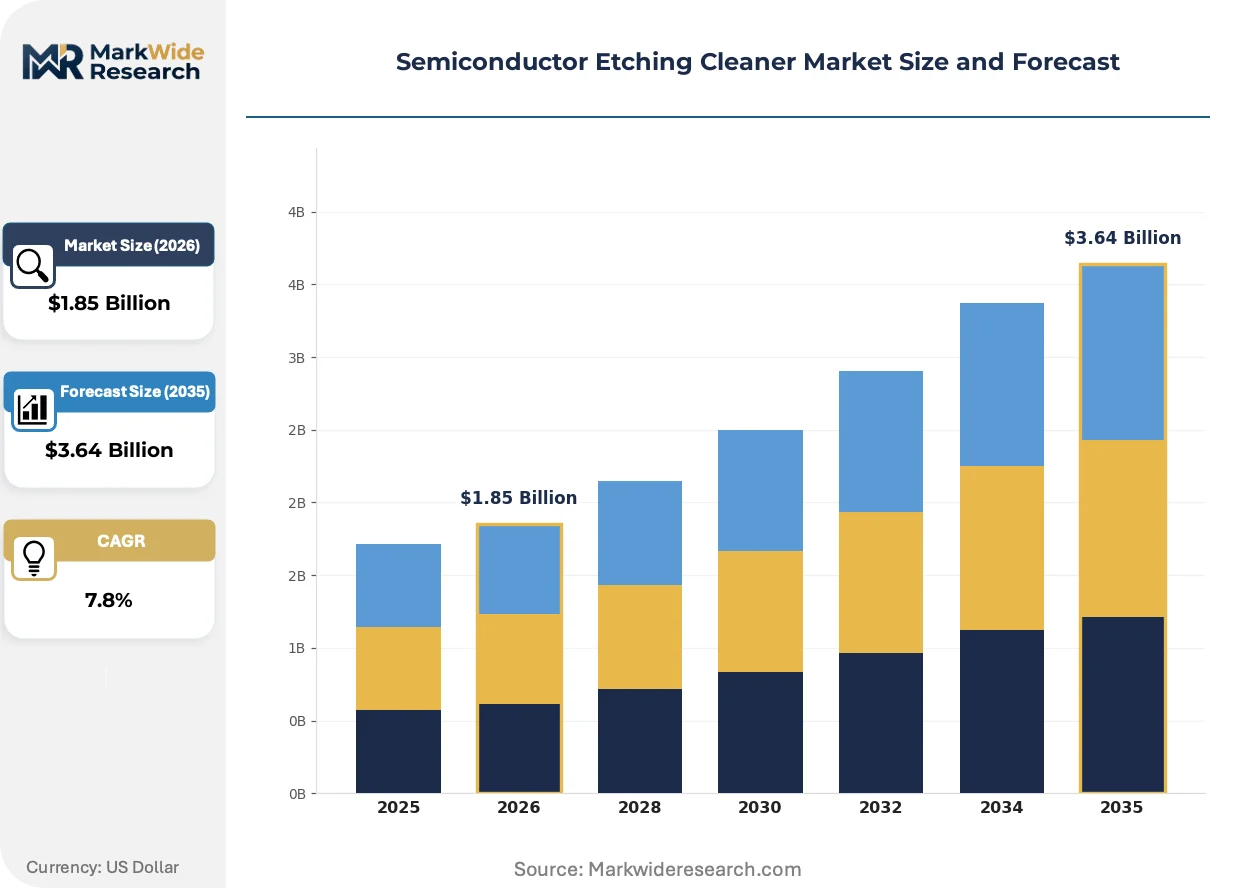
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidic Cleaner, Alkaline Cleaner, Solvent Cleaner, Biodegradable Cleaner Application: Wafer Cleaning, PCB Cleaning, Photomask Cleaning, Equipment Cleaning End User: Semiconductor Manufacturers, Foundries, Research Institutions, Electronics Companies Distribution Channel: Direct Sales, Distributors, Online Channels, Retailers |
| Companies Covered | Entegris, DuPont, Merck (Versum Materials), Mitsubishi Gas Chemical, Fujifilm, BASF, Tokyo Ohka Kogyo, Avantor, Technic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Etching Cleaner Market Trends and Innovations
Formulation science and delivery system architecture are converging to address purity thresholds, regulatory fragmentation, and sustainability mandates simultaneously. Three developments are restructuring competitive positioning.
Supercritical CO2 cleaning is collapsing the distinction between solvent and aqueous process steps by eliminating liquid waste streams entirely. Memory fabs in Korea and Japan are piloting systems for photoresist stripping at 20nm nodes and below. This technology is collapsing capital allocation toward centralized waste treatment infrastructure by removing rinse water requirements.
Japan's METI is tightening JIS impurity standards for hydrogen peroxide used in leading-edge memory production, effectively gating non-domestic suppliers from qualification. Korean foundries must dual-source from METI-certified Japanese producers and domestic alternatives under MFDS joint regulation. European suppliers face exclusion absent localized purification investments.
Consolidated procurement consortia among Taiwan foundries are displacing individual fab purchasing autonomy. TSMC and UMC affiliates now negotiate solvent cleaner contracts through centralized chemical management platforms. This concentration is most visible in the Hsinchu Science Park corridor, where third-party logistics providers control inventory positioning.
Semiconductor Etching Cleaner Market Segmentation
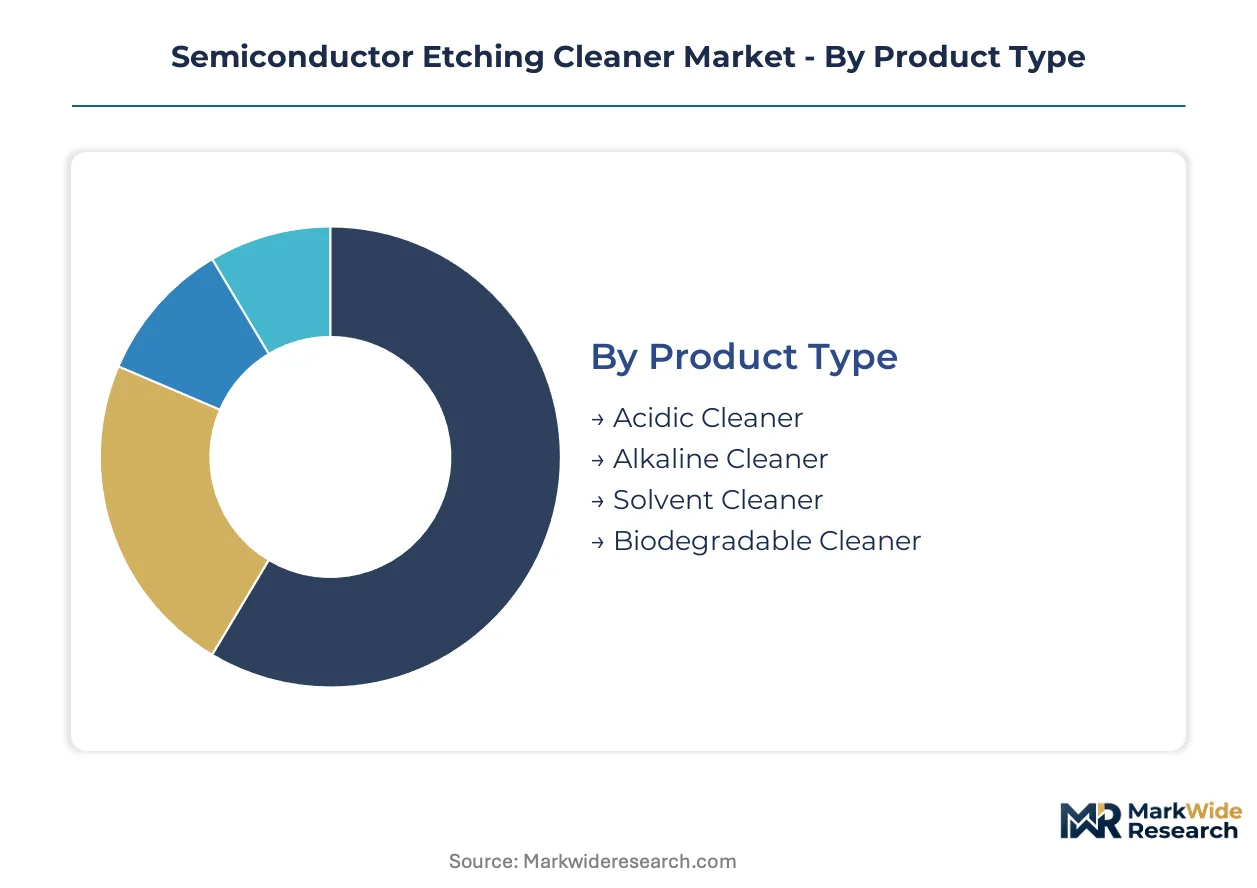
Etching cleaner procurement varies sharply across process steps, purity requirements, and customer scale. Manufacturers configure formulation portfolios around these segment boundaries to capture margin pools in advanced node production.
Product Type:
Formulation chemistry spans corrosive mineral acid blends through engineered biodegradable alternatives, each serving distinct contamination removal protocols.
- Acidic Cleaner:Hydrofluoric and sulfuric acid mixtures strip post-etch oxide residues from wafer surfaces. Foundries in Taiwan and South Korea consume the largest volumes as 3nm and 2nm logic ramps multiply etch clean steps per wafer.
- Solvent Cleaner:N-methyl-2-pyrrolidone and proprietary glycol ether formulations dissolve organic photoresist residues. EPA hazardous air pollutant standards and OSHA permissible exposure limits constrain glycol ether blends in United States manufacturing, raising compliance costs for formulators.
- Alkaline Cleaner:Ammonia-hydrogen peroxide mixtures target metallic contamination removal with lower substrate attack risk.
- Biodegradable Cleaner:Zero-liquid-discharge mandates in Taiwan and Korea create procurement preference for cleaners meeting Scope 3 emissions accounting standards.
The dominant share belongs to Solvent Cleaner, while Biodegradable Cleaner is closing the gap fastest.
Application:
Process integration depth determines value capture, with wafer-level cleaning commanding premium pricing against tool maintenance applications.
- Wafer Cleaning:Direct die yield impact drives purity specifications below 100 parts per trillion for critical metal ions. Memory fabs in Korea and Japan scale hydrogen peroxide-intensive protocols for 3D NAND stacking architectures.
- Equipment Cleaning:Long-term service contracts tied to tool uptime guarantees generate recurring revenue pools distinct from consumable chemical sales. Fluid handling integration opportunities concentrate margin capture here.
- PCB Cleaning:Lower purity thresholds accommodate broader supplier qualification.
- Photomask Cleaning:Specialized formulations address reticle surface sensitivity.
Wafer Cleaning retains the largest value pool, though Equipment Cleaning is gaining share fastest through captive service contract structures.
End User:
Customer scale and qualification rigor create tiered access barriers for formulation suppliers.
- Semiconductor Manufacturers:Integrated device makers run captive chemical qualification programs with 18-24 month validation cycles.
- Foundries:TSMC and UMC affiliates negotiate through centralized chemical management platforms in the Hsinchu Science Park corridor, displacing individual fab purchasing autonomy.
- Electronics Companies:Assembly and packaging operations drive secondary demand for equipment cleaning formulations.
- Research Institutions:Pilot line volumes support formulation testing and early-stage qualification.
Foundries command the dominant procurement volume, while Electronics Companies are expanding fastest through outsourced packaging growth.
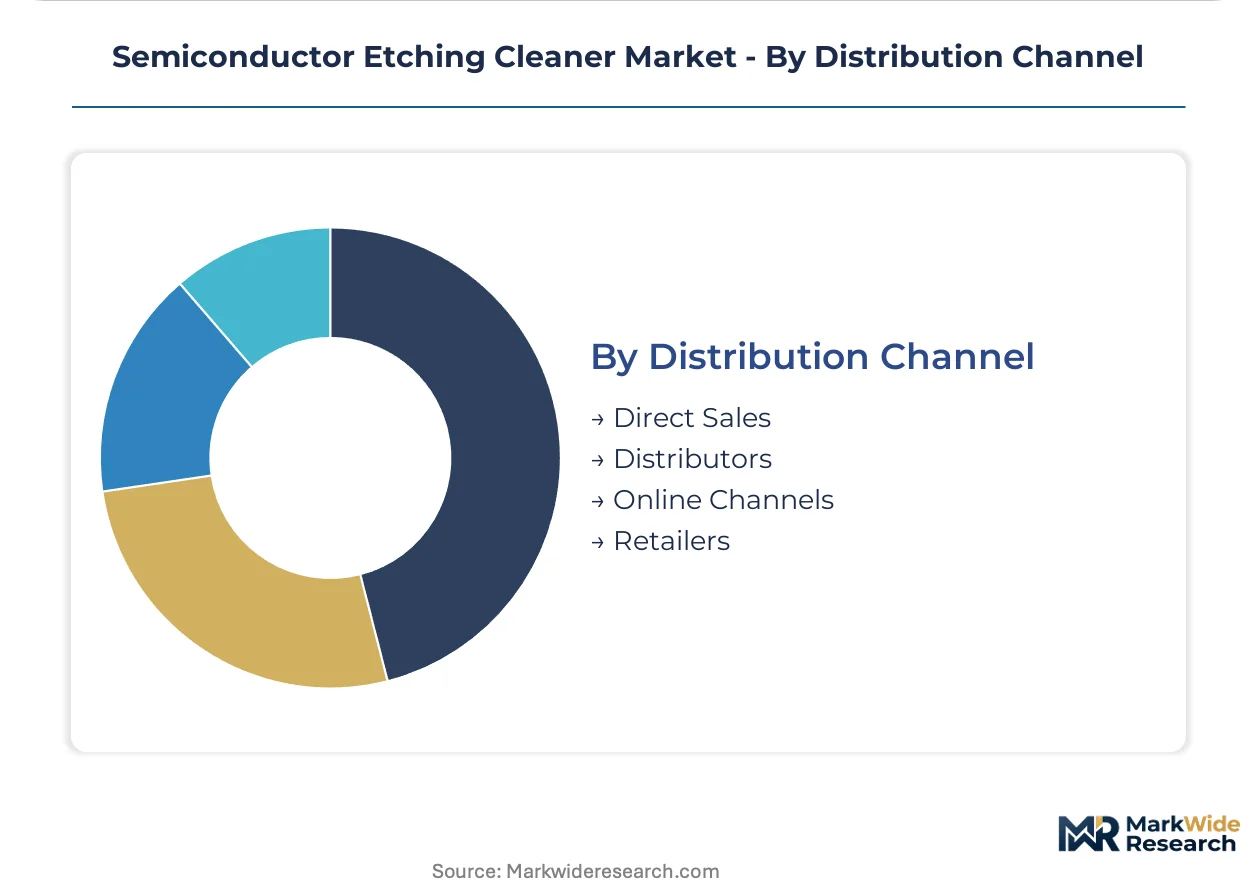
Distribution Channel:
Channel structure reflects inventory positioning requirements and technical service intensity.
- Direct Sales:High-volume foundry accounts require dedicated technical service teams and just-in-time delivery coordination.
- Distributors:Regional chemical logistics providers control inventory positioning for mid-tier semiconductor manufacturers.
- Online Channels:Standard-grade formulations for research and pilot line procurement.
- Retailers:Minimal presence given purity certification requirements.
Direct Sales holds the dominant share, though Distributors are expanding fastest through third-party logistics consolidation in East Asian manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity chemical supply chains cluster in East Asian manufacturing corridors where leading-edge fab density creates concentrated demand. Taiwan and South Korea dominate advanced logic consumption, while Japan controls critical hydrogen peroxide feedstocks. Regulatory divergence between EPA standards in the United States, REACH in Europe, and METI-certified JIS thresholds in Japan fragments qualification protocols across geographies.
United States
Domestic demand concentrates in Arizona and Texas where Intel and TSMC have committed advanced node capacity. EPA hazardous air pollutant standards and OSHA permissible exposure limits constrain glycol ether solvent formulations, raising compliance costs for formulators serving legacy fabs in Oregon and New Mexico. The Southwest manufacturing corridor is absorbing qualification investments as new 3nm-equivalent capacity ramps.
Taiwan
TSMC and UMC affiliates in the Hsinchu Science Park corridor consume the world's highest per-fab volumes of post-etch cleaners as 2nm logic ramps multiply cleaning steps per wafer. Zero-liquid-discharge mandates from the environmental ministry are reshaping procurement toward biodegradable alternatives. Third-party logistics providers now control inventory positioning across the Hsinchu-Taichung-Tainan fab belt.
South Korea
Samsung and SK Hynix memory fabs in the Seoul Capital Area and Busan-Ulsan corridor scale hydrogen peroxide-intensive protocols for 3D NAND stacking architectures. MFDS joint regulation with the environmental ministry governs effluent chemistry from cleaner rinse cycles, creating compliance barriers for non-domestic formulations. Korean suppliers are expanding purification capacity to reduce dependence on Japanese hydrogen peroxide imports.
Japan
METI-enforced JIS impurity standards for hydrogen peroxide effectively gate non-domestic suppliers from qualification at leading-edge memory producers in the Kanto and Kyushu regions. Domestic chemical conglomerates dominate ultra-high purity supply chains serving Korean and Taiwanese foundries through export channels. The Nagoya-Tokyo corridor maintains specialized analytical chemistry talent scarce outside East Asian manufacturing clusters.
Germany
BASF and specialty chemical producers in the Rhine-Ruhr and Bavarian industrial regions supply European semiconductor fabricators with REACH-compliant formulations. The EU Green Deal chemicals strategy and F-Gas Regulation are forcing reformulation of fluorinated post-etch cleaners, opening demand for compliant alternatives. German chemical logistics providers are consolidating distribution networks to serve the Dresden silicon cluster and expanding Leuven-Grenoble corridor.
Semiconductor Etching Cleaner Market Competitive Landscape
Integrated fluid handling specialists and diversified chemical conglomerates split the market between captive delivery system control and bulk formulation supply. Three to five Japanese and Korean conglomerates dominate ultra-high purity hydrogen peroxide feedstocks, while North American and European players anchor specialty solvent and fluoropolymer portfolios. Strategic moves concentrate on backward integration into purification assets and geographic expansion through localized blending facilities to bypass import qualification barriers.
Within the fluid handling integration tier, Entegris exemplifies the archetype of chemical delivery system control adjacent to etch clean steps. DuPont occupies a position representing North American specialty fluoropolymer and solvent supply. Mitsubishi Gas Chemical anchors the ultra-high purity hydrogen peroxide segment serving memory fab demand. These three companies represent distinct strategic positions: delivery system integration, regional formulation anchoring, and critical feedstock concentration.
| Leading Market Players |
|---|
| Entegris |
| DuPont |
| Merck (Versum Materials) |
| Mitsubishi Gas Chemical |
| Fujifilm |
| BASF |
| Tokyo Ohka Kogyo |
| Avantor |
| Technic Inc. |
| Others |
Pricing and Supply Chain Analysis
Japanese hydrogen peroxide purification assets command premium pricing power over downstream formulators in Taiwan and South Korea. Margin pools concentrate at the feedstock tier where METI-certified producers gate access to leading-edge memory fabs.
Pricing Analysis
REACH registration dictates the pricing tier structure across European semiconductor supply chains. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified formulations from REACH-compliant alternatives and commodity-grade cleaners. Price differentiation stems from certification grade and volume scale, with foundry consortia extracting discounts through centralized procurement. Cost compression in solvent cleaners is intensifying because EPA hazardous air pollutant standards raise compliance burdens for glycol ether blends. Equipment cleaning service contracts show least price sensitivity due to uptime guarantee bundling.
Supply Chain Analysis
Tariff exposure between Japan and South Korea dominates supply chain risk planning for hydrogen peroxide-intensive memory production. Feedstock concentration centers on Japan, South Korea, and Taiwan for ultra-high purity hydrogen peroxide, N-methyl-2-pyrrolidone, and fluorinated solvents. Raw material dependencies include electronic-grade hydrogen peroxide, specialty glycol ethers, and hydrofluoric acid precursors. Single-source vulnerability persists at the purification asset tier where Japanese conglomerates control analytical chemistry capacity. Distribution runs through third-party logistics providers positioned across the Hsinchu-Taichung-Tainan fab belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor etching cleaner procurement is shifting toward platform-economics consolidation as TSMC and UMC affiliates centralize chemical management through interoperable logistics systems.
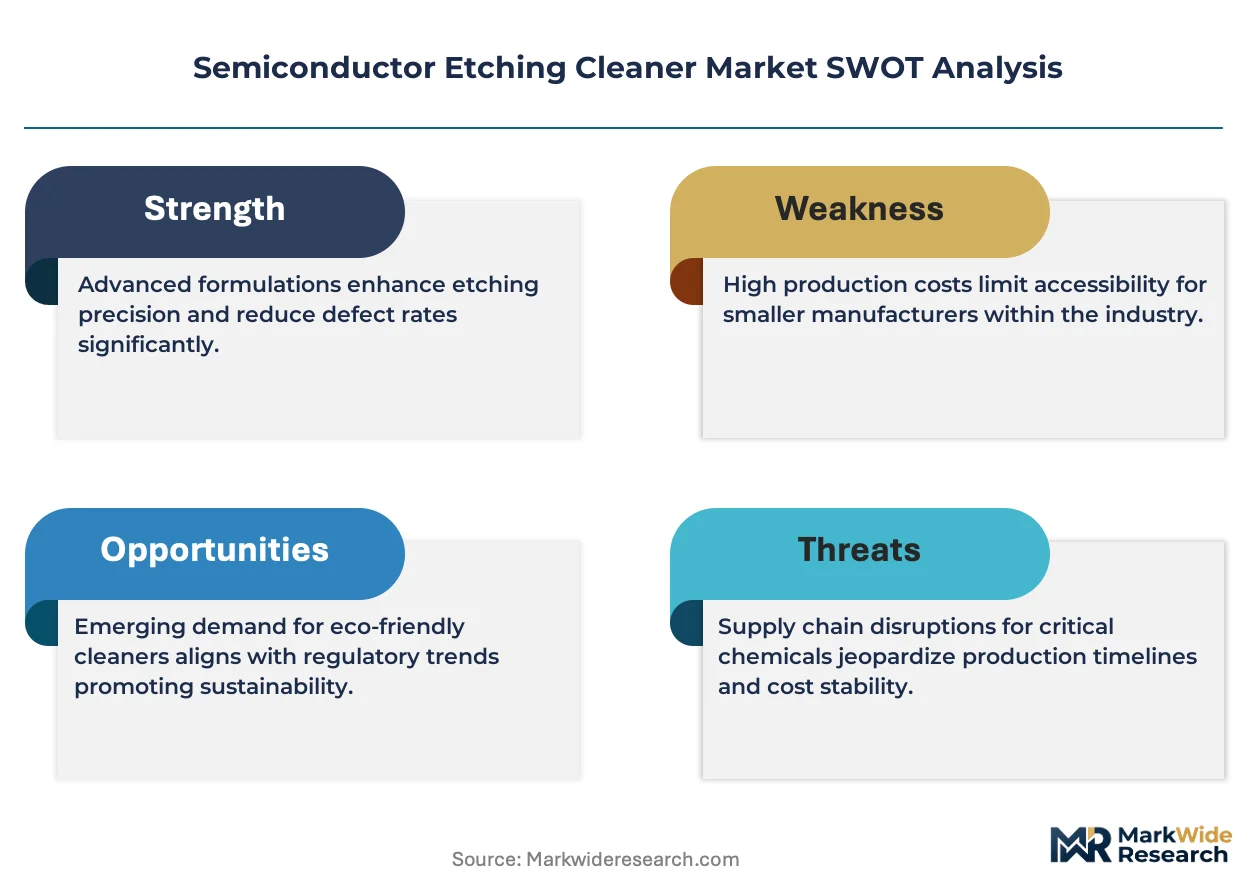
For Market Incumbents: Insulate qualification pipelines by securing METI certification for hydrogen peroxide supply and expanding captive purification capacity in Taiwan. Backward integration into fluid handling systems adjacent to etch clean steps protects margin pools from commodity formulation pressure. Threat substitution from supercritical CO2 cleaning demands R&D investment in hybrid process compatibility. For New Entrants and Emerging Players: Establish a beachhead in biodegradable cleaner formulations serving Korean zero-liquid-discharge mandates. The most penetrable segment is equipment cleaning service contracts where long-term uptime guarantees displace transactional chemical sales. Go-to-market leverage rests on partnering with third-party logistics providers controlling inventory positioning in East Asian manufacturing clusters. For Investors and Strategic Acquirers: Capital is best deployed toward purification asset operators with METI-certified capacity and regional blending facilities that bypass import qualification barriers. Long-term viability over the coming decade hinges on regulatory agility across divergent EPA, REACH, and JIS frameworks. Watch for supercritical CO2 pilot adoption rates at Korean memory fabs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purification Assets | METI certification gates access to Japanese and Korean memory fab supply chains. |
| Biodegradable Formulation Development | Taiwan zero-liquid-discharge mandates create procurement preference for Scope 3-compliant alternatives. |
| Fluid Handling System Integration | Entegris demonstrates margin capture through captive control of high-purity chemical delivery infrastructure. |
| Regional Blending Facility Expansion | Localized production bypasses REACH and JIS import qualification barriers for European and Japanese markets. |
| Equipment Cleaning Service Contract Structuring | Long-term uptime guarantees generate recurring revenue pools distinct from consumable chemical sales. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across trade and regulatory databases. Plant managers at Taiwanese and Korean foundries, procurement leads at memory fabs, distribution channel partners in the Hsinchu corridor, and technical R&D directors at formulation suppliers provided operational perspectives. Secondary sources included customs and trade data, SEC filings from disclosed chemical suppliers, METI regulatory bulletins, and EPA hazardous air pollutant standard updates. Bottom-up volume modeling and top-down value triangulation cross-validated segment estimates.
Forecast inputs span node migration timelines, regulatory compliance cost trajectories, and foundry capacity expansion schedules across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application process step, end-user scale category, and regional regulatory cluster. CAGRs were derived from slope analysis of node-driven consumption intensity curves and purity requirement escalation patterns. Industry-specific forecast inputs incorporate etch clean steps per wafer at 3nm and 2nm logic nodes and hydrogen peroxide intensity coefficients for 3D NAND stacking architectures.
Stress conditions across tariff regime shifts, purification asset outages, and regulatory acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about node ramp schedules and qualification timeline stability. Semiconductor capital expenditure cyclicality and geopolitical intervention in technology trade represent primary revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Holmium Sputtering Target Market