
 Electrical Isolator Market | 2026-2036
Electrical Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Isolator Market Analytics
Aftermarket service revenue is narrowing as a margin pool as manufacturers shift toward integrated lifecycle contracts. Texas Instruments leverages its analog semiconductor expertise to embed isolation functions within mixed-signal ICs. Infineon Technologies anchors its position through silicon carbide and IGBT co-packaging with integrated galvanic isolation. Murata Manufacturing specializes in compact ceramic-based isolators for space-constrained industrial drives.
An electrical isolator is a passive or active device that provides galvanic separation between two circuits while permitting signal or power transfer, typically achieving isolation ratings from 1 kV to 5 kV RMS or higher depending on application standards. It serves to protect personnel and equipment from voltage transients, ground loops, and fault currents in high-voltage industrial and power systems. Gas insulated isolators still command the largest installed base in utility transmission, though vacuum insulated designs are gaining share in medium-voltage distribution where maintenance intervals matter. The renewable energy end user segment shows the steepest trajectory as offshore wind and utility-scale solar require isolation components rated for harsh environmental cycling.
The EU F-Gas Regulation and REACH restrictions on sulfur hexafluoride are reshaping product roadmaps for European suppliers, while China's GB standards and NMPA-equivalent grid codes enforce domestic testing protocols for UHV substation equipment. IEEE and IEC 62271 series standards govern dielectric withstand and mechanical endurance, creating certification barriers that favor incumbents with established type-test libraries. Stakeholders must monitor regulatory timetables for SF6 phase-downs and position their R&D portfolios toward dry-air or vacuum interruption technologies before compliance deadlines harden.
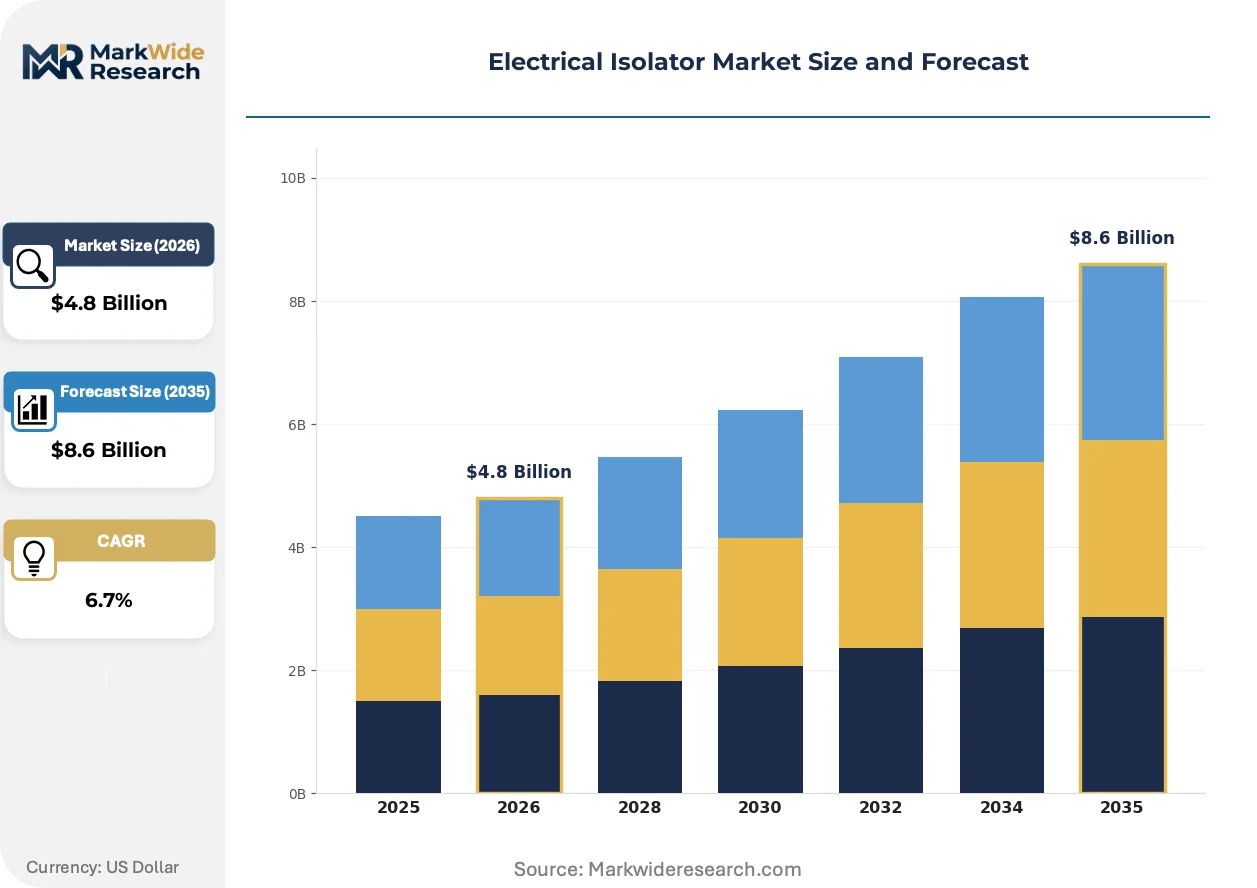
Market Dynamics
SF6 phase-down mandates under the EU F-Gas Regulation are forcing a wholesale technology transition across medium and high-voltage isolation equipment, compressing development timelines and redistributing competitive advantage toward vacuum and air-insulated architectures.
Growth Catalysts
- Renewable energy buildout:Offshore wind farms in the North Sea and utility-scale solar installations across Spain require isolators rated for salt spray, thermal cycling, and grid synchronization stress.
- REACH restrictions:The European Chemicals Agency's tightening controls on sulfur hexafluoride are accelerating R&D budgets toward dry-air interruption technologies.
- Ultra-high-voltage corridors:China's State Grid is commissioning 800 kV and 1100 kV transmission lines requiring specialized isolator assemblies with extended mechanical endurance.
Market Restraints
- Raw material volatility:Ceramic insulator bodies depend on high-purity alumina supplies concentrated in Guizhou province, exposing manufacturers to export quota fluctuations.
- Technical performance gaps:Vacuum interrupters below 72.5 kV struggle to match SF6 dielectric withstand in compact GIS footprints, limiting substitution in space-constrained urban substations.
- Certification timeline compression:IEC 62271-102 type testing for new designs requires 12-18 month laboratory cycles, delaying revenue recognition for platform refreshes.
Strategic Opportunities
- Digital substation integration:IEC 61850 process bus architectures enable embedded isolator health monitoring through fiber-optic current sensors, opening software-enabled service contracts.
- India's transmission expansion:The Central Electricity Authority's Green Energy Corridors mandate 765 kV and 400 kV substations with localized content requirements under the PLI scheme.
- Retrofit aftermarket:Aging SF6 installations in Germany and France face mandatory replacement windows, creating captive demand for drop-in vacuum alternatives with compatible mounting interfaces.
Industry Challenges
- Specialized workforce scarcity:Vacuum brazing and ceramic-to-metal sealing require technicians trained in hermetic packaging, a skill base concentrated in Japanese and German industrial clusters.
- Legacy system integration:Utilities operating 1980s-vintage air-blast switchgear demand isolators with mechanical interlock geometries that conflict with modern modular designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Isolator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Insulated, Gas Insulated, Vacuum Insulated, Polymer Insulated Application: Power Generation, Transmission, Distribution, Industrial End User: Utilities, Construction, Manufacturing, Renewable Energy Installation Type: Indoor, Outdoor, Compact, Enclosed |
| Companies Covered | Infineon Technologies, ON Semiconductor, Texas Instruments, NXP Semiconductors, Murata Manufacturing, Analog Devices, ROHM Semiconductor, Silicon Labs, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Isolator Market Evolving Landscape
Isolation technology is converging with power electronics and digital sensing, collapsing the traditional boundary between passive mechanical components and active protection systems. This integration is redrawing supplier boundaries and value capture models.
Vacuum interrupter technology is hybridizing with solid-state switching elements in medium-voltage hybrid breakers. Offshore wind developers in Denmark and the Netherlands are piloting these units for fault current limitation without mechanical wear. The architecture is compressing maintenance intervals from five years to fifteen while enabling remote condition monitoring through embedded Rogowski coils.
The EU F-Gas Regulation's 2030 phase-down targets are forcing manufacturers to abandon SF6 entirely in new 52 kV and below designs. Siemens Energy and ABB have committed to dry-air platforms, triggering a supply chain scramble for epoxy resin formulations with equivalent tracking resistance. Distribution utilities in Italy and Poland are now specifying F-gas-free as a mandatory tender criterion, accelerating competitive differentiation around environmental credentials.
Utility procurement teams are consolidating supplier relationships around lifecycle performance guarantees rather than unit capital cost. EDF and Enel have shifted to fifteen-year service contracts covering isolator replacement, inspection, and predictive analytics. This bundling is squeezing pure-play component vendors and favoring integrated solution providers with captive installation and maintenance capabilities. The shift is most pronounced in France and Spain, where regulatory asset models reward uptime over initial expenditure.
Electrical Isolator Market Segmentation
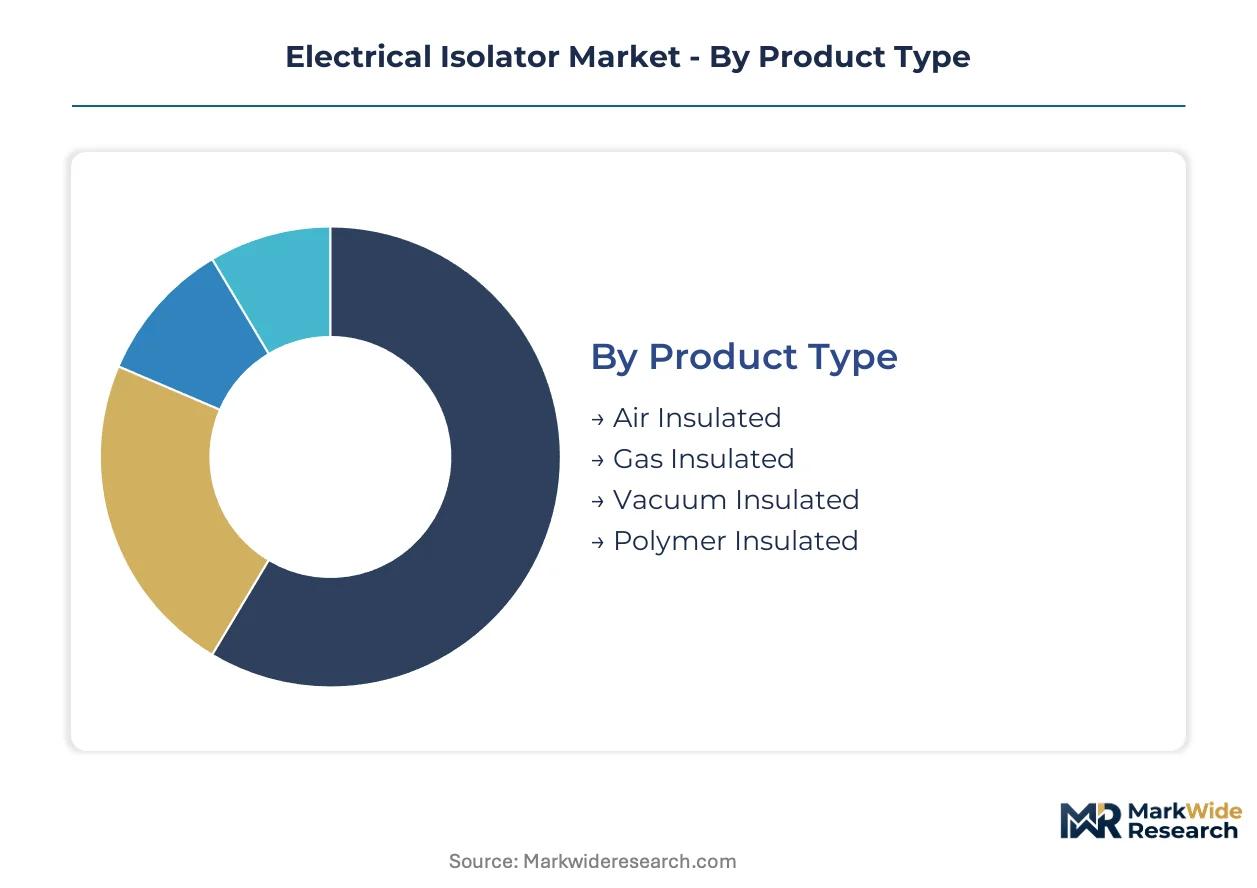
Electrical isolator procurement patterns diverge sharply across installation environments and voltage classes, with aftermarket service intensity varying from fifteen-year lifecycle contracts in transmission utilities to spot replacement in industrial maintenance budgets. Segment-specific technical standards and regional certification requirements create distinct margin pools that reward specialized manufacturing footprints.
Product Type:
After-sales service intensity peaks with gas insulated designs requiring specialized SF6 handling equipment and certified technician networks, while vacuum alternatives shift margin capture toward predictive analytics subscriptions.
- Air Insulated:These designs rely on atmospheric dielectric clearance between live conductors and grounded frames, demanding larger installation footprints but eliminating pressurized vessel maintenance. Demand concentrates in India's Green Energy Corridors and African transmission expansions where capital cost sensitivity outweighs land constraints. EPC contractors favor these units for 132 kV and below substations in rural India under CEA localization mandates.
- Gas Insulated:SF6-filled enclosures achieve compact 550 kV ratings in footprint-constrained urban substations across Germany and Japan. The EU F-Gas Regulation's phase-down timeline is compressing residual demand toward refurbishment services rather than new installations, with Enel and EDF accelerating SF6 recovery protocols ahead of compliance deadlines.
- Vacuum Insulated:Ceramic-brazed interrupter assemblies eliminate atmospheric contamination risks in offshore wind nacelles and coastal substations. Danish and Dutch developers specify these for North Sea platforms where salt spray corrosion degrades conventional insulation.
- Polymer Insulated:Silicone rubber housings replace porcelain in seismic zones and contamination-prone environments. Tokyo Electric and California utilities specify these for earthquake resilience and reduced weight in elevated structures.
Gas insulated designs hold the largest installed share; momentum sits with vacuum insulated architectures as F-gas restrictions harden.
Application:
Cost tier stratification separates transmission-grade type-tested assemblies from distribution units sourced through framework agreements, with procurement cycles stretching from eighteen months to spot-market purchasing.
- Power Generation:Generator circuit breakers and busbar isolators in combined-cycle plants require synchronized switching capabilities and seismic qualification. Saudi Arabia's gas-fired capacity expansion and Vietnam's LNG-to-power projects drive specification intensity for 24 kV and 36 kV generator outlet units.
- Transmission:Ultra-high-voltage corridors at 800 kV and 1100 kV demand specialized multi-break isolators with extended mechanical endurance. China's State Grid procurement dominates volume, with Xi'an and Shenyang manufacturing clusters supplying porcelain insulator strings and composite alternatives for 765 kV towers.
- Distribution:Ring main units and padmount switchgear integrate isolators with fuse protection for urban underground networks. Italian and Polish utilities now mandate F-gas-free designs in 52 kV and below tenders, accelerating vacuum platform adoption.
- Industrial:Motor control centers and arc furnace installations require isolators rated for frequent operation and fault current withstand. German automotive battery gigafactories and Texas petrochemical complexes specify these for process isolation and maintenance safety.
Transmission commands the premium pricing tier; distribution applications are climbing the fastest as grid modernization accelerates across emerging economies.
End User:
Customer type determines contract structure, with utilities favoring performance guarantees and construction firms purchasing on project-specific schedules with limited service attachments.
- Utilities:National grid operators and distribution companies procure through multi-year framework agreements bundling equipment, installation, and predictive maintenance. EDF's fifteen-year service contracts and Enel's digital substation pilots exemplify this shift toward outcome-based procurement.
- Construction:EPC contractors source isolators as part of turnkey substation packages, prioritizing delivery certainty and mounting compatibility over technical differentiation. Middle East infrastructure projects and Southeast Asian industrial zone expansions drive spot demand for standardized 145 kV and 245 kV assemblies.
- Manufacturing:Automotive, semiconductor, and battery production facilities require isolators for in-plant substations and process power distribution. Tesla's Nevada and Berlin gigafactories specify compact gas-insulated or vacuum designs for space-constrained electrical rooms.
- Renewable Energy:Offshore wind developers and utility-scale solar operators demand isolators rated for harsh environmental cycling and grid synchronization stress. North Sea wind farms and Spanish solar parks specify salt-spray-resistant designs with extended maintenance intervals.
Utilities retain the dominant procurement volume; renewable energy developers are gaining share fastest as capacity buildouts accelerate.
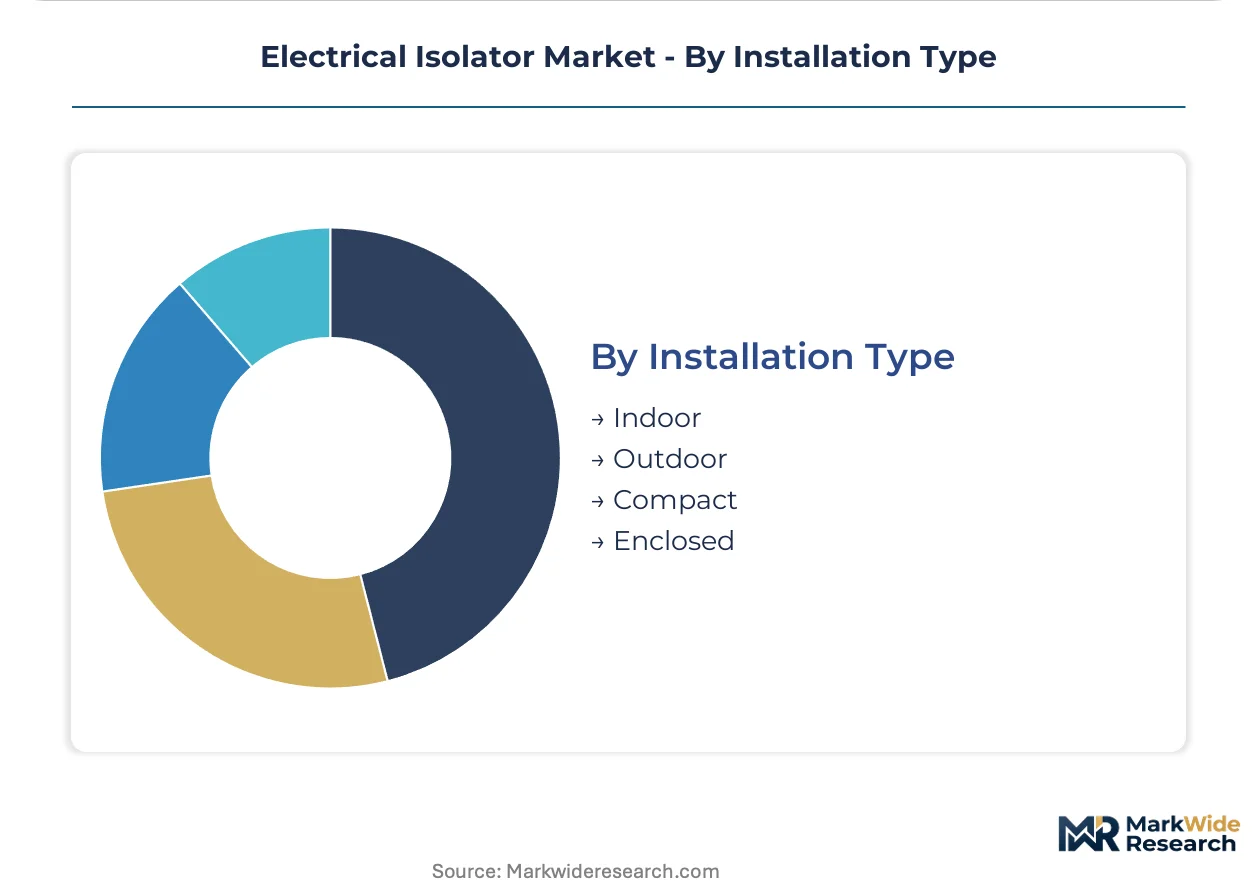
Installation Type:
Volume concentration favors outdoor installations in transmission corridors, while margin accrues to compact designs addressing urban land scarcity and indoor electrical room constraints.
- Indoor:Metal-enclosed switchgear in industrial facilities and urban substations requires isolators with reduced phase spacing and interlocked access mechanisms. Japanese metropolitan utilities and German industrial parks specify these for fire safety and personnel protection.
- Outdoor:Open-terminal designs on lattice structures dominate high-voltage transmission with porcelain or composite insulator strings. China's western UHV corridors and India's interstate transmission networks account for the largest procurement volumes.
- Compact:GIS and hybrid switchgear compress multiple functions into sealed enclosures for dense urban environments. Singapore's underground substations and London's network reinforcement projects specify these where surface land is unavailable.
- Enclosed:Weatherproof housings protect isolators in coastal, desert, and contamination-prone environments. Australian mining operations and Middle East desalination plants require IP-rated enclosures against dust ingress and humidity.
Outdoor installations hold the largest share; compact designs are expanding most quickly as urban substation footprints shrink.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for electrical isolators diverges sharply by geography. Procurement in India and Southeast Asia prioritizes capital cost minimization, while German and Japanese utilities absorb premium pricing for lifecycle performance guarantees and predictive maintenance integration.
China
State Grid Corporation commissions 800 kV and 1100 kV ultra-high-voltage corridors across western provinces, driving specialized isolator demand for extended mechanical endurance. GB standards and NMPA-equivalent grid codes enforce domestic testing protocols for substation equipment. Xi'an and Shenyang manufacturing clusters supply porcelain insulator strings and composite alternatives for 765 kV transmission towers.
Germany
Distribution utilities face mandatory SF6 phase-down deadlines under the EU F-Gas Regulation, compressing timelines for vacuum and dry-air platform adoption. ECHA restrictions on sulfur hexafluoride accelerate R&D budgets toward F-gas-free interruption technologies. Industrial clusters in Bavaria and North Rhine-Westphalia host hermetic packaging specialists trained in vacuum brazing and ceramic-to-metal sealing.
United States
Texas petrochemical complexes and Nevada battery gigafactories specify compact isolators for space-constrained electrical rooms and process isolation safety. FERC grid reliability standards and IEEE 62271 series certifications create compliance barriers favoring established type-test libraries. Southeast manufacturing zones absorb volume for industrial motor control centers requiring frequent operation ratings.
India
The Central Electricity Authority's Green Energy Corridors mandate 765 kV and 400 kV substations with localized content requirements under the PLI scheme. CEA localization mandates favor 132 kV air-insulated designs for rural transmission expansions where land constraints are minimal. Gujarat and Maharashtra industrial corridors concentrate EPC contractor procurement for standardized substation packages.
Japan
Tokyo Electric and metropolitan utilities specify polymer-insulated designs for earthquake resilience and reduced weight in elevated structures. METI efficiency standards and JIS certification requirements govern dielectric withstand specifications for high-voltage equipment. Kanto and Kansai manufacturing bases maintain captive technician networks for ceramic-based isolator production.
Electrical Isolator Market Competitive Landscape
Capability concentration sits with specialized hermetic packaging firms; scale advantage sits with diversified power semiconductor conglomerates. The vendor base organizes around three strategic archetypes: integrated power electronics suppliers with captive isolation functions, dedicated component specialists focused on ceramic and magnetic isolation, and industrial conglomerates with legacy switchgear portfolios. Dominant competitive moves include backward integration into ceramic substrate manufacturing and technology licensing agreements for vacuum interrupter designs.
Among diversified semiconductor suppliers, Infineon Technologies, Texas Instruments, and Murata Manufacturing occupy distinct positioning vectors. Infineon exemplifies the power-electronics-integrated archetype through silicon carbide and IGBT co-packaging with galvanic isolation functions. Texas Instruments represents analog semiconductor expertise applied to embedded isolation within mixed-signal integrated circuits. Murata Manufacturing anchors the compact ceramic specialization tier, serving space-constrained industrial drive applications with brazed ceramic interrupter assemblies.
| Leading Market Players |
|---|
| Infineon Technologies |
| ON Semiconductor |
| Texas Instruments |
| NXP Semiconductors |
| Murata Manufacturing |
| Analog Devices |
| ROHM Semiconductor |
| Silicon Labs |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Guizhou province's alumina export quotas anchor ceramic insulator body costs, compressing margin pools toward vacuum brazing specialists in Bavaria and North Rhine-Westphalia. Pricing power concentrates with manufacturers commanding captive technician networks for hermetic sealing.
Pricing Analysis
Extended lifecycle service contracts now drive lifetime value capture as utilities shift from spot replacement purchasing. Three-tier pricing structure across premium, standard, and economy levels separates transmission-grade type-tested assemblies from distribution framework agreements. Cost compression in air-insulated tiers intensifies because Indian EPC contractors prioritize capital minimization under CEA localization mandates. Renewable energy developers show least price sensitivity, absorbing premiums for salt-spray-resistant designs with fifteen-year maintenance intervals.
Supply Chain Analysis
Extended payment terms from State Grid procurement cycles strain working capital for ceramic substrate suppliers. Manufacturing gravity centers on China, Germany, and Japan for porcelain insulator strings, vacuum interrupter assemblies, and polymer housings respectively. Feedstock dependency rests on high-purity alumina from Guizhou, epoxy resin formulations from industrial chemical clusters, and silicone rubber compounds from Kanto manufacturing bases. Single-source vulnerability runs through Japanese vacuum brazing equipment. Distribution runs through utility framework agreements, EPC turnkey packages, and industrial direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to China's UHV transmission buildout and EU F-Gas Regulation compliance deadlines.
For Market Incumbents: Insulate installed base revenue through predictive analytics subscriptions tied to IEC 61850 process bus architectures. Deepen backward integration into ceramic substrate manufacturing to offset Guizhou alumina quota volatility. Vacuum platform R&D investment represents the critical lever against SF6 phase-down acceleration. For New Entrants and Emerging Players: Establish a beachhead in India's Green Energy Corridors where CEA localization mandates create procurement preference for domestic assembly partners. Target 132 kV air-insulated substations in rural Maharashtra and Gujarat where land constraints are minimal and capital sensitivity peaks. Partner with German hermetic packaging specialists for technology licensing rather than greenfield capability building. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial conglomerates holding legacy switchgear portfolios but lacking digital substation integration capabilities. Five-to-ten year viability hinges on F-gas-free technology transition completion. Monitor EU ECHA enforcement timetables as the inflection signal for vacuum platform valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive alumina supply from Guizhou insulates margin compression from export quota volatility. |
| Digital Substation Platform Integration | IEC 61850 process bus architectures enable software-enabled service contracts with EDF and Enel. |
| Vacuum Interrupter Technology Licensing | Technology transfer agreements with Bavarian hermetic packaging specialists accelerate F-gas-free roadmaps. |
| Green Energy Corridor Partnership | Joint ventures with Indian EPC contractors satisfy CEA localization mandates for 765 kV substations. |
| Predictive Maintenance Service Launch | Fifteen-year lifecycle contracts bundle isolator replacement with embedded Rogowski coil monitoring. |
Research Methodology
Desk research of IEC 62271 type-test libraries, customs trade data, and utility procurement databases preceded structured interviews with substation planning officers, EPC contractor procurement leads, vacuum interrupter R&D directors, and aftermarket service heads. Primary fieldwork across China, Germany, and India validated secondary estimates. Bottom-up unit economics triangulated against top-down transmission investment forecasts.
Assumption sets held EU F-Gas Regulation phase-down timelines and China UHV commissioning schedules fixed while varying raw material cost trajectories and renewable energy capacity buildout rates across the analysis window. Segmentation modeling spanned voltage class, insulation medium, installation environment, and end-user procurement structure. CAGRs derived from utility capital expenditure projections and industrial motor control center replacement cycles.
Sensitivities concentrate around alumina export quota adjustments, ECHA enforcement acceleration, and offshore wind project sanctioning delays. Forecasts reflect documented assumptions regarding technology substitution timelines and regulatory compliance deadlines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Insulator Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Europe Electrical Bushing Market