
 Semiconductor Logistics Market | 2026-2036
Semiconductor Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Logistics Market Analytics
Foundry capacity in Taiwan is expanding faster than port throughput can absorb, creating a structural bottleneck at Kaohsiung and Taichung harbors. DHL Supply Chain & Global Forwarding leverages dedicated semiconductor lanes from Hsinchu Science Park to anchor its Asia-Pacific network. Kuehne + Nagel sustains temperature-controlled charter capacity for EUV photomask shipments. DSV differentiates through bonded warehousing at Amsterdam Schiphol, competing for European distribution of memory modules.
Semiconductor logistics encompasses the specialized movement, storage, and handling of integrated circuits, wafers, and chipmaking equipment under controlled atmospheric conditions, typically maintaining Class 1000 cleanroom equivalence and vibration thresholds below 0.5 G during transit. Freight forwarding commands the largest value pool due to capital-intensive cold chain and shock-mitigation requirements for lithography components, while IoT Solutions within the technology dimension represents the fastest-expanding segment as real-time wafer lot tracking becomes mandatory for foundry customers. Cloud-Based Platforms now sit at the margin center, enabling OEMs to consolidate multi-tier distributor visibility without owning physical infrastructure.
REACH and RoHS frameworks in Europe constrain packaging materials and chemical handling protocols for cross-border semiconductor shipments, while the EU AI Act introduces traceability requirements that extend through logistics chains for chips destined for high-risk applications. The US Department of Commerce export controls on advanced node equipment force logistics providers to reconfigure routing certificates and end-user documentation. Stakeholders must monitor how dual-use technology classifications proliferate beyond current jurisdiction sets, as compliance complexity becomes the primary determinant of provider switching costs.
Market Dynamics
Foundry concentration in Taiwan has created a structural chokepoint where port throughput at Kaohsiung and Taichung lags wafer output expansion, forcing logistics networks to absorb capacity constraints through air freight substitution and bonded warehousing densification.
Growth Catalysts
- EU Chips Act traceability mandates:Certification requirements for semiconductor shipments create recurring revenue streams for logistics providers with audit-ready documentation systems.
- Automotive ADAS penetration:Chip-grade cold chain demand from vehicle OEMs pulls specialized handling capacity into the semiconductor lane network.
- EUV photomask transport protocols:Temperature-controlled charter requirements for lithography components sustain premium freight forwarding margins.
Market Restraints
- Marine fuel cost volatility:Bunker price swings compress margins on ocean freight legs that handle bare wafer volumes.
- Single-source lithography equipment dependency:ASML's monopoly on EUV scanners concentrates routing risk through Dutch customs corridors.
- REACH packaging material constraints:ECHA restrictions on chemical handling protocols limit cross-border reuse of standard semiconductor containers.
Strategic Opportunities
- India PLI scheme fab incentives:Greenfield foundry construction in Gujarat and Karnataka will require de novo cold chain infrastructure without legacy port constraints.
- Cloud-based visibility platforms:Multi-tier distributor consolidation tools enable OEMs to outsource physical infrastructure while retaining lot-level traceability.
- EU AI Act high-risk chip logistics:Traceability requirements for autonomous system semiconductors extend compliance service contracts through the value chain.
Industry Challenges
- Cleanroom technician scarcity:Class 1000 equivalence certification for handling staff lags demand in emerging logistics hubs.
- Dual-use export control documentation:US Department of Commerce advanced node equipment classifications force routing certificate reconfiguration mid-shipment.
- Legacy ERP integration friction:Real-time wafer tracking APIs encounter protocol mismatches with foundry MES systems deployed before 2018.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Logistics Market |
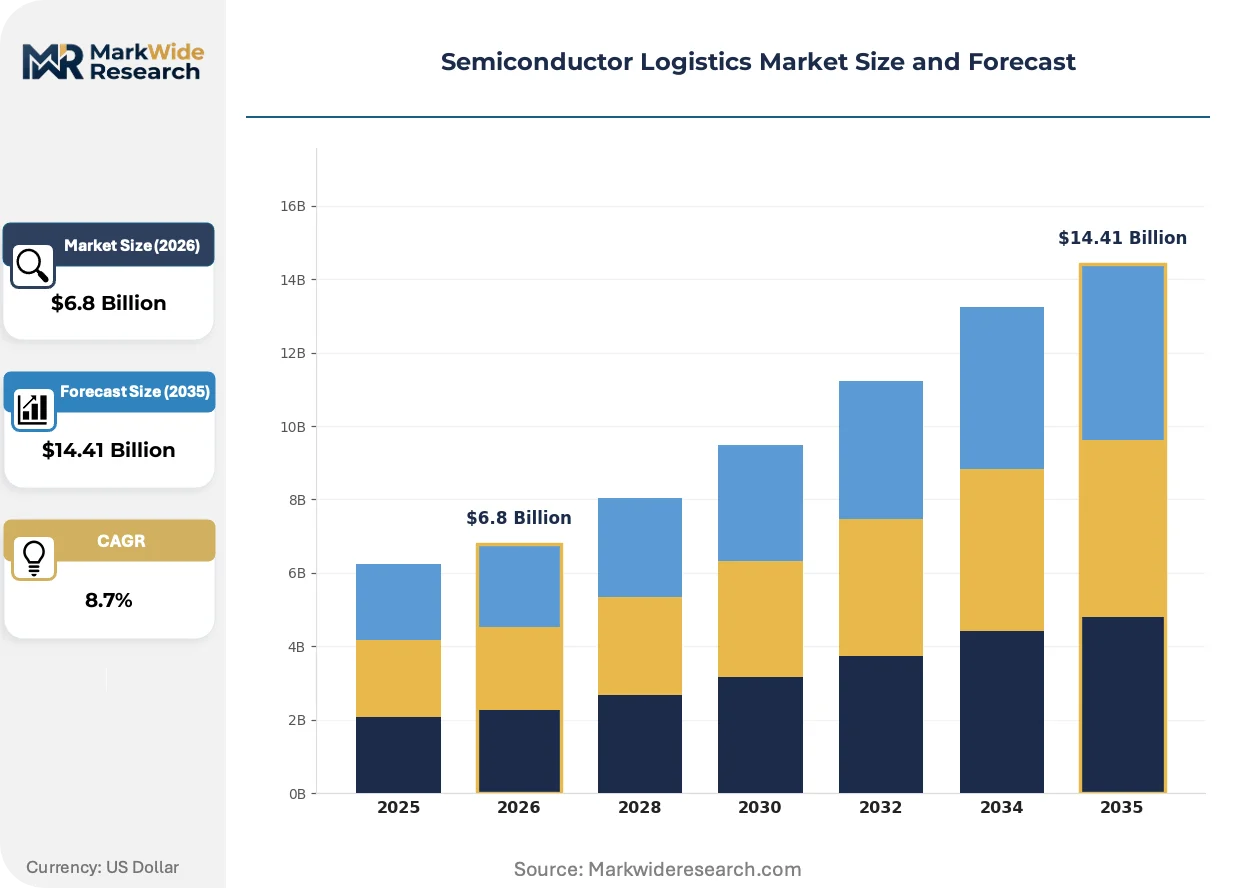
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Inventory Management, Supply Chain Consulting Client Type: OEMs, Distributors, Retailers, End Users Technology: RFID Tracking, IoT Solutions, Cloud-Based Platforms, Automation Tools Delivery Model: Just-In-Time, Direct Shipping, Drop Shipping, Third-Party Logistics |
| Companies Covered | DSV, UPS Supply Chain Solutions, DHL Supply Chain & Global Forwarding, CEVA Logistics, FedEx Logistics, Kuehne + Nagel, Yusen Logistics, Kintetsu World Express, Nippon Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Logistics Market Evolving Landscape
Operational technology investment is compressing decision cycles from shipment-level to lot-level granularity, embedding semiconductor logistics deeper into foundry production scheduling systems.
Distributed ledger protocols for provenance verification are decentralizing custody documentation away from carrier-centric systems toward consortia models where foundries, OEMs, and logistics providers maintain synchronized records. TSMC and Samsung have piloted blockchain-based handoff certificates for EUV mask shipments since 2022. The structural consequence is a compression in dispute resolution cycles and a shift in liability allocation toward the technology provider.
REACH and RoHS framework expansion is tightening material constraints on semiconductor packaging for European-bound shipments, with ECHA now reviewing additional restricted substances in anti-static films. The industrial consequence is accelerated qualification of alternative polymer formulations that maintain ionic contamination thresholds below 10 parts per billion. Memory module distributors serving automotive OEMs face the most acute compliance recertification timelines.
Buyer consolidation among hyperscale cloud operators is compressing contract durations from annual to quarterly renegotiation cycles, with procurement teams now demanding real-time lane pricing indexed to fuel and capacity indices. Freight forwarders are responding with API-first rate exposure tools that replace static tariff sheets. This shift is most visible in Taiwan-to-US West Coast corridors where Microsoft, Amazon, and Google collectively account for dominant wafer lot volumes.
Semiconductor Logistics Market Segmentation
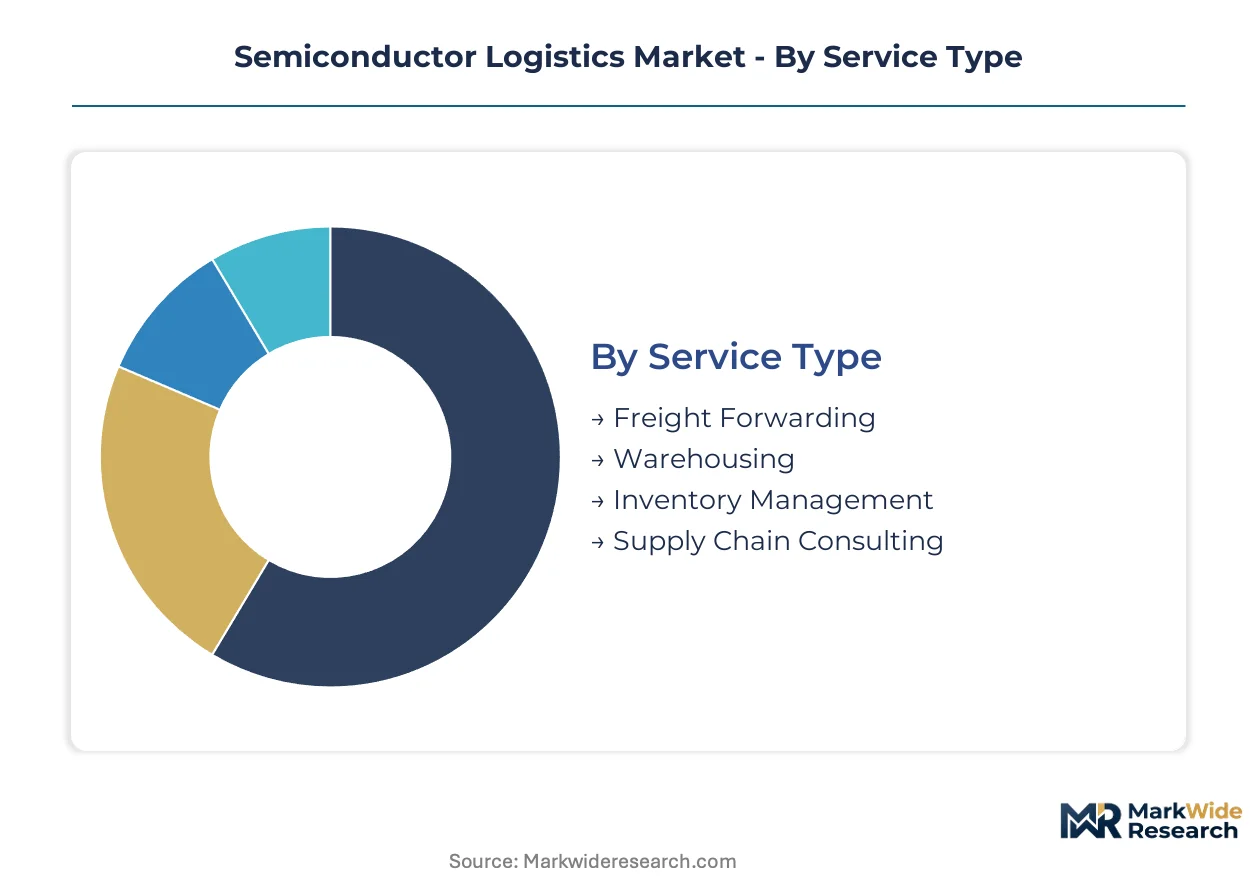
Semiconductor logistics providers configure service portfolios around four distinct axes: capital intensity of physical handling, customer integration depth, data infrastructure maturity, and inventory velocity requirements. Each axis carries different margin profiles and switching costs, shaping how specialized players defend position against integrated forwarding networks.
Service Type:
Supply concentration in Taiwan's foundry corridor elevates freight forwarding above other service tiers, as lithography equipment and EUV mask movements command premium charter capacity that warehousing alone cannot replicate.
- Freight Forwarding:Capital-intensive cold chain and shock-mitigation infrastructure for lithography components. Demand concentrates with ASML equipment movements through Dutch customs corridors and TSMC-bound charters from Schiphol, where temperature-controlled capacity scarcity sustains margin premiums.
- Warehousing:Bonded cleanroom facilities maintaining Class 1000 equivalence for WIP inventory. DSV's Amsterdam Schiphol operations and DHL's Hsinchu Science Park nodes compete for memory module distribution to automotive OEMs requiring chip-grade environmental controls.
- Inventory Management:Lot-level tracking integration with foundry MES systems for real-time WIP visibility. Automotive ADAS chip qualification timelines pull demand toward providers with TSMC-certified API connectivity.
- Supply Chain Consulting:EU Chips Act traceability documentation and REACH packaging compliance advisory. ECHA material restriction updates drive recurring certification projects for cross-border semiconductor shipments.
Today's leader: Freight Forwarding. Tomorrow's challenger: Inventory Management.
Client Type:
Cost tier stratification separates high-volume contract logistics from transactional spot arrangements, with OEMs capturing scale pricing while distributors absorb complexity premiums for multi-tier visibility.
- OEMs:Hyperscale cloud operators and automotive manufacturers with quarterly renegotiation cycles and API-first rate exposure tools. Microsoft, Amazon, and Google collectively dominate Taiwan-to-US West Coast wafer lot volumes, compressing contract durations from annual to quarterly cycles.
- Distributors:Memory module specialists serving fragmented automotive OEM networks. REACH and RoHS compliance recertification timelines concentrate demand with providers offering ECHA-aligned packaging material qualification.
- Retailers:Electronics channel partners requiring last-mile traceability for consumer semiconductor products. EU AI Act high-risk application classifications extend documentation requirements through retail logistics chains.
- End Users:Direct foundry relationships for captive logistics operations. TSMC and Samsung blockchain-based EUV mask handoff pilots since 2022 reduce intermediary dependence for mask provenance verification.
OEMs anchor current revenue. Distributors are climbing the fastest as compliance complexity deepens.
Technology:
Application-specific technology deployment separates real-time operational systems from retrospective analytics, with foundry integration requirements dictating investment priority.
- RFID Tracking:Wafer lot identification at fab ingress and egress points. Kaohsiung and Taichung port congestion forces air freight substitution where RFID handoff verification accelerates customs clearance.
- IoT Solutions:Environmental monitoring for shock, vibration, and temperature excursions during EUV photomask transit. Kuehne + Nagel sustains dedicated charter capacity with sensor-equipped containers maintaining thresholds below 0.5 G vibration.
- Cloud-Based Platforms:Multi-tier distributor visibility without physical infrastructure ownership. OEM procurement teams demand real-time lane pricing indexed to marine fuel and capacity indices, displacing static tariff sheets.
- Automation Tools:Robotic handling for cleanroom-equivalent container movements. Class 1000 certification scarcity for technician staff accelerates automation investment in emerging logistics hubs.
Cloud-Based Platforms dominate margin capture. IoT Solutions show steepest expansion trajectory as real-time wafer tracking becomes mandatory.
Delivery Model:
Volume concentration in advanced node production favors velocity-optimized models over inventory-heavy alternatives, with foundry cycle time pressure eliminating buffer stock tolerance.
- Just-In-Time:Synchronized delivery windows with lithography equipment installation schedules. ASML EUV scanner monopoly concentrates routing risk through single customs corridors, requiring precise arrival coordination.
- Direct Shipping:Foundry-to-OEM lot movements bypassing distributor warehouses. India PLI scheme fab construction in Gujarat and Karnataka will require de novo direct shipping networks without legacy port constraints.
- Drop Shipping:End-user fulfillment from bonded warehouse inventory. Automotive ADAS chip demand pulls drop shipping capacity into semiconductor lane networks previously optimized for consumer electronics.
- Third-Party Logistics:Outsourced handling for non-core semiconductor movements. US Department of Commerce export control documentation complexity increases switching costs for providers with pre-cleared routing certificates.
Just-In-Time commands current premium pricing. Direct Shipping is gaining share fastest as India fab investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting semiconductor logistics investment toward jurisdictions where compliance costs remain below EU REACH thresholds. Foundry construction in India and Southeast Asia exploits this gap, pulling capital away from legacy European hubs.
United States
CHIPS and Science Act subsidies are accelerating fab construction in Arizona and Texas, creating demand for specialized cold chain corridors from Dutch ASML equipment origins. The Department of Commerce export controls on advanced node equipment force logistics providers to maintain pre-cleared routing certificates. Phoenix and Austin logistics clusters are expanding bonded warehousing capacity to handle EUV scanner inbound flows.
Taiwan
TSMC and UMC foundry output dominates global wafer supply, generating concentrated demand for shock-resistant transport from Hsinchu Science Park. Kaohsiung and Taichung port congestion is forcing air freight substitution for time-critical photomask movements. The National Development Council fab expansion plans are outpacing harbor infrastructure upgrades, creating structural capacity bottlenecks.
Netherlands
ASML's Veldhoven headquarters anchors EUV lithography equipment supply, concentrating high-value logistics through Amsterdam Schiphol customs corridors. ECHA REACH restrictions on packaging materials force container qualification cycles for cross-border semiconductor shipments. DSV's bonded warehousing operations at Schiphol compete for European distribution of memory modules requiring Class 1000 equivalence.
India
PLI scheme fab incentives in Gujarat and Karnataka are attracting greenfield foundry construction without legacy port constraints. The Ministry of Electronics and Information Technology semiconductor mission mandates traceability standards that reshape logistics provider certification requirements. Dholera and Bengaluru logistics corridors require de novo cold chain infrastructure investment.
Japan
Tokyo Electron and Shin-Etsu Chemical supply chain nodes generate demand for vibration-controlled transport of silicon wafer materials. METI semiconductor supply chain resilience initiatives are subsidizing domestic logistics infrastructure upgrades. Kyushu and Hiroshima manufacturing clusters are expanding cleanroom-equivalent handling capacity for advanced node components.
Semiconductor Logistics Market Competitive Landscape
European freight forwarders anchor one tier; Asia-Pacific specialists hold charter capacity advantages in Taiwan corridor operations. The market structures around three player tiers: integrated global networks, regional cleanroom specialists, and technology-enabled visibility platforms. Strategic differentiation concentrates on M&A-driven geographic expansion and API-first customer integration.
Among integrated forwarding networks, DHL Supply Chain & Global Forwarding and Kuehne + Nagel occupy positions representing capital-intensive cold chain infrastructure archetypes. DSV exemplifies the bonded warehousing specialist model through its Amsterdam Schiphol operations. These three companies collectively illustrate how provider switching costs escalate with compliance documentation depth.
| Leading Market Players |
|---|
| DSV |
| UPS Supply Chain Solutions |
| DHL Supply Chain & Global Forwarding |
| CEVA Logistics |
| FedEx Logistics |
| Kuehne + Nagel |
| Yusen Logistics |
| Kintetsu World Express |
| Nippon Express |
| Others |
Value Network & Pricing Analysis
Captive integration into foundry-adjacent logistics networks anchors both supply positioning and pricing power for semiconductor freight forwarders serving TSMC and UMC output corridors. This vertical control over Class 1000 cleanroom handling and shock-mitigation infrastructure enables premium rate capture where port congestion at Kaohsiung and Taichung forces air freight substitution for time-critical photomask movements.
Pricing Analysis
Distributor margin layers dominate semiconductor logistics pricing, with memory module specialists serving fragmented automotive OEM networks absorbing complexity premiums for REACH-compliant packaging qualification. Three-tier pricing structure across premium charter capacity, standard bonded warehousing, and economy ocean freight separates EUV photomask movements from bare wafer volumes. Cost compression in ocean freight tiers is intensifying because marine fuel volatility compresses margins on legacy port routes. Hyperscale cloud operators exhibit least price sensitivity due to quarterly renegotiation cycles indexed to real-time capacity indices, while regional distributors face acute sensitivity from ECHA material restriction recertification timelines.
Supply Chain Analysis
REACH and RoHS certification gating constrains cross-border reuse of standard semiconductor containers, forcing accelerated qualification of alternative polymer formulations for European-bound shipments. Supply concentrates in Taiwan, South Korea, and the Netherlands, with lithography equipment movements drawing from ASML's Veldhoven monopoly and photomask charters resting on Schiphol temperature-controlled capacity. Raw material dependencies span silicon wafers, EUV photoresists, and ionic contamination-controlled packaging films. Single-source lithography equipment vulnerability concentrates routing risk through Dutch customs corridors. Distribution runs through bonded warehouse nodes at Amsterdam Schiphol and Hsinchu Science Park for automotive ADAS chip qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor logistics functions as a stable compounder anchored by EU Chips Act traceability mandates that create recurring certification revenue streams across contract durations. Foundry output expansion in Taiwan and greenfield construction in India sustain infrastructure utilization premiums throughout the analysis window.
For Market Incumbents: Cement API-first integration capabilities with TSMC-certified MES connectivity to defend against cloud-platform entrants displacing static tariff structures. Add bonded cleanroom capacity in Gujarat and Karnataka before India PLI scheme fab commissioning eliminates first-mover positioning. Prioritize ECHA-aligned packaging material qualification to capture REACH recertification cycles from memory module distributors.
For New Entrants and Emerging Players: Enter via cloud-based visibility platforms targeting mid-tier automotive OEMs lacking direct foundry relationships for lot-level traceability. White-space concentrates in India Dholera logistics corridors where de novo cold chain infrastructure precedes legacy port constraints. Pursue EU AI Act high-risk chip documentation services as the most penetrable compliance wedge against incumbent forwarding networks.
For Investors and Strategic Acquirers: Roll-up economics work for regional cleanroom specialists because certification scarcity for Class 1000 technician staff creates defendable local moats. Target acquisition archetypes: bonded warehousing operators at constrained air freight hubs with pre-cleared US Department of Commerce routing certificates. Watch for India Ministry of Electronics and Information Technology traceability standard announcements as inflection signal for infrastructure investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables real-time lane pricing indexed to marine fuel and capacity indices for hyperscaler procurement teams. |
| India Logistics Corridor Expansion | Captures PLI scheme fab construction in Gujarat and Karnataka without legacy port throughput constraints. |
| EUV Photomask Charter Capacity Addition | Sustains premium margins through temperature-controlled ASML equipment movements via Amsterdam Schiphol. |
| Blockchain Provenance Verification | Reduces dispute resolution cycles for TSMC and Samsung EUV mask handoff documentation. |
| REACH Packaging Material Qualification | Secures recurring certification revenue from ECHA restriction updates for automotive memory distributors. |
Research Methodology
Multiple input streams — primary interviews with freight forwarding executives, foundry logistics managers, and automotive OEM procurement leads; secondary validation through customs trade data, SEC logistics provider filings, and ECHA regulatory updates — were reconciled through bottom-up and top-down triangulation. Foundry MES system integration protocols and EU Chips Act documentation requirements were cross-referenced against carrier API capability disclosures.
Data-stream reconciliation across service type, client tier, technology deployment, and delivery model dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level capacity utilization trends and infrastructure investment pipelines. Forecast inputs incorporated ASML equipment shipment patterns, Taiwan port throughput constraints, and India PLI scheme disbursement timelines without year-specific anchoring.
Inputs from carrier tariff disclosures and foundry production schedules were available through the study window; gaps in real-time MES API standardization introduce uncertainty bands around lot-level tracking adoption curves. Forecasts reflect documented assumptions regarding EU AI Act implementation scope and US Department of Commerce export control classification expansion. A model refresh is warranted upon material change in India fab construction velocity or ECHA restricted substance list updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market