
 Interventional Radiology Market | 2026-2036
Interventional Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Radiology Market Analysis
Modularization of imaging-guided procedure kits is hardening as the dominant procurement pattern across hospital systems. Siemens Healthineers leverages its integrated angiography-CT platforms to anchor premium positioning in hybrid operating suites. Boston Scientific competes through specialized embolization coils and drug-eluting bead portfolios. Philips Healthcare differentiates via its cone-beam CT roadmap and interventional oncology software ecosystem.
Interventional radiology encompasses image-guided, minimally invasive diagnostic and therapeutic procedures performed using catheters, guidewires, needles, and specialized instruments under real-time imaging with typical working diameters of 2–6 French for vascular access. Fluoroscopy remains the backbone modality, though cone-beam CT and intraprocedural ultrasound are expanding functional capabilities for soft-tissue targeting. Catheters and guidewires command the largest product revenue pool due to single-use consumption patterns and procedure volume density in peripheral vascular and neurointerventional workflows. Oncology applications represent the fastest-expanding therapeutic segment, driven by locoregional tumor treatments and palliative interventions that reduce systemic toxicity burdens.
The FDA's 510(k) clearance pathway and the EU Medical Device Regulation's clinical evidence requirements govern product commercialization and post-market surveillance obligations across the two largest addressable markets. Japan's PMDA and METI coordinate reimbursement pricing with technical standards for advanced medical devices, creating layered market access conditions. Stakeholders must monitor evolving AI-enabled imaging integration standards and shifting site-of-care economics between inpatient hospitals and outpatient facilities.
Market Dynamics
Modular procedure kits are compressing procurement cycles across hospital systems, forcing device manufacturers to reconfigure supply relationships around standardized component platforms rather than proprietary closed systems.
Growth Catalysts
- Oncology Suite Expansion:Academic medical centers in the United States are outfitting dedicated interventional radiology wings for tumor ablation, creating pull-through demand for consumables and imaging systems.
- MDR Clinical Evidence Pathways:The EU Medical Device Regulation's streamlined equivalence routes for well-established technologies are accelerating 510(k)-cleared device entries into European markets.
- Fluoroscopy-to-Cone-Beam Migration:Hybrid angiography-CT platforms are displacing standalone fluoroscopy in new hospital construction, expanding addressable hardware spend per installation.
Market Restraints
- Niobium-Tantalum Price Volatility:Embolization coil and guidewire manufacturers face margin compression from rare earth metal input swings tied to Central African supply concentration.
- Class II Device Friction:FDA 510(k) substantial equivalence determinations for software-enabled imaging integration are extending clearance timelines by six to eighteen months versus hardware-only submissions.
- Interventional Cardiology Competition:Cath lab scheduling priority for cardiac procedures limits available slot hours for oncology interventions in mid-sized community hospitals.
Strategic Opportunities
- Outpatient Migration:Ambulatory surgery centers in Germany are securing reimbursement for radiofrequency ablation outside inpatient settings, opening lower-overhead procedure venues.
- AI-Enabled Targeting:Real-time lesion segmentation algorithms are converging with cone-beam CT workflows to reduce operator dependence and training barriers.
- Japan PMDA Fast-Track:METI's Sakigake designation for breakthrough devices offers priority review and early reimbursement pricing for novel embolization platforms.
Industry Challenges
- Cross-Trained Specialist Scarcity:Dual-competency radiologists with interventional oncology fellowships remain concentrated at tertiary centers, constraining procedure volume expansion.
- Legacy PACS Integration:Proprietary DICOM formats from angiography-CT hybrids require custom middleware development, delaying deployment and elevating IT capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Radiology Market |
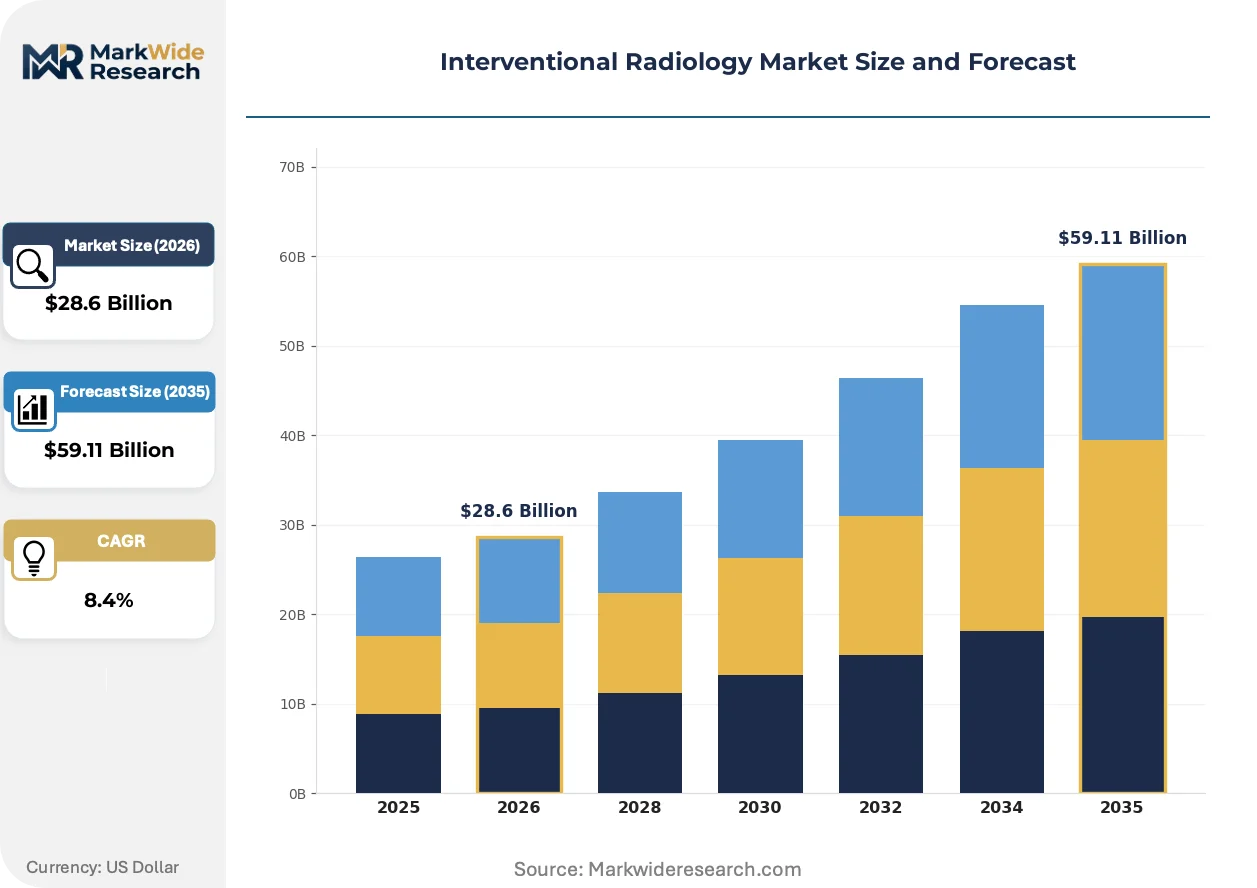
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
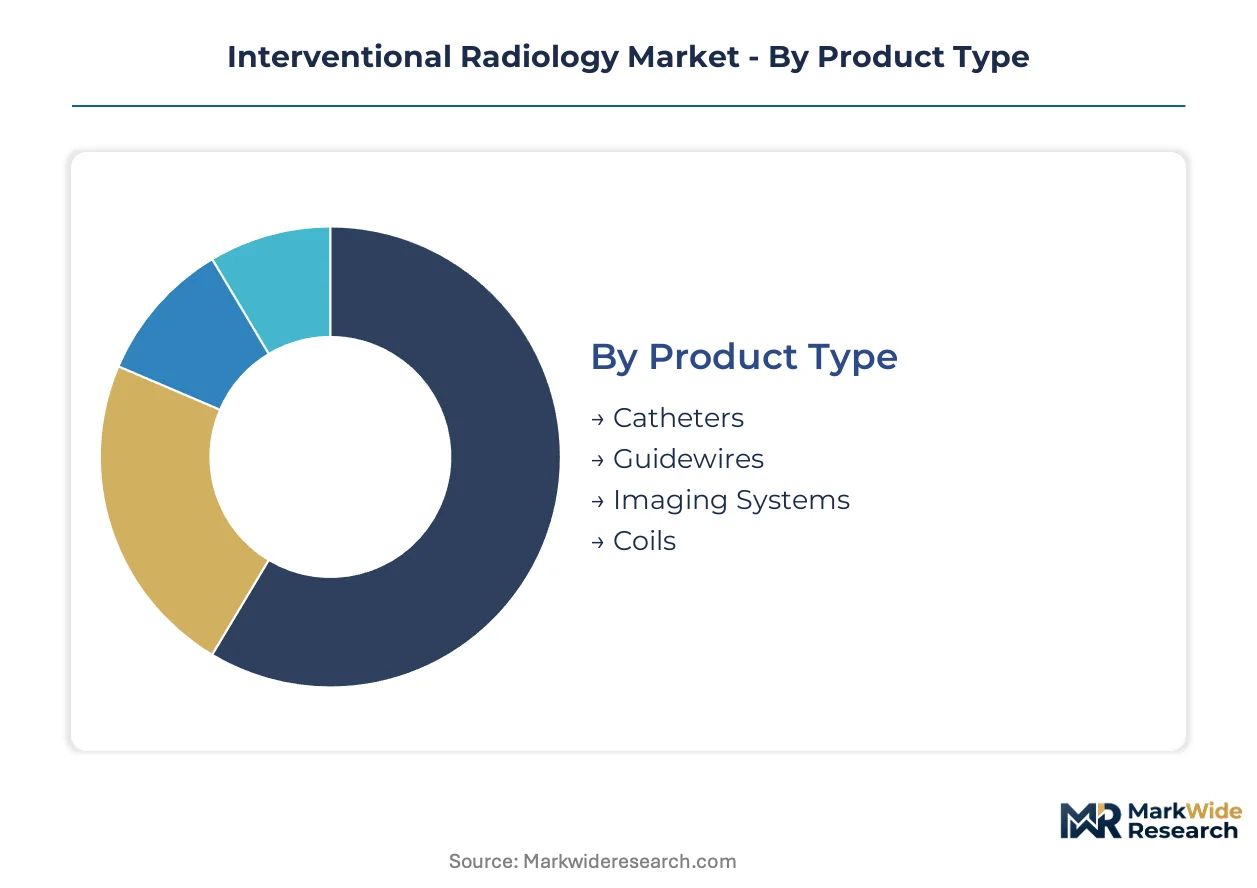
| Segmentation | Product Type: Catheters, Guidewires, Imaging Systems, Coils Application: Oncology, Urology, Gastroenterology, Pain Management End User: Hospitals, Outpatient Facilities, Ambulatory Surgical Centers, Research Institutions Technology: Fluoroscopy, Ultrasound, CT Imaging, MRI |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Siemens Healthineers, GE HealthCare, Philips Healthcare, Johnson & Johnson (Cordis), Cook Medical, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Radiology Market Emerging Trajectories
Real-time imaging fusion and disposable kit standardization are compressing procedure times and reshaping how hospitals evaluate capital equipment procurement against per-case consumable economics.
Cone-beam CT is converging with intraprocedural ultrasound to enable soft-tissue navigation without contrast administration. Oncology interventionalists at academic centers are adopting these fused workflows for liver and renal ablations. The technology is converging with automated needle guidance systems to reduce fluoroscopy exposure and operator variability.
The EU Medical Device Regulation's post-market surveillance requirements are mandating annual safety reporting for Class IIa and IIb devices. Manufacturers must maintain European Authorized Representatives and vigilance systems. Interventional oncology software modules face particular scrutiny where algorithm updates trigger re-certification obligations.
Hospital procurement departments are consolidating vendor relationships through master service agreements that bundle capital equipment, disposables, and maintenance. Integrated delivery networks in the United States are displacing standalone device purchasing with multi-year partnerships. Japan's university hospitals are piloting similar consolidated sourcing for angiography suites.
Interventional Radiology Market Segmentation
Device classification under FDA 510(k) and EU MDR pathways varies sharply across product categories, creating divergent commercialization timelines and evidence burdens. Understanding how regulatory requirements map to each segment enables manufacturers to prioritize development resources and anticipate market access hurdles.
Product Type:
FDA Class II designations dominate this category, with substantial equivalence determinations ranging from six months for established catheter platforms to eighteen months for software-integrated imaging systems under the EU MDR's clinical evaluation requirements.
- Catheters:Single-use vascular access devices with working diameters of 2–6 French, manufactured from polyurethane and nylon blends. Demand concentrates in peripheral vascular workflows at academic medical centers in the United States, where procedure volume density drives consumable procurement through modular kit agreements.
- Guidewires:Nitinol and stainless steel core constructions with hydrophilic coatings for lesion navigation. German hospital systems anchor European demand, though niobium-tantalum price volatility from Central African supply concentration compresses manufacturer margins.
- Imaging Systems:Angiography-CT hybrid platforms requiring FDA 510(k) and PMDA technical standards compliance.
- Coils:Platinum embolization devices for vascular occlusion, subject to MDR post-market surveillance obligations.
Leading the category by volume: Catheters. Growing fastest: Imaging Systems.
Application:
Cost tier stratification separates high-acuity oncology interventions from routine pain management procedures, with reimbursement differentials of 40–60% between inpatient tumor ablation and outpatient nerve blocks.
- Oncology:Locoregional tumor treatments including radiofrequency ablation, microwave ablation, and transarterial chemoembolization. Academic medical centers in the United States and Japan drive adoption, pulled by expanding interventional suites and METI's Sakigake fast-track designation for novel embolization platforms.
- Pain Management:Image-guided nerve blocks and vertebral augmentation for palliative care. Ambulatory surgery centers in Germany are securing reimbursement for radiofrequency ablation outside inpatient settings, opening lower-overhead venues.
- Urology:Prostate artery embolization and nephrostomy procedures, concentrated at tertiary referral centers.
- Gastroenterology:Biliary drainage and portal vein interventions, limited by cross-trained specialist scarcity.
Oncology commands premium pricing. Pain Management is climbing the fastest as site-of-care economics shift toward outpatient facilities.
End User:
Customer type determines capital intensity, with hospitals deploying full angiography-CT hybrids while outpatient facilities rely on leased fluoroscopy systems and disposable-heavy workflows.
- Hospitals:Integrated delivery networks in the United States are consolidating vendor relationships through master service agreements bundling capital equipment, disposables, and maintenance. Hybrid operating suite construction is accelerating fluoroscopy-to-cone-beam migration.
- Ambulatory Surgical Centers:Lower-overhead venues in Germany and pilot programs in Japan's university hospitals are adopting consolidated sourcing models for angiography suites.
- Outpatient Facilities:Standalone imaging centers with leased equipment and per-procedure consumable economics.
- Research Institutions:Early-stage AI-enabled targeting algorithm development, facing proprietary DICOM format integration delays.
Hospitals dominate installed base. Ambulatory Surgical Centers are gaining share fastest as reimbursement pathways mature.
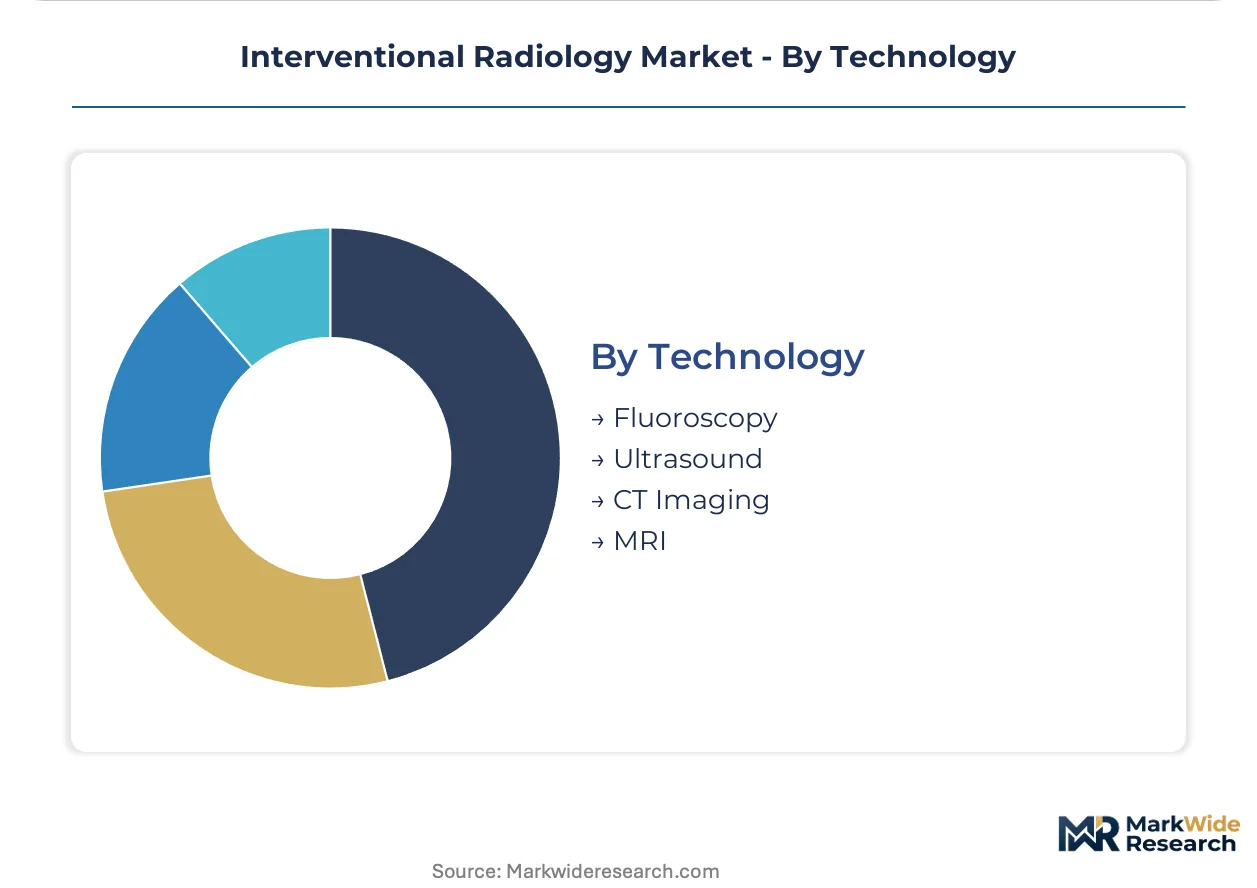
Technology:
Maturity curves separate legacy fluoroscopy dominance from emerging cone-beam CT adoption, with training barriers and IT capital requirements determining uptake velocity.
- Fluoroscopy:Real-time X-ray guidance remains the backbone modality for vascular access and device navigation. Mid-sized community hospitals in the United States maintain heavy reliance, though cath lab scheduling priority for cardiac procedures limits available slot hours for oncology interventions.
- Cone-Beam CT:Three-dimensional soft-tissue imaging without contrast administration, converging with intraprocedural ultrasound for liver and renal ablations. Siemens Healthineers anchors premium positioning through integrated angiography-CT platforms.
- Ultrasound:Intraprocedural guidance for soft-tissue targeting, expanding functional capabilities alongside fluoroscopy.
- CT Imaging:Diagnostic staging and treatment planning, with limited real-time interventional deployment.
Fluoroscopy leads by procedure volume. Cone-Beam CT shows the steepest expansion trajectory as hybrid suite construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of interventional radiology devices concentrates in Germany, Japan, and the United States, while consumption spreads across academic medical centers and ambulatory networks in these same markets with diverging reimbursement maturity.
United States
Academic medical centers in Boston and Houston are expanding dedicated interventional oncology suites, pulling hardware and consumable demand. The FDA's 510(k) pathway governs Class II device clearances, though software-integrated imaging submissions face extended timelines. Integrated delivery networks across the Midwest are consolidating vendor relationships through master service agreements.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia are securing reimbursement for radiofrequency ablation outside inpatient settings. The EU Medical Device Regulation's post-market surveillance obligations mandate annual safety reporting for Class IIa and IIb devices. Siemens Healthineers anchors premium positioning in hybrid operating suite construction across university hospitals.
Japan
University hospitals in Tokyo and Osaka are piloting consolidated sourcing models for angiography suites. METI's Sakigake designation offers priority review and early reimbursement pricing for novel embolization platforms. The PMDA coordinates technical standards with reimbursement pricing, creating layered market access for breakthrough devices.
United Kingdom
Tertiary referral centers in London and Manchester are adopting cone-beam CT workflows for liver and renal ablations. The Medicines and Healthcare products Regulatory Agency enforces CE marking under retained EU law post-Brexit. Research institutions in Cambridge are developing AI-enabled targeting algorithms with proprietary DICOM integration challenges.
China
Provincial hospitals in Shanghai and Beijing are deploying hybrid angiography-CT platforms in new construction. The National Medical Products Administration oversees technical standards for advanced medical devices under accelerated review pathways. Domestic manufacturers are expanding catheter and guidewire production to serve volume demand in peripheral vascular workflows.
Interventional Radiology Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with imaging and interventional portfolios. Tier-one positions are held by manufacturers with integrated hardware-software ecosystems, while mid-tier players compete through specialized consumable portfolios. Strategic archetypes include full-stack imaging-interventional hybrids, focused embolization device specialists, and catheter-platform pure-plays. Dominant competitive moves encompass multi-year hospital partnership agreements and backward integration into nitinol and platinum component supply.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positioning across vascular and oncology intervention portfolios. Siemens Healthineers occupies a position as the imaging-integrated hybrid platform anchor, while Philips Healthcare represents the cone-beam CT and software ecosystem vector. Stryker Corporation and GE HealthCare sit within the capital equipment and disposable bundling archetype, competing for integrated delivery network contracts.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Siemens Healthineers |
| GE HealthCare |
| Philips Healthcare |
| Johnson & Johnson (Cordis) |
| Cook Medical |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Niobium-tantalum feedstock from Central African mines flows through German and Japanese refineries before reaching platinum coil and nitinol guidewire manufacturers, with rare earth price volatility compressing margins at the component tier and forcing three-tier pricing stratification across premium angiography-CT platforms, mid-range fluoroscopy systems, and economy catheter kits.
Pricing Analysis
Margin tightening in consumable tiers reflects niobium-tantalum price volatility and single-use consumption patterns. Three-tier pricing structure across premium, standard, and economy levels separates Siemens Healthineers integrated platforms from mid-range Philips cone-beam CT offerings and economy catheter-platform pure-plays. Cost-down pressure on standard-tier devices accelerates because hospital procurement departments are consolidating vendor relationships through master service agreements. Academic medical centers show least price sensitivity due to bundled capital-disposable contracts, while ambulatory surgery centers in Germany exhibit highest sensitivity as reimbursement pathways mature for outpatient radiofrequency ablation.
Supply Chain Analysis
Platinum group metal supply rests on South African mining operations and Russian refining capacity, with nitinol shape-memory alloy production concentrated in United States and Japanese specialty metalworks. Embolization coil manufacturers draw from niobium-tantalum wire feedstock processed through Central African supply corridors. Single-source vulnerability in rare earth metal concentration creates exposure to geopolitical disruption and commodity price swings. Distribution runs through hospital procurement departments and integrated delivery network master service agreements in the United States, with direct-to-hospital contracting dominating angiography-CT platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over nitinol and platinum component supply determines margin defense, with backward integration into specialty metal feedstock emerging as the decisive competitive lever.
For Market Incumbents: Hedge against niobium-tantalum price volatility through captive supply agreements with Central African refineries or Japanese specialty metalworks. Secure hospital system partnerships through multi-year master service agreements bundling capital equipment, disposables, and maintenance to lock out mid-tier competitors. Reinforce software-integrated imaging positions before FDA 510(k) timelines extend further for algorithm-enabled submissions. For New Entrants and Emerging Players: Direct-to-ambulatory sales channels in Germany offer the most penetrable entry vector as reimbursement for outpatient radiofrequency ablation expands outside inpatient settings. Target AI-enabled targeting algorithm development for cone-beam CT workflows, where proprietary DICOM integration delays create white-space for middleware specialists. Pursue Japan's METI Sakigake fast-track designation as a regulatory accelerant for novel embolization platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor catheter-platform pure-plays with established FDA 510(k) clearance portfolios and modular kit agreements with United States academic medical centers. Long-term viability over the projection horizon hinges on software-integrated imaging capabilities and cone-beam CT roadmap execution. Monitor FDA substantial equivalence determination timelines for software-enabled imaging integration as an inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Master service agreements with United States integrated delivery networks lock in multi-year consumable volumes. |
| CE Marking Pathway | EU MDR streamlined equivalence routes accelerate 510(k)-cleared device entries into European markets. |
| Backward Integration | Captive nitinol and platinum component supply defends margin compression from rare earth metal volatility. |
| Software Companion Development | Real-time lesion segmentation algorithms reduce operator dependence and training barriers in cone-beam CT workflows. |
| Reimbursement Strategy | Germany ambulatory surgery center radiofrequency ablation pathways open lower-overhead procedure venues. |
Methodological Framework
Independent corroboration across interventional radiology department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, EU MDR technical documentation, PMDA reimbursement pricing filings, and hospital capital equipment procurement records. Bottom-up procedure volume modeling triangulates against top-down imaging system installation data across the analysis window.
Rate-of-change decomposition separates hardware replacement cycles from consumable consumption velocity across product type, application, end user, and technology dimensions. CAGRs derive from segmented procedure volume projections and per-case consumable economics. Forecast inputs incorporate hybrid angiography-CT platform adoption curves and outpatient migration patterns in Germany and Japan.
The model holds under stable reimbursement pathways and regulatory clearance timelines; deviation in FDA software-integrated imaging review durations or niobium-tantalum supply disruptions would shift hardware and consumable demand trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Medical Holography Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
Contrast Media Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Orthopedic Radiology Equipment Market