
 Uterine Fibroid Embolization Devices Market | 2026-2036
Uterine Fibroid Embolization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Uterine Fibroid Embolization Devices Market Analytics
Ambulatory surgical centers is unwinding the historical hospital-centric purchasing pattern for embolization procedures. Siemens Healthineers AG leverages its imaging-integrated angiography suites to dominate the interventional radiology workflow. Boston Scientific Corporation differentiates through specialized microcatheter portfolios calibrated for tortuous uterine vasculature. Merit Medical Systems, Inc. anchors its position via comprehensive embolization kits that reduce procedural setup complexity.
Uterine fibroid embolization devices comprise minimally invasive instruments—microcatheters, embolic coils, and balloon occlusion catheters—delivered through femoral or radial arterial access to occlude uterine artery blood supply, inducing fibroid ischemia and shrinkage without hysterectomy. Fluoroscopy-guided systems currently occupy the largest installed base due to real-time vascular visualization and lower capital requirements, while MRI-guided platforms represent the fastest-growing technology segment as radiation-free soft-tissue targeting attracts academic medical centers. Specialty clinics sustain margin concentration through premium pricing on same-day discharge protocols.
FDA 510(k) premarket notification and EU MDR conformity assessment govern device safety and clinical evidence thresholds, with FDA requiring biocompatibility and mechanical performance data and MDR mandating post-market surveillance systems that extend manufacturer accountability. HIPAA and GDPR frameworks constrain how procedural outcome data flows into commercial registries, complicating real-world evidence strategies. Stakeholders must weigh imaging modality capital commitments against reimbursement velocity as payers scrutinize site-of-service economics.
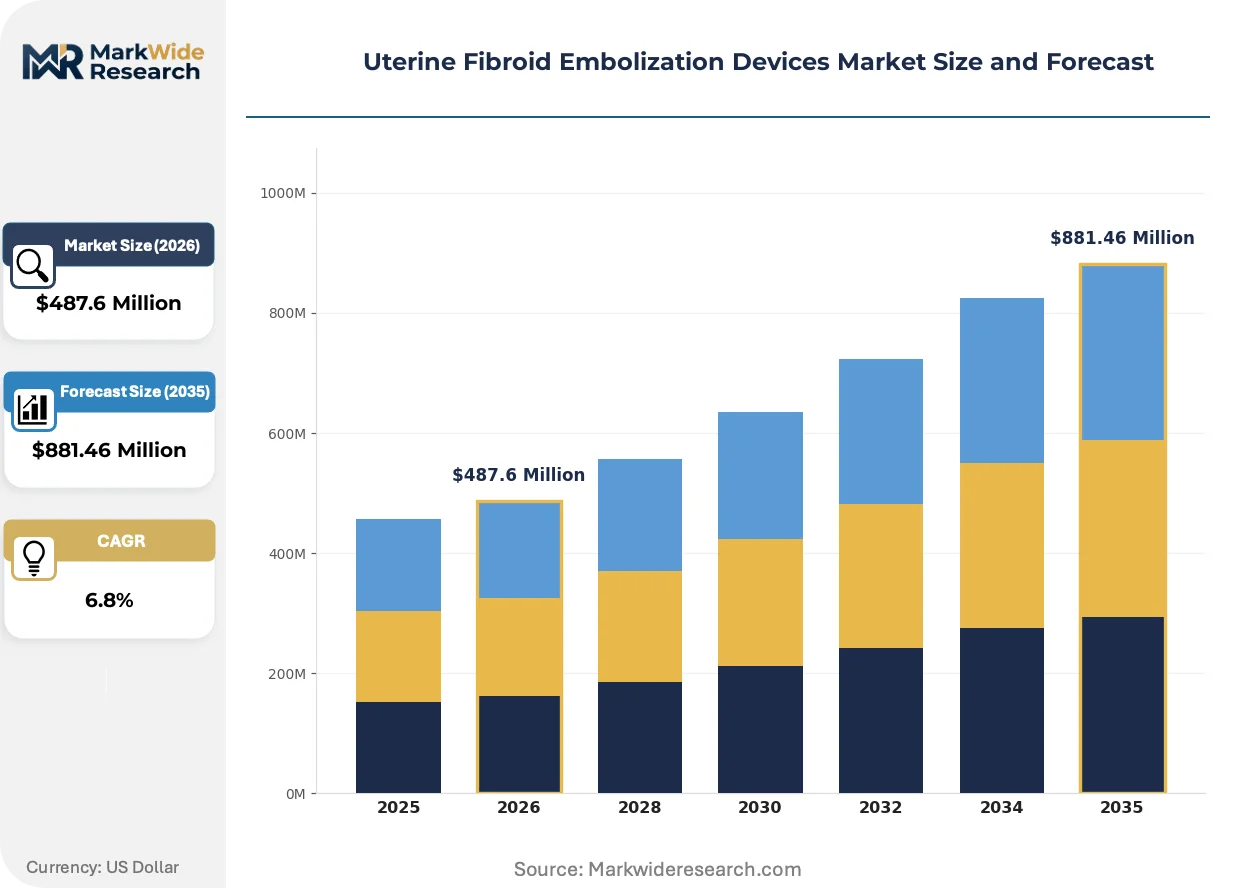
Market Dynamics
Outpatient migration from inpatient hospital settings to ambulatory surgical centers is restructuring capital allocation and purchasing authority across the uterine fibroid embolization value chain. This site-of-service shift compresses procedure economics while elevating throughput and same-day discharge capabilities as decisive vendor selection criteria.
Growth Catalysts
- Commercial Payer Coverage Expansion:United States insurers have broadened uterine artery embolization reimbursement codes, reducing patient out-of-pocket burden and accelerating procedure volume in outpatient settings.
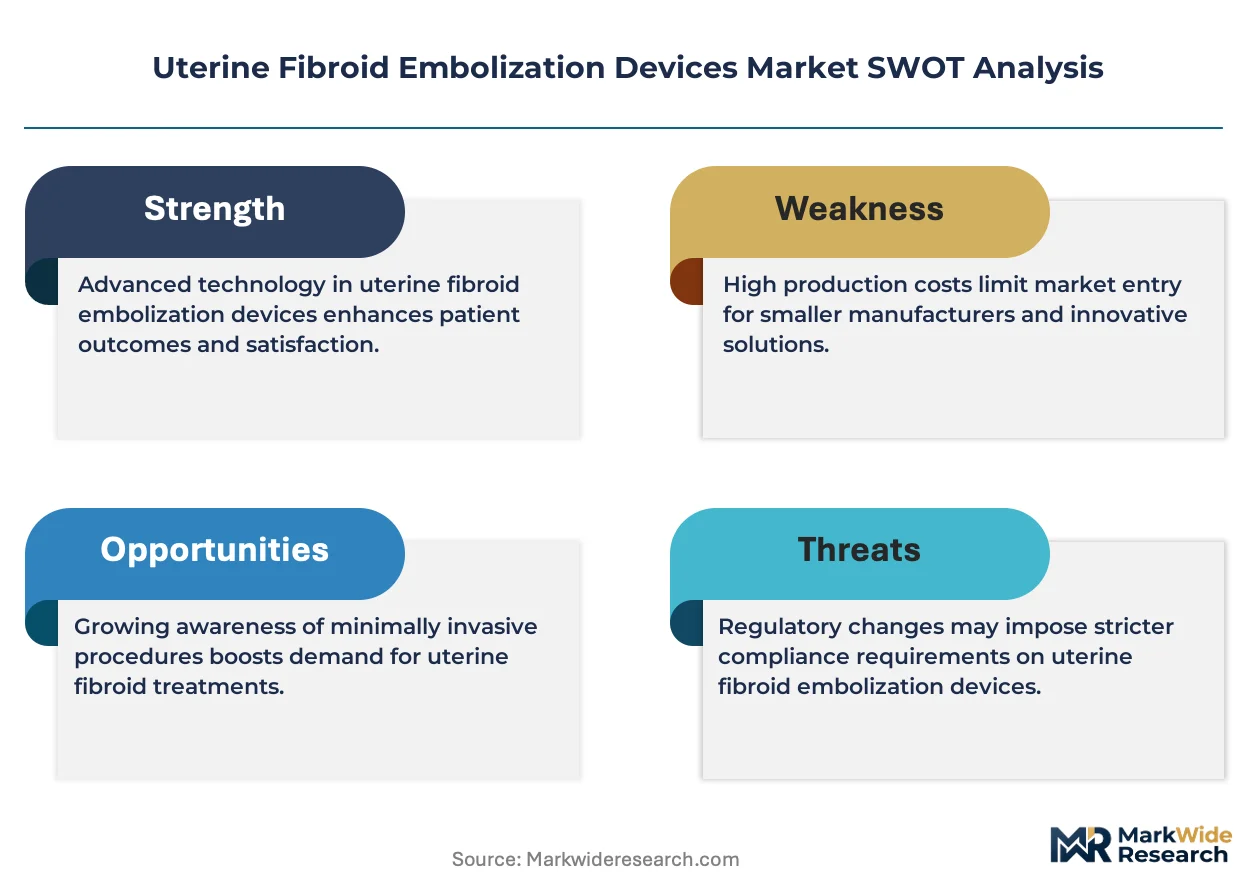
- FDA 510(k) Pathway Efficiency:The premarket notification framework enables faster device clearance compared to PMA routes, compressing time-to-market for microcatheter and embolic innovations.
- Magnetic Resonance Imaging Integration:Radiation-free soft-tissue targeting capabilities are attracting academic medical center investment, differentiating premium service offerings from fluoroscopy-dependent competitors.
Market Restraints
- Polymer Raw Material Concentration:Specialty medical-grade polymers for microcatheter construction concentrate among a limited supplier base in Germany and Japan, exposing manufacturers to input cost volatility and allocation risk.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates extended post-market surveillance systems and PMCF studies, extending conformity assessment timelines and elevating regulatory compliance costs.
- Hysterectomy Substitution Persistence:Gynecologic surgeons in fee-for-service environments continue defaulting to hysterectomy for symptomatic fibroids, limiting interventional radiology penetration despite superior recovery profiles.
Strategic Opportunities
- Radial Artery Access Standardization:Transradial techniques reduce femoral access complications and enable faster ambulation, creating differentiation for device portfolios optimized for smaller-caliber vascular entry.
- HIPAA-Compliant Real-World Evidence Registries:Procedural outcome databases that satisfy privacy frameworks can accelerate payer negotiations and support value-based contracting with integrated delivery networks.
- India Outpatient Infrastructure Buildout:Private hospital chains in Mumbai, Delhi, and Bangalore are investing in interventional radiology suites, opening addressable market expansion for mid-tier device pricing.
Industry Challenges
- Interventional Radiology Workforce Constraints:Fellowship-trained operators capable of complex uterine arterial navigation remain concentrated in tertiary centers, limiting procedure decentralization despite ASC capital investment.
- CE Mark Recertification Complexity:Legacy devices previously cleared under MDD must undergo MDR technical documentation updates, straining quality management system bandwidth and delaying portfolio refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uterine Fibroid Embolization Devices Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Coils, Micro Catheters, Guides End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Fluoroscopy, MRI-guided Systems, CT-guided Systems, Digital Subtraction Angiography Delivery Mode: Transcatheter, Percutaneous, Open Surgical, Laparoscopic |
| Companies Covered | Siemens Healthineers AG, Terumo Medical Corporation, Boston Scientific Corporation, Teleflex, Inc., Hologic, Inc., Medtronic plc, Cook Group, Inc., IMBiotechnologies Ltd., Merit Medical Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uterine Fibroid Embolization Devices Market Evolving Landscape
Technology convergence between imaging modalities and catheter engineering is compressing procedure times while elevating precision targeting. Three developments are materially altering competitive positioning and investment priorities across the sector.
Microcatheter distal tip engineering is miniaturizing to navigate increasingly tortuous uterine arterial branches without vessel spasm or perforation. Academic medical centers in the United States are adopting sub-2.7 French platforms at accelerating cadence. This miniaturization is enabling single-operator procedures and reducing contrast load, compressing equipment requirements for ambulatory surgical center entry.
EU MDR post-market clinical follow-up mandates are extending manufacturer accountability timelines and elevating clinical evidence generation costs. Device sponsors must now maintain active surveillance systems rather than passive vigilance. High-risk embolic categories face the steepest compliance burden, with notified bodies in Germany and the Netherlands extending review cycles.
Site-of-service economics are driving purchasing committee consolidation as health systems centralize procurement across hospital and ambulatory assets. Interventional radiology supply agreements now span multiple care settings under unified vendor contracts. This concentration is most visible in United States integrated delivery networks, where same-day discharge protocols command premium device pricing.
Uterine Fibroid Embolization Devices Market Segmentation
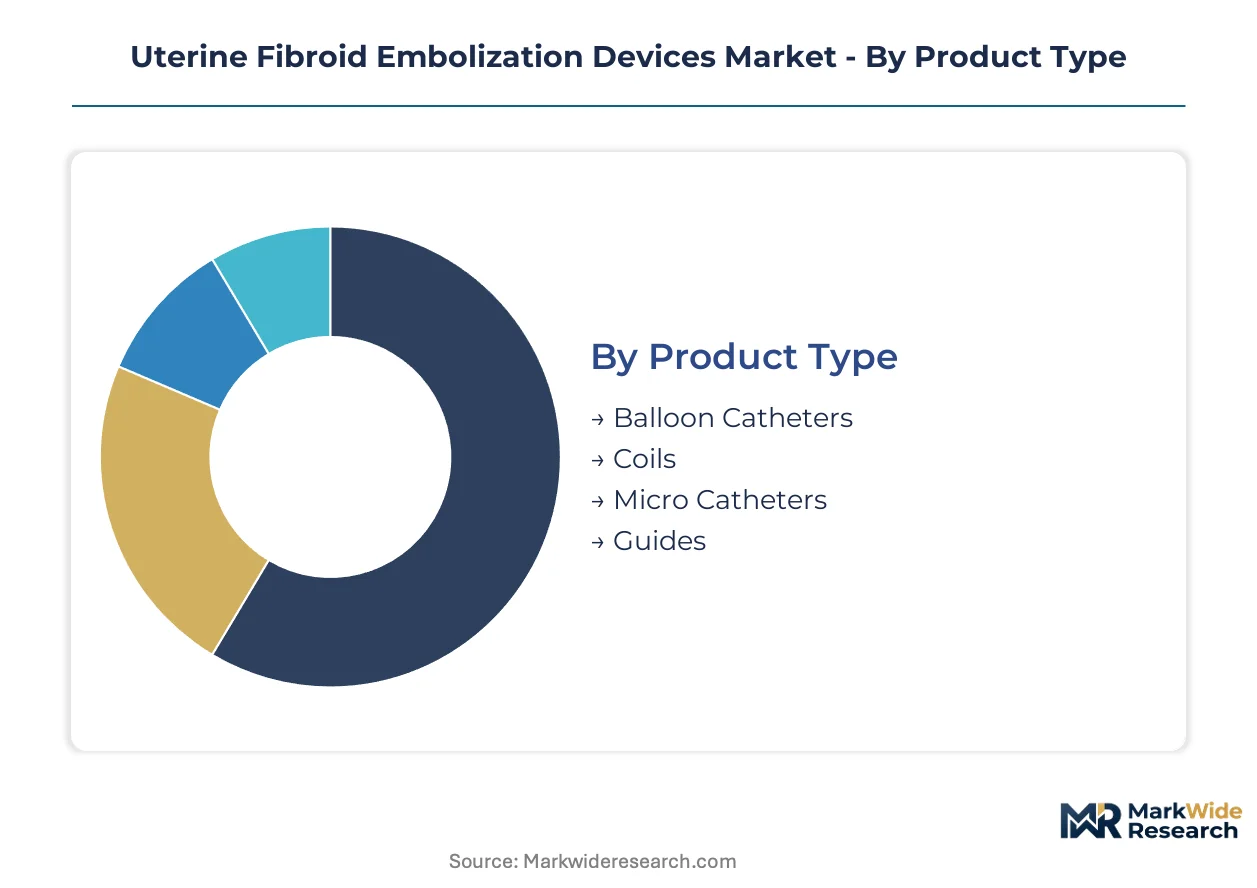
Device segmentation in uterine fibroid embolization tracks how procedural economics, imaging modality preferences, and site-of-service migration reshape purchasing authority across interventional radiology supply chains. Category boundaries increasingly blur as manufacturers bundle microcatheter-embolic combinations and imaging-integrated platforms to capture ambulatory surgical center procurement committees.
Product Type:
Microcatheters and embolic agents flow through distinct channel architectures—tertiary hospitals demand comprehensive portfolios while ambulatory surgical centers prioritize compact kits with reduced setup complexity.
- Micro Catheters:Distal tip engineering now reaches sub-2.7 French profiles enabling single-operator navigation through tortuous uterine arterial branches. United States academic medical centers are driving adoption of hydrophilic-coated platforms that reduce vessel spasm incidence during prolonged procedures.
- Coils:Pushable and detachable variants provide permanent mechanical occlusion of feeding arteries, with platinum-tungsten alloys dominating premium pricing tiers. German and Japanese polymer suppliers constrain input availability for specialized coil delivery systems, elevating manufacturing allocation risk.
- Balloon Catheters:Temporary occlusion platforms enable controlled embolic injection with reflux prevention, particularly valued in complex bilateral uterine artery anatomy.
- Guides:Selective catheter shapes including Roberts, Cobra, and Simmons configurations provide proximal access support for distal microcatheter advancement.
Micro Catheters dominate installed base. Coils represent where expansion concentrates.
End User:
Procurement authority is migrating from hospital materials management to ambulatory surgical center physician-owners who prioritize throughput economics over capital intensity.
- Ambulatory Surgical Centers:Outpatient migration has compressed procedure economics while elevating same-day discharge capabilities as decisive vendor selection criteria. United States integrated delivery networks now centralize supply agreements across hospital and ambulatory assets under unified contracts.
- Hospitals:Tertiary centers retain complex case referrals and fellowship training programs, sustaining demand for full imaging-integrated angiography suites. MRI-guided procedure volume concentrates at academic institutions with radiation-free soft-tissue targeting capabilities.
- Specialty Clinics:Gynecology-focused practices in fee-for-service environments capture margin through premium pricing on concierge access and reduced wait times.
- Research Institutes:Clinical trial sponsors and post-market surveillance obligations under EU MDR drive device evaluation partnerships with academic medical centers in the Netherlands and Germany.
Hospitals retain procedure volume leadership. Ambulatory Surgical Centers are climbing the fastest.
Technology:
Capital commitment thresholds and reimbursement velocity determine imaging modality penetration across customer tiers.
- Fluoroscopy:Real-time vascular visualization with lower capital requirements sustains broad installed base across community hospitals and emerging markets. C-arm mobility enables hybrid operating room configurations that serve multiple service lines.
- MRI-guided Systems:Radiation-free soft-tissue targeting attracts academic medical center investment for complex fibroid mapping, though extended procedure times constrain throughput economics.
- Digital Subtraction Angiography:High-resolution vascular roadmap generation supports complex arterial reconstructions, particularly in post-surgical anatomy with collateral vessel development.
- CT-guided Systems:Cross-sectional imaging provides pre-procedural planning and post-embolization assessment, with cone-beam CT integration emerging in hybrid angiography suites.
Fluoroscopy commands broadest deployment. MRI-guided Systems represent steepest expansion trajectory.
Delivery Mode:
Vascular access site selection is reshaping device portfolio requirements as transradial techniques gain procedural share.
- Transcatheter:Femoral and radial arterial access routes deliver microcatheters to uterine artery origins, with radial approaches enabling faster ambulation and reduced access site complications. Device manufacturers are optimizing catheter lengths and torque response for smaller-caliber radial sheath compatibility.
- Percutaneous:Direct puncture techniques serve salvage scenarios when arterial access fails, though limited adoption reflects operator training concentration.
- Laparoscopic:Hybrid surgical-interventional approaches address concomitant pathology, with temporary arterial occlusion preceding myomectomy in selected cases.
- Open Surgical:Direct uterine artery ligation persists in resource-constrained settings without interventional radiology infrastructure.
Transcatheter delivery dominates procedural volume. Transradial refinement within this category is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate purchasing authority for uterine fibroid embolization devices, while academic medical centers in Germany and Japan anchor premium technology adoption. Private hospital chains in India and outpatient clinics in Brazil represent emerging volume centers as interventional radiology infrastructure expands.
United States
Commercial payers including UnitedHealthcare and Anthem have broadened uterine artery embolization reimbursement codes, reducing patient cost barriers and accelerating ambulatory surgical center volume. FDA 510(k) clearance pathways enable faster device introductions compared to PMA routes. The Cleveland Clinic and Mayo Clinic anchor MRI-guided procedure adoption in academic settings.
Germany
Notified bodies under EU MDR extend conformity assessment timelines for high-risk embolic devices, elevating clinical evidence requirements for market access. The country's statutory health insurance system maintains favorable reimbursement for minimally invasive gynecologic interventions. Berlin and Munich academic hospitals concentrate post-market clinical follow-up studies mandated by MDR Article 74.
Japan
PMDA marketing authorization pathways for embolization devices emphasize biocompatibility data and mechanical performance validation. The aging demographic sustains demand for uterine-sparing alternatives to hysterectomy. Tokyo and Osaka metropolitan areas concentrate fellowship-trained interventional radiologists capable of complex arterial navigation.
India
Private hospital chains including Apollo and Fortis are investing in interventional radiology suites across Mumbai, Delhi, and Bangalore. CDSCO medical device rules govern import licensing and quality standards for embolization catheters. Mid-tier device pricing strategies target outpatient infrastructure buildout in tier-1 cities.
Brazil
ANVISA medical device registration requirements shape import timelines for embolization portfolios. The public SUS system and private insurance segments sustain parallel demand channels. São Paulo and Rio de Janeiro concentrate specialized gynecologic interventional practices serving symptomatic fibroid patients.
Uterine Fibroid Embolization Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with imaging-integrated angiography platforms and specialized interventional radiology device manufacturers with focused embolization portfolios. Strategic archetypes include capital equipment-integrated workflow providers, comprehensive kit suppliers reducing procedural complexity, and distal access specialists optimizing for tortuous vasculature. Dominant competitive moves encompass strategic partnerships between device and imaging manufacturers and geographic expansion through distributor networks in emerging outpatient markets.
Within the diversified conglomerate tier, Siemens Healthineers AG and Boston Scientific Corporation exemplify contrasting positioning archetypes. Siemens Healthineers occupies a position anchored in imaging-integrated angiography suites that dominate interventional radiology workflow capture. Boston Scientific Corporation represents the specialized portfolio approach, with microcatheter engineering calibrated for challenging uterine arterial anatomy. Merit Medical Systems, Inc. sits within the comprehensive kit supplier archetype, reducing procedural setup burden for ambulatory surgical center environments.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Terumo Medical Corporation |
| Boston Scientific Corporation |
| Teleflex, Inc. |
| Hologic, Inc. |
| Medtronic plc |
| Cook Group, Inc. |
| IMBiotechnologies Ltd. |
| Merit Medical Systems, Inc. |
| Others |
Value Network & Pricing Analysis
Polymer substitution from conventional nylon to hydrophilic-coated Pebax in microcatheter construction is simultaneously shifting procurement geography toward German and Japanese specialty resin suppliers while compressing margin structures for device manufacturers locked into fixed-price hospital contracts. This material transition elevates input costs by fifteen to twenty percent while payers resist procedure reimbursement adjustments, squeezing profitability across the embolization device value chain.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate procurement agreements between device manufacturers and ambulatory surgical center chains, insulating suppliers from raw material volatility while capping upside capture. Three-tier pricing structure across premium hydrophilic platforms, standard nylon configurations, and economy bare-metal variants separates academic medical centers from community hospitals from price-sensitive outpatient clinics. Pricing pressure stems from integrated delivery network consolidation that centralizes purchasing authority across multiple sites under single vendor contracts. Ambulatory surgical centers exhibit highest price sensitivity due to compressed procedure economics, while tertiary academic centers absorb premium pricing for MRI-compatible platforms.
Supply Chain Analysis
Just-in-time inventory strategies predominate among US device manufacturers, though EU MDR post-market surveillance obligations are forcing strategic stockpiling of embolic agents to ensure continuity during notified body review delays. Geographic supply concentration centers on Germany for specialty polymer extrusion, Japan for platinum-tungsten alloy wire drawing, and the United States for final device assembly and sterilization. Raw material dependencies include medical-grade Pebax elastomers, radiopaque filler compounds, and hydrophilic coating polymers. Single-source vulnerability in German polymer supply exposes manufacturers to allocation risk during capacity constraints. Distribution runs through specialized interventional radiology distributors serving hospital and ambulatory channels with consignment inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where FDA 510(k) clearance pathways and EU MDR conformity assessments create multi-year barriers to competitive entry that protect incumbent positioning.
For Market Incumbents: Compound switching cost advantages by embedding proprietary microcatheter designs into imaging-integrated angiography workflows that lock hospital systems into unified vendor ecosystems. Deepen backward integration into hydrophilic coating polymer production to insulate margins from German supplier concentration. Accelerate CE Mark recertification under MDR Article 74 ahead of legacy MDD certificate expiration to capture competitor shelf-life gaps.
For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-track pathways offer accelerated market access for radiation-free MRI-guided embolization platforms targeting academic medical centers underserved by fluoroscopy-dependent incumbents. White-space concentration exists in transradial-optimized microcatheter portfolios for ambulatory surgical centers seeking same-day discharge protocols. India outpatient infrastructure buildout in Mumbai, Delhi, and Bangalore presents geographic entry point through mid-tier pricing strategies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed interventional radiology device specialists possessing MDR-compliant quality management systems but constrained distribution reach outside core European markets. Five-to-ten year viability hinges on reimbursement velocity for outpatient uterine artery embolization procedures outpacing hysterectomy substitution persistence. Monitor commercial payer coverage expansion signals from UnitedHealthcare and Anthem as inflection indicators for ambulatory surgical center volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 74 compliance unlocks European ambulatory surgical center procurement committees. |
| Hospital System Partnership | Integrated delivery network contracts consolidate purchasing authority across hospital and outpatient assets. |
| Reimbursement Strategy | Commercial payer coverage expansion reduces patient out-of-pocket burden and accelerates procedure volume. |
| Software Companion Development | HIPAA-compliant real-world evidence registries support value-based contracting with payers. |
| Radial Access Portfolio Optimization | Transradial techniques enable faster ambulation and differentiate device offerings for outpatient settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center physician-owners. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, hospital procurement databases, and commercial payer coverage policy filings. Bottom-up procedure volume estimates were triangulated against top-down device shipment data to reconcile market sizing.
Across the analysis window, forecasts were derived from segmented modeling across product type, end user, technology, and delivery mode dimensions. CAGRs were computed from annualized growth trajectories calibrated to historical reimbursement velocity and site-of-service migration patterns. Industry-specific inputs included interventional radiology fellowship training pipeline capacity, EU MDR notified body review cycle durations, and commercial payer coverage expansion timelines.
Underlying assumptions cover sustained outpatient migration from inpatient settings, stable polymer raw material supply from German and Japanese suppliers, and continued commercial payer coverage broadening, with deviation risk concentrated in EU MDR recertification delays and interventional radiology workforce constraints. Revision becomes warranted when ambulatory surgical center reimbursement rates cross downward adjustment thresholds or polymer allocation constraints trigger sustained input cost spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
General Surgical Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Spherical IOL Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Medical Manifolds Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Global Venous Blood Collection Devices Market