
 United States Computed Tomography Market | 2026-2036
United States Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
United States Computed Tomography Market Analytics
Hospital procurement priorities is shifting toward outpatient imaging centers and diagnostic clinics as health systems decentralize diagnostic capacity. GE Healthcare leverages its installed base of multi-slice systems to sustain service revenue streams across integrated delivery networks. Siemens Healthineers anchors its position through R&D intensity in photon-counting detector technology. Canon Medical Systems Corporation specializes in compact system designs that compete for ambulatory surgical center placements.
Computed tomography denotes an X-ray-based cross-sectional imaging modality utilizing rotating gantry architectures with detector arrays capturing attenuation data for tomographic reconstruction, typically operating at tube voltages between 80 and 140 kVp. Multi-slice CT dominates current installed value due to throughput requirements in emergency and trauma settings, while AI-enhanced imaging represents the fastest-growing technology segment as reconstruction speed and dose reduction become purchasing criteria. Dual-energy CT occupies premium price tiers where material differentiation drives oncology and cardiovascular application demand.
FDA premarket notification pathways govern system clearance, while CMS reimbursement codes directly shape hospital capital allocation cycles for CT replacement and expansion. The National Electrical Manufacturers Association XR-29 standard constrains dose reporting capabilities, filtering vendor competition toward compliant platform architectures. Stakeholders must monitor artificial intelligence validation requirements and site-of-care reimbursement shifts to align portfolio investments with evolving clinical economics.
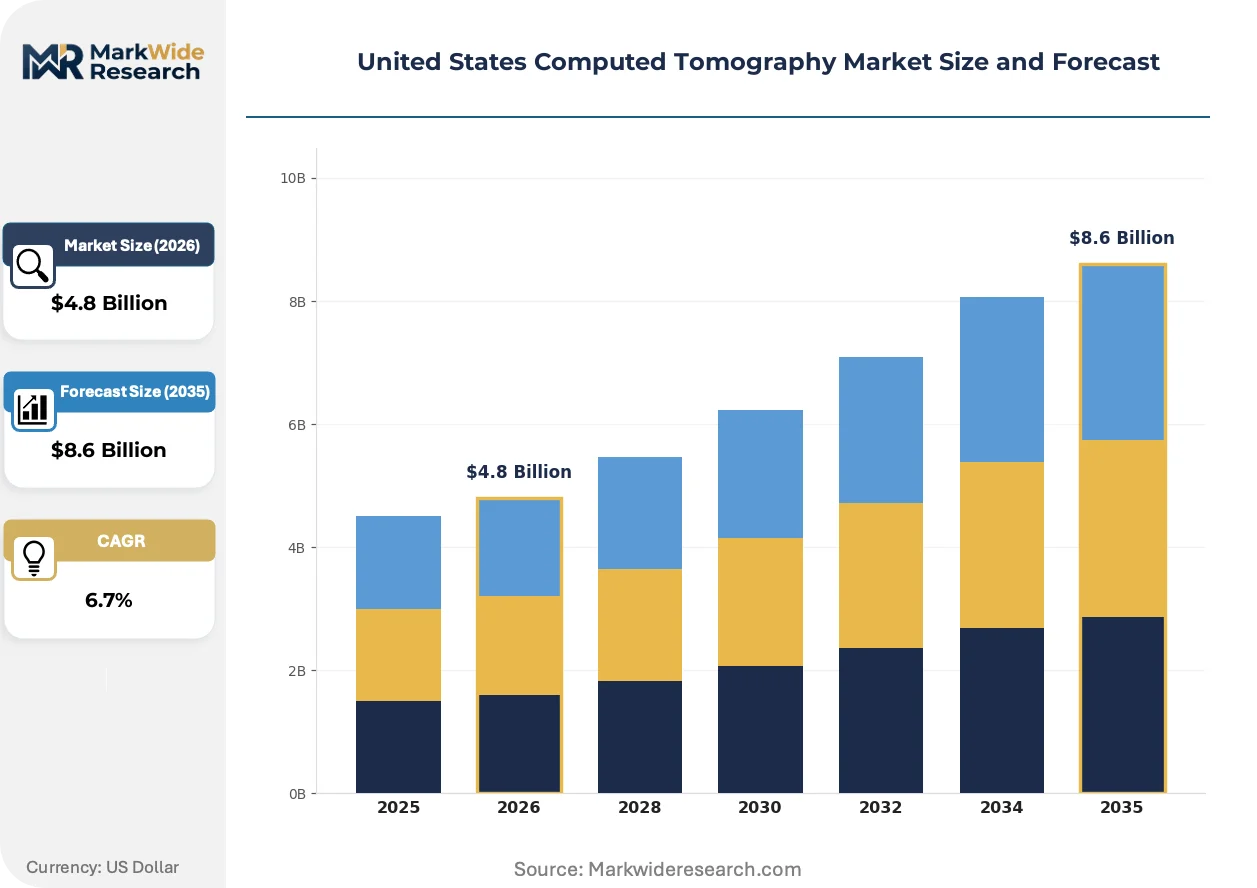
Market Dynamics
AI-enhanced reconstruction algorithms are redrawing competitive boundaries as FDA clearance pathways accelerate vendor differentiation around dose reduction and imaging speed. Hospital capital allocation cycles now hinge on CMS reimbursement code alignment, compressing replacement timelines for legacy systems.
Growth Catalysts
- Outpatient imaging centers:Care decentralization is accelerating capital deployment into ambulatory diagnostic capacity across integrated delivery networks.
- CMS reimbursement codes:Favorable site-of-care payment differentials are pulling CT procurement toward freestanding facilities.
- Photon-counting detector technology:Material differentiation capabilities in oncology and cardiovascular applications are commanding premium placement in academic medical centers.
Market Restraints
- Detector material supply concentration:Scintillator crystal sourcing from limited qualified vendors creates input vulnerability for gantry manufacturers.
- FDA premarket notification timelines:AI algorithm validation requirements are extending clearance cycles for iterative reconstruction software.
- Substitution from MRI:Magnetic resonance imaging advances in soft-tissue contrast are displacing CT in certain neurological and musculoskeletal protocols.
Strategic Opportunities
- Southeastern United States:Hospital network expansion converging with aging demographics is concentrating replacement demand in Florida, Georgia, and North Carolina.
- Dual-energy CT:Material decomposition capabilities in iodine quantification and uric acid detection are opening premium service lines in nephrology and urology.
- XR-29 dose reporting compliance:The National Electrical Manufacturers Association standard is creating upgrade pull-through for non-compliant installed base systems.
Industry Challenges
- Medical physicist staffing:Qualified personnel for CT protocol optimization and dose monitoring are scarce in rural and community hospital settings.
- Legacy PACS integration:AI-enhanced systems require costly middleware development to interface with decade-old picture archiving infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Computed Tomography Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cone Beam CT, Multi-Slice CT, Dual-Energy CT, Positron Emission Tomography End User: Hospitals, Diagnostic Clinics, Research Laboratories, Outpatient Imaging Centers Technology: Analog Technology, Digital Technology, AI-Enhanced Imaging, Portable CT Scanners Application: Oncology, Neurology, Cardiovascular, Orthopedics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, United Imaging Healthcare, Carestream Health, Neusoft Corporation, Hitachi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Computed Tomography Market Evolving Landscape
Computed tomography hardware architectures are fragmenting as vendors pursue divergent paths through detector physics, gantry mobility, and software-defined imaging pipelines. Three trajectories are commanding R&D investment and reshaping buyer evaluation criteria.
Photon-counting CT is modularizing system design by replacing energy-integrating detectors with direct-conversion semiconductors that register individual photon energies. Academic medical centers and specialty cardiac hospitals are piloting these platforms for coronary plaque characterization. The technology is modularizing the traditional trade-off between spatial resolution and dose efficiency, enabling sub-millimeter imaging at reduced exposure levels.
FDA premarket notification pathways for AI-enhanced reconstruction are compressing product development timelines for vendors with established quality management systems. The industrial consequence is a bifurcation between algorithm-native platforms and retrofit software offerings. Emergency and trauma settings are most affected, as reconstruction speed directly impacts throughput in high-volume departments.
Service contract unbundling is fragmenting the traditional bundled maintenance model as health systems seek granular control over parts, labor, and software update costs. Independent service organizations are capturing slice count-based maintenance agreements previously held by OEMs. This pattern is most visible in the southeastern United States, where IDN consolidation has concentrated bargaining power among fewer procurement decision-makers.
United States Computed Tomography Market Segmentation
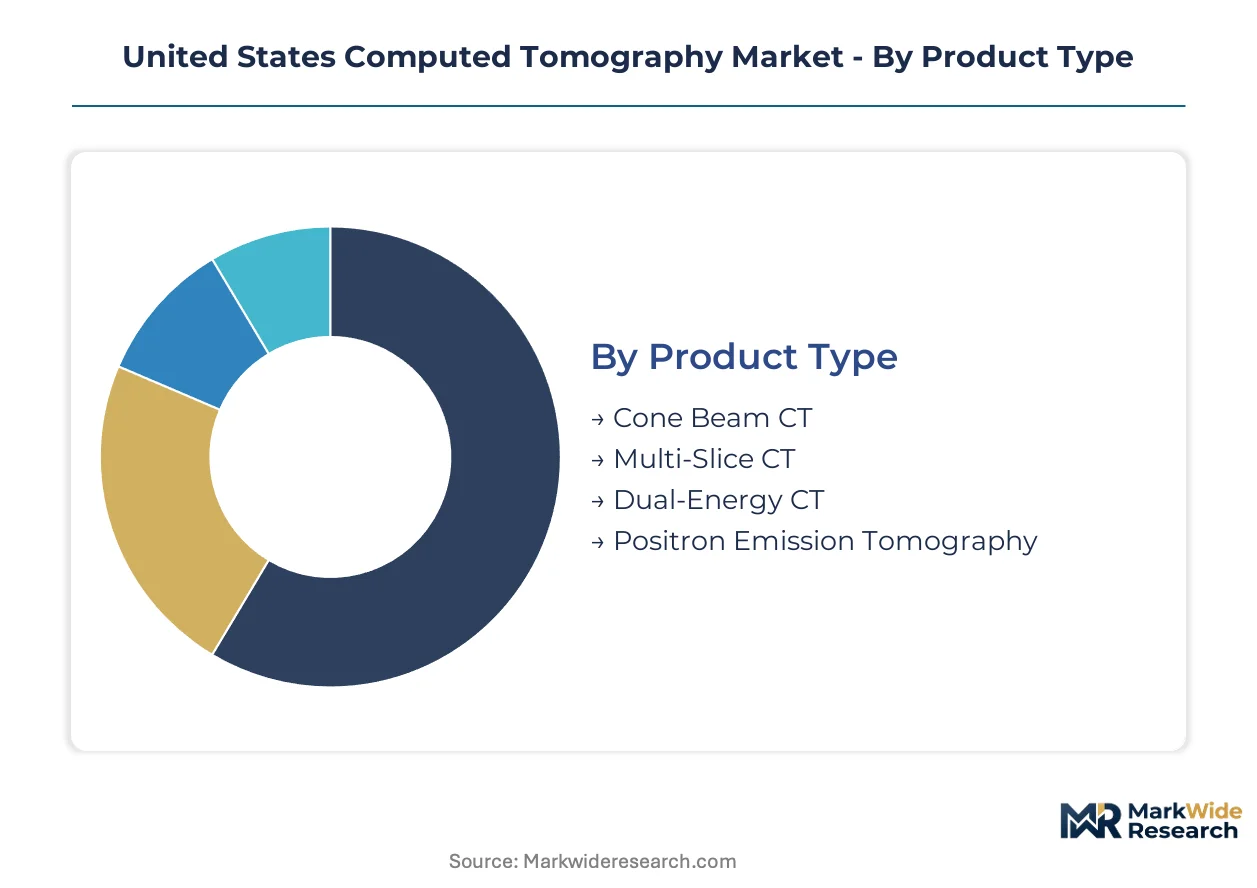
Computed tomography procurement decisions in the United States diverge sharply across care settings, with site-of-care reimbursement differentials and throughput requirements driving distinct equipment specifications. Hospital networks evaluate systems against emergency department volume targets, while ambulatory operators prioritize compact footprints and favorable CMS coding alignment.
Product Type:
Capital allocation cycles favor throughput density in high-volume settings and material differentiation in specialty referral centers.
- Multi-Slice CT:Systems deploy 64 to 320 detector rows for sub-second whole-body coverage, with tube ratings exceeding 80 kW for trauma throughput. Demand concentrates in southeastern hospital networks where emergency department expansion and aging demographics converge on replacement cycles.
- Dual-Energy CT:Spectral separation at 80 and 140 kVp enables iodine quantification and virtual non-contrast imaging for renal mass characterization. Academic medical centers in Florida and Georgia command premium placement for oncology and urology service lines.
- Cone Beam CT:Flat-panel detectors capture volumetric data at reduced dose for maxillofacial and extremity imaging. Dental schools and oral surgery centers in Texas and California anchor installed base concentration.
- Positron Emission Tomography:Hybrid PET/CT systems fuse metabolic and anatomical data for oncology staging. National Cancer Institute-designated centers drive procurement for clinical trial eligibility.
Volume sits with Multi-Slice CT; growth tilts toward Dual-Energy CT.
End User:
Site-of-care economics reshape buyer concentration as reimbursement differentials pull capital toward freestanding facilities.
- Outpatient Imaging Centers:Freestanding facilities capture favorable CMS payment rates for non-hospital settings, driving de novo construction across integrated delivery networks. Georgia and North Carolina health systems deploy compact systems for ambulatory diagnostic capacity.
- Hospitals:Emergency and trauma departments require 24/7 operational readiness with sub-minute reconstruction speeds. IDN consolidation in the Southeast concentrates bargaining power among fewer procurement committees.
- Diagnostic Clinics:Physician-owned imaging practices prioritize lease financing and shared service arrangements for mid-tier slice counts. Rural access programs in Appalachia subsidize placement in underserved counties.
- Research Laboratories:National Institutes of Health-funded institutions acquire photon-counting prototypes for coronary plaque characterization studies. FDA investigational device exemption pathways govern pre-commercial deployment.
Revenue concentration remains with Hospitals; expansion velocity favors Outpatient Imaging Centers.
Technology:
Reconstruction pipeline architecture determines competitive positioning as FDA clearance pathways accelerate for algorithm-native platforms.
- AI-Enhanced Imaging:Deep learning reconstruction reduces noise at equivalent dose levels or enables dose reduction at matched image quality. Emergency departments in high-volume academic centers pilot FDA-cleared iterative algorithms for throughput gains.
- Digital Technology:Solid-state detectors with direct conversion electronics replace analog signal chains for improved dynamic range. Community hospitals in the Midwest upgrade from 16-slice analog systems for XR-29 compliance.
- Portable CT Scanners:Self-contained gantry units with battery power deploy to intensive care units and operating suites for intraoperative imaging. Stroke network certification requirements in Florida drive mobile unit placement.
- Analog Technology:Legacy energy-integrating detectors with photodiode-scintillator stacks persist in installed base systems approaching end-of-service life. Replacement demand concentrates where maintenance parts scarcity accelerates decommissioning.
Installed value clusters in Digital Technology; steepest expansion trajectory belongs to AI-Enhanced Imaging.
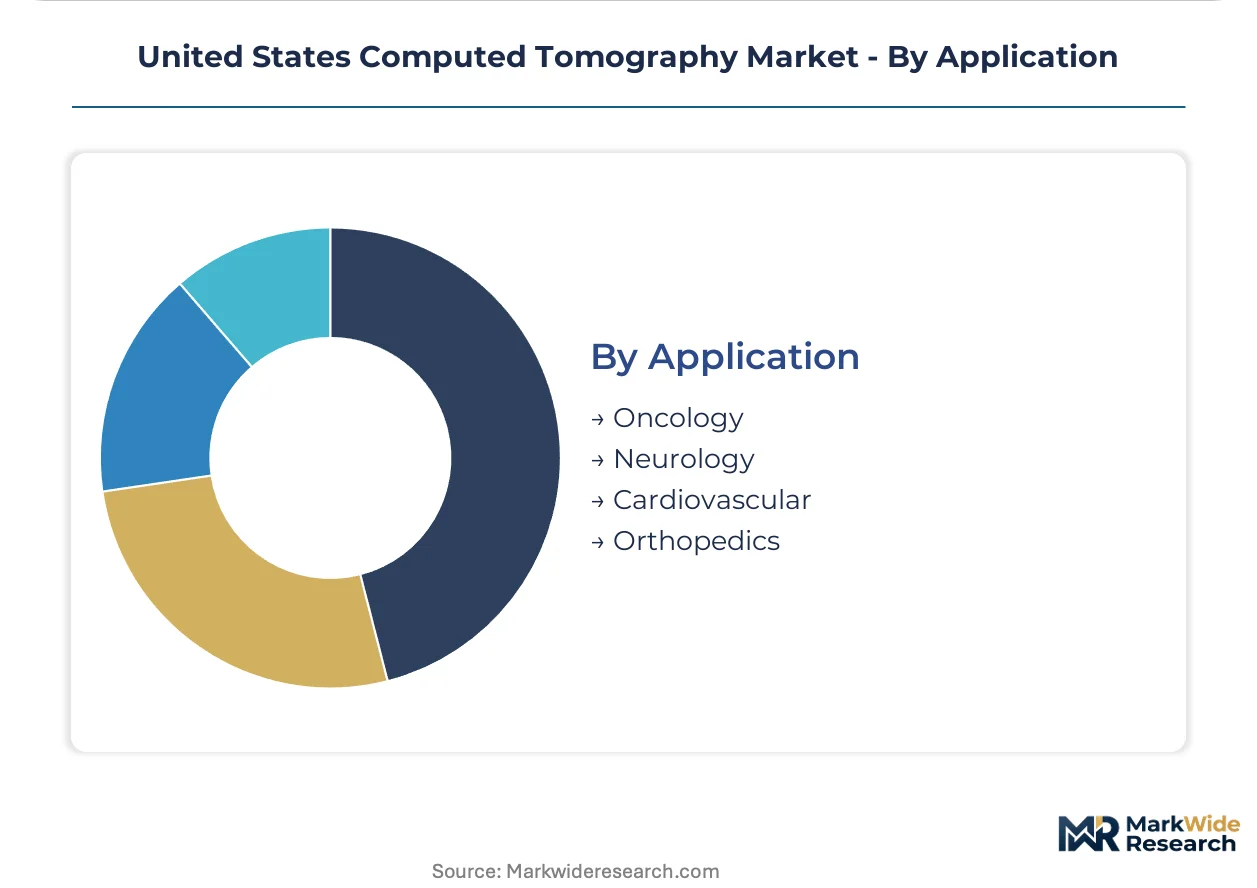
Application:
Clinical indication drives detector specification and contrast protocol design across referral patterns.
- Oncology:Staging and treatment response assessment require multi-phase contrast protocols with low-dose surveillance capabilities. NCI-designated cancer centers in the Southeast anchor demand for spectral imaging.
- Cardiovascular:Coronary CT angiography demands sub-millimeter spatial resolution and robust heart rate control for diagnostic image quality. Cardiac hospitals in Texas and Florida lead photon-counting pilot programs.
- Neurology:Perfusion imaging for stroke triage prioritizes rapid acquisition and automated processing for door-to-needle time targets. Comprehensive stroke centers drive 24/7 coverage requirements.
- Orthopedics:Metal artifact reduction algorithms enable post-arthroplasty evaluation and trauma hardware assessment. Ambulatory surgery centers prioritize weight-bearing extremity protocols.
Procedure volume concentrates in Oncology; cardiovascular applications gain share fastest through preventive imaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network expansion zones in the southeastern United States concentrate CT procurement demand through tax-advantaged healthcare facility development programs. Aging demographics and integrated delivery network consolidation amplify replacement cycles across Florida, Georgia, and North Carolina corridors.
Southeastern United States
Florida hospital networks deploy multi-slice systems for emergency department throughput targets tied to stroke center certification requirements. CMS site-of-care payment differentials pull capital toward freestanding imaging facilities in Georgia and North Carolina. Academic medical centers in Atlanta and Miami pilot photon-counting detector platforms for cardiac plaque characterization studies.
Texas
Comprehensive stroke center designation requirements drive 24/7 CT coverage mandates across Dallas-Fort Worth and Houston metropolitan clusters. Rural access programs subsidize compact system placement in underserved counties along the Rio Grande Valley. Cardiac hospitals in San Antonio lead coronary CT angiography service line development.
California
National Cancer Institute-designated centers in Los Angeles and San Francisco anchor hybrid PET/CT procurement for clinical trial eligibility. Ambulatory surgery centers in Orange County prioritize cone beam CT for maxillofacial protocols. FDA investigational device exemption pathways govern photon-counting prototype deployment at Stanford and UCLA research laboratories.
Midwest
Community hospitals in Illinois and Ohio upgrade from legacy 16-slice analog systems to achieve XR-29 dose reporting compliance. Independent service organizations capture maintenance agreements previously held by OEMs across Michigan health system consolidations. Diagnostic clinics in Wisconsin emphasize lease financing structures for mid-tier slice count deployments.
Northeast Corridor
Research laboratories in Massachusetts and New York acquire AI-enhanced reconstruction platforms through NIH-funded instrumentation grants. Outpatient imaging center construction accelerates in Philadelphia suburbs driven by favorable reimbursement geography. Legacy PACS integration challenges concentrate middleware development demand in Boston and New York metropolitan networks.
United States Computed Tomography Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with installed base service revenue anchoring incumbent positions while compact system specialists penetrate ambulatory channels. The vendor landscape organizes around three archetypes: full-platform OEMs with multi-modality portfolios, detector-technology specialists pursuing premium spectral imaging tiers, and regional challengers competing on acquisition cost. M&A activity concentrates on AI algorithm developers and independent service organizations, while R&D partnerships target photon-counting detector commercialization timelines.
Among the full-platform OEM tier, GE Healthcare and Siemens Healthineers exemplify archetypes leveraging installed base scale to sustain service contract pricing power across integrated delivery networks. Canon Medical Systems Corporation occupies a position within the compact system specialization vector, representing the archetype of footprint-optimized designs targeting ambulatory surgical center placements. These three anchors illustrate how vendor strategy fragments across detector physics, gantry mobility, and software-defined imaging pipeline investments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| United Imaging Healthcare |
| Carestream Health |
| Neusoft Corporation |
| Hitachi |
| Others |
Value Network & Pricing Analysis
Integrated delivery network procurement committees in the southeastern United States anchor contract-based pricing power for CT system OEMs, with multi-year service bundling and slice-count tiering defining the dominant commercial structure. Their consolidated bargaining position compresses margins on hardware while extending revenue visibility through captive maintenance agreements.
Pricing Analysis
Short lead-time premiums command substantial markups for emergency replacement deployments, while spot inventory from independent service organizations trades at discounts to OEM list prices. Three-tier pricing structure across premium photon-counting systems, standard multi-slice configurations, and economy refurbished platforms segments buyer budgets. Pricing pressure stems from independent service organization capture of maintenance agreements previously held by OEMs. Community hospitals in rural settings exhibit highest price sensitivity due to capital constraint, while academic medical centers prioritize material differentiation over acquisition cost.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act reshape sourcing for federally funded hospital construction projects, pushing gantry assembly toward US-based contract manufacturers. Scintillator crystal supply concentrates in Japan and Germany, with cadmium zinc telluride semiconductor substrates sourced from US and Israeli specialty foundries. Detector module assembly hinges on rare earth phosphor availability from Chinese processors. Single-source vulnerability in photon-counting detector substrates creates qualification bottlenecks for next-generation platforms. Distribution runs through manufacturer-direct sales teams for hospital networks and regional distributors for ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
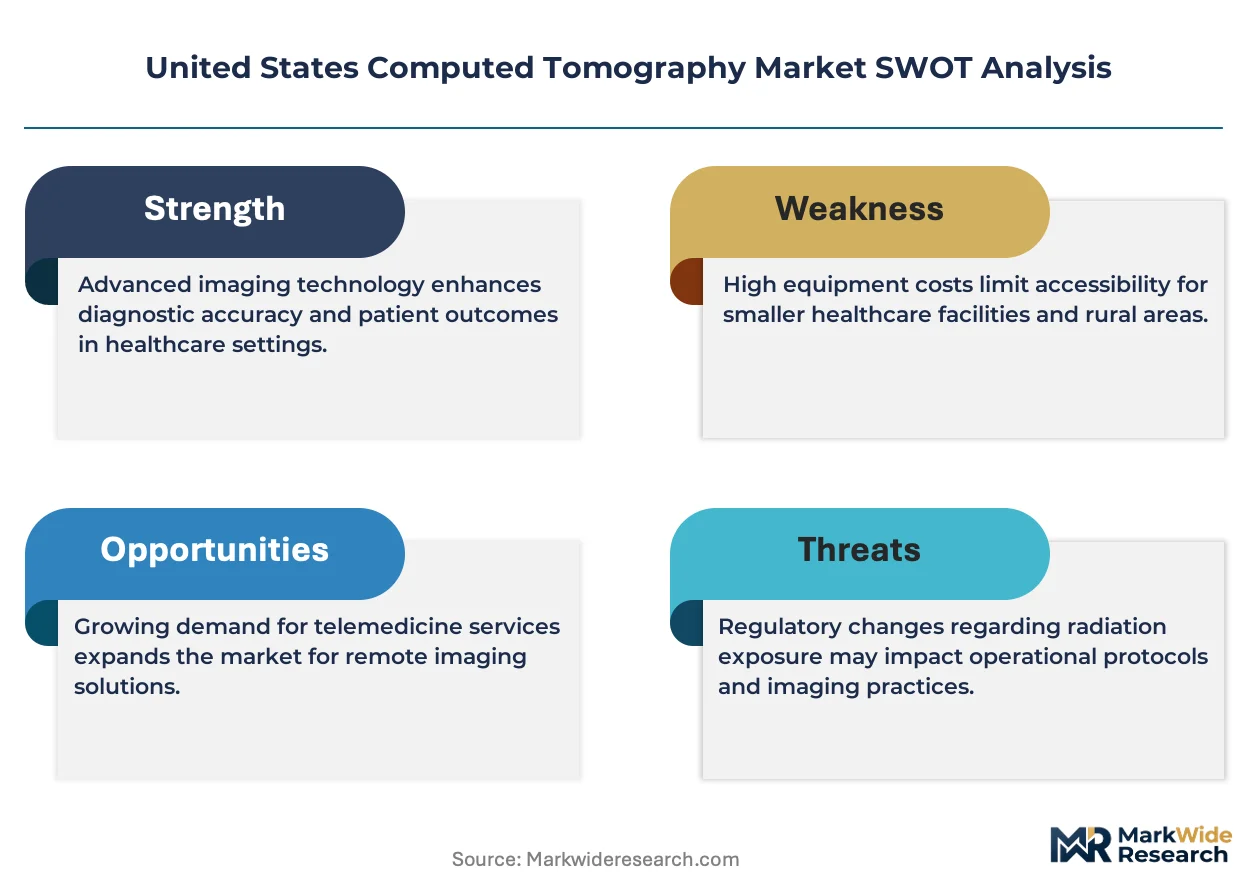
The United States CT market operates as a cost-of-compliance story where FDA premarket notification pathways and XR-29 dose reporting standards erect regulatory moats that favor established quality management systems over new entrants.
For Market Incumbents: Deepen photon-counting detector R&D partnerships to secure premium placement in academic medical centers before technology commoditization. Lock in exclusive scintillator supply agreements to neutralize independent service organization parts arbitrage. Consolidate service contract pricing power across IDN footprints in Georgia and North Carolina where procurement committee concentration is highest.
For New Entrants and Emerging Players: AI-native reconstruction algorithms offer a technology-first wedge into emergency department throughput optimization, bypassing hardware manufacturing scale requirements. Target outpatient imaging centers in Florida and Texas where favorable CMS site-of-care differentials accelerate de novo construction. Pursue software-only FDA clearance pathways to compress time-to-revenue versus full system platforms.
For Investors and Strategic Acquirers: The window for entry favors independent service organizations with slice-count-based maintenance expertise and AI algorithm developers with FDA-cleared iterative reconstruction platforms. Long-term viability rests on reimbursement policy continuity and photon-counting commercialization timelines. Watch CMS site-of-care payment rulemaking as the critical inflection signal for capital allocation toward freestanding versus hospital-based capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enhanced Reconstruction | Accelerates clearance timelines for algorithm-native platforms in emergency settings. |
| Hospital System Partnership | Locks in multi-year service revenue across IDN consolidation zones in the Southeast. |
| Photon-Counting Detector Commercialization | Commands premium placement in cardiac and oncology service lines. |
| Reimbursement Strategy Alignment | Captures favorable CMS coding for outpatient imaging center construction. |
| Software Companion Development | Enables legacy PACS integration without costly middleware for community hospitals. |
Research Methodology
Document review covered FDA 510(k) clearance databases, CMS reimbursement rulemaking dockets, and NEMA XR-29 compliance registries, complemented by interviews with hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and independent service organization executives. Secondary validation drew from SEC filings of publicly traded OEMs, hospital capital expenditure disclosures, and trade data on scintillator crystal imports. Bottom-up equipment shipment estimates triangulated against top-down healthcare capital spending surveys.
Historical shipment trends cross-referenced with panel input from CT physicists and procurement directors informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user setting, reconstruction technology, and clinical application, with geographic clustering by hospital network expansion corridors. CAGRs derived from replacement cycle analysis and site-of-care reimbursement elasticity. Forecast inputs incorporated AI algorithm adoption curves and photon-counting detector yield rates.
Several conditions sit outside the modeled scope, including unforeseen FDA regulatory shifts, disruptive substitution from MRI advances, and major CMS reimbursement recalibration. Forecasts reflect documented assumptions regarding IDN consolidation velocity and detector material supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
France Mammography Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Specialty PACS Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Carotid Ultrasound Imaging Market