
 US Diagnostic Imaging Services Market | 2026-2036
US Diagnostic Imaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Diagnostic Imaging Services Market Insights
Asset-light leasing and joint venture models with hospital systems is narrowing the capital barrier for mid-scale operators. Radiology Partners leverages its partnership network with health systems to sustain geographic density across metropolitan corridors. RadNet anchors its position through captive imaging center ownership and in-house production of radiology reads. SimonMed Imaging differentiates via same-day scheduling capacity and direct-to-employer contracting.
Diagnostic imaging services encompass the acquisition, interpretation, and reporting of anatomical and physiological visual data using ionizing and non-ionizing radiation modalities, with spatial resolution thresholds ranging from sub-millimeter CT slices to functional PET metabolic mapping. These services enable non-invasive disease detection, treatment planning, and therapeutic monitoring across acute and chronic care pathways. Magnetic Resonance Imaging captures the highest-margin elective cases in neurological evaluation and musculoskeletal analysis where soft-tissue contrast superiority commands premium pricing. Computed Tomography dominates acute pulmonary screening and trauma triage volumes due to speed and wide availability in emergency settings. Ultrasound Imaging competes on cost efficiency and portability, particularly in outpatient facilities and ambulatory surgery centers where real-time guidance reduces procedural complications.
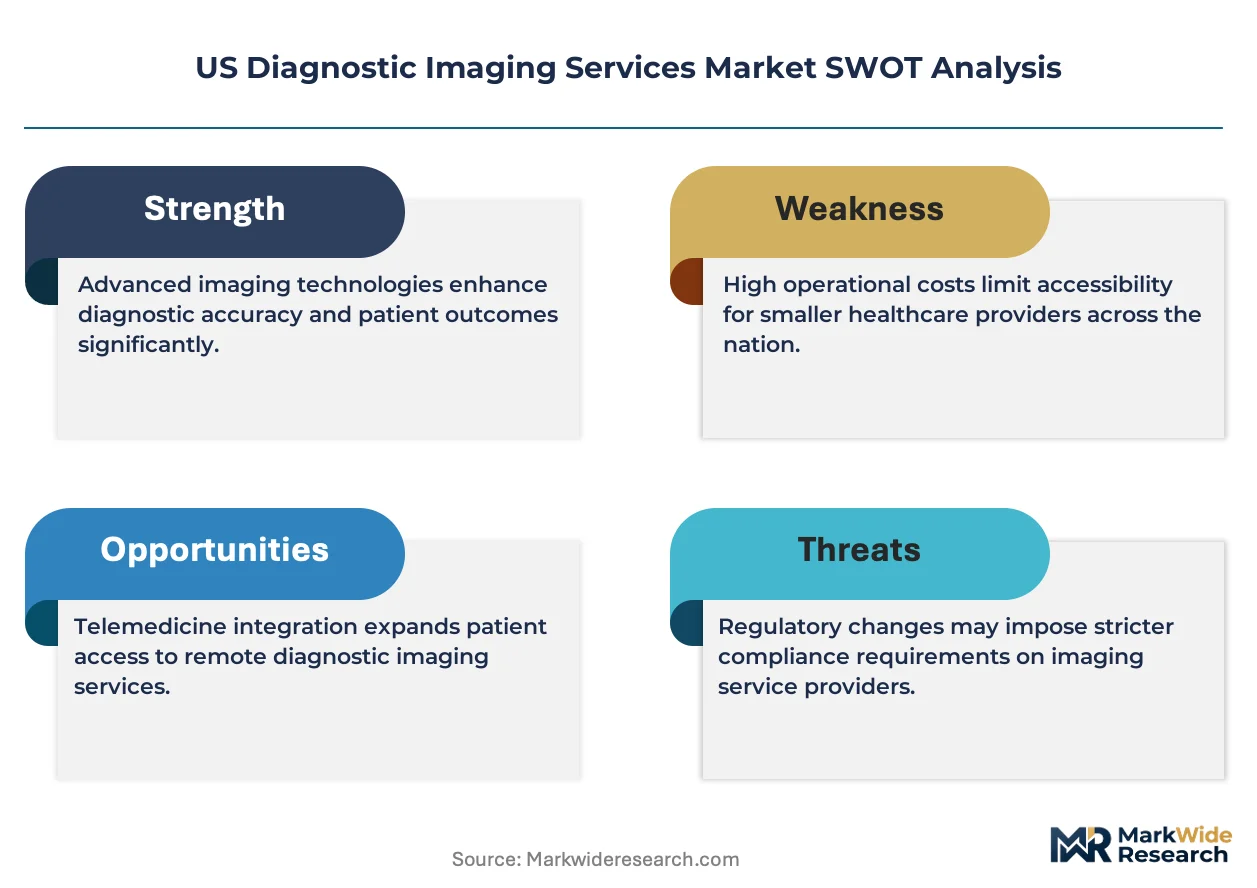
FDA oversees device safety and software-as-medical-device algorithms that increasingly automate image reconstruction and lesion detection. CMS payment rules and the Protecting Access to Medicare Act shape utilization patterns by mandating appropriate use criteria and site-neutral pricing pressures. State-level certificate-of-need regulations in jurisdictions like New York and Illinois restrict capital deployment for new imaging suites. Stakeholders must monitor how FDA artificial intelligence guidance and CMS site-neutral payment expansion alter the economics of freestanding versus hospital-based imaging delivery.
Market Dynamics
Site-neutral payment mandates from CMS are compressing reimbursement differentials between hospital-based and freestanding imaging centers, forcing operators to restructure cost bases and redirect capital toward outpatient capacity.
Growth Catalysts
- Medicare Advantage expansion:CMS payment rate advantages for managed care enrollees are pulling elective imaging volumes toward ambulatory settings in metropolitan corridors.
- Artificial intelligence deployment:FDA-cleared algorithms for lesion detection and workflow triage are reducing radiologist read times and expanding throughput capacity at fixed labor cost.
- Texas and Florida demographic concentration:Retiree migration patterns are elevating cardiovascular and oncology screening demand in Sun Belt metropolitan statistical areas.
Market Restraints
- Helium supply concentration:MRI magnet cooling depends on Qatar and Russia-sourced helium, with price volatility threatening high-field system operating economics.
- Certificate-of-need jurisdictions:New York and Illinois state regulations block new imaging suite deployment, protecting incumbent capacity but constraining patient access expansion.
- CT dose limitation protocols:ALARA principles and pediatric dose reduction mandates are capping scan intensity per patient encounter.
Strategic Opportunities
- Rural hospital joint ventures:Critical access facilities in Mississippi and Alabama lack capital for modality acquisition, creating partnership entry points for regional operators.
- Direct-to-employer contracting:Self-insured employers in manufacturing and logistics verticals are bypassing payers to secure bundled imaging rates for occupational health screening.
- Portable ultrasound penetration:Point-of-care systems are displacing department-based echocardiography in emergency medicine and anesthesiology workflows.
Industry Challenges
- Radiologist workforce compression:Fellowship-trained neuroradiologists and interventional specialists command premium compensation, constraining expansion timelines for advanced service lines.
- PACS integration complexity:Legacy picture archiving systems from multiple vendors require costly middleware layers to achieve interoperability with cloud-native AI platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Diagnostic Imaging Services Market |
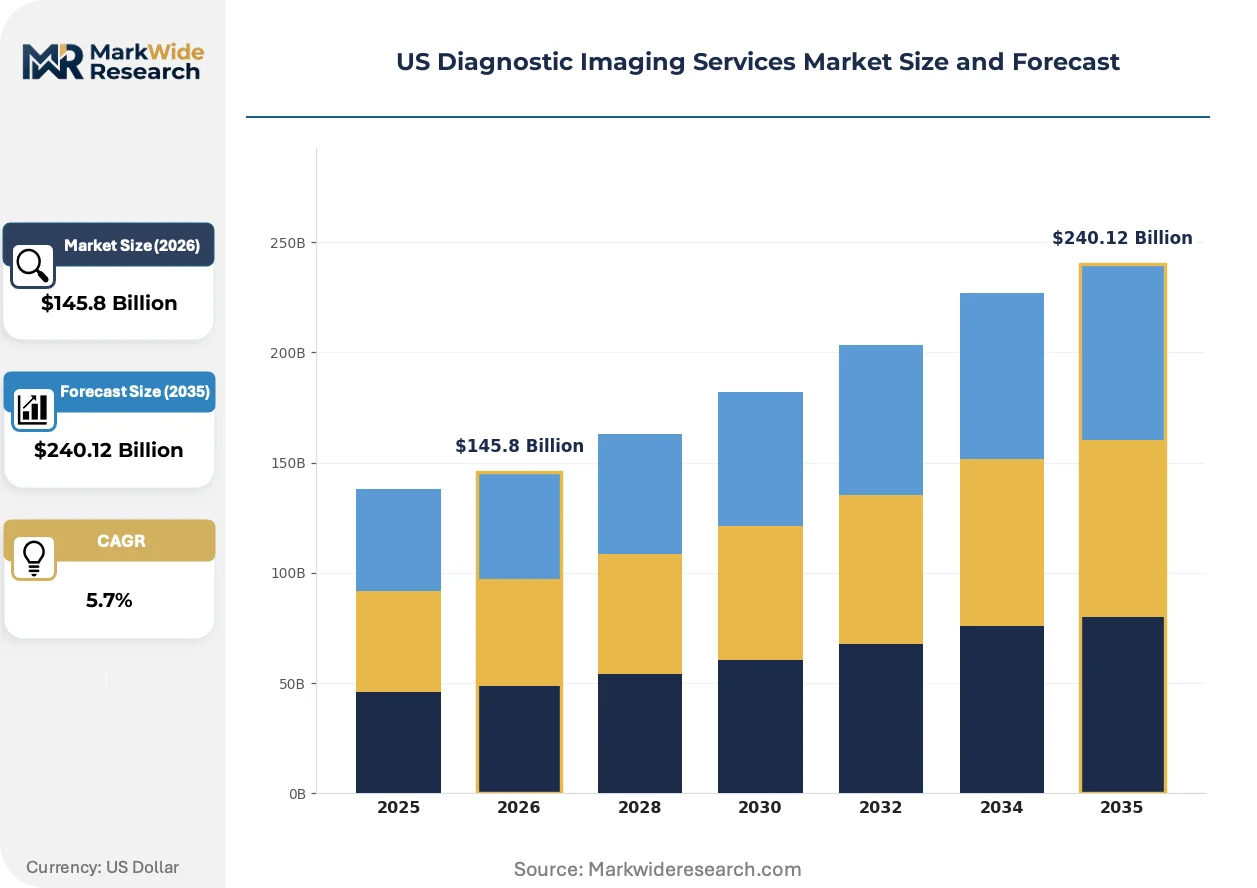
| Market Size in 2026 | $145.8 Billion |
| Market Size in 2035 | $240.12 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Magnetic Resonance Imaging, Computed Tomography, Ultrasound Imaging, X-Ray Services, Positron Emission Tomography End User: Specialty Clinics, Diagnostic Centers, Outpatient Facilities, Imaging Labs, Ambulatory Surgery Centers Application: Oncological Diagnostics, Cardiovascular Assessment, Neurological Evaluation, Musculoskeletal Analysis, Pulmonary Screening Technology: 3D Imaging, Digital Radiography, Contrast-Enhanced Imaging, Portable Imaging Devices, Image-Guided Procedures |
| Companies Covered | RadNet, RAYUS Radiology, Akumin, Radiology Partners, US Radiology Specialists, SimonMed Imaging, MedQuest Associates, LucidHealth, Envision Radiology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Diagnostic Imaging Services Market Trends and Innovations
Computational reconstruction and ambient intelligence are redefining how imaging data is acquired, processed, and delivered to clinical decision points across acute and ambulatory care pathways.
Photon-counting CT detectors are digitizing spectral imaging capabilities that previously required dual-source hardware configurations. Academic medical centers and large health systems are replacing first-generation dual-energy systems at 7-10 year replacement cycles. The technology is digitizing tissue characterization accuracy while compressing contrast agent volumes per study.
CMS site-neutral payment expansion is eliminating facility fee differentials for imaging services delivered in hospital outpatient departments versus freestanding centers. Freestanding operators are capturing volume migration as health systems divest non-core imaging assets. Cardiovascular and orthopedic service lines in Texas and California are restructuring referral patterns to retain patient capture.
Employer-sponsored centers are displacing traditional payer networks as the primary access channel for routine screening populations. Manufacturing and logistics employers in the Southeast are contracting directly with imaging operators for occupational health and preventive screening bundles. This channel shift is most visible in Florida and Georgia where self-insured employer density exceeds national averages.
US Diagnostic Imaging Services Market Segmentation
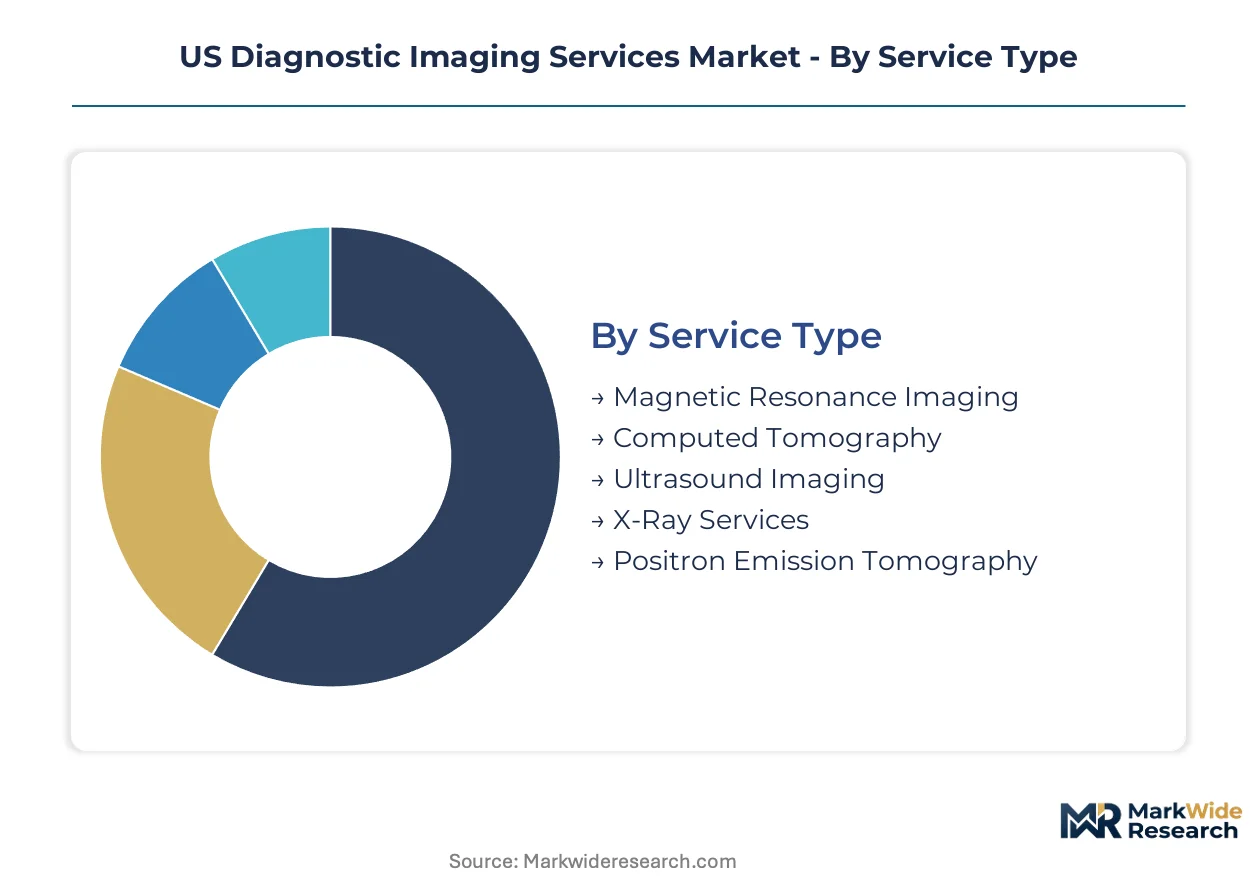
Segmentation reveals how capital intensity, reimbursement differentials, and clinical throughput requirements fragment service delivery across the US diagnostic imaging landscape. Understanding modality-level economics and site-of-care dynamics enables operators to align capacity investments with volume migration patterns.
Service Type:
Cycle times vary dramatically across modalities, with CT and X-ray delivering sub-hour turnaround while MRI and PET require extended scheduling windows and specialized radiologist availability.
- Magnetic Resonance Imaging:High-field systems utilize superconducting magnets and radiofrequency coils to generate sub-millimeter soft-tissue contrast without ionizing radiation. Demand concentrates in Texas and Florida neurological evaluation centers where retiree populations drive elective spine and brain imaging volumes constrained by helium supply volatility.
- Computed Tomography:X-ray tube and detector array systems reconstruct cross-sectional anatomy through rapid gantry rotation, dominating emergency department trauma triage. Florida and California acute care networks sustain the highest throughput volumes, though ALARA dose protocols cap scan intensity per patient encounter.
- Ultrasound Imaging:Piezoelectric transducer systems deliver real-time anatomical visualization at lower capital cost than cross-sectional modalities.
- X-Ray Services:Digital detector panels have displaced analog film systems across outpatient and inpatient settings.
- Positron Emission Tomography:Cyclotron-produced radiotracer dependency creates supply chain complexity for metabolic imaging.
X-Ray Services anchors the volume base while Ultrasound Imaging gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital outpatient departments from lean freestanding operators competing on price transparency and scheduling velocity.
- Diagnostic Centers:Dedicated imaging facilities aggregate multi-modality capacity under centralized radiologist staffing, capturing economies of scale in metropolitan corridors. Texas and California freestanding operators are restructuring referral relationships as CMS site-neutral payment mandates compress reimbursement differentials.
- Specialty Clinics:Orthopedic and cardiology group practices embed imaging capacity to control patient capture and accelerate treatment decisions. Florida cardiovascular specialty networks are expanding in-house CT and stress echo capacity to retain referral volumes.
- Outpatient Facilities:Hospital-affiliated ambulatory sites balance clinical integration with lower cost structures than main campuses.
- Imaging Labs:High-volume screening operations focus on mammography and bone density services.
- Ambulatory Surgery Centers:Procedure-integrated imaging supports intraoperative navigation and immediate complication assessment.
Diagnostic Centers anchor the volume base while Ambulatory Surgery Centers are expanding most quickly.
Application:
Clinical application segmentation tracks disease prevalence demographics and reimbursement intensity across acute and chronic care pathways.
- Oncological Diagnostics:PET-CT fusion imaging and multiparametric MRI enable tumor staging and treatment response monitoring with metabolic and anatomical correlation. Texas and Florida oncology networks are elevating screening compliance rates among Medicare Advantage enrollees.
- Cardiovascular Assessment:Coronary CT angiography and cardiac MRI quantify plaque burden and myocardial viability without invasive catheterization. California health systems are deploying CT fractional flow reserve algorithms to reduce unnecessary catheterization laboratory referrals.
- Neurological Evaluation:MRI dominates stroke protocol and dementia assessment workflows.
- Musculoskeletal Analysis:Sports medicine and orthopedic practices drive MRI and ultrasound demand.
- Pulmonary Screening:Low-dose CT protocols target high-risk smoking populations under Medicare coverage determinations.
Cardiovascular Assessment anchors the volume base while Oncological Diagnostics is climbing the fastest.
Technology:
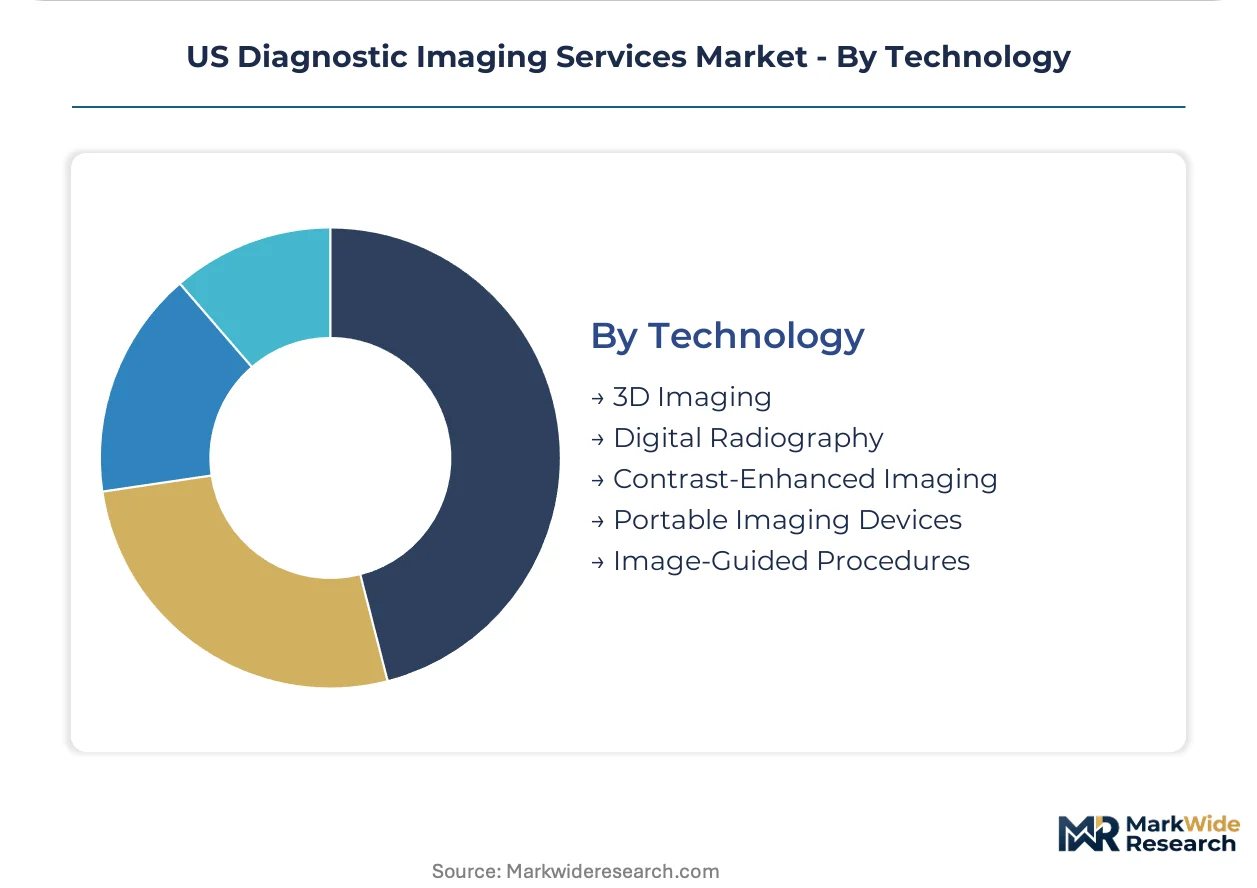
Technology maturity curves separate established digital platforms from emerging capabilities requiring substantial retraining and infrastructure investment.
- 3D Imaging:Volumetric reconstruction algorithms transform multi-slice CT and tomographic ultrasound into navigable anatomical models for surgical planning. Academic medical centers in California and Texas are replacing legacy visualization workstations with cloud-native rendering platforms.
- Digital Radiography:Flat-panel detector systems have achieved near-complete penetration of general radiography, delivering immediate image availability and dose reduction compared to computed radiography. Mississippi and Alabama rural hospitals are accessing DR upgrades through joint venture partnerships with regional operators.
- Contrast-Enhanced Imaging:Iodinated and gadolinium-based agents improve lesion conspicuity across CT and MRI protocols.
- Portable Imaging Devices:Point-of-care ultrasound and mobile X-ray systems displace department-based workflows.
- Image-Guided Procedures:Real-time navigation supports biopsy and intervention accuracy.
Digital Radiography anchors the volume base while Portable Imaging Devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service flows remain predominantly domestic, with imaging capacity expanding in high-migration corridors while certificate-of-need states constrain new suite deployment. Texas, Florida, and California absorb disproportionate volume growth from demographic concentration and Medicare Advantage penetration.
Texas
Retiree migration and cardiovascular disease prevalence elevate CT and MRI throughput across Dallas-Fort Worth and Houston metropolitan corridors. State CON absence permits rapid capacity deployment by freestanding operators. Radiology Partners maintains dense coverage through health system joint ventures in the Texas Medical Center cluster.
Florida
Medicare Advantage enrollment concentration pulls elective imaging toward ambulatory settings in Miami-Dade and Tampa Bay markets. Florida's CON program for acute care beds does not extend to outpatient imaging, enabling specialty clinic expansion. SimonMed Imaging anchors same-day scheduling capacity across the Orlando corridor.
California
Academic medical centers in Los Angeles and San Francisco deploy photon-counting CT at 7-10 year replacement cycles. State-level climate mandates and seismic retrofit requirements elevate facility construction costs. RadNet operates captive imaging centers throughout the Bay Area and Southern California metroplex.
New York
Certificate-of-need regulations restrict new MRI and CT suite deployment in New York City and upstate markets, protecting incumbent capacity. Aging infrastructure in Brooklyn and Queens drives demand for modernized digital radiography platforms. Hospital outpatient departments retain volume through clinical integration advantages.
Illinois
CON jurisdictions in Chicago and Cook County block freestanding center expansion, compressing patient access growth. Academic medical centers in the Illinois Medical District sustain advanced PET-CT and cardiac MRI service lines. Regional operators pursue joint ventures with critical access hospitals in downstate markets to bypass CON constraints.
US Diagnostic Imaging Services Market Competitive Landscape
On the supply side, the industry is consolidating through acquisition of independent imaging centers by national platforms with radiologist employment models. Radiology Partners and US Radiology Specialists exemplify the scale-driven archetype, deploying capital to aggregate geographic density. RadNet represents the captive-asset model, owning center real estate and imaging equipment directly. SimonMed Imaging occupies the consumer-access tier, competing on scheduling velocity and direct contracting. Dominant competitive moves include health system joint ventures for referral security and AI-enabled workflow automation for throughput expansion.
Within the national platform tier, Radiology Partners and US Radiology Specialists exemplify scale-driven consolidation through health system partnerships. RadNet anchors the captive-ownership archetype with vertically integrated center operations. SimonMed Imaging occupies the consumer-access position, differentiating through same-day capacity and employer-direct channels.
| Leading Market Players |
|---|
| RadNet |
| RAYUS Radiology |
| Akumin |
| Radiology Partners |
| US Radiology Specialists |
| SimonMed Imaging |
| MedQuest Associates |
| LucidHealth |
| Envision Radiology |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-field MRI systems across Texas and Florida metropolitan corridors drives both supplier pricing power and hospital system procurement urgency. CMS site-neutral payment mandates compress reimbursement differentials, forcing freestanding operators to restructure cost bases while equipment manufacturers exploit capacity scarcity to sustain premium pricing on magnet systems.
Pricing Analysis
Hospital systems and specialty clinics anchor a contract-based pricing structure dominated by multi-year equipment lease agreements bundled with service contracts. Price differentiation separates premium-tier academic medical centers with 3T MRI capabilities from standard-tier community hospitals and economy-tier rural critical access facilities. Cost compression in the standard tier intensifies as Medicare Advantage expansion pulls elective volumes toward ambulatory settings. Self-insured employers demonstrate highest price sensitivity, bypassing traditional payer networks to secure bundled rates.
Supply Chain Analysis
Helium supply concentration between Qatar and Russia dominates radiology supply chain risk for MRI magnet cooling systems. Superconducting magnet manufacturing draws from Japan, Germany, and USA production facilities, while gadolinium-based contrast agents and iodinated media source from Ireland, China, and India pharmaceutical plants. Single-source vulnerability in helium procurement threatens high-field system operating economics across Sun Belt imaging networks. Distribution runs through OEM direct sales teams and specialized medical equipment distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US diagnostic imaging services market sits in early-cycle expansion as Medicare Advantage penetration and AI-enabled workflow automation accelerate volume migration toward outpatient settings.
For Market Incumbents: Pre-empt radiologist workforce compression by locking fellowship-trained neuroradiologists and interventional specialists into employment contracts before compensation escalation constrains advanced service line expansion. Consolidate geographic density in Texas and Florida through health system joint ventures that secure referral capture against emerging employer-direct channels. For New Entrants and Emerging Players: Rural hospital joint ventures in Mississippi and Alabama represent the most penetrable entry point, as critical access facilities lack capital for modality acquisition and face CON constraints in neighboring states. Target direct-to-employer contracting in Southeast manufacturing and logistics verticals, leveraging same-day scheduling capacity as the primary go-to-market differentiator against incumbent payer-network dependency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional operators with captive radiologist employment models and multi-site geographic density in Sun Belt metropolitan corridors. Long-term viability across the analysis window favors platforms with AI-enabled throughput expansion and site-neutral payment adaptation. Monitor FDA artificial intelligence guidance expansion as the critical inflection signal for workflow automation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Health System Joint Venture | Secures referral capture and geographic density in Texas Medical Center cluster. |
| AI Workflow Deployment | FDA-cleared lesion detection algorithms expand radiologist throughput at fixed labor cost. |
| Direct-to-Employer Contracting | Bypasses traditional payer networks for occupational health screening in Florida manufacturing. |
| Helium Supply Hedging | Mitigates Qatar-Russia concentration risk threatening high-field MRI operating economics. |
| Site-Neutral Payment Adaptation | Restructures cost bases to capture volume migration from hospital outpatient departments. |
Research Methodology
Initial hypotheses were tested against primary input from radiology group practice administrators, hospital procurement committee members, biomedical equipment engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and state CON regulatory records. Bottom-up center-level capacity modeling triangulated with top-down national expenditure estimates derived the market size and growth projections.
Demand-supply balance across the projection horizon integrated Medicare Advantage enrollment trajectories, radiologist workforce pipeline data, and equipment replacement cycle timing. Segmentation dimensions modeled include modality type, site-of-care setting, clinical application, and geographic metropolitan statistical area. CAGRs were derived from volume-intensity projections tied to disease prevalence demographics and reimbursement rate evolution.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, helium commodity pricing, or AI regulatory pathways would shift the trajectory. Forecasts reflect documented assumptions about site-neutral payment expansion velocity and radiologist supply constraints. Material shifts in FDA artificial intelligence guidance or CMS site-neutral payment implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Open System MRI Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market