
 Europe Nuclear Imaging Devices Market | 2026-2036
Europe Nuclear Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Imaging Devices Market Insights
Aftermarket service revenue is reshaping margin distribution across the Europe nuclear imaging landscape. Siemens Healthineers AG leverages its pan-European service footprint to capture recurring maintenance contracts on installed PET and SPECT bases. GE Healthcare sustains competitive pressure through dense field engineering networks in France and Italy. Koninklijke Philips NV differentiates via software upgrade pathways that extend hardware lifecycles without full system replacement.
Nuclear imaging devices employ gamma radiation detection—through scintillation crystals, photomultiplier tubes, or solid-state digital detectors—to map radiopharmaceutical distribution in vivo for diagnostic and therapeutic monitoring purposes; modern hybrid systems achieve spatial resolution below 4 mm FWHM by fusing anatomical CT or MRI data with functional PET or SPECT signals. Hybrid systems command the dominant share of new capital expenditure as hospitals seek consolidated throughput from single-platform investments. Digital imaging technology is displacing analog detector architectures fastest in research institutions pursuing quantitative radiomics protocols.
The EU MDR and EMA oversight of radiopharmaceutical quality standards jointly elevate compliance costs for device manufacturers seeking CE marking renewal. Germany's KBA-equivalent device regulator, BfArM, enforces additional post-market surveillance requirements that slow market entry for non-established suppliers. Stakeholders must monitor convergence between AI-enhanced reconstruction algorithms and evolving EMA guidance on software-as-medical-device classification.
Market Dynamics
Aftermarket service revenue streams are restructuring margin capture across the Europe nuclear imaging devices market, with recurring maintenance contracts now commanding disproportionate strategic attention from installed base holders.
Growth Catalysts
- Oncology network expansion:European hospital systems are consolidating cancer care into specialized centers that require high-throughput PET-CT suites to manage patient volume efficiently.
- EU MDR compliance cycles:The Medical Device Regulation's phased implementation deadlines are accelerating replacement demand for legacy systems that cannot meet enhanced post-market surveillance requirements.
- Digital detector migration:Solid-state silicon photomultiplier architectures are displacing analog photomultiplier tubes in research institutions pursuing quantitative radiomics protocols.
Market Restraints
- Scintillation crystal supply concentration:Lutetium-based crystal production concentrates among a limited supplier base in Asia, exposing European OEMs to input cost volatility and allocation risk.
- EMA radiopharmaceutical quality standards:Elevation of Good Manufacturing Practice requirements for radiotracer delivery systems extends conformity assessment timelines and elevates certification costs for device manufacturers.
- Extended replacement cycles:Software upgrade pathways now extend hardware lifecycles to 12-15 years, compressing new capital expenditure frequency in mature European markets.
Strategic Opportunities
- Central and Eastern Europe infrastructure gap:Poland, Czech Republic, and Hungary maintain aging cobalt-therapeutic and first-generation SPECT bases that present replacement demand as EU structural funds flow into healthcare modernization.
- AI-enhanced reconstruction convergence:Deep learning algorithms for low-dose PET image reconstruction are creating differentiation vectors for vendors that can validate performance under EMA software-as-medical-device guidance.
- Theranostics integration:Lutetium-177 prostate cancer therapy expansion is driving demand for paired diagnostic-therapeutic imaging platforms that track radiopharmaceutical biodistribution through treatment cycles.
Industry Challenges
- Qualified nuclear medicine technologist scarcity:Specialized training programs for PET-CT operation and radiopharmaceutical handling are not expanding at pace with installed base growth, constraining throughput realization.
- CE marking renewal complexity:BfArM's enhanced post-market surveillance requirements for Germany create documentation burdens that delay market entry for non-established suppliers seeking pan-European access.
- Legacy PACS integration friction:New hybrid systems face interoperability challenges with hospital information systems that run on decade-old DICOM implementations, extending installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Imaging Devices Market |
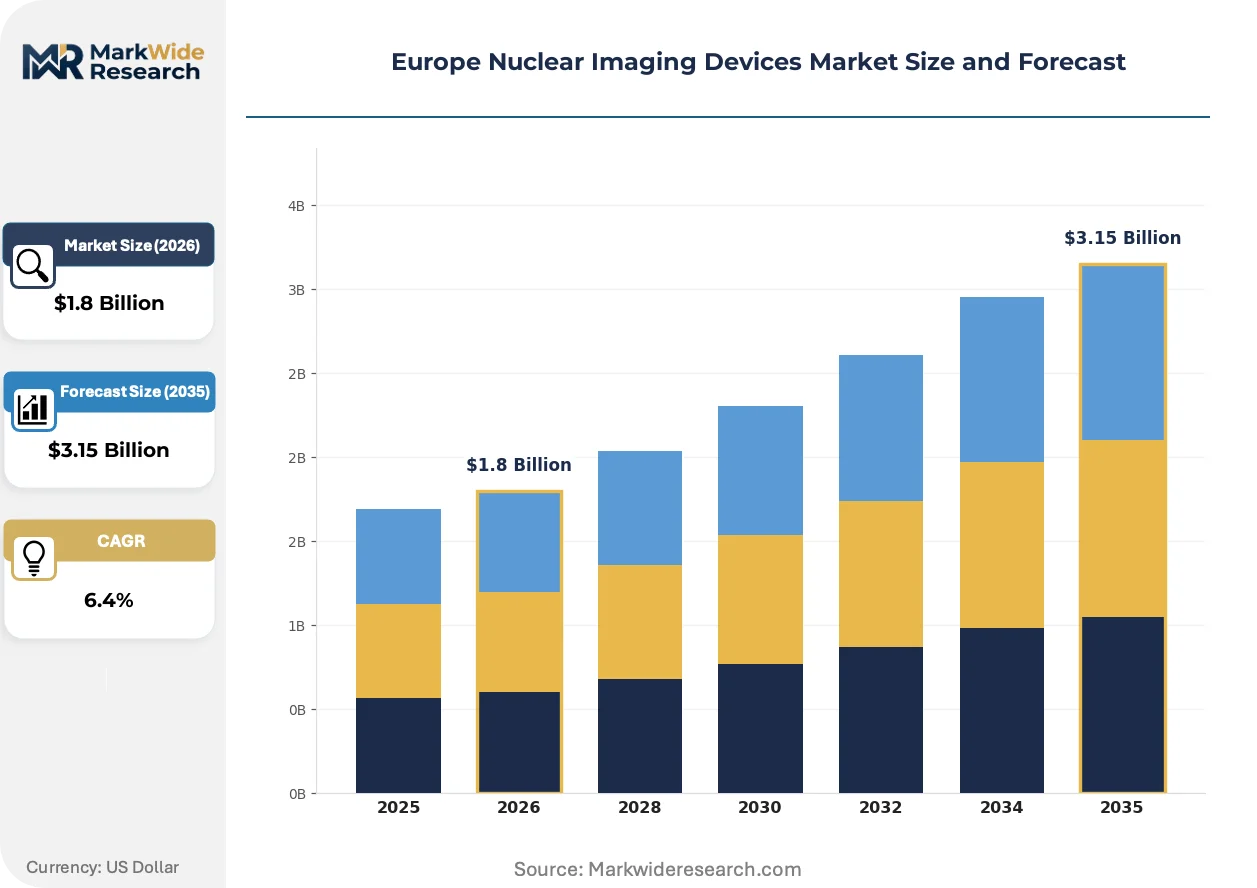
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Scanners, SPECT Systems, Hybrid Systems, Accessories End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Delivery Mode: Portable Devices, Fixed Systems, Mobile Units, Stand-alone Systems Technology: Analog Imaging, Digital Imaging, Software Integration, AI Enhancement |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Mediso Medical Imaging Systems, Shimadzu Corporation, Bracco Imaging SpA, Cardinal Health Inc., United Imaging Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Imaging Devices Market Trends and Innovations
Digital detector architectures and artificial intelligence integration are converging to redefine performance benchmarks and procurement criteria across European nuclear imaging, compressing the gap between research-grade capabilities and clinical deployment.
Silicon photomultiplier arrays are replacing vacuum tube photodetectors in next-generation PET systems, delivering improved timing resolution and magnetic field compatibility that enables simultaneous PET-MRI operation. University medical centers in Germany and the Netherlands are adopting these platforms fastest for neuroimaging protocols requiring sub-millimeter spatial resolution. The technology is hybridizing functional and anatomical imaging workflows into single-session examinations that consolidate hospital capital budgets.
EMA's evolving framework for software-as-medical-device classification is creating compliance uncertainty for vendors deploying AI-enhanced reconstruction algorithms. The regulator's draft guidance on machine learning-based medical devices demands clinical validation datasets that exceed historical 510(k) equivalence standards. PET-CT manufacturers with European development centers are restructuring quality management systems to accommodate iterative algorithm updates under MDR Article 10.
Service contract unbundling is fragmenting traditional OEM-aftermarket relationships as independent service organizations capture maintenance revenue on out-of-warranty SPECT bases. French and Italian hospital purchasing consortia are negotiating multi-vendor service agreements that separate hardware maintenance from software support. This restructuring concentrates negotiating leverage among large hospital networks while pressuring manufacturer margin structures in Southern Europe.
Europe Nuclear Imaging Devices Market Segmentation
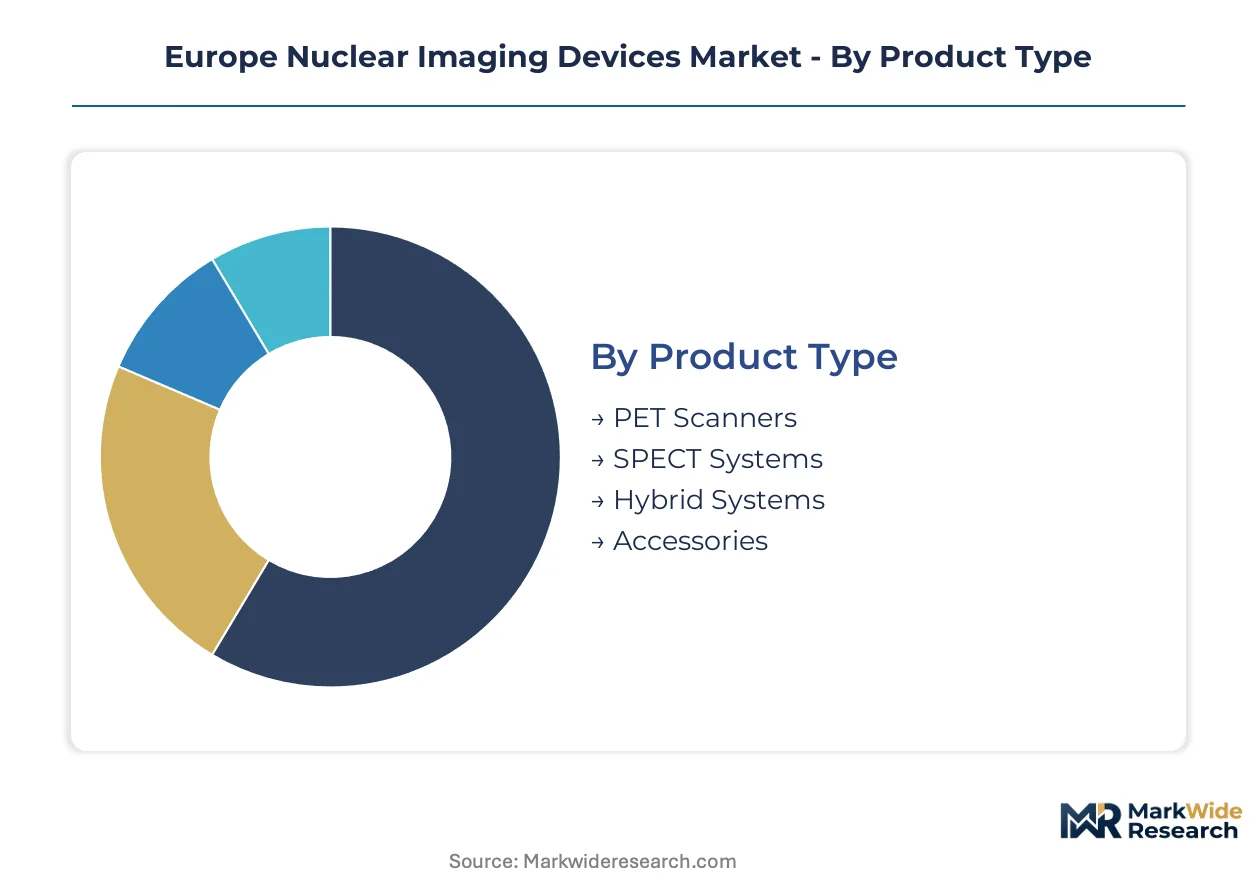
Segmentation across product architecture, clinical setting, deployment mode, and detector technology reveals distinct procurement patterns among European healthcare networks. Each dimension carries specific regulatory and reimbursement implications under EU MDR and national health technology assessment frameworks.
Product Type:
Cost tier differentiation separates capital-intensive hybrid platforms from modular component sales and service attachments.
- Hybrid Systems:PET-CT and PET-MRI configurations fuse functional radiotracer mapping with anatomical imaging in single-session workflows. German university hospitals and French cancer centers concentrate procurement of these platforms to consolidate capital budgets and maximize patient throughput per square meter of shielded suite space.
- PET Scanners:Standalone positron emission tomography systems employ scintillation crystal arrays and photodetector rings to capture annihilation photon pairs. United Kingdom NHS trusts favor dedicated PET bases for cardiac viability protocols where CT fusion adds limited diagnostic value.
- SPECT Systems:Single-photon emission computed tomography devices using gamma camera technology remain prevalent in Central European community hospitals with constrained capital budgets.
- Accessories:Radiopharmaceutical injection systems, patient positioning aids, and shielded transport containers constitute recurring revenue streams with shorter replacement cycles than primary imaging hardware.
Hybrid Systems hold installed capacity. PET Scanners is rotating up the share rankings.
End User:
Customer type determines procurement authority complexity and service contract negotiation leverage.
- Hospitals:Integrated delivery networks across Germany, France, and the United Kingdom command multi-system purchasing power and demand pan-European service coverage with guaranteed uptime clauses.
- Research Institutions:University medical centers in the Netherlands and Switzerland drive adoption of silicon photomultiplier architectures and quantitative radiomics protocols. EMA software-as-medical-device guidance constrains deployment of experimental AI reconstruction algorithms in these settings.
- Diagnostic Centers:Independent imaging facilities in Italy and Spain prioritize throughput-per-euro metrics and favor refurbished SPECT bases with unbundled third-party maintenance contracts.
- Clinics:Smaller cardiology and oncology practices concentrate demand for compact SPECT systems with simplified workflow interfaces and reduced shielding requirements.
Hospitals dominate capital deployment. Research Institutions is climbing the fastest.
Delivery Mode:
Volume and mobility requirements shape infrastructure investment and regulatory pathway selection.
- Fixed Systems:Permanent installation in shielded suites represents the conventional deployment model for high-throughput PET-CT operations. BfArM post-market surveillance requirements in Germany extend commissioning timelines for these configurations.
- Mobile Units:Truck-mounted or trailer-based systems serve rural populations in Poland and Hungary where permanent nuclear medicine infrastructure remains sparse. EU structural funds are financing mobile fleet expansion in these markets.
- Portable Devices:Compact gamma cameras and handheld probes enable bedside cardiac imaging in intensive care settings across French hospital networks.
- Stand-alone Systems:Self-shielded SPECT configurations reduce facility modification costs for diagnostic centers in Southern Europe with limited construction budgets.
Fixed Systems anchor the installed base. Mobile Units is gaining share fastest.
Technology:
Maturity gradients separate legacy analog architectures from emerging digital and AI-augmented modalities.
- Digital Imaging:Solid-state silicon photomultiplier detectors replace vacuum tube photomultipliers, delivering improved timing resolution and magnetic field compatibility for simultaneous PET-MRI operation. German neuroimaging centers adopt these platforms for sub-millimeter resolution requirements.
- AI Enhancement:Deep learning algorithms for low-dose PET image reconstruction reduce radiotracer exposure while preserving diagnostic confidence. EMA's evolving software-as-medical-device classification creates compliance uncertainty for vendors deploying iterative algorithm updates.
- Analog Imaging:Conventional photomultiplier tube architectures persist in extended-lifecycle SPECT systems across aging European installed bases.
- Software Integration:DICOM-compliant reconstruction and PACS connectivity modules address interoperability friction with decade-old hospital information systems.
Digital Imaging commands replacement demand. AI Enhancement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys hybrid PET-CT systems at higher density than France or the United Kingdom, while Southern European markets retain analog SPECT bases longer due to capital constraints and extended replacement cycles.
Germany
Bavarian university hospitals drive silicon photomultiplier adoption for neuroimaging protocols requiring sub-millimeter resolution. BfArM enforces enhanced post-market surveillance requirements that delay CE marking renewal for non-established suppliers. The Munich-Berlin corridor concentrates PET-CT procurement by integrated cancer centers consolidating regional oncology networks.
France
French hospital purchasing consortia negotiate multi-vendor service agreements separating hardware maintenance from software support. ANSM oversight of radiopharmaceutical quality standards elevates conformity assessment costs for device manufacturers. The Paris-Saclay cluster anchors hybrid system deployment across Île-de-France cancer centers.
United Kingdom
NHS trusts favor dedicated PET scanners for cardiac viability protocols where CT fusion adds limited diagnostic value. NICE health technology assessments influence reimbursement thresholds for new imaging modalities. London teaching hospitals and Manchester cancer centers lead procurement of AI-enhanced reconstruction platforms.
Italy
Independent diagnostic centers in Lombardy and Veneto prioritize throughput-per-euro metrics and favor refurbished SPECT bases with unbundled third-party maintenance. Regional health authorities face budget pressures that extend hardware lifecycles beyond typical depreciation schedules. Milan anchors the northern imaging infrastructure concentration.
Poland
EU structural funds finance mobile nuclear imaging fleet expansion serving rural populations where permanent infrastructure remains sparse. The national reimbursement framework limits PET-CT penetration outside Warsaw and Kraków academic centers. Regional hospitals in Silesia and Greater Poland present replacement demand for aging first-generation SPECT systems.
Europe Nuclear Imaging Devices Market Competitive Landscape
Capability concentration sits with diversified imaging conglomerates commanding pan-European service networks; scale advantage sits with diversified healthcare technology portfolios spanning multiple diagnostic modalities. Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips NV anchor the established tier through dense field engineering footprints and recurring maintenance contract capture. Strategic differentiation vectors include software upgrade pathways extending hardware lifecycles, AI-enhanced reconstruction algorithm validation under EMA guidance, and theranostics platform integration for paired diagnostic-therapeutic workflows.
Within the diversified healthcare technology tier, Siemens Healthineers AG and GE Healthcare occupy positions defined by installed base density and service contract penetration across German, French, and United Kingdom hospital networks. Koninklijke Philips NV exemplifies the software-centric archetype through digital detector architectures and reconstruction algorithm development. Canon Medical Systems Corporation and Shimadzu Corporation represent Japanese-origin competitors pursuing hybrid system market share through magnetic field compatibility and timing resolution improvements. Mediso Medical Imaging Systems anchors the specialized European vendor segment with focused nuclear medicine portfolios.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Mediso Medical Imaging Systems |
| Shimadzu Corporation |
| Bracco Imaging SpA |
| Cardinal Health Inc. |
| United Imaging Healthcare |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in lutetium-based scintillation crystal production across Asian supplier bases drives input cost volatility and forces European OEMs into long-term offtake negotiations that reshape procurement economics and margin distribution across the nuclear imaging value chain.
Pricing Analysis
Long-term service contracts dominate the European nuclear imaging landscape, with hospitals negotiating multi-year maintenance agreements that bundle hardware uptime guarantees with software upgrade entitlements. Price differentiation rests on CE marking tier and installed base density, with premium tiers commanding pan-European service coverage. Cost compression in refurbished SPECT segments intensifies as independent service organizations capture aftermarket revenue. Diagnostic centers in Southern Europe exhibit highest price sensitivity, while German university hospitals prioritize resolution specifications over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among specialized crystal growth facilities in Japan and China, with European OEMs retaining final system integration and software development in-house. Scintillation crystal production draws from rare earth processing concentrated in China, while photodetector assembly rests on semiconductor foundries in Taiwan and South Korea. Single-source vulnerability in lutetium supply creates exposure to export restriction shocks. Distribution runs through authorized dealer networks for capital equipment and direct OEM relationships for radiopharmaceutical delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among French and Italian hospital purchasing consortia that negotiate multi-vendor service agreements, fragmenting traditional OEM-aftermarket relationships and compressing manufacturer margins across Southern Europe.
For Market Incumbents: Pre-empt independent service organization encroachment by unbundling software support from hardware maintenance to retain pricing control on AI-enhanced reconstruction modules. Accelerate silicon photomultiplier certification under EMA software-as-medical-device guidance to create switching costs for research institutions pursuing quantitative radiomics protocols. For New Entrants and Emerging Players: Build out mobile nuclear imaging fleet operations serving rural Poland and Hungary where EU structural funds finance infrastructure expansion and permanent suite installation remains uneconomical. Target diagnostic centers in Lombardy and Veneto with refurbished SPECT bases paired with third-party maintenance contracts to bypass entrenched OEM service networks. For Investors and Strategic Acquirers: Capital is best deployed toward specialized European vendors with focused nuclear medicine portfolios and established CE marking pathways, as regulatory complexity creates defensive moats against Asian competitors. Monitor convergence between AI-enhanced reconstruction algorithm validation and EMA software-as-medical-device classification as the inflection signal for platform differentiation viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance accelerates market access for digital detector architectures across German hospital networks. |
| Hospital System Partnership | Multi-year service contracts with French cancer centers lock in recurring revenue and displace independent service organizations. |
| Software Companion Development | AI-enhanced reconstruction modules validated under EMA guidance create differentiation vectors for PET-CT vendors. |
| Backward Integration into Crystal Supply | Captive lutetium sourcing mitigates allocation risk from Asian supplier concentration and stabilizes input costs. |
| Reimbursement Strategy | NICE health technology assessment alignment secures NHS trust procurement for cardiac viability imaging protocols. |
Research Methodology
Desk research of EMA guidance documents, BfArM post-market surveillance databases, and hospital procurement records preceded structured interviews with nuclear medicine technologists, biomedical engineers, GPO contracts managers, and radiopharmaceutical supply specialists. Secondary validation drew from EU Medical Device Regulation implementation reports, NICE health technology assessments, and CMS Medicare reimbursement data. Bottom-up installed base enumeration triangulated against top-down capital expenditure estimates from national health accounts.
Assumptions held fixed across the modeling period include EU MDR enforcement timelines, EMA software-as-medical-device classification frameworks, and national reimbursement thresholds for PET-CT procedures. Variables tested across sensitivity bands encompass scintillation crystal price trajectories, qualified technologist supply expansion rates, and mobile unit fleet penetration in Central and Eastern Europe. CAGRs derived from segmented demand modeling across hybrid systems, standalone PET, and SPECT configurations, with theranostics integration intensity serving as a demand elasticity input.
Stress conditions across lutetium supply disruption scenarios, BfArM surveillance requirement stringency, and AI algorithm validation failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of stable EU structural fund allocation to healthcare infrastructure and unchanged EMA radiopharmaceutical quality standards. Cross-checking against national health technology assessment body reimbursement decisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
India Mammography Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Breast Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
France Mammography Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Mammography Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Japan Computed Tomography Market