
 Orthopedic Radiology Equipment Market | 2026-2036
Orthopedic Radiology Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Radiology Equipment Market Outlook
Ambulatory orthopedic clinics are rotating toward ownership of on-site diagnostic imaging, displacing traditional hospital-dependent referral patterns for trauma and joint assessments. Siemens Healthineers leverages its installed base of C-arms to sustain service revenue streams across European orthopedic day clinics. GE Healthcare anchors its position through digital X-ray platforms designed for high-throughput sports medicine environments. Canon Medical Systems differentiates via compact MRI configurations that fit retrofit installations in existing orthopedic suites.
Orthopedic radiology equipment encompasses diagnostic imaging systems engineered specifically for musculoskeletal evaluation, typically operating at tube voltages of 50-150 kVp for extremity radiography and incorporating weight-bearing capture mechanics for joint loading analysis. These systems serve the commercial purpose of enabling point-of-care diagnosis, surgical planning, and post-operative monitoring within musculoskeletal care pathways. CT scanners lead capital expenditure among product categories due to their irreplaceable role in complex fracture classification and pre-operative templating for arthroplasty, while 3D imaging technology captures the fastest expansion as orthopedic clinics adopt intraoperative navigation and patient-specific implant workflows. Digital imaging maintains mature, high-volume status across hospital radiology departments where PACS integration and throughput optimization dominate procurement criteria.
The FDA's 510(k) premarket notification framework governs device clearance timelines for US manufacturers, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa and above orthopedic imaging systems entering European markets. Japan's PMDA enforces JIS standards for electromagnetic compatibility that shape design specifications for equipment destined for East Asian deployment. Stakeholders must monitor how divergent regulatory burdens across FDA, EMA, and PMDA jurisdictions influence product development prioritization and geographic launch sequencing.
Market Dynamics
Ambulatory surgical centers are consolidating diagnostic workflows on-site, compressing traditional hospital referral volumes for trauma imaging and post-operative monitoring. This structural reconfiguration redistributes capital expenditure toward compact fluoroscopy and weight-bearing radiography systems.
Growth Catalysts
- EU Medical Device Regulation:Class IIa orthopedic imaging systems face stricter clinical evidence requirements, accelerating quality differentiation among manufacturers serving European orthopedic day clinics.
- Intraoperative navigation:3D imaging technology enables patient-specific implant workflows, pulling capital investment into surgical suites for real-time anatomical mapping during arthroplasty.
- Germany:Orthopedic outpatient clinics deploy mini-C-arm fluoroscopy units to capture trauma cases previously routed to hospital emergency departments.
Market Restraints
- Tube voltage calibration:Precision requirements for extremity radiography at 50-150 kVp demand specialized engineering talent, constraining supplier expansion.
- Japan PMDA electromagnetic compatibility:JIS standards impose design specifications that extend development cycles for equipment targeting East Asian markets.
- CT scanner capital intensity:Complex fracture classification and pre-operative templating require irreplaceable imaging modalities that dominate facility budgets.
Strategic Opportunities
- Retrofit MRI installations:Compact configurations fit existing orthopedic suites, opening upgrade pathways for clinics without construction permits.
- Sports medicine throughput:Digital X-ray platforms designed for high-volume environments capture injury assessment volumes from athletic training facilities.
- FDA 510(k) pathway:Accelerated clearance timelines for digital radiography systems compress commercialization schedules for US market entry.
Industry Challenges
- PACS integration complexity:Legacy hospital radiology departments demand seamless connectivity with existing imaging archives, extending sales cycles.
- Weight-bearing capture mechanics:Joint loading analysis requires specialized mechanical engineering that outpaces standard radiography training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Radiology Equipment Market |
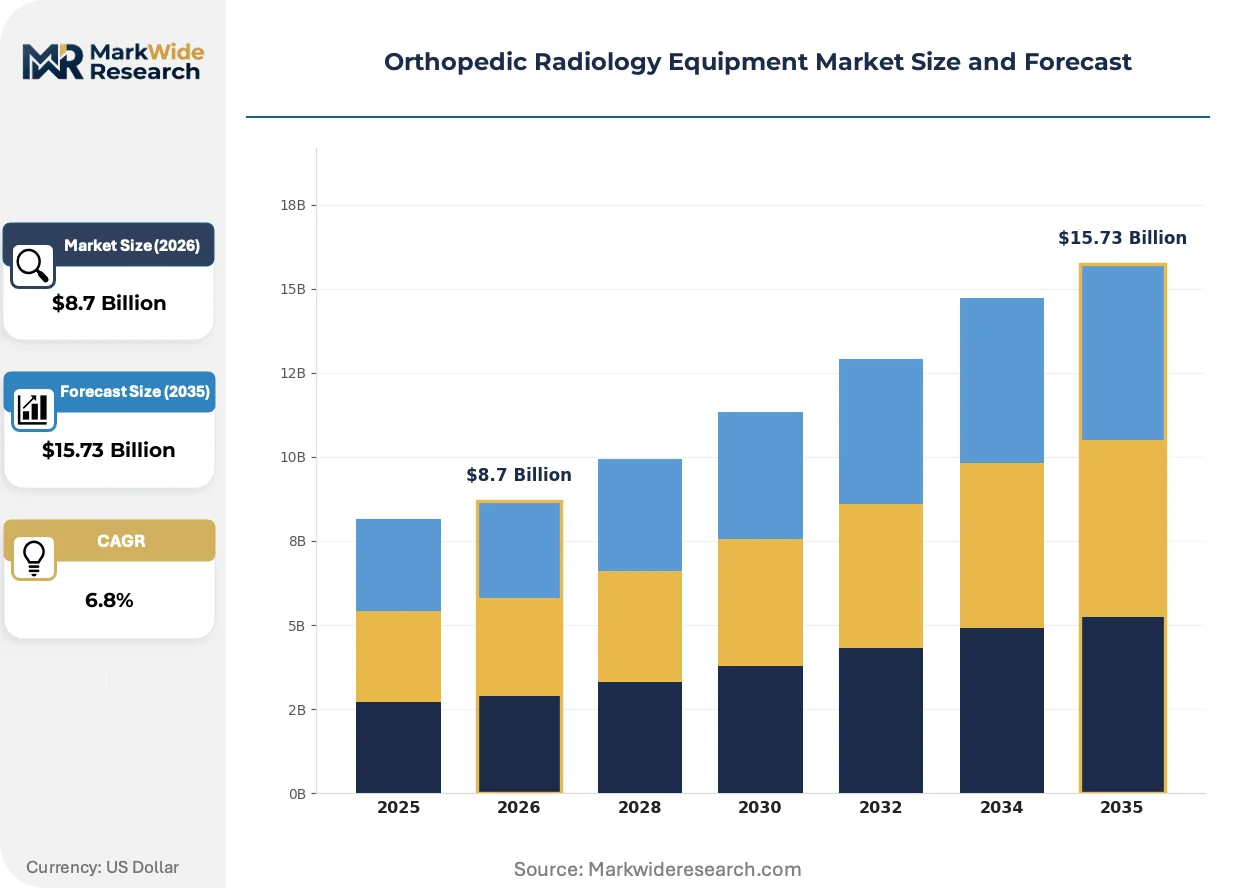
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, MRI Machines, CT Scanners, Ultrasound Devices End User: Hospitals, Imaging Centers, Orthopedic Clinics, Sports Clinics Technology: Digital Imaging, Fluoroscopy, Advanced Visualization, 3D Imaging Application: Trauma Assessment, Joint Disorders, Bone Fractures, Pre-operative Planning |
| Companies Covered | Philips Healthcare, Canon Medical Systems, Orthoscan, Carestream, FUJIFILM, Ziehm Imaging, Siemens Healthineers, Shimadzu, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Radiology Equipment Market Strategic Shifts
Orthopedic imaging is converging with surgical navigation, collapsing the boundary between diagnostic capture and operative intervention. Equipment vendors now engineer for dual-use environments.
Intraoperative 3D imaging is fragmenting the traditional separation between pre-operative planning and surgical execution. Orthopedic clinics in Germany and the United States are adopting cone-beam CT and fluoroscopic navigation for real-time implant positioning. This convergence compresses revision rates while demanding new capital allocation models that blend diagnostic and therapeutic equipment procurement.
The EU Medical Device Regulation imposes post-market surveillance obligations on Class IIa orthopedic imaging systems, extending compliance timelines for European commercialization. Manufacturers must maintain clinical evidence registries that track device performance across orthopedic day clinics. German and French markets exhibit the most pronounced response, with procurement committees now weighting regulatory documentation alongside technical specifications.
Service revenue unbundling is separating hardware sales from maintenance contracts across European orthopedic day clinics. Siemens Healthineers leverages its installed C-arm base to sustain recurring revenue streams independent of new equipment transactions. This model is most visible in Germany, where clinic chains negotiate multi-year service agreements that lock in technical support while deferring capital refresh cycles.
Orthopedic Radiology Equipment Market Segmentation
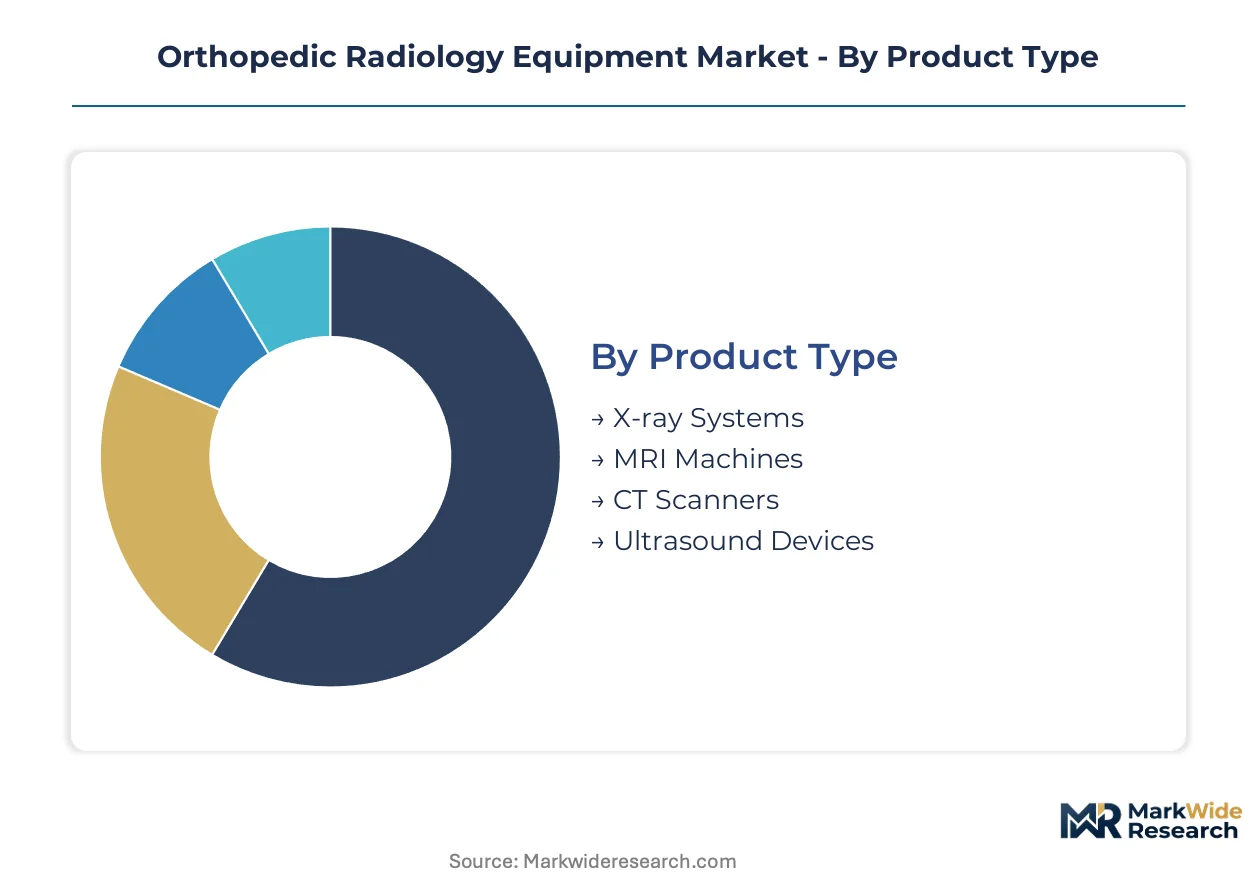
Orthopedic radiology equipment flows through distinct procurement channels shaped by capital intensity and workflow integration requirements. Understanding segment boundaries clarifies how manufacturers align product specifications with facility capabilities and regulatory constraints.
Product Type:
CT scanners and digital X-ray systems dominate hospital procurement through direct sales channels, while compact MRI and ultrasound devices increasingly reach orthopedic clinics via distributor networks.
- X-ray Systems:Digital radiography platforms operate at 50-150 kVp for extremity imaging with weight-bearing capture mechanics. Demand concentrates in German orthopedic day clinics investing in mini-C-arm units to retain trauma cases locally rather than referring to hospital emergency departments.
- CT Scanners:Cone-beam and conventional CT systems enable complex fracture classification and pre-operative templating for arthroplasty. Capital expenditure concentrates in hospital radiology departments where PACS integration and throughput optimization dominate procurement criteria.
- MRI Machines:Compact configurations designed for retrofit installation in existing orthopedic suites.
- Ultrasound Devices:Portable systems for point-of-care joint and soft tissue assessment.
By volume, X-ray Systems lead. By growth pace, CT Scanners are climbing the fastest.
End User:
Procurement authority varies sharply across facility types, with hospitals consolidating multi-modality purchasing while orthopedic clinics negotiate single-unit transactions.
- Hospitals:Centralized radiology departments with established PACS infrastructure and multi-year capital planning cycles. Demand concentrates in the United States where the FDA's 510(k) clearance pathway accelerates commercialization timelines for digital radiography systems.
- Orthopedic Clinics:Ambulatory facilities expanding on-site imaging capabilities to reduce referral leakage. German outpatient clinics deploy mini-C-arm fluoroscopy units to capture trauma cases previously routed to hospital emergency departments.
- Imaging Centers:Independent diagnostic facilities serving multiple referring physician groups.
- Sports Clinics:High-throughput environments requiring rapid injury assessment workflows.
Orthopedic Clinics are gaining share fastest as ambulatory sites consolidate diagnostic workflows.
Technology:
Technology selection tracks the convergence between diagnostic capture and surgical intervention, with intraoperative systems commanding premium positioning.
- 3D Imaging:Cone-beam CT and fluoroscopic navigation enable real-time implant positioning and patient-specific workflows. Demand concentrates in surgical suites across Germany and the United States where intraoperative navigation is collapsing the boundary between pre-operative planning and operative execution.
- Digital Imaging:Mature, high-volume status across hospital radiology departments where PACS integration dominates procurement criteria.
- Fluoroscopy:Continuous X-ray imaging for dynamic joint assessment and surgical guidance.
- Advanced Visualization:Software-layer enhancements for anatomical mapping and measurement.
Digital Imaging holds the largest installed base. 3D Imaging shows the steepest expansion trajectory.
Application:
Application-specific requirements determine tube voltage calibration, mechanical design, and software configuration across product portfolios.
- Pre-operative Planning:CT-based templating and 3D reconstruction for arthroplasty and complex fracture management. Demand concentrates in hospital orthopedic departments where irreplaceable imaging modalities dominate facility budgets.
- Trauma Assessment:Rapid extremity radiography and fracture classification in emergency and urgent care settings.
- Joint Disorders:Weight-bearing capture mechanics for loading analysis in degenerative conditions.
- Bone Fractures:Standard radiography and fluoroscopy for acute injury evaluation.
Pre-operative Planning commands the highest equipment specification. Trauma Assessment generates the highest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany, the United States, and Japan supply the majority of advanced orthopedic imaging systems worldwide. These production centers feed distribution networks serving distinct regulatory environments and care delivery models across developed markets.
United States
Sports medicine clinics and ambulatory surgical centers drive demand for compact fluoroscopy and digital radiography platforms. The FDA's 510(k) premarket notification framework accelerates clearance timelines for digital radiography systems, compressing commercialization schedules for domestic manufacturers. Boston and Minneapolis medical device clusters anchor development of intraoperative navigation systems.
Germany
Orthopedic outpatient clinics invest heavily in mini-C-arm fluoroscopy units to capture trauma cases locally rather than referring to hospital emergency departments. The EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa orthopedic imaging systems, extending compliance timelines for European commercialization. Bavaria's medical technology corridor concentrates engineering talent for precision tube voltage calibration systems.
Japan
Aging demographics sustain demand for joint replacement imaging and post-operative monitoring equipment. The PMDA enforces JIS standards for electromagnetic compatibility that shape design specifications for equipment targeting domestic and East Asian deployment. Tokyo and Osaka metropolitan areas host concentrated procurement committees for hospital radiology departments.
United Kingdom
NHS procurement frameworks favor digital X-ray platforms with established PACS integration credentials for hospital radiology departments. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-market surveillance obligations. London and Manchester orthopedic day clinics negotiate service revenue unbundling contracts extending technical support agreements.
China
Domestic manufacturers expand capacity for extremity radiography systems serving provincial hospital networks. The NMPA governs device registration under GB standards that increasingly reference international electromagnetic compatibility benchmarks. Shanghai and Shenzhen medical device zones concentrate assembly operations for export-oriented compact MRI configurations.
Orthopedic Radiology Equipment Market Competitive Environment
Concentration sits with diversified medical technology conglomerates commanding installed base advantages and service revenue streams. Siemens Healthineers leverages its C-arm installed base across European orthopedic day clinics to sustain recurring maintenance contracts independent of new equipment transactions. Three archetypes dominate: imaging conglomerates with full-modality portfolios, specialized orthopedic equipment vendors with surgical navigation integration, and regional manufacturers competing on compact system cost structures. Competitive moves center on multi-year service agreement lock-ins and retrofit installation capabilities for existing clinic infrastructure.
Within the imaging conglomerate tier, Siemens Healthineers and GE Healthcare exemplify scale-driven positioning through digital X-ray and fluoroscopy platforms. Canon Medical Systems occupies a specialist position emphasizing compact MRI configurations designed for orthopedic suite retrofit installations. Among Japan-based precision manufacturers, Shimadzu represents engineering-intensive archetypes focused on tube voltage calibration and weight-bearing capture mechanics.
| Leading Market Players |
|---|
| Philips Healthcare |
| Canon Medical Systems |
| Orthoscan |
| Carestream |
| FUJIFILM |
| Ziehm Imaging |
| Siemens Healthineers |
| Shimadzu |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Multi-year service agreements lock in both supply access and price visibility for orthopedic imaging equipment across German and United States markets, compressing capital expenditure volatility while tethering clinic budgets to recurring maintenance obligations under EU MDR compliance frameworks.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales service bundling. Price differentiation hinges on FDA 510(k) clearance status and PACS integration complexity. Cost compression in economy-tier digital radiography intensifies as domestic Chinese manufacturers expand extremity system capacity. Orthopedic clinics in ambulatory settings exhibit highest price sensitivity, while hospital radiology departments prioritize throughput optimization over unit cost.
Supply Chain Analysis
Germany, the United States, and Japan anchor precision manufacturing for tube voltage calibration systems and weight-bearing capture mechanics. Component sourcing draws from specialized foundries for high-voltage generators, flat-panel detectors, and precision mechanical assemblies. Single-source vulnerability concentrates in rare-earth phosphor supply for digital detector fabrication. Distribution runs through direct sales channels for hospital systems and distributor networks for orthopedic day clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care ultrasound and portable MRI systems threaten traditional orthopedic radiology equipment incumbents by displacing referral-dependent imaging workflows into primary care settings.
For Market Incumbents: Fortify installed base retention through multi-year service contract lock-ins across European orthopedic day clinics. Deepen backward integration into tube voltage calibration engineering to constrain supplier expansion by competitors. Accelerate CE marking documentation investment ahead of EU MDR post-market surveillance enforcement. For New Entrants and Emerging Players: Aftermarket PACS integration services represent a service-layer gap where incumbents under-serve legacy hospital radiology departments. Target sports medicine clinics in the United States with compact fluoroscopy units designed for high-throughput injury assessment. Pursue distributor partnerships rather than direct sales to bypass capital planning cycle barriers. For Investors and Strategic Acquirers: Niche surgical navigation integrators with cone-beam CT capabilities command acquisition priority as intraoperative imaging converges with orthopedic intervention. Long-term viability frames around equipment vendors capturing recurring service revenue independent of capital refresh cycles. Monitor FDA 510(k) clearance velocity as inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend compliance timelines for Class IIa orthopedic imaging systems entering German and French markets. |
| Hospital System Partnership | PACS integration credentials determine procurement committee selection for digital X-ray platforms in NHS and United States hospital radiology departments. |
| Software Companion Development | Advanced visualization layers for anatomical mapping differentiate intraoperative navigation systems from commodity fluoroscopy hardware. |
| Reimbursement Strategy | Coverage determination for weight-bearing radiography mechanics influences orthopedic clinic capital allocation for joint loading analysis equipment. |
| FDA Submission | 510(k) premarket notification framework accelerates commercialization timelines for digital radiography systems targeting United States ambulatory surgical centers. |
Study Parameters
The analysis maps digital X-ray platforms, CT scanners, compact MRI configurations, and intraoperative navigation systems, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and orthopedic clinic administrators. Primary interviews with equipment vendors and service technicians combine with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up unit demand modeling triangulates against top-down capital expenditure estimates from healthcare facility financial disclosures.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span product type, end-user facility category, technology tier, and application purpose. CAGRs derive from installed base growth rates and replacement cycle analysis. Forecast inputs incorporate EU MDR compliance timeline shifts and ambulatory surgical center imaging capability expansion patterns.
Underlying assumptions cover regulatory pathway stability, capital expenditure continuity, and referral pattern displacement velocity, with deviation risk concentrated in electromagnetic compatibility standard revisions and PACS interoperability mandate changes. Recalibration cycles align with material shifts in FDA clearance velocity and EU MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Echocardiography Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Portable MRI Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
South America MRI Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
China Digital X-Ray Market