
 Global Interventional Oncology Market | 2026-2036
Global Interventional Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interventional Oncology Market Foresight
Asset-light leasing models for imaging and ablation suites is rewriting competitive entry dynamics in interventional oncology. Boston Scientific Corporation leverages its end-to-end embolization portfolio to anchor hospital system contracts across North America. Merit Medical Systems sustains manufacturing scale in catheter-based delivery systems that competes on cost with integrated multinationals. Siemens Healthineers dominates the imaging equipment layer, where its hybrid angiography systems control the procedural workflow and extend into software-driven treatment planning.
Interventional oncology encompasses percutaneous and endovascular techniques that destroy or devascularize tumors through thermal, chemical, or mechanical means, typically requiring image guidance via CT, MRI, or fluoroscopy with sub-millimeter targeting accuracy. Its primary purpose is to treat unresectable or poor-surgical-risk malignancies while preserving surrounding healthy tissue. Ablation devices command the largest revenue share among product types due to recurring catheter purchases and disposable energy applicators. Embolization systems represent the fastest-expanding segment as transarterial chemoembolization gains adoption for hepatocellular carcinoma. Liver cancer leads therapy area demand, reflecting the established clinical evidence base and reimbursement pathways for locoregional treatment.
The FDA regulates ablation and embolization devices through the premarket notification pathway, while the EU MDR imposes stricter clinical evidence requirements for class III implantable instruments. Japan's PMDA accelerates reviews for combination products that pair drug-eluting beads with delivery catheters, reshaping product development priorities. Stakeholders must monitor how reimbursement divergence between Medicare's transitional pass-through payments and Germany's DRG refinements affects site-of-care migration from inpatient to ambulatory settings.
Market Dynamics
The interventional oncology market pivots on the tension between hospital capital constraints and the clinical imperative to expand tumor ablation capacity. Equipment leasing consortia are rewriting site-of-care economics, compressing payback periods for hybrid angiography suites while fragmenting vendor lock-in across procurement networks.
Growth Catalysts
- Transarterial chemoembolization protocols:Hepatocellular carcinoma treatment guidelines in Germany now mandate locoregional therapy as first-line for intermediate-stage patients, expanding reimbursable indications.
- FDA breakthrough device designation:Novel irreversible electroporation systems gain accelerated commercialization timelines, compressing the gap between clinical validation and hospital adoption.
- Japan's PMDA combination product pathway:Drug-eluting bead catheter pairings receive priority review status, redirecting R&D investment toward integrated delivery platforms.
Market Restraints
- Disposable catheter cost concentration:Single-use ablation applicators account for 60-70% of per-procedure spend, creating margin pressure at high-volume centers.
- Imaging equipment supplier concentration:Hybrid angiography system manufacturing concentrates among three vendors, exposing procurement officers to extended lead times and limited price leverage.
- EU MDR clinical evidence requirements:Class III implantable instrument classifications demand expanded premarket trials, extending certification timelines by 18-24 months for novel ablation technologies.
Strategic Opportunities
- Ambulatory surgical center migration:Medicare's transitional pass-through payment structure creates margin arbitrage for same-day tumor ablations, redirecting volume from inpatient wards in the United States.
- MRI-guided focused ultrasound convergence:Real-time thermometry integration with closed-loop energy delivery enables non-invasive uterine fibroid and bone metastasis protocols.
- India's PLI scheme for medical devices:Domestic catheter manufacturing incentives attract contract manufacturers seeking cost-competitive export platforms for Southeast Asian markets.
Industry Challenges
- Interventional radiology fellowship scarcity:Training program capacity constraints limit the specialist pipeline needed to staff expanded ablation programs at community hospitals.
- Legacy PACS integration complexity:Treatment planning software from Siemens Healthineers requires middleware layers to communicate with third-party electronic health record systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interventional Oncology Market |
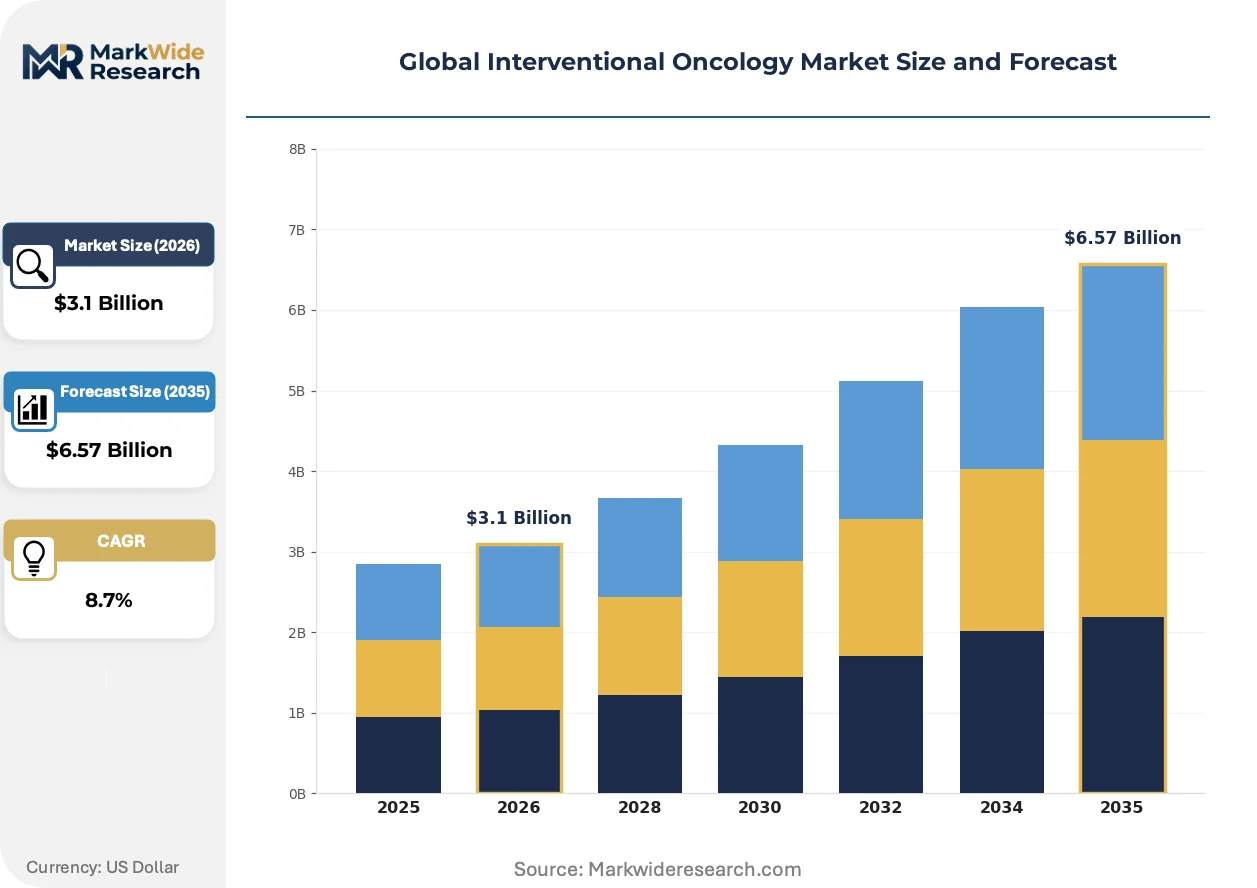
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ablation Devices, Embolization Systems, Imaging Equipment, Biopsy Needles Therapy Area: Liver Cancer, Lung Neoplasms, Kidney Tumors, Bone Metastases, Soft Tissue Sarcomas End User: Specialized Clinics, Ambulatory Surgical Centers, Cancer Institutes, Diagnostic Centers Deployment: Hospital Integration, Standalone Systems, Cloud-Based Platforms, Hybrid Installations |
| Companies Covered | AngioDynamics, Merit Medical Systems, Boston Scientific Corporation, Johnson & Johnson, Siemens Healthineers, Medtronic, Cook Medical, Stryker Corporation, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interventional Oncology Market Shifts & Advancements
Artificial intelligence is compressing the planning-to-procedure interval for tumor ablation, embedding predictive modeling directly into imaging workstations. Three developments are restructuring competitive positioning.
Artificial intelligence-powered segmentation algorithms now automate tumor boundary delineation across multiphase CT datasets, reducing planning time from 45 minutes to under 10 minutes. Academic medical centers in the United States and Germany are deploying these tools for complex hepatic and renal lesions. The technology is digitizing the radiologist's role from manual contouring to protocol supervision, compressing staffing requirements while elevating procedural throughput targets.
Japan's PMDA revised its guidance on software-as-a-medical-device in 2023, creating a distinct review track for AI-enabled treatment planning modules. Manufacturers must now submit algorithm training datasets and performance validation across diverse patient populations. Ablation device companies with integrated imaging partnerships gain first-mover advantage, while standalone software vendors face extended qualification timelines.
Hospital procurement committees are unbundling after-sales service contracts from equipment leases, negotiating separate performance-based maintenance agreements. German university hospitals pioneered this model, tying vendor payments to system uptime guarantees and software update cadence. The shift is most visible in North Rhine-Westphalia, where purchasing consortia aggregate demand across multiple sites to extract service-level concessions.
Global Interventional Oncology Market Segmentation
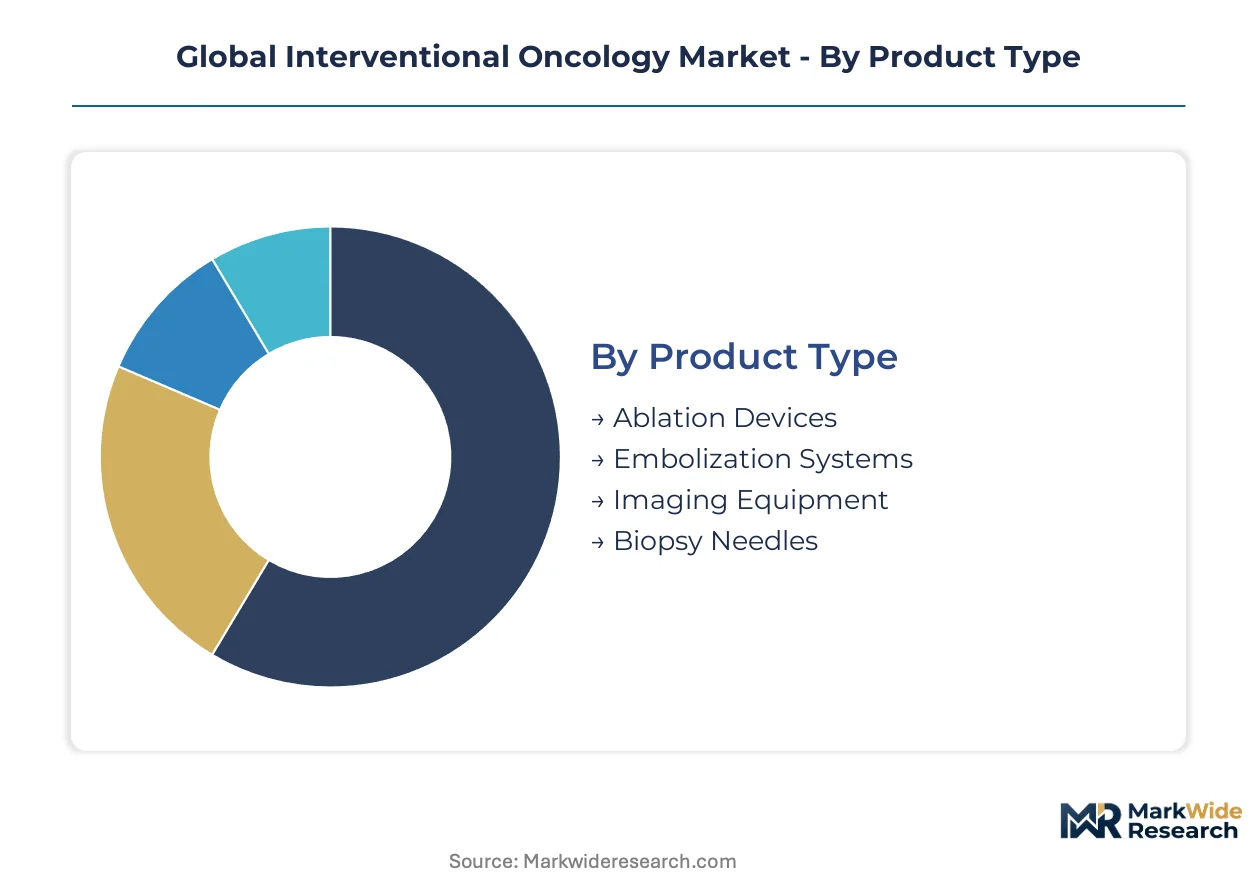
Product configuration in interventional oncology determines capital deployment cycles, consumable replenishment rhythms, and the intensity of vendor service relationships. Segmentation clarity enables procurement committees to match equipment specifications against procedural volume forecasts and reimbursement pathways.
Product Type:
After-sales-service intensity varies sharply across this category, with imaging platforms demanding multi-year maintenance contracts and disposable applicators requiring just-in-time inventory management.
- Ablation Devices:Thermal and electrical energy delivery systems utilizing radiofrequency, microwave, cryoablation, or irreversible electroporation mechanisms. Demand concentrates in Germany's university hospital networks where locoregional therapy protocols for hepatocellular carcinoma drive catheter consumption. Single-use energy applicators generate recurring revenue streams that anchor long-term vendor contracts.
- Embolization Systems:Catheter-based delivery platforms for transarterial chemoembolization and radioembolization incorporating drug-eluting beads or Y-90 microspheres. Japanese cancer institutes prioritize these systems following PMDA's combination product pathway acceleration, redirecting manufacturer R&D toward integrated bead-catheter pairings.
- Imaging Equipment:Hybrid angiography systems, CT guidance platforms, and MRI-compatible navigation workstations from concentrated vendor bases.
- Biopsy Needles:Percutaneous sampling instruments for tissue confirmation preceding ablation procedures.
By volume, Ablation Devices leads. By expansion trajectory, Embolization Systems is climbing the fastest.
Therapy Area:
Clinical evidence depth and reimbursement maturity separate high-investment segments from emerging indications still building procedure economics.
- Liver Cancer:Hepatocellular carcinoma and metastatic colorectal lesions represent the most established interventional oncology application. German treatment guidelines mandate locoregional therapy as first-line for intermediate-stage patients, cementing reimbursable demand. Transarterial chemoembolization protocols here command the deepest clinical evidence base.
- Lung Neoplasms:Percutaneous ablation of primary and metastatic pulmonary lesions via microwave or cryoablation approaches. United States cancer institutes are expanding these programs as surgical candidacy constraints drive minimally invasive alternatives for high-risk patients.
- Kidney Tumors:Thermal ablation of renal cell carcinoma lesions preserving nephron function.
- Bone Metastases:Palliative ablation and cementoplasty for pain management in skeletal metastatic disease.
- Soft Tissue Sarcomas:Emerging application for limb-sparing ablation in unresectable extremity tumors.
By procedure volume, Liver Cancer dominates. By clinical pipeline activity, Lung Neoplasms is gaining share fastest.
End User:
Site-of-care migration patterns are fragmenting procurement authority across institutional types with diverging capital constraints.
- Specialized Clinics:Dedicated interventional radiology facilities focusing on outpatient tumor ablation procedures. These settings in the United States exploit Medicare's transitional pass-through payment structure to capture margin arbitrage from hospital-based delivery.
- Ambulatory Surgical Centers:Same-day procedural venues requiring compact imaging integration and rapid patient throughput. Equipment leasing consortia are rewriting capital access for these operators.
- Cancer Institutes:Comprehensive oncology centers combining ablation with systemic therapy protocols.
- Diagnostic Centers:Imaging-focused facilities expanding into therapeutic interventions.
By installed base, Cancer Institutes lead. By volume growth rate, Ambulatory Surgical Centers is expanding most quickly.
Deployment:
System architecture choices determine workflow integration depth and the extent of vendor lock-in across hardware and software layers.
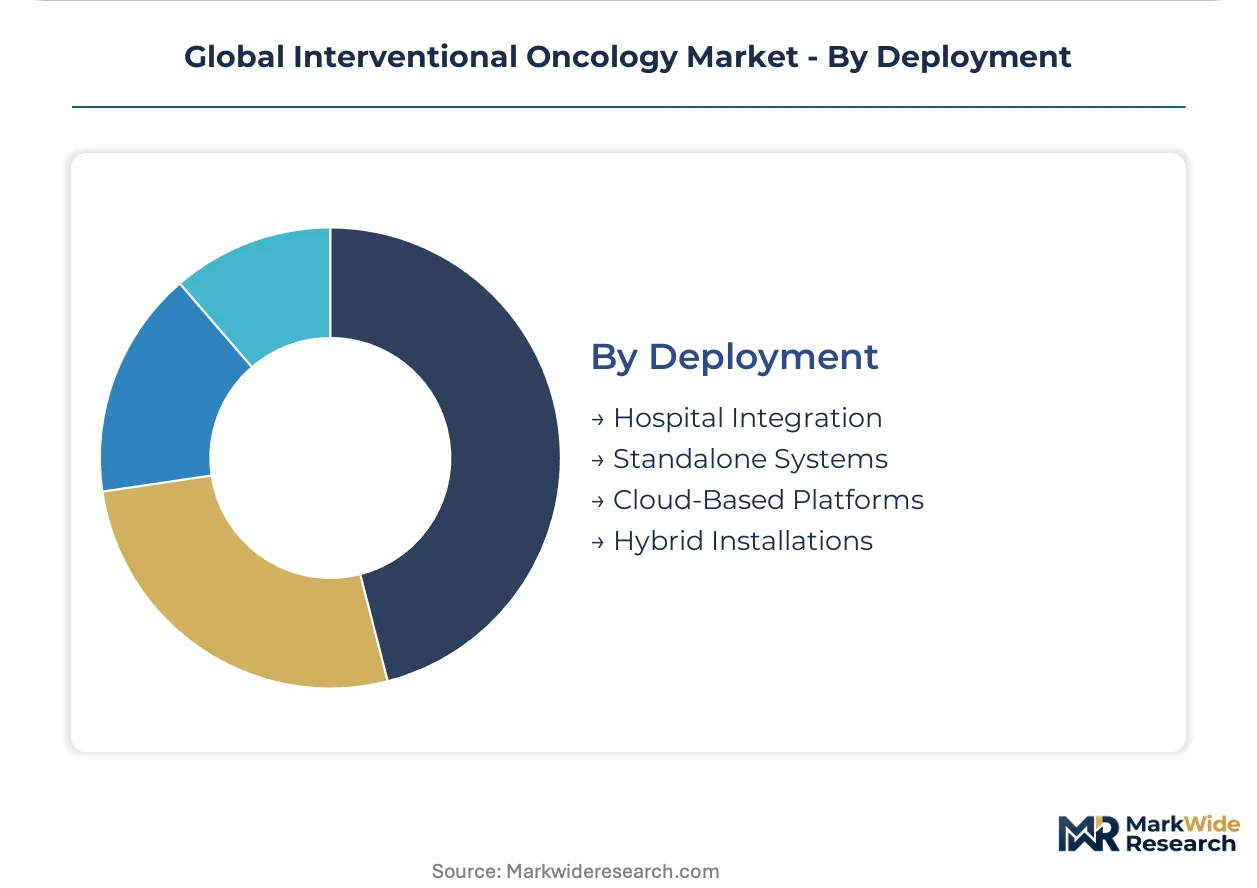
- Hospital Integration:Embedded angiography suites within surgical or radiology departments with direct EMR connectivity. German university hospitals in North Rhine-Westphalia pioneered unbundled service contracts here, tying vendor payments to uptime guarantees.
- Standalone Systems:Mobile or dedicated ablation platforms operating independently of institutional imaging infrastructure.
- Cloud-Based Platforms:Remote treatment planning and AI-powered segmentation tools accessed via subscription models.
- Hybrid Installations:Combined angiography-CT-MRI environments enabling multi-modal procedural navigation.
By deployment share, Hospital Integration leads. By new installation growth, Cloud-Based Platforms is advancing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel ablation technologies in the United States, while Japan's PMDA combination product reforms redirect manufacturer R&D priorities. Germany's DRG refinements and India's PLI scheme for medical devices are reshaping procurement economics across their respective hospital networks.
United States
Cancer institutes are expanding minimally invasive tumor treatment programs as surgical candidacy constraints drive demand for percutaneous alternatives. Medicare's transitional pass-through payment structure creates margin arbitrage for same-day tumor ablations performed at ambulatory surgical centers. Major academic medical centers in Boston and the Research Triangle deploy AI-powered segmentation algorithms for complex hepatic lesions.
Germany
University hospitals integrate interventional radiology with oncology departments as locoregional therapy guidelines mandate first-line treatment for intermediate-stage hepatocellular carcinoma. The country's DRG refinements affect site-of-care migration from inpatient to ambulatory settings. Purchasing consortia in North Rhine-Westphalia aggregate demand across multiple sites to extract service-level concessions from imaging equipment vendors.
Japan
Cancer institutes prioritize transarterial chemoembolization systems following PMDA's priority review status for drug-eluting bead catheter pairings. The regulator's 2023 software-as-a-medical-device guidance creates distinct review tracks for AI-enabled treatment planning modules. Tokyo and Osaka academic centers lead adoption of integrated delivery platforms combining embolization with real-time navigation.
India
Domestic catheter manufacturing incentives under the PLI scheme attract contract manufacturers seeking cost-competitive export platforms for Southeast Asian markets. Equipment leasing consortia are rewriting capital access for standalone interventional radiology facilities in Delhi and Mumbai. Regional cancer centers in Maharashtra and Gujarat expand ablation capacity through public-private partnerships.
China
Hospital procurement committees unbundle after-sales service contracts from equipment leases as NMPA streamlines premarket notification pathways for ablation devices. Hybrid angiography system demand concentrates in tertiary hospitals in Beijing and Shanghai. Provincial medical device innovation zones in Jiangsu and Guangdong incubate domestic catheter manufacturers targeting price-sensitive community hospitals.
Global Interventional Oncology Market Competitive Landscape
On the supply side, the industry is consolidating around integrated imaging-therapy platforms while fragmenting across disposable catheter niches. Three strategic archetypes dominate: end-to-end embolization portfolio holders, imaging equipment layer controllers, and manufacturing-scale catheter specialists. Competitive moves concentrate on strategic partnerships between device manufacturers and AI software vendors, plus geographic expansion through equipment leasing consortia.
Within the integrated systems tier, Siemens Healthineers exemplifies imaging equipment dominance where hybrid angiography systems control procedural workflow. Boston Scientific Corporation and Merit Medical Systems occupy positions across the catheter-based delivery spectrum, with the former anchoring hospital system contracts and the latter competing on manufacturing scale. These three companies represent the converging pressures between capital equipment concentration and consumable cost competition.
| Leading Market Players |
|---|
| AngioDynamics |
| Merit Medical Systems |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Siemens Healthineers |
| Medtronic |
| Cook Medical |
| Stryker Corporation |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Jiangsu Province's catheter manufacturing clusters anchor global disposable supply, with capacity expansion in domestic innovation zones feeding downstream pricing leverage into European and North American procurement negotiations. Equipment vendors unbundle service contracts from hardware leases to defend margin structures against cost pressure from high-volume ambulatory centers.
Pricing Analysis
Certification level creates the primary spread across the interventional oncology equipment tier, with FDA breakthrough-designated ablation systems commanding premium positioning against CE-marked alternatives in German university hospital procurement. Three-tier pricing structure across premium, standard, and economy levels segments the disposable catheter market, where single-use applicator costs concentrate 60-70% of per-procedure spend. Cost compression in standard-tier catheters intensifies because India's PLI scheme attracts contract manufacturers to export platforms. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while cancer institutes prioritize clinical outcome metrics over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hybrid angiography system components and precision catheter assemblies. Manufacturing concentrates in Germany for imaging equipment, Japan for drug-eluting bead formulations, and India for cost-competitive catheter production. Raw material dependencies include nickel-titanium alloys for steerable catheters, rare-earth elements for MRI-compatible navigation, and polymer substrates for drug-eluting matrices. Single-source vulnerability concentrates in hybrid angiography system manufacturing among three vendors. Distribution runs through equipment leasing consortia and group purchasing organizations that aggregate hospital demand across multi-site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interventional oncology functions as a defensive-moat market where regulatory entrenchment via FDA breakthrough designation and EU MDR certification timelines creates structural barriers that protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Insulate market position by deepening backward integration into catheter manufacturing to capture margin from disposable consumables, and by anchoring multi-year service contracts with uptime guarantees that raise switching costs for hospital procurement committees. Emerging AI-enabled treatment planning vendors pose substitution risk to standalone hardware vendors lacking software partnerships.
For New Entrants and Emerging Players: Pursue white-space opportunity in cloud-based treatment planning platforms serving ambulatory surgical centers lacking capital for embedded imaging infrastructure, and in MRI-guided focused ultrasound systems for non-invasive bone metastasis protocols. India's regional cancer centers present the most penetrable geography given PLI scheme incentives and public-private partnership expansion. Lead with equipment leasing consortium partnerships rather than direct capital sales to bypass hospital budget constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because single-use catheter replenishment cycles and multi-year imaging service contracts generate predictable cash flows insulated from capital expenditure cyclicality. Acquisition targets should concentrate on AI-powered segmentation software vendors with PMDA or FDA qualification progress, where imaging equipment incumbents face capability gaps. Watch for inflection in interventional radiology fellowship program expansion rates as the specialist pipeline constraint that limits procedural volume growth.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated commercialization timelines compress validation-to-adoption gaps for novel ablation technologies. |
| Hospital System Partnership | End-to-end embolization portfolios anchor multi-year contracts across integrated delivery networks. |
| Software Companion Development | AI-powered segmentation modules digitize radiologist workflows and elevate procedural throughput targets. |
| Reimbursement Strategy | Medicare transitional pass-through payment structures enable margin arbitrage for ambulatory site migration. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend certification timelines and raise competitive barriers. |
Research Methodology
Initial hypotheses were tested against primary input from interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated with top-down equipment shipment data.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, therapy area, end user, and deployment architecture dimensions. CAGRs derived from procedure volume trajectories, replacement cycle assumptions for imaging equipment, and consumable replenishment rates. Forecast inputs included interventional radiology fellowship program capacity, DRG refinement schedules, and regulatory pathway timelines.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device tariff regimes, or reimbursement rate adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding procedural adoption curves and equipment replacement timelines. Material shifts in FDA breakthrough designation criteria or EU MDR classification interpretations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Head and Neck Cancer Drugs Market
Oncology
Bone Metastasis Market
Oncology
Cancer API Market
Oncology
Lung Cancer Treatment Market
Oncology
Throat Cancer Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Thymus Cancer Market
Oncology
Ustekinumab Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
AI in Oncology Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Stomach Cancer Treatment Market
Oncology
Metastatic Cancer Drug Market
Oncology
Pancreatic Cancer Therapeutics Market