
 Fluoroscopy C-Arms Market | 2026-2036
Fluoroscopy C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroscopy C-Arms Market Intelligence
The fluoroscopy C-arms sector is restructuring around a sharp split between premium flat-panel detector systems and commodity image intensifier units. GE Healthcare leverages in-house detector manufacturing to sustain margin control across hospital networks. Koninklijke Philips N.V. anchors its position through software-integrated cardiovascular imaging suites. Siemens Healthineers differentiates via 3D rotational angiography capabilities that command premium placement in academic medical centers.
Fluoroscopy C-arms are X-ray imaging systems with C-shaped gantries that enable real-time intraoperative visualization, typically operating at 30-110 kV tube voltage with pulsed or continuous exposure modes for surgical guidance. Flat panel detector technology now dominates new installations due to superior dose efficiency and spatial resolution compared to legacy image intensifiers. Mobile C-arms capture the fastest growth trajectory as ambulatory surgery centers expand orthopedic and pain management procedures outside hospital settings. Digital fluoroscopy systems command the deepest margin pools where high-definition imaging and 3D reconstruction modules justify premium pricing against basic fluoroscopic units.
FDA 510(k) premarket notification requirements govern device clearance timelines in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for CE marking access across European markets. Japan's PMDA enforces JIS-compliant quality management systems that shape product localization strategies for Asia-Pacific entry. Stakeholders must monitor evolving radiation dose reporting mandates and cybersecurity standards for connected imaging systems as regulatory frameworks harden across major markets.
Market Dynamics
The fluoroscopy C-arms sector is bifurcating sharply between premium flat-panel detector systems and commodity image intensifier units, with flat-panel technology commanding placement in academic medical centers while price-sensitive buyers retain legacy equipment longer than anticipated replacement cycles.
Growth Catalysts
- MDR CE marking pathways:The EU Medical Device Regulation's stricter clinical evidence standards are accelerating R&D investment in next-generation detector materials among manufacturers seeking European market access.
- Ambulatory surgery center expansion:Orthopedic and pain management procedures are migrating outside hospital settings, creating concentrated demand pull for mobile C-arm configurations with compact footprints and rapid deployment capabilities.
- Flat-panel detector maturation:Superior dose efficiency and spatial resolution compared to legacy image intensifiers is now compelling enough to overcome capital budget inertia in mid-tier hospital networks.
Market Restraints
- Flat-panel detector supply concentration:Manufacturing of high-performance amorphous silicon and CMOS sensors concentrates among a handful of East Asian component suppliers, exposing OEMs to input cost volatility and allocation risk.
- FDA 510(k) timeline friction:Premarket notification requirements for software-integrated cardiovascular imaging suites extend product development cycles, compressing revenue recognition windows for multi-modality platforms.
- Image intensifier residual demand:Budget-constrained facilities in secondary and tertiary markets continue procuring legacy systems, fragmenting volume across incompatible technology generations and complicating service infrastructure.
Strategic Opportunities
- Japan PMDA localization:JIS-compliant quality management systems create barriers to entry that reward early investment in product adaptation for Asia-Pacific's highest-value imaging market.
- 3D rotational angiography convergence:Integration of cone-beam CT reconstruction with conventional fluoroscopy workflows is opening premium placement opportunities in hybrid operating suites for complex orthopedic and neurovascular interventions.
- Cybersecurity certification tailwinds:Evolving standards for connected imaging systems are creating first-mover advantages for vendors with pre-validated network security architectures against hospital IT procurement checklists.
Industry Challenges
- Clinical engineering talent scarcity:Hospitals face persistent gaps in recruiting biomedical technicians capable of servicing digital fluoroscopy systems with embedded software and networked diagnostics, extending equipment downtime and straining OEM service contracts.
- Legacy system integration complexity:PACS and EMR connectivity requirements for new flat-panel installations often demand costly middleware development to bridge incompatible data formats from retained image intensifier fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroscopy C-Arms Market |
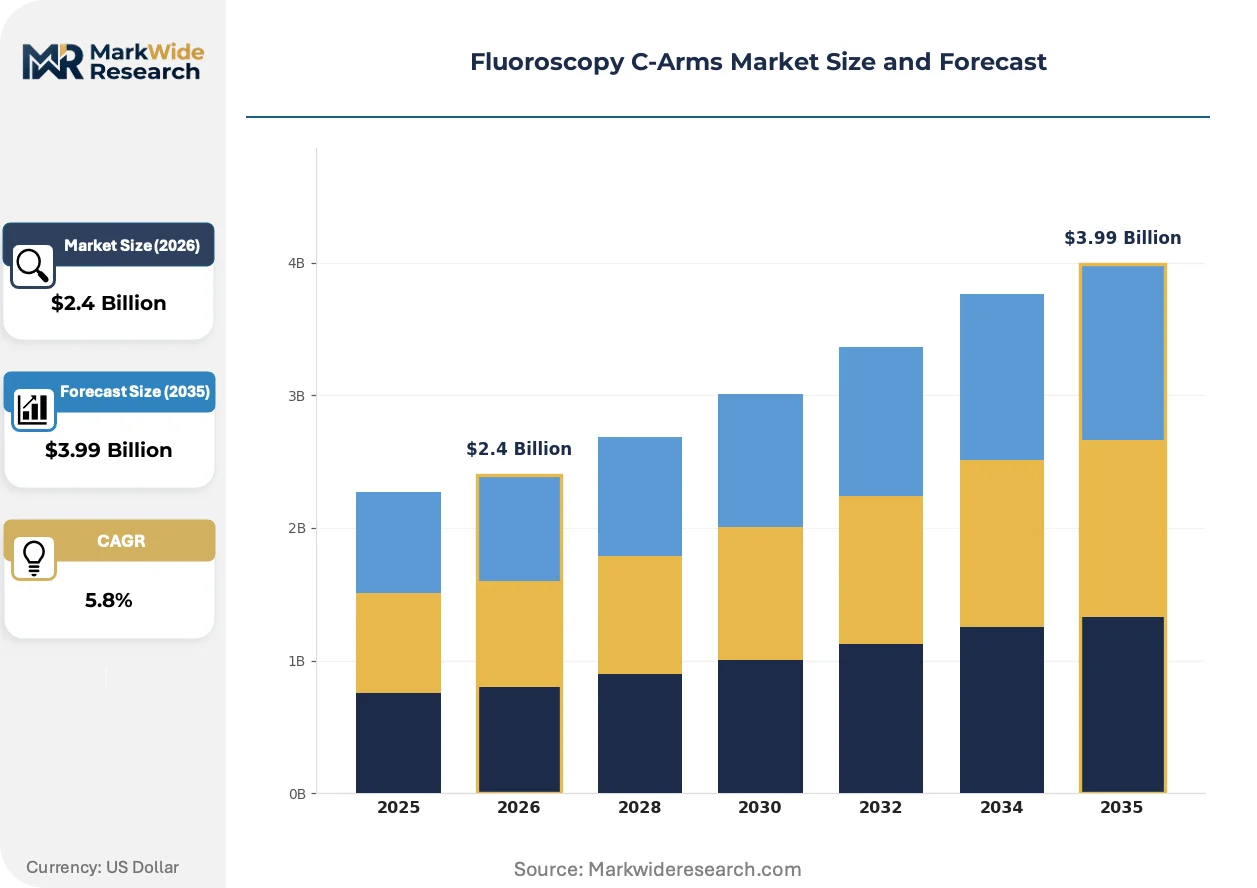
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile C-Arms, Fixed C-Arms, Compact C-Arms, Mini C-Arms, Digital C-Arms Application: Orthopedics, Cardiovascular Procedures, Gastroenterology, Urology, Pain Management End User: Ambulatory Surgery Centers, Diagnostic Imaging Centers, Specialty Clinics, Academic Medical Centers Technology: Flat Panel Detector, Image Intensifier, Digital Fluoroscopy, 3D Imaging, High-Definition Imaging |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Ziehm Imaging GmbH, Shimadzu Corporation, Hologic, Inc., CANON MEDICAL SYSTEMS CORPORATION, FUJIFILM Corporation, Genoray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroscopy C-Arms Market Strategic Shifts & Innovations
Real-time intraoperative visualization is absorbing computational imaging advances that were previously confined to diagnostic radiology, compressing the capability gap between surgical guidance and preoperative planning systems across hospital capital budgets.
CMOS flat-panel detectors are absorbing photon-counting sensitivity thresholds that previously required cryogenic cooling systems, enabling spectral imaging capabilities in mobile C-arm form factors. Ambulatory surgery centers in Germany and the United States are adopting these systems for outpatient spine and trauma procedures at replacement rates exceeding hospital-based installations. The technology is absorbing margin pressure from commoditized image intensifier segments by creating definitive performance differentiation that justifies premium pricing against refurbished equipment.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for CE-marked fluoroscopy systems, increasing compliance infrastructure costs but also creating competitive moats for established manufacturers with robust quality management systems. Japanese and Australian regulators are observing MDR implementation outcomes to calibrate their own device approval frameworks, suggesting regulatory convergence toward evidence-heavy pathways. Cardiovascular imaging suites with software-integrated 3D reconstruction modules face the steepest compliance burden, prompting vendors to pre-position clinical evidence packages during product development rather than post-hoc regulatory submission.
Hospital procurement departments are unbundling after-sales service contracts from equipment financing, treating preventive maintenance and software updates as separately negotiable spend categories. This pattern is most pronounced in United States health systems with centralized supply chain functions, where multi-hospital networks leverage aggregate service volume to extract performance-based contract terms. Independent service organizations are capturing portions of legacy image intensifier maintenance that OEMs had treated as captive revenue, fragmenting the post-installation value chain and compressing service margin pools for manufacturers.
Fluoroscopy C-Arms Market Segmentation
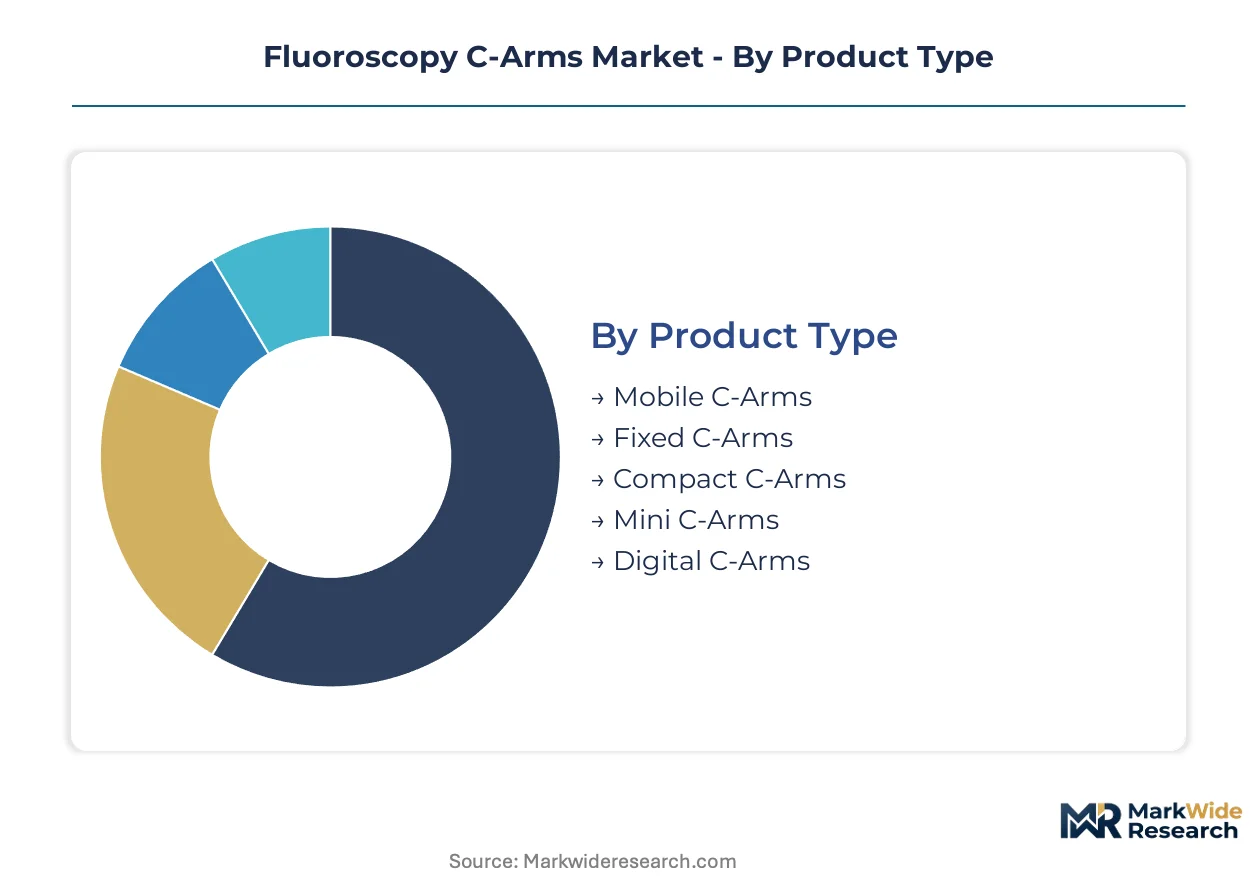
The fluoroscopy C-arms market fragments across equipment mobility, clinical application, and detector technology in ways that directly shape procurement timelines and service contract structures. Understanding these segment boundaries clarifies why replacement cycles vary dramatically between hospital networks and outpatient facilities.
Product Type:
Upgrade urgency differs sharply across mobility tiers, with compact footprints commanding ambulatory investment while fixed installations anchor hybrid operating suite construction.
- Mobile C-Arms:Wheeled gantry systems with motorized positioning enable rapid redeployment between procedure rooms. Demand concentrates in United States ambulatory surgery centers where same-day joint procedures require intraoperative imaging without fixed-room capital commitment.
- Fixed C-Arms:Ceiling-mounted or floor-fixed installations with integrated patient tables serve dedicated cardiovascular and interventional suites. Academic medical centers in Germany and Japan prioritize these configurations for complex electrophysiology workflows despite longer installation timelines.
- Compact C-Arms:Reduced footprint systems bridge mobile flexibility with fixed-system stability for mid-volume orthopedic practices.
- Mini C-Arms:Extremity-focused systems with limited field of view target podiatry and hand surgery clinics.
- Digital C-Arms:Fully digital signal chain architectures eliminate analog-to-digital conversion stages for dose-optimized imaging.
Volume placements concentrate in mobile configurations; the faster expansion belongs to compact systems.
Application:
Procedure reimbursement rates and clinical outcome evidence intensity determine which applications justify premium detector investments versus legacy equipment retention.
- Orthopedics:Fracture reduction, joint replacement, and spine instrumentation procedures dominate C-arm utilization hours. United States orthopedic surgery centers drive replacement demand as outpatient migration accelerates for knee and shoulder procedures.
- Cardiovascular Procedures:Percutaneous coronary intervention and electrophysiology mapping demand real-time visualization with sub-millimeter spatial resolution. Japanese academic medical centers anchor premium system placements where 3D rotational angiography justifies capital allocation against diagnostic catheterization volume.
- Gastroenterology:ERCP and biliary interventions utilize C-arm guidance for cannulation and stent placement.
- Urology:Percutaneous nephrolithotomy and stent positioning procedures require limited fluoroscopy exposure.
- Pain Management:Epidural steroid injections and nerve blocks employ C-arm verification for needle placement accuracy.
Procedure volume clusters in orthopedic applications; cardiovascular workflows generate the steepest expansion trajectory for premium system placements.
End User:
Capital access and utilization intensity create distinct procurement patterns across facility types, with centralized purchasing power reshaping vendor negotiation leverage.
- Ambulatory Surgery Centers:Freestanding facilities with focused procedure portfolios prioritize rapid deployment and compact storage. United States multi-site operators aggregate purchasing volume to extract performance-based service terms from OEMs.
- Diagnostic Imaging Centers:Dedicated imaging facilities balance throughput economics against modality diversification needs.
- Specialty Clinics:Single-specialty practices with high procedure volume concentrate demand for specific C-arm configurations matched to their service mix.
- Academic Medical Centers:Teaching hospitals with research mandates and complex case mixes anchor premium system placements. German university hospitals command 3D rotational angiography capabilities for hybrid operating suite construction where neurovascular and orthopedic interventions converge.
Procurement volume concentrates in ambulatory surgery centers; academic medical centers drive technology adoption for next-generation detector platforms.
Technology:
Detector architecture choices now determine regulatory compliance pathways and cybersecurity certification requirements alongside imaging performance.
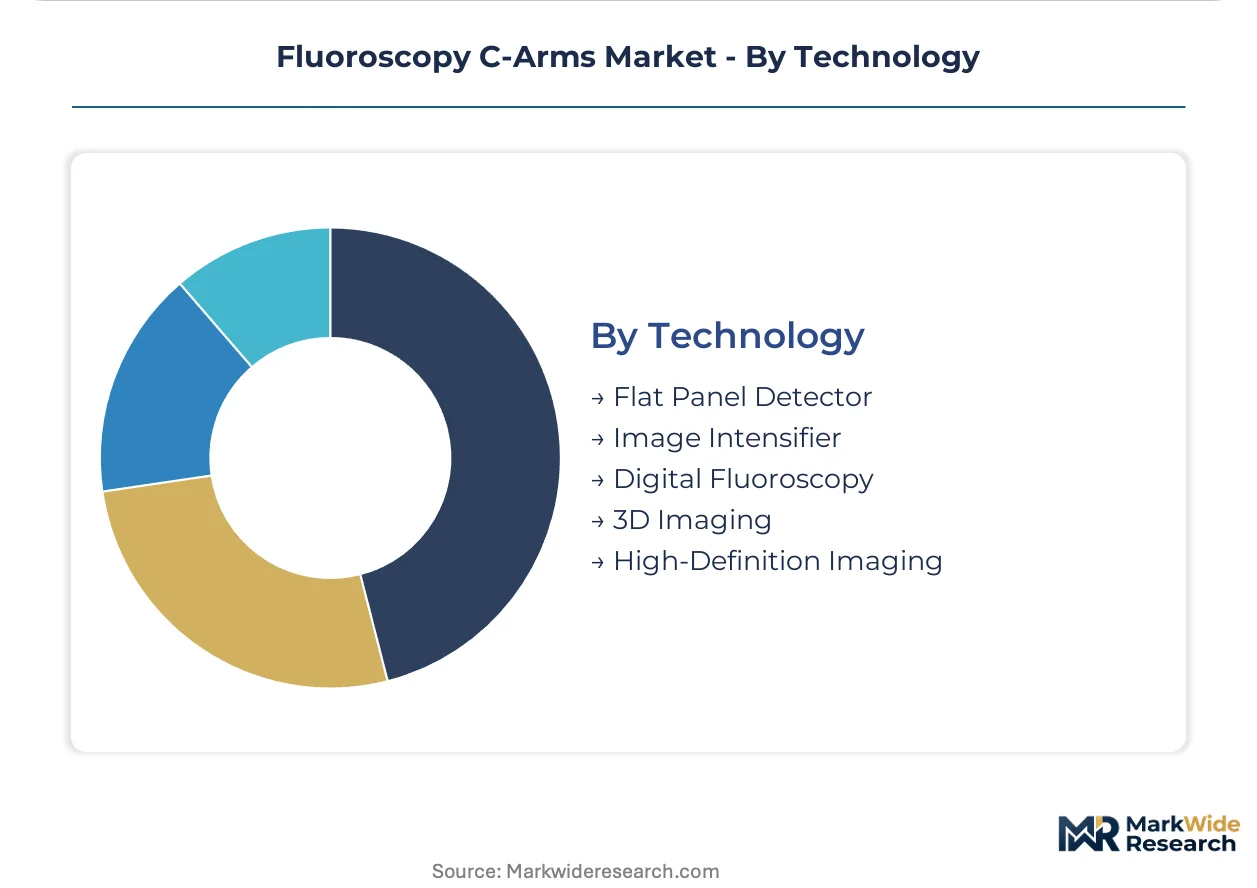
- Flat Panel Detector:Amorphous silicon or CMOS sensor arrays with direct digital readout deliver superior dose efficiency and spatial resolution. MDR CE marking requirements in Europe accelerate R&D investment in next-generation detector materials as manufacturers pre-position clinical evidence packages.
- Image Intensifier:Vacuum tube-based analog systems with phosphor input screens persist in budget-constrained secondary markets. Tertiary hospitals in Japan retain legacy fleets longer than anticipated replacement cycles, fragmenting service infrastructure across incompatible technology generations.
- Digital Fluoroscopy:Pulsed exposure modes with digital image processing enable dose reduction protocols for pediatric and interventional applications.
- 3D Imaging:Cone-beam CT reconstruction integrated with conventional fluoroscopy creates hybrid visualization for complex orthopedic and neurovascular workflows.
- High-Definition Imaging:Enhanced spatial resolution modes with specialized filtration target microvascular and fine bone detail requirements.
New installations concentrate in flat panel detector configurations; 3D imaging capabilities are gaining share fastest in hybrid operating suite deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors fluoroscopy C-arm procurement intensity through its dense cluster of orthopedic surgery centers and health system headquarters. Hospital capital expenditure patterns in this metropolitan corridor concentrate demand for mobile configurations serving outpatient joint procedures.
United States
Ambulatory surgery center expansion in Texas and Florida drives concentrated demand for compact mobile C-arms with rapid deployment capabilities. FDA 510(k) premarket notification pathways govern clearance timelines for software-integrated cardiovascular imaging suites. The Minneapolis-St. Paul corridor hosts health system procurement headquarters that aggregate multi-hospital purchasing volume to extract performance-based service terms.
Germany
University hospitals in Bavaria and Baden-Württemberg prioritize fixed C-arm installations with 3D rotational angiography for hybrid operating suite construction. EU MDR CE marking requirements impose stricter clinical evidence standards that accelerate R&D investment in next-generation detector materials. The Munich medical technology cluster concentrates manufacturing engineering talent for precision gantry systems serving academic medical centers.
Japan
Academic medical centers in Tokyo and Osaka anchor premium system placements where electrophysiology workflow volume justifies capital allocation against diagnostic catheterization throughput. PMDA enforces JIS-compliant quality management systems that shape product localization strategies for Asia-Pacific market entry. The Kobe biomedical device corridor concentrates regulatory consulting expertise for Asia-Pacific registration pathways.
China
Tertiary hospitals in Shanghai and Beijing expand fluoroscopy infrastructure as interventional cardiology procedure volume rises. NMPA device registration requirements govern market access timelines for imported imaging systems. The Suzhou industrial park hosts contract manufacturing operations for detector component assembly serving domestic OEMs.
India
Corporate hospital chains in Maharashtra and Karnataka upgrade imaging infrastructure as medical tourism and domestic surgical volume expand. CDSCO medical device rules govern import licensing and quality standards for C-arm installations. The Hyderabad medical device cluster concentrates service engineering capabilities for refurbished equipment refurbishment and technical training.
Fluoroscopy C-Arms Market Key Industry Players
Premium-margin players sit above commodity-margin players across detector technology tiers, with flat-panel systems commanding placement in academic centers while image intensifier configurations serve budget-constrained secondary markets. The vendor base organizes around three strategic archetypes: diversified imaging conglomerates with captive detector manufacturing, specialized surgical imaging firms with focused orthopedic portfolios, and regional equipment assemblers serving price-sensitive procurement channels. Competitive moves concentrate on backward integration into sensor fabrication and strategic partnerships with ambulatory surgery center networks.
Among diversified imaging conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions exemplifying premium-tier market presence through integrated software-hardware portfolios. Siemens Healthineers represents the academic medical center anchor archetype, with German corporate structure signaling European regulatory pre-positioning. Ziehm Imaging GmbH exemplifies the specialized surgical imaging firm archetype, its Bavarian base indicating proximity to German precision engineering supply chains.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Ziehm Imaging GmbH |
| Shimadzu Corporation |
| Hologic, Inc. |
| CANON MEDICAL SYSTEMS CORPORATION |
| FUJIFILM Corporation |
| Genoray Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Ambulatory surgery center networks in the United States concentrate procurement volume for mobile C-arm configurations, anchoring a value-based pricing model where capital expenditure ties to procedure throughput guarantees and uptime commitments rather than equipment acquisition alone. This buyer concentration forces OEMs to unbundle service contracts from hardware financing, compressing margin pools across flat-panel detector tiers while amplifying price transparency in secondary markets.
Pricing Analysis
Throughput-linked value pricing anchors C-arm transactions, with academic medical centers paying premium tiers for 3D rotational angiography capabilities while ambulatory surgery centers negotiate compact mobile configurations against per-procedure reimbursement benchmarks. Price differentiation rests on detector technology grade and FDA 510(k) clearance tier, with flat-panel systems commanding substantial premiums over image intensifier units. Pricing pressure intensifies from refurbished equipment channels and independent service organizations capturing legacy maintenance revenue. Budget-constrained tertiary hospitals in Japan exhibit highest price sensitivity; German university hospitals show lowest sensitivity due to research funding insulation.
Supply Chain Analysis
Dual-sourcing mandates from major OEMs now govern amorphous silicon and CMOS sensor procurement, with buyers qualifying suppliers across Japan, South Korea, and Taiwan to mitigate concentration risk in flat-panel detector fabrication. High-performance sensor arrays, precision gantry components, and specialized X-ray tube assemblies constitute critical input dependencies. Supply chain vulnerability centers on single-source exposure for cryogenically cooled detector substrates amid geopolitical friction in East Asian semiconductor corridors. Distribution flows through authorized dealer networks serving hospital procurement committees and GPO contracts in the United States, with direct OEM sales dominating German and Japanese academic medical center placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as MDR CE marking requirements and FDA 510(k) timeline friction raise compliance infrastructure costs beyond mid-tier OEM capacity, forcing weaker players toward exit or acquisition.
For Market Incumbents: Cement market position through captive manufacturing of flat-panel detector substrates and pre-positioned cybersecurity certification for connected imaging architectures. Threats from independent service organizations fragmenting post-installation revenue demand tighter channel control over spare parts allocation. Priority investment in JIS-compliant quality systems for PMDA pathways secures Asia-Pacific pricing power against regional assemblers. For New Entrants and Emerging Players: Budget-constrained orthopedic surgery centers in India and secondary hospital networks in China's interior provinces represent penetrable white-space demand. Compact C-arm configurations with localized software interfaces address unmet need in mid-volume outpatient settings. Partnership with refurbished equipment distributors in Hyderabad and Suzhou offers low-capital market entry without competing against GE Healthcare and Siemens Healthineers in premium tenders. For Investors and Strategic Acquirers: The window for entry favors specialized surgical imaging firms with focused orthopedic portfolios and established CE marking infrastructure. Long-term viability hinges on detector technology ownership rather than system assembly capability. Watch for inflection signals in hospital procurement committee unbundling of service contracts, which would accelerate margin compression for pure-play equipment vendors lacking aftermarket capture.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements create compliance moats for established manufacturers with robust quality systems. |
| Hospital System Partnership | Multi-site ambulatory surgery center networks in Texas and Florida aggregate volume for performance-based service terms. |
| Backward Integration into Detectors | In-house amorphous silicon sensor production insulates GE Healthcare from East Asian supply allocation volatility. |
| Software Companion Development | 3D reconstruction modules integrated with cardiovascular imaging suites command premium placement in Japanese academic centers. |
| Reimbursement Strategy | Outpatient procedure coding alignment for mobile C-arm utilization accelerates replacement demand in United States orthopedic clinics. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and aftermarket service heads. FDA 510(k) premarket notification databases, PMDA quality management system registrations, and EU MDR technical documentation filings provided device-specific evidence standards. Bottom-up installation tracking across ambulatory surgery center networks triangulated against top-down capital expenditure surveys from health system headquarters in Minneapolis, Munich, and Tokyo.
Segmentation-level modeling addressed equipment mobility tiers, detector technology architectures, clinical application workflows, and end-user facility types across the projection horizon. CAGRs derived from procedure volume trajectories in orthopedic and cardiovascular applications, weighted by replacement cycle assumptions for image intensifier versus flat-panel detector fleets. Input variables included hospital capital budget elasticity, reimbursement rate evolution for outpatient joint procedures, and regulatory pathway timeline distributions for software-integrated platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to radiation dose reporting mandate implementation and cybersecurity standard enforcement for connected imaging systems. Deviation in East Asian semiconductor supply continuity or tariff exposure on detector substrates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
PACS and RIS Market