
 Global Electroretinography Market | 2026-2036
Global Electroretinography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electroretinography Market Foresight
Specialized eye hospitals is reorganizing procurement priorities toward portable electroretinographs that enable bedside and operating-room diagnostics without patient transfer. LKC Technologies, Inc. dominates full-field ERG technology through sustained investment in FDA-cleared protocols for inherited retinal disease trials. Diagnosys LLC competes across multifocal and pattern ERG modalities with specialized software analytics for glaucoma progression tracking. Electro-Diagnostic Imaging, Inc. anchors its position in vision research institutes through controls over custom electrode manufacturing and calibration services.
Electroretinography measures electrical responses from retinal photoreceptors and inner neurons using corneal electrodes following standardized light stimuli, with signal amplification typically capturing microvolt-range responses across scotopic and photopic adaptation states. The technique serves primary commercial purpose in objective retinal function assessment where structural imaging proves insufficient, particularly for early-stage photoreceptor degeneration and toxicology screening. Portable and handheld ERG devices are capturing fastest-growing demand as ophthalmology clinics seek point-of-care alternatives to centralized lab workflows, while desktop electroretinographs retain margin concentration in academic medical centers running multicenter clinical trials. Full-field electroretinography leads technology penetration due to established International Society for Clinical Electrophysiology of Vision protocols, though multifocal electroretinography extends into niche glaucoma assessment applications where spatial resolution of macular dysfunction carries diagnostic premium.
FDA 510(k) clearance pathways shape U.S. market entry timelines for novel ERG devices, while EU MDR clinical evaluation requirements under notified body oversight extend conformity assessment duration for European commercialization. Japan's PMDA enforces JIS-compatible electromagnetic safety standards that influence hardware design for Asian market access. Stakeholders must monitor evolving reimbursement coding for home-based and telemedicine ERG applications as payer frameworks adapt to decentralized ophthalmic care models.
Market Dynamics
Portable electroretinography hardware is compressing the traditional site-of-service model for retinal diagnostics, forcing equipment vendors to reconfigure service architectures around decentralized clinical workflows rather than centralized laboratory installations.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for portable ERG devices are compressing commercialization cycles for ophthalmic diagnostic innovators targeting the United States market entry.
- Specialized eye hospitals:Bedside diagnostic requirements in tertiary ophthalmology centers are pulling portable electroretinograph procurement away from traditional desktop laboratory configurations.
- Japan's PMDA electromagnetic standards:JIS-compatible device designs are opening Asian market access pathways for manufacturers investing in region-specific hardware certification.
Market Restraints
- Custom electrode supply concentration:Precision manufacturing capabilities for ERG-specific corneal electrodes cluster with limited specialty suppliers, creating input bottleneck vulnerability.
- EU MDR clinical evaluation extension:Notified body oversight requirements under the Medical Device Regulation are elongating conformity assessment timelines for European commercialization.
- Optical coherence tomography substitution:Structural retinal imaging modalities compete for diagnostic budget allocation in early-stage disease screening where ERG functional assessment carries premium pricing.
Strategic Opportunities
- Germany's aging demographic concentration:Established reimbursement pathways for advanced retinal diagnostics in German statutory health insurance create demand pull for multifocal ERG systems.
- Telemedicine ERG coding evolution:Payer framework adaptation to decentralized ophthalmic care models is opening reimbursement white space for home-based retinal assessment services.
- Pattern ERG-glaucoma convergence:Spatial resolution capabilities in macular dysfunction assessment are creating application expansion into progression tracking for optic nerve disease management.
Industry Challenges
- ISO 10993 biocompatibility certification:Corneal electrode materials require extended toxicological evaluation timelines that compress product launch windows.
- Multicenter trial protocol standardization:Inherited retinal disease study coordination demands specialized electrophysiology expertise that concentrates in limited academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electroretinography Market |
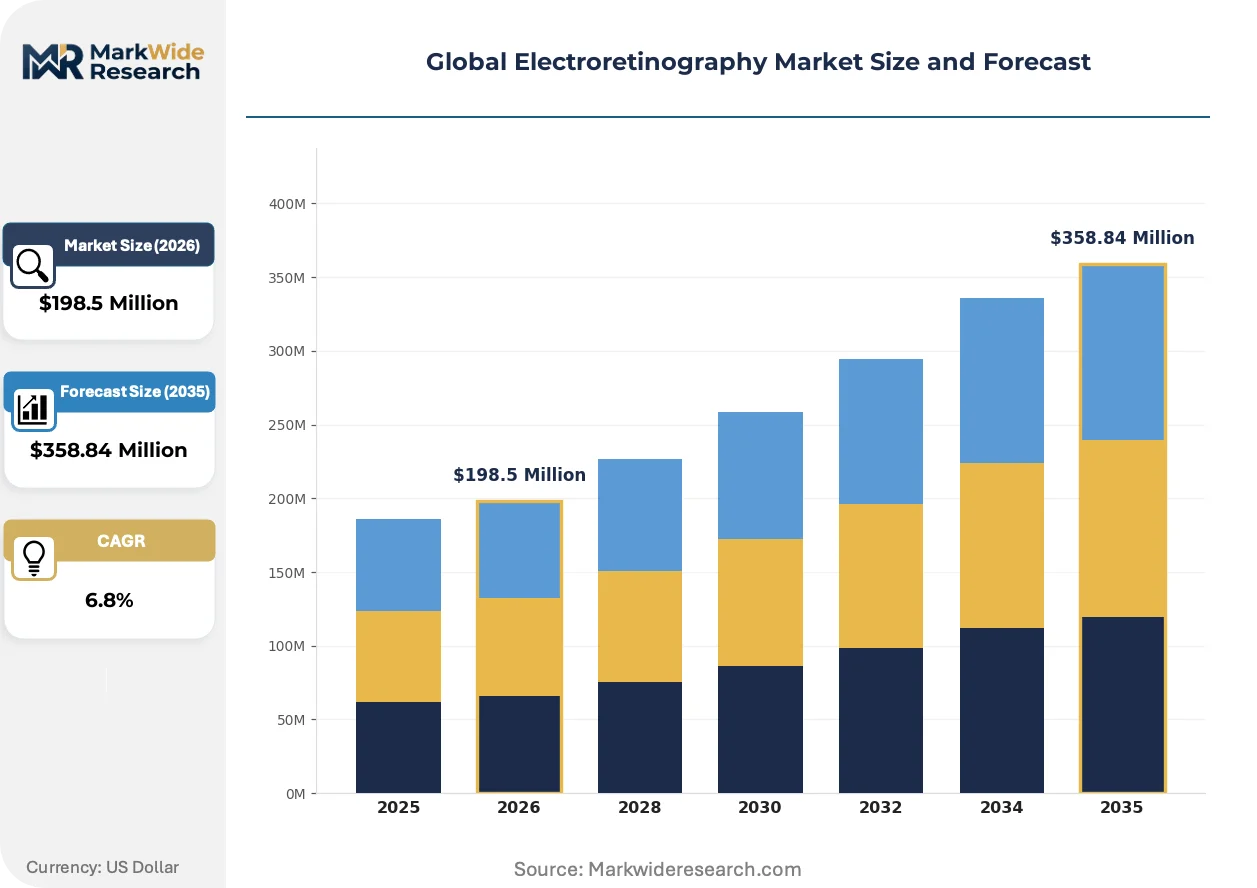
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $358.84 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Electroretinographs, Desktop Electroretinographs, Multifunction ERG Devices, Handheld ERG Devices Technology: Full-Field Electroretinography, Multifocal Electroretinography, Pattern Electroretinography, Flicker Electroretinography Application: Retinal Degeneration Diagnosis, Drug Toxicity Testing, Glaucoma Assessment, Diabetic Retinopathy Monitoring, Optic Nerve Disorders End User: Ophthalmology Clinics, Vision Research Institutes, Diagnostic Laboratories, Specialized Eye Hospitals |
| Companies Covered | LKC Technologies, Inc., Diagnosys LLC, Electro-Diagnostic Imaging, Inc., Diopsys, Inc., Metrovision, Roland-consult, CSO Italia, Konan Medical USA, Inc., Cadwell Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electroretinography Market Shifts & Advancements
Electroretinography technology trajectories are diverging between miniaturized point-of-care systems and precision laboratory instruments, with regulatory frameworks and reimbursement architectures struggling to synchronize with hardware evolution speeds.
Miniaturized electroretinograph hardware is bifurcating the installed base between portable bedside units and fixed laboratory systems. Community ophthalmology clinics in the United States are adopting handheld ERG devices at accelerating replacement cycles. Desktop electroretinograph vendors are retreating toward academic medical center niches where multicenter clinical trial protocols require standardized International Society for Clinical Electrophysiology of Vision compliance.
EU MDR clinical evidence requirements are tightening post-market surveillance obligations for ophthalmic diagnostic equipment. Notified body oversight now demands extended clinical evaluation reports that document real-world performance across diverse patient populations. Full-field electroretinograph manufacturers targeting European commercialization are restructuring quality management systems to accommodate post-market clinical follow-up mandates.
After-sales service unbundling is disrupting traditional equipment procurement contracts in German and Japanese eye hospitals. Buyers are separating hardware acquisition from maintenance agreements and software upgrade subscriptions. This pattern is most visible in specialized eye hospitals running high-throughput inherited retinal disease screening programs where uptime guarantees command premium pricing separate from capital equipment financing.
Global Electroretinography Market Segmentation
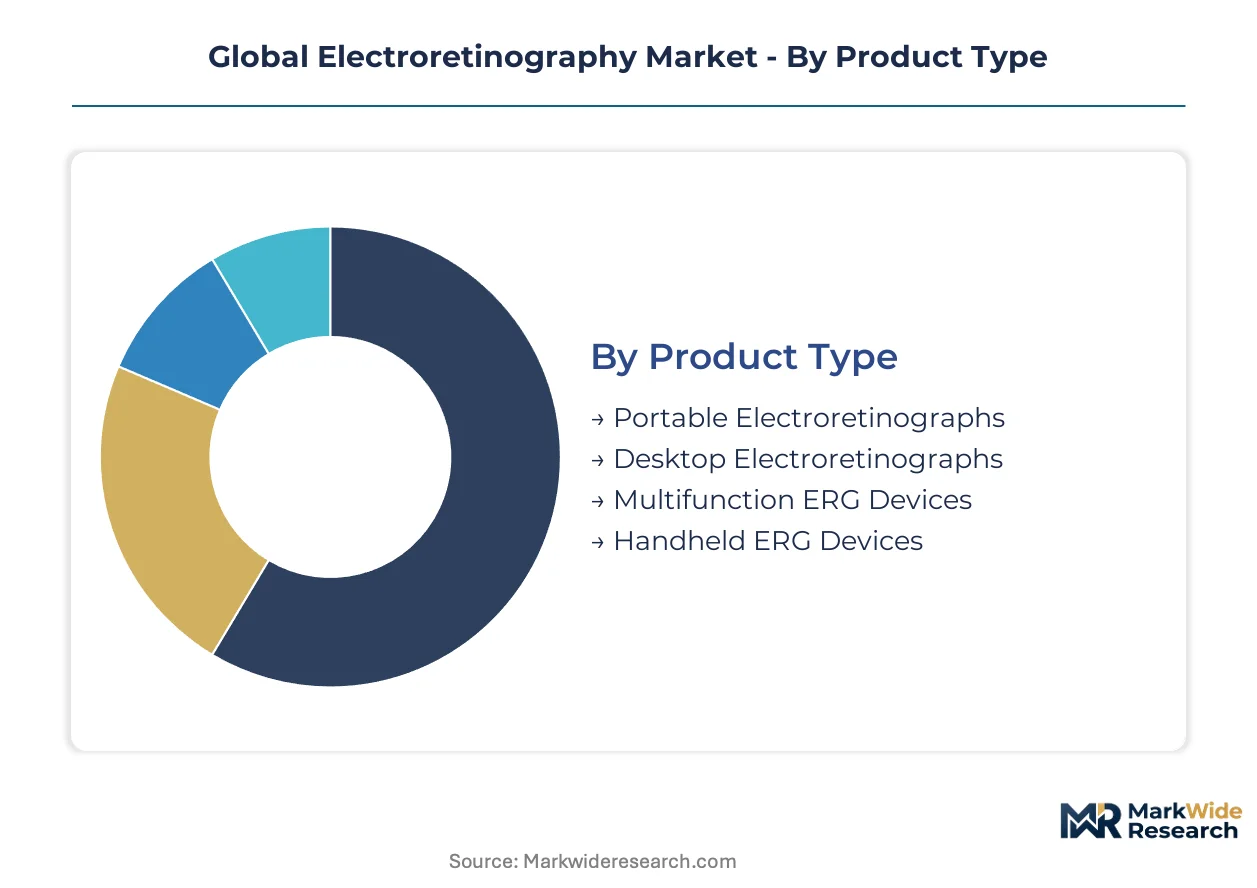
Electroretinography market segmentation reveals how hardware form factors, clinical protocols, and care delivery settings create distinct procurement and reimbursement pathways. Each dimension carries specific regulatory footprints that shape vendor commercialization strategies across jurisdictions.
Product Type:
FDA 510(k) clearance timelines diverge sharply between portable and fixed-installation ERG systems, with bedside-capable devices facing abbreviated review pathways under ophthalmic diagnostic device guidance.
- Portable Electroretinographs:Battery-powered units with integrated amplification and wireless data transmission enable bedside assessment without patient transport. Specialized eye hospitals in the United States and Germany are pulling procurement toward these configurations as operating-room and emergency retinal assessment workflows expand.
- Desktop Electroretinographs:Fixed laboratory installations with standardized International Society for Clinical Electrophysiology of Vision protocol compliance anchor multicenter clinical trial infrastructure. Academic medical centers in Japan and the United States retain these systems for inherited retinal disease research where signal precision and environmental control outweigh mobility requirements.
- Multifunction ERG Devices:Modular platforms combining full-field, multifocal, and pattern electroretinography capabilities in single hardware footprints.
- Handheld ERG Devices:Smartphone-integrated or standalone miniaturized units for point-of-care screening in community ophthalmology settings.
Desktop Electroretinographs handle the majority of throughput in trial settings; Handheld ERG Devices are expanding most quickly into decentralized care models.
Technology:
Cost tiers separate established diagnostic protocols from emerging spatial resolution techniques, with reimbursement coding maturity determining clinical adoption velocity.
- Full-Field Electroretinography:Standardized flash stimuli across scotopic and photopic adaptation states capture global retinal function through corneal electrodes. German statutory health insurance and United States Medicare reimbursement pathways are most established for this protocol, supporting volume concentration in high-throughput screening programs.
- Multifocal Electroretinography:Spatially resolved stimulation arrays isolate macular cone function with topographic mapping capabilities. Japan's PMDA has cleared several mfERG systems for glaucoma progression monitoring, creating demand concentration in tertiary ophthalmology centers where optic nerve disease management requires functional-structural correlation.
- Pattern Electroretinography:Contrast-reversing grating stimuli assess ganglion cell function with applications extending into early glaucoma detection.
- Flicker Electroretinography:Rapid luminance modulation isolates cone system temporal response characteristics for toxicology screening protocols.
Full-Field Electroretinography commands the installed base; Multifocal Electroretinography is climbing the fastest as macular disease protocols mature.
Application:
Customer type concentration varies by clinical indication, with pharmaceutical toxicology screening creating distinct procurement patterns from chronic disease monitoring.
- Retinal Degeneration Diagnosis:Objective functional assessment for inherited photoreceptor disorders where structural imaging appears normal until advanced disease stages. Vision research institutes in the United States and United Kingdom concentrate demand for comprehensive electrophysiology suites supporting gene therapy trial endpoints.
- Drug Toxicity Testing:Prospective and retrospective screening for retinotoxic compounds in pharmaceutical development pipelines. Contract research organizations running FDA-mandated ocular safety studies drive procurement of standardized full-field systems with 21 CFR Part 11 compliant data management.
- Glaucoma Assessment:Pattern and multifocal ERG protocols for detecting pre-perimetric ganglion cell dysfunction.
- Diabetic Retinopathy Monitoring:Functional surveillance complementing fundus photography and OCT in diabetes management programs.
- Optic Nerve Disorders:Electrophysiological differentiation of compressive, inflammatory, and hereditary optic neuropathies.
Retinal Degeneration Diagnosis anchors the research segment; Drug Toxicity Testing is gaining share fastest as ocular safety pharmacology expands.
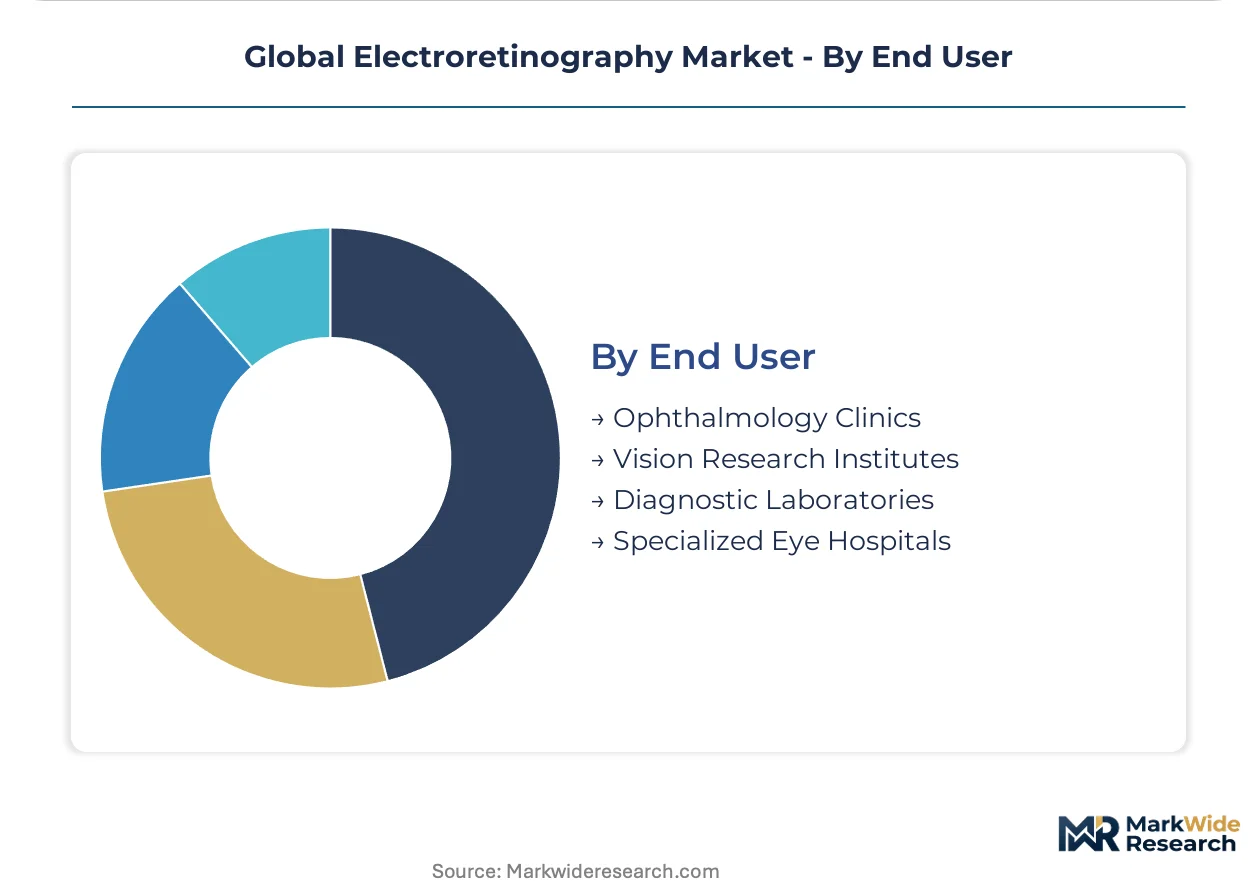
End User:
Supply concentration in electrode manufacturing and calibration services creates vendor lock-in dynamics that differ across institutional purchasing power.
- Specialized Eye Hospitals:Tertiary referral centers with high inherited retinal disease caseloads and surgical retina services. These institutions in Germany, Japan, and the United States are unbundling after-sales contracts and demanding uptime guarantees separate from capital equipment financing.
- Ophthalmology Clinics:Community and suburban practices where point-of-care diagnostic capability supports patient retention and referral network positioning. Portable and handheld ERG adoption is concentrating here as reimbursement for remote retinal assessment evolves.
- Vision Research Institutes:Academic and government laboratories where custom electrode specifications and protocol development drive vendor relationships.
- Diagnostic Laboratories:Centralized testing facilities processing referred specimens with standardized reporting for regional healthcare networks.
Ophthalmology Clinics represent the broadest addressable base; Specialized Eye Hospitals are the fastest mover on equipment refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites European distribution efficiency for ophthalmic diagnostic equipment, while direct transpacific shipping lanes from Yokohama and Los Angeles anchor supply chain velocity across the Pacific basin.
United States
Medicare reimbursement pathways for multifocal ERG protocols and gene therapy trial endpoints concentrate demand in academic medical centers. FDA 510(k) ophthalmic device guidance compresses clearance timelines for portable systems. The Boston-Cambridge corridor anchors inherited retinal disease research infrastructure with specialized electrophysiology suites.
Germany
Statutory health insurance reimbursement for advanced retinal diagnostics pulls procurement toward desktop systems in tertiary eye hospitals. EU MDR notified body oversight extends conformity assessment duration for European commercialization. The Rhine-Ruhr metropolitan region concentrates specialized eye hospital networks with high-throughput screening programs.
Japan
PMDA JIS-compatible electromagnetic safety standards shape hardware design for Asian market access. Aging demographic concentration in Kanto region drives demand for point-of-care diagnostic capability. Tokyo's university hospital clusters maintain multicenter clinical trial coordination for inherited retinal disease protocols.
United Kingdom
NHS specialized commissioning frameworks for rare disease diagnostics channel funding toward comprehensive electrophysiology services. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements. London's Moorfields Eye Hospital anchors national referral networks for retinal degeneration assessment.
Australia
TGA medical device inclusion pathways for ophthalmic diagnostics align with ISO 13485 quality management expectations. Medicare Benefits Schedule item numbers for electrophysiological testing support community clinic adoption. Melbourne's Centre for Eye Research Australia coordinates national inherited retinal disease registries.
Global Electroretinography Market Competitive Landscape
Concentration sits with full-field ERG technology specialists and multifocal system innovators. The vendor base stratifies across three tiers: established laboratory instrument manufacturers, portable device entrants, and research-grade custom electrode suppliers. Competitive positioning hardens around FDA 510(k) clearance portfolios, ISO 10993 biocompatibility certification timelines, and after-sales service unbundling capabilities. M&A activity targets portable technology acquisitions while strategic partnerships concentrate on multicenter trial protocol standardization.
Among United States-based diagnostic innovators, LKC Technologies, Inc. and Diagnosys LLC occupy positions spanning full-field and multifocal modalities. Electro-Diagnostic Imaging, Inc. represents the research-grade custom electrode tier with calibration service integration. These three enterprises exemplify how specialization across protocol types and service architectures creates defensible positioning against generalized ophthalmic device competitors.
| Leading Market Players |
|---|
| LKC Technologies, Inc. |
| Diagnosys LLC |
| Electro-Diagnostic Imaging, Inc. |
| Diopsys, Inc. |
| Metrovision |
| Roland-consult |
| CSO Italia |
| Konan Medical USA, Inc. |
| Cadwell Industries, Inc. |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both electrode supplier qualification and price differentiation across portable and desktop electroretinograph tiers, compressing launch timelines for premium hardware while elevating entry costs for economy positioning. German statutory health insurance reimbursement bands and United States Medicare coding density further stratify procurement budgets between academic medical centers and community ophthalmology clinics.
Pricing Analysis
Volume-discount tiering separates high-throughput inherited retinal disease screening programs from low-volume community diagnostic workflows. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 quality management maturity and FDA 510(k) clearance breadth. Pricing pressure stems from optical coherence tomography substitution in early-stage disease screening where structural imaging carries lower per-test economics. Community ophthalmology clinics exhibit highest price sensitivity; vision research institutes prioritize signal precision over unit economics.
Supply Chain Analysis
Custom corneal electrode manufacturing concentrates in United States, Germany, and Japan specialty suppliers with precision electrochemistry capabilities. Precision-milled silver-silver chloride electrodes, medical-grade silicone substrates, and calibrated amplification modules anchor hardware bill-of-materials. Single-source vulnerability runs through FDA-registered electrode vendors with extended toxicological evaluation timelines. Distribution runs through specialized ophthalmic device distributors serving hospital purchasing committees and GPO contract channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroretinography platform economics hinge on interoperability between handheld screening devices and centralized laboratory data management systems, with telemedicine reimbursement coding evolution determining ecosystem viability.
For Market Incumbents: Shield full-field ERG protocol dominance through backward integration into custom electrode manufacturing and calibration service captive supply. Lock in academic medical center relationships via multicenter trial protocol standardization investments that raise switching costs for competing portable entrants. Defend against optical coherence tomography substitution by embedding functional-structural correlation software analytics. For New Entrants and Emerging Players: Lead with smartphone-integrated handheld ERG form factors targeting United States community ophthalmology clinics where Medicare reimbursement for remote retinal assessment is crystallizing. Capture white space in home-based monitoring applications where payer frameworks are adapting to decentralized care models. Pursue hospital-at-home partnership channels rather than direct capital equipment sales. For Investors and Strategic Acquirers: EU MDR clinical evaluation extension reshapes the acquisition landscape toward portable device innovators with abbreviated FDA 510(k) clearance timelines that bypass European conformity assessment bottlenecks. Target research-grade custom electrode suppliers with ISO 10993 certification pipelines and vision research institute relationships. Watch telemedicine ERG coding decisions by United States Medicare as the signal for home-based service market viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Abbreviated review timelines for portable devices compress commercialization cycles for United States market entry. |
| CE Marking Pathway Investment | EU MDR notified body oversight demands extended clinical evaluation reports that elongate European commercialization timelines. |
| Hospital System Partnership | Specialized eye hospitals in Germany and Japan are unbundling after-sales contracts and demanding uptime guarantees. |
| Software Companion Development | Pattern ERG analytics for glaucoma progression tracking extends application into optic nerve disease management. |
| Reimbursement Strategy | Medicare coding evolution for telemedicine ERG applications determines market viability for home-based screening services. |
Research Methodology
Operator-level perspectives from electrophysiology laboratory directors, ophthalmology clinic practice managers, hospital purchasing committee members, and biomedical equipment procurement specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) device clearances, EU MDR notified body guidance documents, Medicare reimbursement coding updates, and International Society for Clinical Electrophysiology of Vision protocol standards. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation framed market sizing.
Sensitivity analysis tested forecast outputs against portable device adoption velocity, EU MDR conformity assessment duration scenarios, and telemedicine reimbursement crystallization timing. Segmentation modeling spanned hardware form factor, clinical protocol type, end-user institutional category, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, screening program expansion rates, and gene therapy trial endpoint demand. Forecast inputs included PMDA electromagnetic safety standard evolution and German statutory health insurance coverage decisions.
The analysis sits within stated boundaries; outcomes outside portable device battery performance improvements and wireless data transmission reliability thresholds would require recalibration. Forecasts reflect documented assumptions regarding FDA ophthalmic device guidance stability and Medicare coding density for functional retinal assessment. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance obligations and Japan's aging demographic concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Radiation Dose Management Market