
 Cardiac Catheters and Guidewires Market | 2026-2036
Cardiac Catheters and Guidewires Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Catheters and Guidewires Market Intelligence
ISO 13485 certification cycles are redrawing competitive boundaries in cardiac catheter manufacturing. Abbott Laboratories leverages integrated electrophysiology portfolios to sustain R&D intensity across mapping and ablation workflows. Boston Scientific Corporation anchors North American hospital supply chains through direct cath-lab contracting. Asahi Intecc Co., Ltd. specializes in nitinol-core guidewire architectures that dominate Japanese and European PCI procedures.
Cardiac catheters and guidewires constitute sterile, single-use instruments engineered from braided polyamide, Pebax, or stainless-steel substrates with hydrophilic coatings, designed to navigate coronary and peripheral vasculature for diagnostic imaging or therapeutic delivery. Therapeutic catheters command premium positioning due to drug-eluting and ablation functionalities, while balloon catheters face margin compression from commoditization in standard PCI. Electrophysiology technology segments attract disproportionate R&D allocation as atrial fibrillation procedural volumes expand faster than coronary interventions.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose multi-year validation timelines that filter subscale manufacturers from commercial access. Japan's PMDA enforces JIS-compliant biocompatibility testing that adds regional certification costs for foreign entrants. Stakeholders must monitor evolving notified body capacity constraints in Europe and FDA digital health pre-certification pilots that could reshape software-integrated catheter submissions.
Market Dynamics
ISO 13485 certification cycles are redrawing competitive boundaries in cardiac catheter manufacturing, filtering subscale producers from commercial access while elevating quality benchmarks for interventional cardiology supply chains.
Growth Catalysts
- EU MDR conformity assessments:Tighter quality benchmarks for market entry are consolidating procurement toward certified manufacturers with validated technical documentation.
- Aging demographics in Japan:Established interventional cardiology infrastructure sustains catheterization lab utilization and procedural volume expansion.
- Electrophysiology mapping systems:Integrated portfolios sustain R&D intensity across diagnostic imaging and therapeutic delivery workflows.
Market Restraints
- Nitinol supply concentration:Japanese and European PCI procedure dependence on specialized guidewire architectures creates input vulnerability.
- FDA 510(k) multi-year validation timelines:Premarket notification pathways impose capital intensity that excludes emerging manufacturers.
- Balloon catheter commoditization:Standard PCI margin compression limits pricing power in high-volume coronary interventions.
Strategic Opportunities
- Atrial fibrillation procedural expansion:Electrophysiology technology segments attract disproportionate R&D allocation as intervention volumes outpace coronary growth.
- Digital health pre-certification pilots:FDA software-integrated catheter submission pathways could reshape regulatory economics for smart device developers.
- German hospital supply chain consolidation:Direct cath-lab contracting models enable integrated service provision and captive volume capture.
Industry Challenges
- Notified body capacity constraints in Europe:EU MDR technical documentation backlogs extend certification timelines and compress product launch windows.
- JIS-compliant biocompatibility testing:Japan's PMDA regional certification requirements add cost layers for foreign market entrants without local testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Catheters and Guidewires Market |
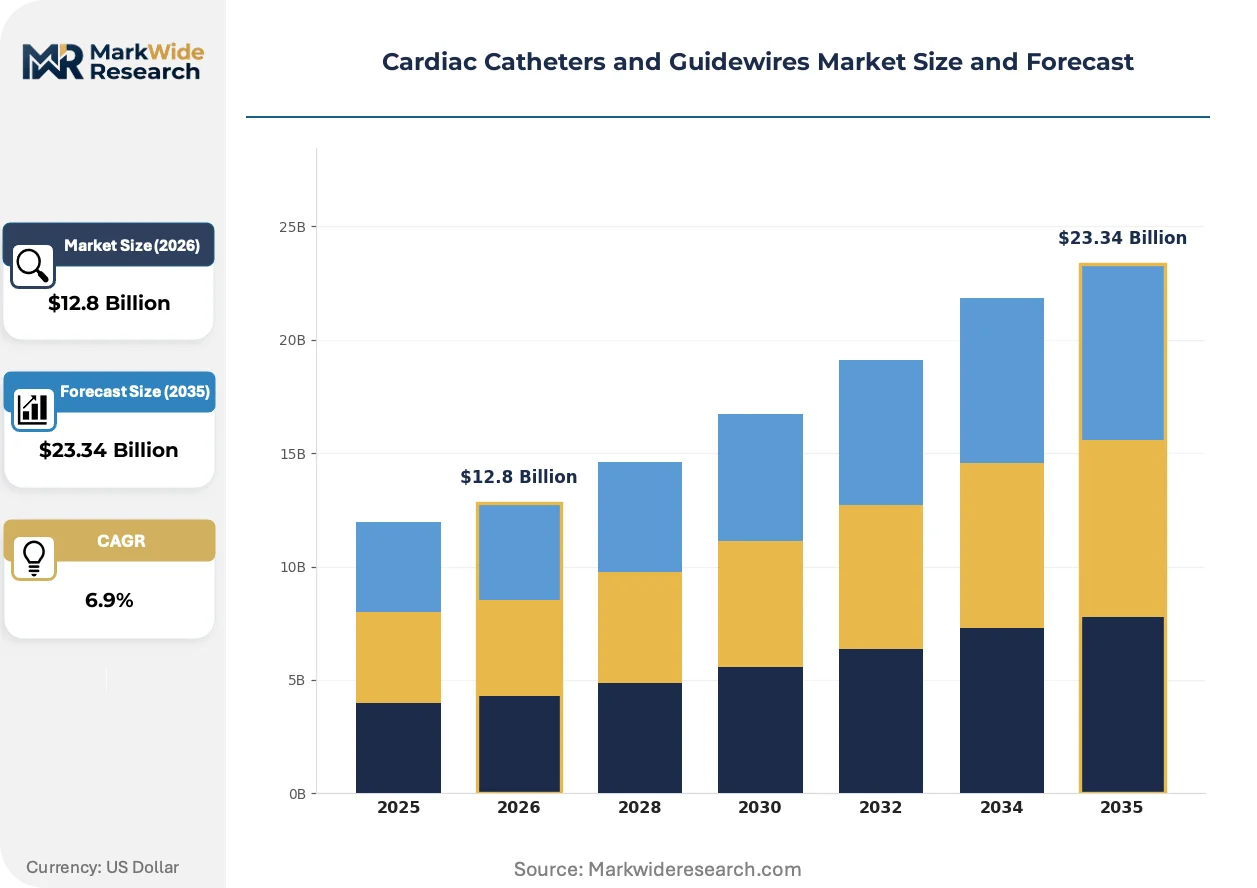
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $23.34 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Catheters, Therapeutic Catheters, Guidewires, Balloon Catheters End User: Hospitals, Cardiac Clinics, Outpatient Facilities, Research Institutions Technology: Electrophysiology, Intracardiac Ultrasound, Optical Coherence Tomography, Fluoroscopy Application: Coronary Angiography, Electrophysiology Procedures, PCI, Structural Heart Interventions |
| Companies Covered | Terumo Medical Corporation, Getinge AB, Abbott Laboratories, Asahi Intecc Co., Ltd., Cardinal Health, Inc., Boston Scientific Corporation, Biotronik SE & Co. KG, Teleflex, Inc., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Catheters and Guidewires Market Strategic Shifts & Innovations
Interventional cardiology device architectures are fragmenting into modular, software-integrated systems that separate hardware navigation from diagnostic intelligence and therapeutic delivery.
Robotic-assisted catheter navigation is decomposing traditional manual guidewire manipulation by enabling sub-millimeter precision in coronary and peripheral vasculature. Academic medical centers in the United States and Germany are piloting these systems for complex chronic total occlusion cases. This capability is decomposing the historical surgeon skill premium into standardized, reproducible procedural outcomes that compress training timelines and expand treatable patient populations.
EU MDR technical documentation requirements are extending validation cycles for legacy catheter families that previously operated under CE-mark grandfathering. Manufacturers must regenerate clinical evidence packages for hydrophilic-coated and drug-eluting platforms. Electrophysiology ablation catheters face the steepest compliance burden due to active therapeutic mechanisms and energy delivery systems requiring updated biocompatibility and electrical safety dossiers.
Hospital procurement committees are consolidating vendor relationships around integrated electrophysiology and interventional cardiology portfolios. Single-source contracting for mapping systems, ablation catheters, and consumable guidewires is displacing multi-vendor spot purchasing. This concentration is most pronounced in United States integrated delivery networks and German hospital federations seeking to standardize cath-lab workflows and reduce supply chain complexity.
Cardiac Catheters and Guidewires Market Segmentation
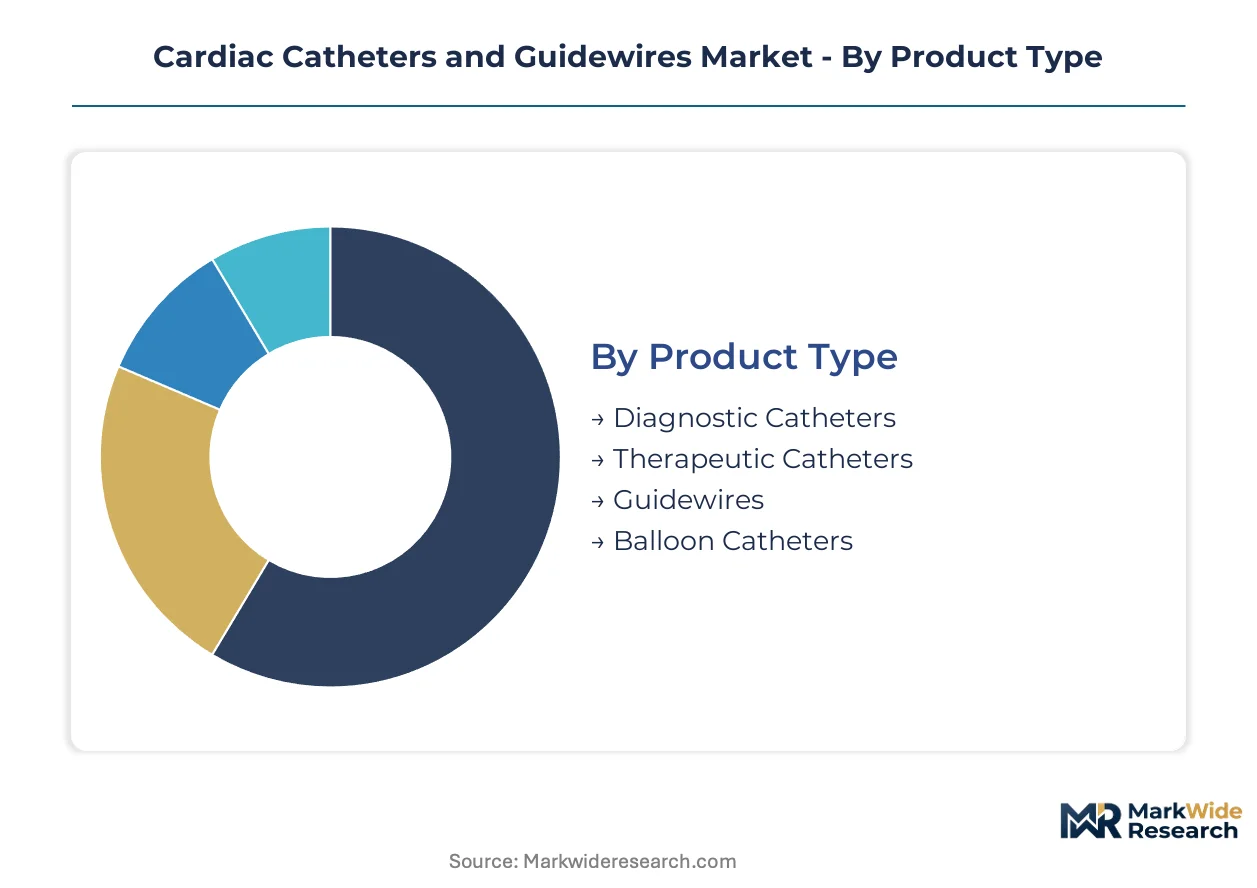
Cardiac catheter segmentation determines procurement pathways, regulatory submission strategies, and R&D allocation across interventional cardiology workflows. Product architecture, imaging modality, and care setting each create distinct margin profiles and competitive dynamics.
Product Type:
Channel mix varies sharply by product category, with therapeutic platforms flowing through integrated hospital contracts while diagnostic consumables distribute through group purchasing organizations.
- Therapeutic Catheters:Drug-eluting and ablation-enabled platforms incorporate active therapeutic mechanisms commanding premium positioning. Demand concentrates in United States academic medical centers and German hospital federations where integrated electrophysiology portfolios justify single-source contracting.
- Guidewires:Nitinol-core architectures with hydrophilic coatings enable sub-millimeter navigation through tortuous vasculature. Japanese and European PCI procedures sustain specialized demand for Asahi Intecc geometries that dominate complex chronic total occlusion cases.
- Diagnostic Catheters:Braided polyamide substrates for coronary angiography face margin compression from standardization.
- Balloon Catheters:Commoditized standard PCI platforms encounter pricing pressure from high-volume procurement.
Therapeutic catheters dominate installed base. Guidewires represent where expansion concentrates.
End User:
Customer type segmentation reveals divergent procurement authority and workflow integration requirements across care settings.
- Hospitals:Catheterization labs with 24/7 interventional capability anchor procedural volume and integrated portfolio contracting. United States integrated delivery networks and German hospital federations consolidate vendor relationships around mapping systems, ablation platforms, and consumable guidewires.
- Cardiac Clinics:Specialized electrophysiology centers concentrate diagnostic imaging and therapeutic delivery for atrial fibrillation. These facilities drive disproportionate R&D allocation as procedural volumes outpace coronary interventions.
- Outpatient Facilities:Ambulatory surgical centers capture select diagnostic catheterizations with lower acuity profiles.
- Research Institutions:Academic medical centers pilot robotic-assisted navigation and software-integrated catheter systems.
Hospitals dominate installed base. Cardiac clinics represent where expansion concentrates.
Technology:
Imaging modality segmentation tracks capital intensity and software integration depth across diagnostic platforms.
- Electrophysiology:Three-dimensional mapping systems with magnetic location technology enable precise ablation catheter positioning. United States and German academic centers deploy these platforms for complex arrhythmia cases with expanding treatable populations.
- Optical Coherence Tomography:Intravascular imaging with near-infrared light provides micron-level resolution for stent optimization. Japanese PCI specialists and German interventionalists integrate OCT into routine complex lesion assessment.
- Intracardiac Ultrasound:Real-time structural visualization guides transseptal puncture and device deployment.
- Fluoroscopy:X-ray-based guidance remains standard for coronary angiography despite radiation exposure tradeoffs.
Fluoroscopy dominates installed base. Electrophysiology represents where expansion concentrates.
Application:
Procedural indication segmentation aligns with demographic disease burden and reimbursement pathways.
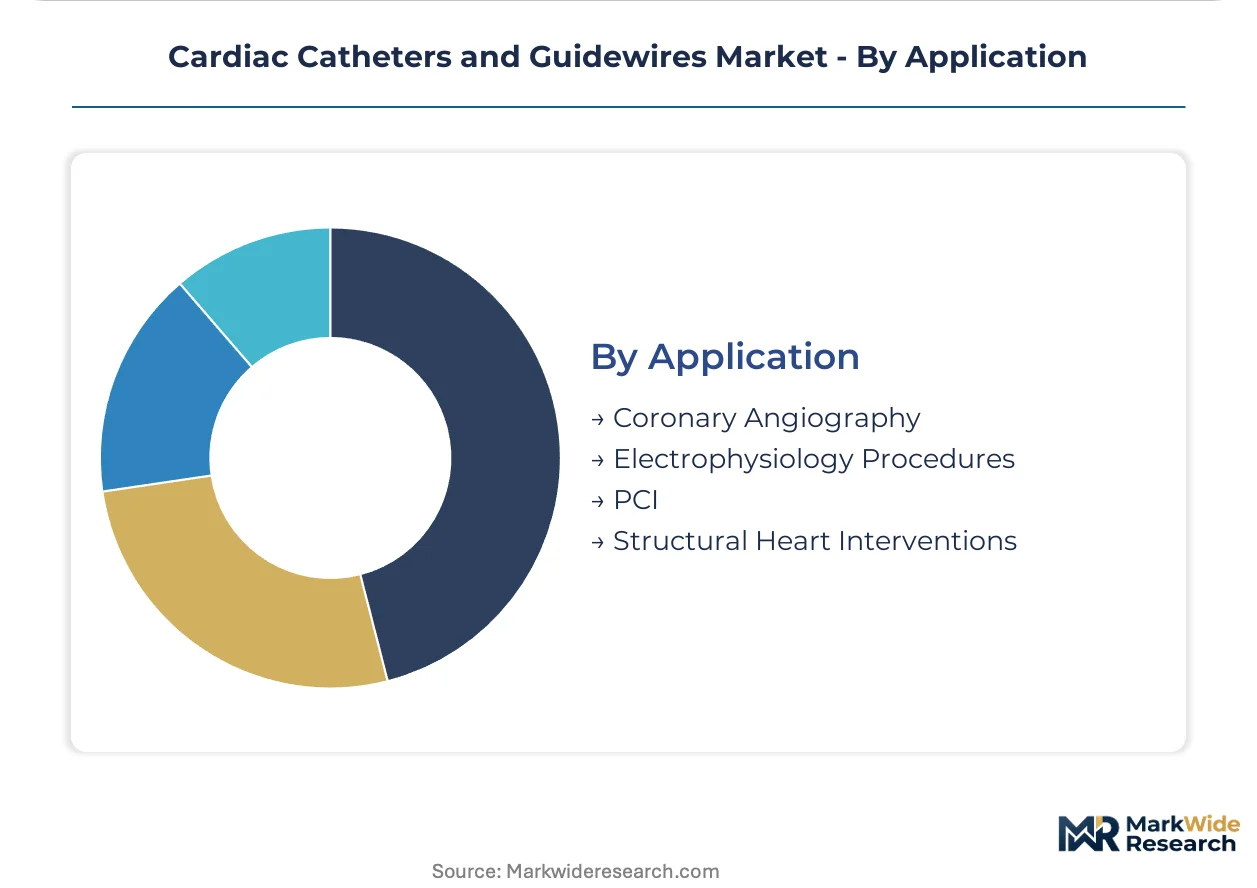
- Electrophysiology Procedures:Atrial fibrillation ablation utilizing radiofrequency or cryothermal energy delivery systems. Aging demographics in Japan, Germany, and the United States sustain catheterization lab utilization with procedural volumes climbing faster than coronary interventions.
- Structural Heart Interventions:Transcatheter valve repair and left atrial appendage occlusion require specialized delivery systems. United States and German centers lead adoption curves for these expanding indications.
- PCI:Percutaneous coronary intervention with balloon and stent deployment remains high-volume but faces margin compression.
- Coronary Angiography:Diagnostic imaging for coronary artery disease assessment serves as gateway procedure.
PCI dominates installed base. Electrophysiology procedures represent where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for catheterization lab portfolios. These three markets anchor procedural volume expansion for electrophysiology and interventional cardiology workflows.
United States
Integrated delivery networks consolidate vendor relationships around mapping systems and ablation platforms. FDA 510(k) clearance pathways impose multi-year validation timelines that filter emerging manufacturers from commercial access. Academic medical centers in Boston and Cleveland pilot robotic-assisted navigation systems for complex chronic total occlusion cases.
Germany
Hospital federations standardize cath-lab workflows through single-source contracting for electrophysiology portfolios. EU MDR conformity assessments extend certification timelines for legacy catheter families requiring regenerated clinical evidence packages. The Rhine-Ruhr metropolitan region hosts concentrated interventional cardiology infrastructure serving Western European procedural demand.
Japan
Aging demographics sustain catheterization lab utilization with atrial fibrillation procedural volumes climbing faster than coronary interventions. PMDA enforces JIS-compliant biocompatibility testing that adds regional certification costs for foreign entrants. Tokyo and Osaka anchor specialized PCI centers demanding nitinol-core guidewire architectures for complex lesion navigation.
China
Domestic hospital construction expands interventional cardiology capacity in tier-one cities. NMPA medical device registration pathways lengthen technical documentation requirements for imported catheter platforms. The Yangtze River Delta clusters domestic manufacturers scaling production of diagnostic and therapeutic catheter substrates.
Switzerland
Swissmedic maintains stringent quality benchmarks for CE-marked devices entering European distribution channels. Geneva and Basel host precision manufacturing clusters supplying hydrophilic coating technologies to catheter producers. The country's regulatory infrastructure supports notified body coordination for EU MDR technical documentation review.
Cardiac Catheters and Guidewires Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with integrated electrophysiology portfolios. Market structure concentrates around manufacturers possessing validated ISO 13485 certification cycles and established hospital supply chain relationships. Three archetypes dominate: integrated portfolio providers, specialized guidewire architects, and diversified cardiovascular device conglomerates. Competitive moves center on direct cath-lab contracting and R&D allocation toward electrophysiology mapping systems.
Among diversified cardiovascular device conglomerates, Abbott Laboratories, Boston Scientific Corporation, and Medtronic exemplify scale-driven positions. Abbott Laboratories represents integrated portfolio architecture spanning diagnostic imaging and therapeutic delivery workflows. Boston Scientific Corporation anchors North American hospital supply chain presence through cath-lab contracting models. Medtronic occupies a position within diversified device manufacturing with cardiovascular segment concentration. Asahi Intecc Co., Ltd. exemplifies specialized guidewire architecture expertise, particularly for nitinol-core designs. Terumo Medical Corporation represents Japanese-origin manufacturing with interventional systems portfolio breadth.
| Leading Market Players |
|---|
| Terumo Medical Corporation |
| Getinge AB |
| Abbott Laboratories |
| Asahi Intecc Co., Ltd. |
| Cardinal Health, Inc. |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Teleflex, Inc. |
| Medtronic |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification cycles gate both supplier qualification and price differentiation simultaneously, filtering subscale manufacturers from commercial access while elevating quality benchmarks that justify premium positioning for therapeutic platforms.
Pricing Analysis
Cost-plus contracts with nitinol indexation dominate procurement between Japanese guidewire specialists and European hospital federations. Three-tier pricing structure across premium, standard, and economy levels separates drug-eluting ablation platforms from diagnostic consumables and commoditized balloon catheters. Pricing pressure stems from balloon catheter commoditization in high-volume PCI, compressing margins for standard coronary interventions. Academic medical centers exhibit lowest price sensitivity due to integrated electrophysiology portfolio contracting, while outpatient surgical centers drive hardest bargain on diagnostic catheter volumes.
Supply Chain Analysis
Nitinol wire drawing capacity in Japan, Germany, and Switzerland anchors specialized guidewire production for complex PCI procedures. Raw material dependencies center on nickel-titanium alloys, hydrophilic polymer coatings, and braided polyamide substrates sourced from precision manufacturing clusters. Single-source vulnerability concentrates in Japanese nitinol-core architectures that dominate chronic total occlusion cases. Distribution runs through direct cath-lab contracting with integrated delivery networks and group purchasing organization channels for diagnostic consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as robotic-assisted navigation decomposes historical surgeon skill premiums into standardized procedural outcomes, creating niches for software-integrated catheter developers alongside incumbent hardware manufacturers.
For Market Incumbents: Shield electrophysiology portfolio margins by deepening backward integration into mapping system software and securing exclusive cath-lab contracts with United States integrated delivery networks. Prioritize EU MDR technical documentation regeneration for legacy ablation catheter families before notified body capacity constraints extend certification timelines further. Counter robotic-assisted navigation entrants by embedding proprietary guidewire geometries into hospital system standard-of-care protocols. For New Entrants and Emerging Players: FDA digital health pre-certification pilots offer fastest regulatory pathway for software-integrated catheter submissions, enabling qualified entrants to bypass traditional multi-year validation timelines. Target cardiac clinic electrophysiology centers in Germany and Japan where atrial fibrillation procedural expansion outpaces coronary intervention growth. Lead with OCT-guided therapeutic delivery platforms that command premium positioning against commoditized diagnostic alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrophysiology mapping systems as three-dimensional magnetic location technology requires disproportionate R&D allocation. Long-term viability favors diversified cardiovascular device conglomerates with validated ISO 13485 cycles and established hospital supply chain relationships over pure-play hardware manufacturers. Watch FDA software-integrated catheter submission approval velocity as inflection indicator for smart device regulatory economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Regeneration | Regenerated clinical evidence packages enable continued CE-mark access for hydrophilic-coated and drug-eluting platforms. |
| Hospital System Partnership | Single-source cath-lab contracting with German hospital federations standardizes workflows and reduces supply chain complexity. |
| Software Companion Development | Robotic-assisted navigation systems decompose manual guidewire manipulation into reproducible sub-millimeter precision outcomes. |
| Reimbursement Strategy | Atrial fibrillation ablation coding alignment secures favorable payment rates for electrophysiology procedural expansion. |
| FDA Submission | Digital health pre-certification pilots reshape regulatory economics for smart catheter developers with integrated diagnostic intelligence. |
Research Approach
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up catheter unit demand modeling triangulated against top-down market sizing from manufacturer revenue disclosures.
Variance decomposition across product type, end user, technology modality, application indication, and regional regulatory cluster enabled granular segment-level forecasting throughout the projection horizon. CAGRs derived from procedural volume trajectories, reimbursement pathway stability, and technology substitution curves with specific inputs from aging demographic projections and cath-lab construction pipelines.
Decision-makers should treat outputs as directional under base assumptions of stable FDA and EU MDR regulatory pathways; material deviation in notified body capacity or digital health pre-certification scope would warrant model refresh. Practitioners should keep alternative scenarios live as robotic-assisted navigation adoption curves and electrophysiology procedural volume trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Artificial Respirator Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Retinal Surgery Devices Market