
 Asia-Pacific Intraoperative Imaging Market | 2026-2036
Asia-Pacific Intraoperative Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Intraoperative Imaging Market Insights
Radiologic technologist shortages across Southeast Asia is collapsing installation timelines for intraoperative CT and MRI suites. GE HealthCare leverages its established service networks to sustain equipment uptime in tier-two Chinese hospitals. Siemens Healthineers AG anchors its position through R&D intensity in advanced visualization software for spine navigation.
Intraoperative imaging encompasses real-time diagnostic visualization systems deployed directly within surgical suites, typically integrating 1.5-tesla MRI gantries, flat-panel C-arm fluoroscopy, or 3D cone-beam CT with sub-millimeter spatial resolution to enable immediate anatomical confirmation without patient transfer. MRI systems command premium placement in neurosurgery suites where margin pools remain deepest, while ultrasound devices gain fastest traction in orthopedic trauma settings across India's corporate hospital chains. Fluoroscopy systems retain mature installed bases but face displacement pressure from 3D imaging modalities in cardiac catheterization labs.
Japan's PMDA, Australia's TGA, and China's NMPA each enforce distinct electromagnetic safety and software validation standards that fragment product certification pathways across the region. India's CDSCO recently aligned medical device rules with international quality management systems, accelerating import clearances for intraoperative ultrasound platforms. Stakeholders must monitor regulatory divergence between ASEAN harmonization frameworks and national pre-market approval requirements when allocating manufacturing and clinical training resources.
Market Dynamics
Japan's PMDA streamlined approval pathways for intraoperative MRI devices in 2024, compressing regulatory timelines and accelerating neurosurgical suite upgrades across tier-one Chinese and Indian hospital networks. This regulatory momentum is concentrating vendor competition around service uptime guarantees rather than equipment specifications alone.
Growth Catalysts
- Neurosurgery volume concentration:China's tier-one cities report climbing cranial and spinal procedure volumes, creating sustained demand for 1.5-tesla MRI-integrated surgical suites that enable real-time margin confirmation without patient transfer.
- CDSCO alignment with ISO 13485:India's medical device regulator accelerated import clearances for intraoperative ultrasound platforms by harmonizing quality management requirements with international standards.
- Flat-panel C-arm fluoroscopy:Orthopedic trauma centers across India's corporate hospital chains are replacing conventional image intensifiers with digital flat-panel detectors, driving replacement cycles in surgical imaging infrastructure.
Market Restraints
- Radiologic technologist scarcity:Southeast Asian markets face collapsing installation timelines for intraoperative CT and MRI suites due to acute shortages of trained imaging specialists capable of operating hybrid surgical equipment.
- Electromagnetic safety fragmentation:Divergent electromagnetic compatibility standards between Japan's PMDA, Australia's TGA, and China's NMPA force manufacturers to maintain separate product certification pathways, elevating compliance overhead.
- 3D cone-beam CT substitution:Flat-panel C-arm systems with 3D reconstruction capability are displacing conventional fluoroscopy in cardiac catheterization labs, rendering mature installed bases economically obsolete.
Strategic Opportunities
- Tier-two Chinese hospital penetration:Secondary cities in Jiangsu and Zhejiang provinces exhibit underpenetrated surgical imaging infrastructure, creating whitespace for vendors capable of delivering remote service support without on-site specialist presence.
- Spine navigation software convergence:Advanced visualization platforms integrating pre-operative planning with intraoperative 3D imaging are opening premium pricing tiers in orthopedic and neurosurgical segments.
- ASEAN harmonization frameworks:Emerging regional regulatory alignment initiatives promise simplified multi-country product registration, reducing time-to-market for intraoperative imaging systems across Southeast Asian markets.
Industry Challenges
- Multimodal system integration:Surgical teams struggle to synchronize 1.5-tesla MRI gantries with existing navigation software and robotic positioning systems, extending training periods and delaying productive utilization.
- Preventive maintenance skill gaps:Tier-two Chinese hospitals lack in-house biomedical engineering capacity for cryogen management and gradient coil servicing on intraoperative MRI platforms, forcing dependence on vendor field service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Intraoperative Imaging Market |
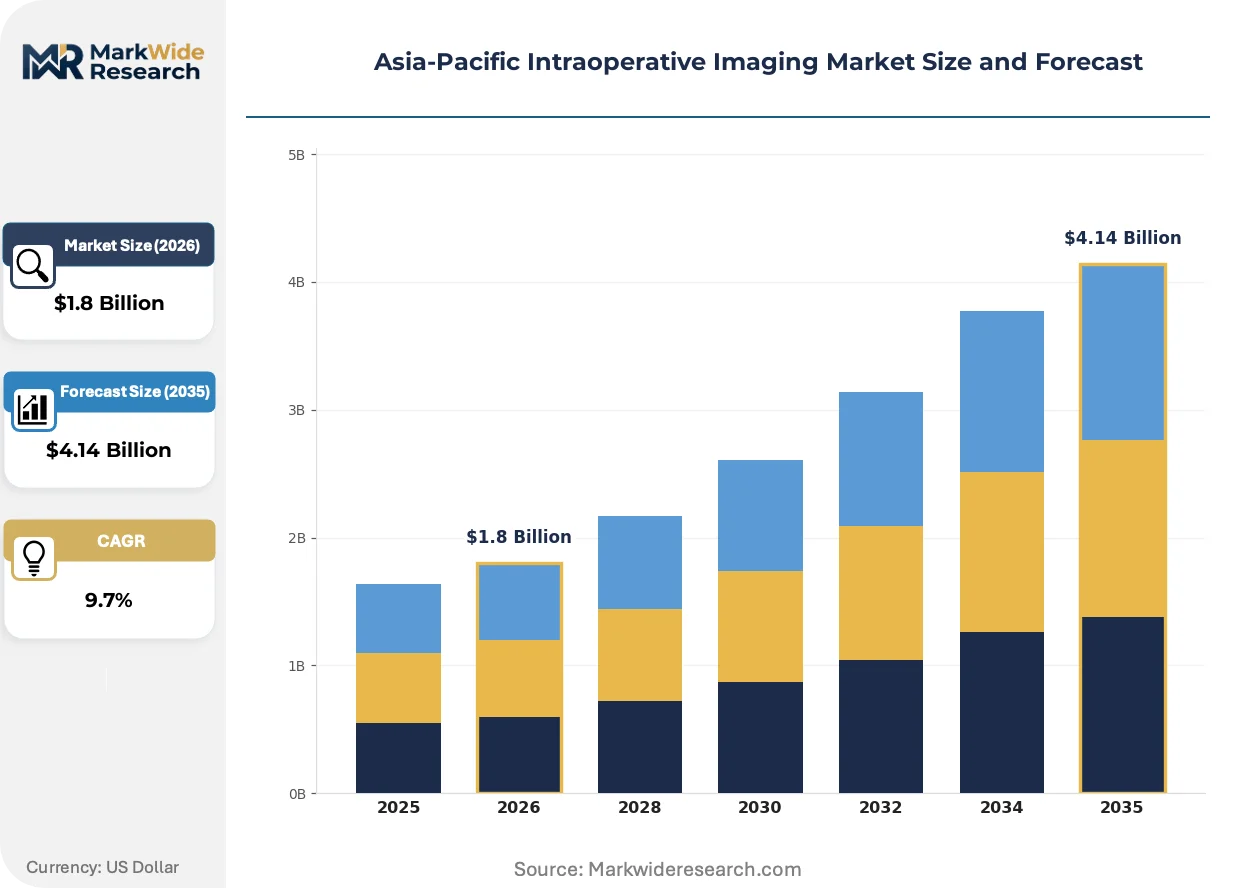
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, Ultrasound Devices, Fluoroscopy Systems Technology: 2D Imaging, 3D Imaging, Augmented Reality, Advanced Visualization Application: Neurosurgery, Orthopedic Surgery, Cardiac Surgery, Spine Surgery End User: Hospitals, Surgical Centers, Research Institutions, Academic Medical Centers |
| Companies Covered | GE HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., Medtronic, Shimadzu Corporation, Brainlab AG, Ziehm Imaging GmbH, Fujifilm Holdings Corporation, Canon Medical Systems Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Intraoperative Imaging Market Trends and Innovations
Real-time diagnostic visualization is fragmenting into modular, software-defined components that separate hardware acquisition from algorithmic enhancement. Vendors are repositioning around predictive service models and interoperable imaging platforms rather than closed-system hardware dominance.
Open-architecture MRI platforms are decomposing the traditional bundled hardware-software procurement model in Asia-Pacific neurosurgery suites. Leading Chinese hospital networks now acquire 1.5-tesla gantries from independent manufacturers while sourcing advanced visualization algorithms through separate software licenses. This unbundling is compressing vendor margin pools and forcing equipment specialists to defend position through service responsiveness rather than proprietary system lock-in.
Japan's PMDA introduced streamlined electromagnetic safety validation protocols for intraoperative MRI devices in 2024, reducing pre-market approval timelines by consolidating software and hardware review processes. Device manufacturers now submit integrated electromagnetic compatibility documentation rather than separate filings, accelerating market entry for next-generation surgical imaging platforms. Australian and Singaporean regulators are monitoring this framework for potential regional adoption, creating pressure for harmonized Asia-Pacific standards.
Hospital procurement committees in India and Southeast Asia are unbundling equipment purchase from multi-year service contracts, treating maintenance and upgrade pathways as separately negotiable commercial terms. Corporate hospital chains now source intraoperative imaging hardware through capital expenditure budgets while financing software subscriptions and predictive maintenance through operational expenditure lines. This bifurcation is most visible in India's corporate healthcare sector, where Manipal and Apollo hospital networks have pioneered transparent total-cost-of-ownership modeling for surgical suite investments.
Asia-Pacific Intraoperative Imaging Market Segmentation
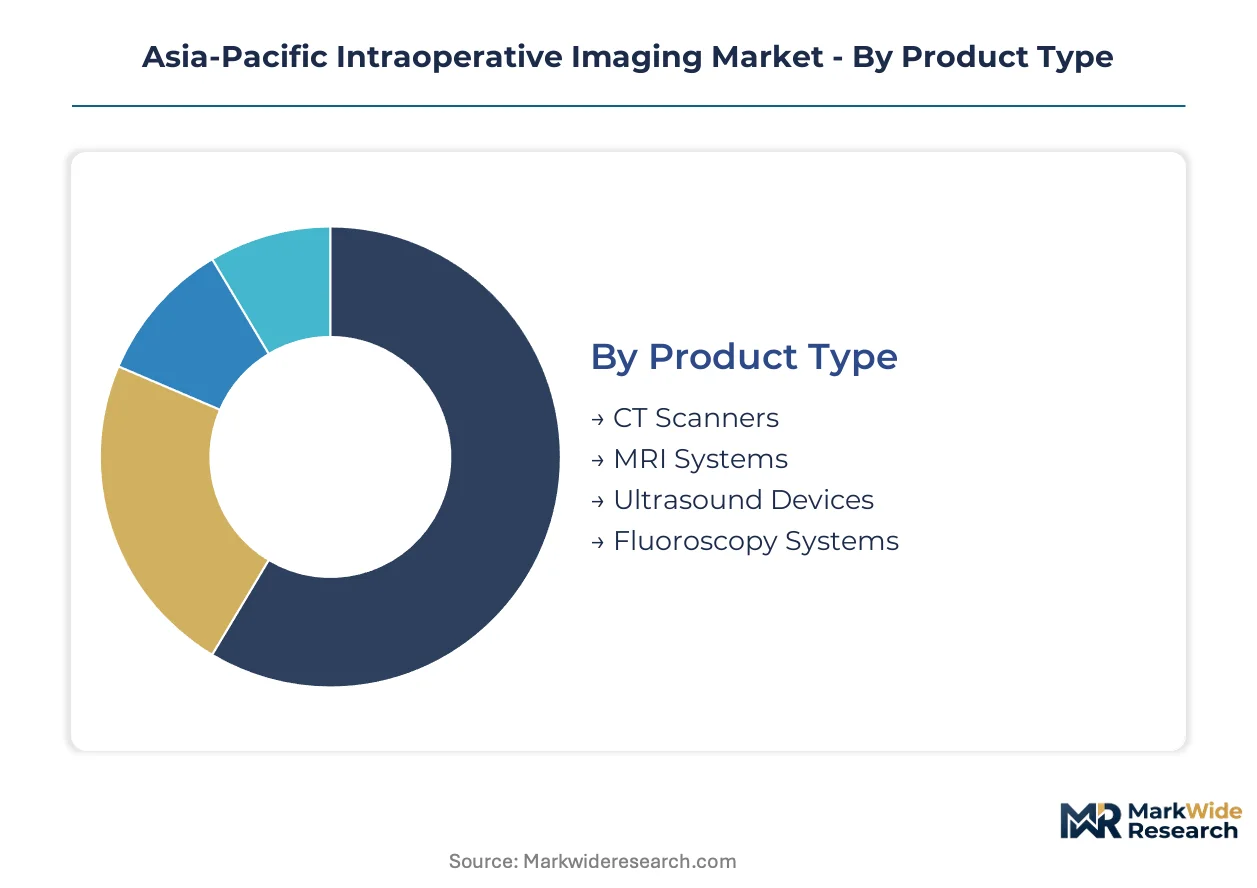
Intraoperative imaging equipment exhibits sharply divergent margin structures across hardware categories, with MRI systems commanding premium placement in neurosurgery suites while ultrasound platforms penetrate orthopedic trauma settings at compressed price points. Technology unbundling is fragmenting traditional bundled procurement models, forcing vendors to defend position through software licensing rather than closed-system hardware dominance.
Product Type:
Margin pools concentrate in MRI-integrated surgical suites where 1.5-tesla gantries enable real-time margin confirmation without patient transfer, while CT scanners face pricing pressure from 3D cone-beam substitution in cardiac catheterization labs.
- CT Scanners:Flat-panel C-arm systems with 3D reconstruction capability are displacing conventional fluoroscopy in cardiac catheterization labs across China's tier-one cities. Orthopedic trauma centers in India's corporate hospital chains now prioritize cone-beam CT for sub-millimeter spatial resolution in spinal navigation procedures.
- MRI Systems:1.5-tesla intraoperative MRI gantries integrate directly with surgical navigation software to enable immediate anatomical confirmation during cranial and spinal procedures. China's tier-one cities report sustained demand for MRI-integrated suites as neurosurgery volumes climb fastest in Beijing and Shanghai hospital networks.
- Ultrasound Devices:Portable intraoperative ultrasound platforms are gaining traction in orthopedic trauma settings across India's Apollo and Manipal hospital chains, accelerated by CDSCO alignment with international quality management standards.
- Fluoroscopy Systems:Digital flat-panel detectors are replacing conventional image intensifiers in Southeast Asian surgical suites, though radiologic technologist shortages are collapsing installation timelines for hybrid imaging infrastructure.
MRI Systems hold installed capacity. Ultrasound Devices are rotating up the share rankings.
Technology:
Software-defined imaging components are decoupling algorithmic enhancement from hardware acquisition, with advanced visualization platforms opening premium pricing tiers in spine navigation applications.
- 2D Imaging:Conventional fluoroscopy retains mature installed bases in cardiac catheterization labs but faces displacement pressure as 3D reconstruction capabilities commoditize planar imaging.
- 3D Imaging:Cone-beam CT reconstruction algorithms integrated with flat-panel C-arms enable real-time volumetric imaging without patient transfer. China's NMPA electromagnetic safety standards and Japan's PMDA streamlined approval pathways are accelerating 3D platform deployment across neurosurgical suites in tier-one Chinese and Japanese hospital networks.
- Augmented Reality:AR overlays combining pre-operative planning with intraoperative imaging are penetrating orthopedic and neurosurgical segments in Australia's academic medical centers, though multimodal system integration extends training periods.
- Advanced Visualization:Software platforms separating pre-operative planning from intraoperative 3D imaging are climbing the fastest in revenue contribution as Chinese hospital networks unbundle hardware procurement from algorithm licensing.
3D Imaging anchors current revenue contribution. Advanced Visualization is expanding most quickly in licensing revenue.
Application:
Procedure volume concentration in China's tier-one cities is driving neurosurgery and spine surgery applications, while cardiac surgery faces substitution pressure from interventional cardiology shifts.
- Neurosurgery:Cranial and spinal procedure volumes in Beijing, Shanghai, and Guangzhou are creating sustained demand for real-time margin confirmation capabilities. Japan's PMDA streamlined electromagnetic safety validation protocols are accelerating MRI-integrated suite upgrades across tier-one Chinese hospital networks.
- Orthopedic Surgery:Trauma centers across India's corporate hospital chains are replacing conventional image intensifiers with digital flat-panel detectors, driving replacement cycles in surgical imaging infrastructure for fracture reduction and joint reconstruction procedures.
- Cardiac Surgery:Conventional fluoroscopy retains installed base in open cardiac procedures but faces volume pressure as transcatheter interventions migrate to hybrid operating rooms with 3D imaging capability.
- Spine Surgery:Navigation software convergence with intraoperative CT and MRI is opening premium pricing tiers in Jiangsu and Zhejiang province hospitals, where underpenetrated surgical imaging infrastructure creates whitespace for remote service support models.
Neurosurgery commands premium placement. Spine Surgery is gaining share fastest in procedure volume.
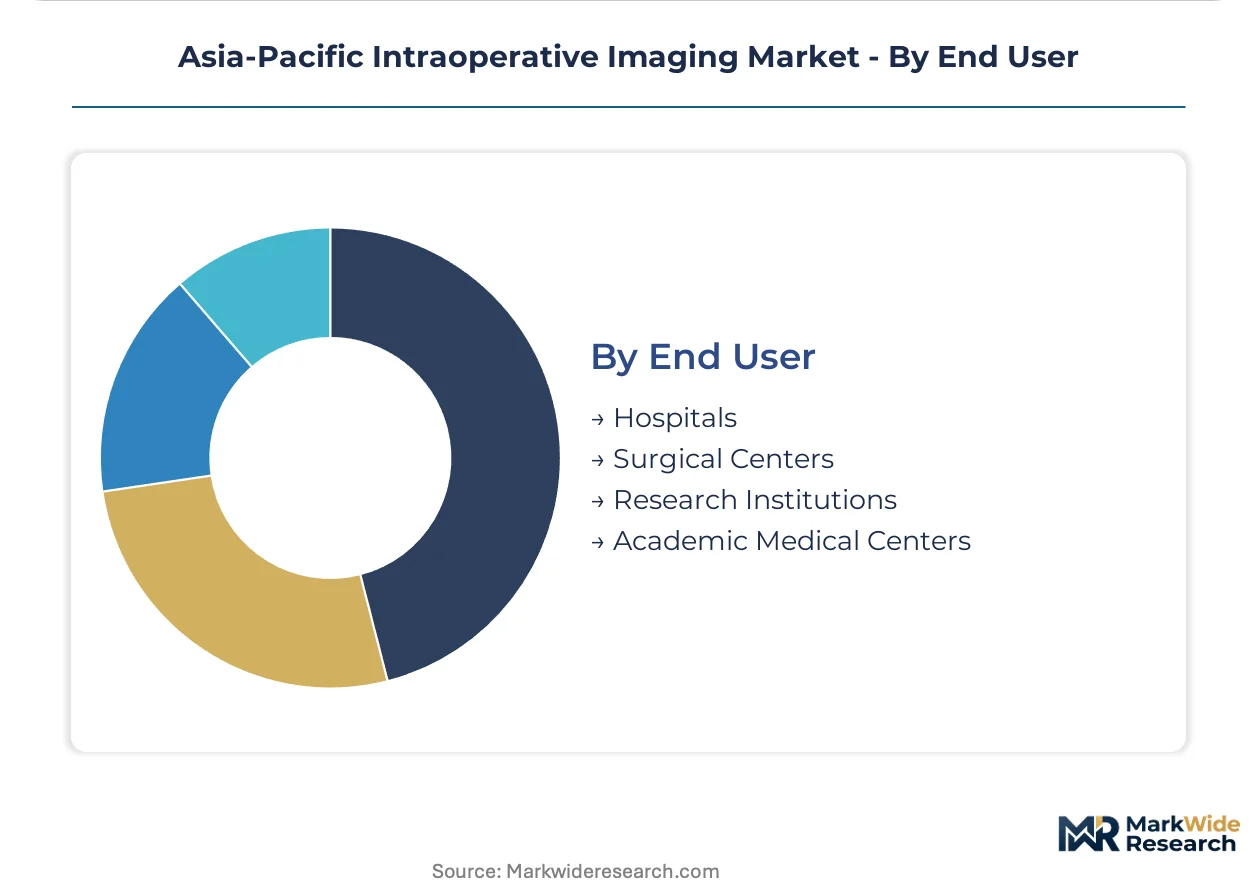
End User:
Procurement bifurcation between capital expenditure hardware budgets and operational expenditure service lines is most visible in India's corporate healthcare sector, where total-cost-of-ownership modeling is reshaping vendor relationships.
- Hospitals:Tier-one Chinese hospital networks are unbundling 1.5-tesla gantry acquisition from advanced visualization software licensing, treating maintenance and upgrade pathways as separately negotiable commercial terms. Tier-two Chinese hospitals in Jiangsu and Zhejiang provinces lack in-house biomedical engineering capacity for cryogen management, forcing dependence on vendor field service networks.
- Surgical Centers:Ambulatory surgical centers in Australia's metropolitan markets are adopting portable ultrasound platforms for orthopedic trauma procedures, leveraging TGA regulatory alignment with international standards.
- Research Institutions:Academic medical centers in Singapore and Australia are piloting open-architecture MRI platforms that decompose traditional bundled hardware-software procurement models.
- Academic Medical Centers:Training programs for radiologic technologists in Southeast Asian markets are struggling to produce sufficient imaging specialists capable of operating hybrid surgical equipment, collapsing installation timelines for intraoperative CT and MRI suites.
Hospitals concentrate installed base. Surgical Centers are climbing the fastest in equipment deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's streamlined electromagnetic safety protocols anchor Japan's regulatory influence across the Asia-Pacific intraoperative imaging landscape. China's NMPA and India's CDSCO are accelerating parallel harmonization efforts as neurosurgery volumes concentrate in tier-one metropolitan hospital networks.
China
Neurosurgery volumes in Beijing, Shanghai, and Guangzhou are climbing fastest among Asia-Pacific metropolitan clusters, creating sustained demand for 1.5-tesla MRI-integrated surgical suites. NMPA electromagnetic compatibility standards are accelerating 3D platform deployment across tier-one hospital networks. Jiangsu and Zhejiang provinces exhibit underpenetrated surgical imaging infrastructure where remote service support models are gaining traction.
Japan
PMDA consolidated software and hardware review processes for intraoperative MRI devices in 2024, compressing pre-market approval timelines for next-generation surgical imaging platforms. METI is monitoring open-architecture MRI procurement trends in academic medical centers. Tokyo and Osaka hospital networks are unbundling gantry acquisition from advanced visualization software licensing.
India
CDSCO alignment with ISO 13485 quality management systems accelerated import clearances for intraoperative ultrasound platforms across Apollo and Manipal corporate hospital chains. Corporate healthcare procurement committees pioneered transparent total-cost-of-ownership modeling for surgical suite investments. Delhi-NCR and Mumbai metropolitan clusters are replacing conventional image intensifiers with digital flat-panel detectors in orthopedic trauma centers.
Australia
TGA regulatory alignment with international standards enabled rapid adoption of portable ultrasound platforms in metropolitan ambulatory surgical centers. Australian regulators are monitoring Japan's PMDA streamlined framework for potential regional adoption. Sydney and Melbourne academic medical centers are piloting augmented reality overlays combining pre-operative planning with intraoperative imaging.
Southeast Asia
Radiologic technologist shortages across Vietnam, Thailand, and Indonesia are collapsing installation timelines for intraoperative CT and MRI suites in emerging hospital networks. ASEAN harmonization frameworks promise simplified multi-country product registration for imaging system vendors. Singapore is anchoring regional training programs for hybrid surgical equipment operation.
Asia-Pacific Intraoperative Imaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific intraoperative imaging market. Tier-one vendors defend position through service uptime guarantees and predictive maintenance networks rather than proprietary hardware lock-in alone. Equipment specialists and software-defined imaging platforms represent the dominant competitive archetypes. Strategic moves concentrate on technology licensing partnerships and unbundled software subscription models.
Among diversified health technology conglomerates, GE HealthCare and Siemens Healthineers AG occupy positions spanning hardware manufacturing and service network density. Koninklijke Philips N.V. exemplifies the imaging platform specialist archetype with concentrated exposure to surgical visualization technologies.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Medtronic |
| Shimadzu Corporation |
| Brainlab AG |
| Ziehm Imaging GmbH |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corp. |
| Others |
Pricing and Supply Chain Analysis
Flat-panel C-arm systems displacing conventional image intensifiers in Southeast Asian surgical suites are simultaneously redrawing component sourcing maps and compressing hardware margin pools across the Asia-Pacific intraoperative imaging landscape. This substitution dynamic redirects supply flows toward South Korean and Japanese detector manufacturers while forcing legacy fluoroscopy vendors into defensive service-contract pricing.
Pricing Analysis
Price spreads between Japan's tier-one academic medical centers and India's corporate hospital chains reach multiples on equivalent MRI gantry configurations, reflecting divergent after-sales bundling expectations and electromagnetic certification tiers. Pricing stratifies across premium, standard, and economy tiers anchored to NMPA versus PMDA validation pathways, with tier-two Chinese hospitals exhibiting acute price sensitivity due to constrained capital expenditure budgets. Cost compression in fluoroscopy hardware is intensifying because 3D cone-beam reconstruction capabilities commoditize planar imaging, while neurosurgery suites in Beijing and Shanghai show least price sensitivity on integrated MRI-navigation packages.
Supply Chain Analysis
Port congestion at Shanghai and Singapore container terminals elevates inbound logistics costs for cryogen shipments and gradient coil assemblies destined for intraoperative MRI installations across Jiangsu and Zhejiang provinces. Manufacturing concentration rests on Japan, Germany, and the United States for superconducting magnet assemblies, while South Korea and Taiwan supply flat-panel detector substrates and ASIC controllers. Single-source vulnerability in helium-3 cooling systems creates supply chain risk given export licensing restrictions. Distribution runs through authorized service networks rather than direct hospital relationships, with GE HealthCare and Siemens Healthineers AG maintaining captive field engineering capacity in tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific intraoperative imaging market sits at an early-cycle expansion phase justified by neurosurgery volume concentration in Chinese tier-one cities that has yet to saturate secondary metropolitan clusters.
For Market Incumbents: Secure predictive maintenance network density in tier-two Chinese provinces before radiologic technologist scarcity hardens into structural installation bottlenecks. Anchor software licensing revenue through open-architecture MRI platform partnerships with Apollo and Manipal hospital chains, defending against unbundling pressure by separating algorithm monetization from hardware margins. For New Entrants and Emerging Players: Lead with portable ultrasound platforms targeting orthopedic trauma settings in India's corporate hospital chains, where CDSCO harmonization with ISO 13485 collapsed import clearance timelines. Penetrate Jiangsu and Zhejiang province whitespace through remote service support models that circumvent on-site specialist requirements, pricing below incumbent field service networks while matching uptime guarantees. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors software-defined imaging platform specialists over pure hardware manufacturers across the five-to-ten year viability window. Target acquisition archetypes combining advanced visualization algorithms with established hospital system partnerships in China or India. Monitor PMDA electromagnetic safety protocol adoption rates across Australian and Singaporean regulators as inflection indicator for regional harmonization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Service Support Model Deployment | Enables tier-two Chinese hospital penetration without radiologic technologist presence on-site. |
| Advanced Visualization Software Licensing | Captures recurring revenue as Chinese networks unbundle hardware from algorithm procurement. |
| Open-Architecture MRI Platform Partnership | Defends vendor position against gantry commoditization through separable software monetization. |
| ASEAN Harmonization Framework Alignment | Reduces multi-country registration overhead for Southeast Asian market expansion. |
| Predictive Maintenance Network Expansion | Addresses cryogen management skill gaps in tier-two Chinese hospital infrastructure. |
Research Methodology
Operator-level perspectives from neurosurgeons, biomedical engineers, hospital procurement committee members, and radiologic technologists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from NMPA device registration databases, PMDA pre-market approval filings, hospital procurement contract disclosures, and ASEAN medical device harmonization framework documentation. Bottom-up installation base modeling triangulated against top-down neurosurgery volume projections across metropolitan hospital networks.
Sensitivity analysis tested forecast robustness across alternative neurosurgery volume growth trajectories and regulatory approval timeline scenarios over the projection horizon. Segmentation dimensions modeled include product modality, technology tier, surgical application, and end-user facility type alongside regional regulatory cluster differentiation. CAGRs derived from equipment replacement cycle analysis and unmet penetration rates in tier-two Chinese provinces, with specific inputs for radiologic technologist training pipeline capacity and electromagnetic safety validation protocol adoption curves.
Forecasts assume regulatory continuity in PMDA, NMPA, CDSCO, and TGA regimes; material policy shifts would require re-modeling. Specific risk factors include ASEAN harmonization framework implementation delays, helium supply chain disruptions affecting cryogen-dependent MRI platforms, and radiologic technologist training program expansion shortfalls in Southeast Asian markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market