
 Nonvascular Interventional Radiology Devices Market | 2026-2036
Nonvascular Interventional Radiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nonvascular Interventional Radiology Devices Market Analytics
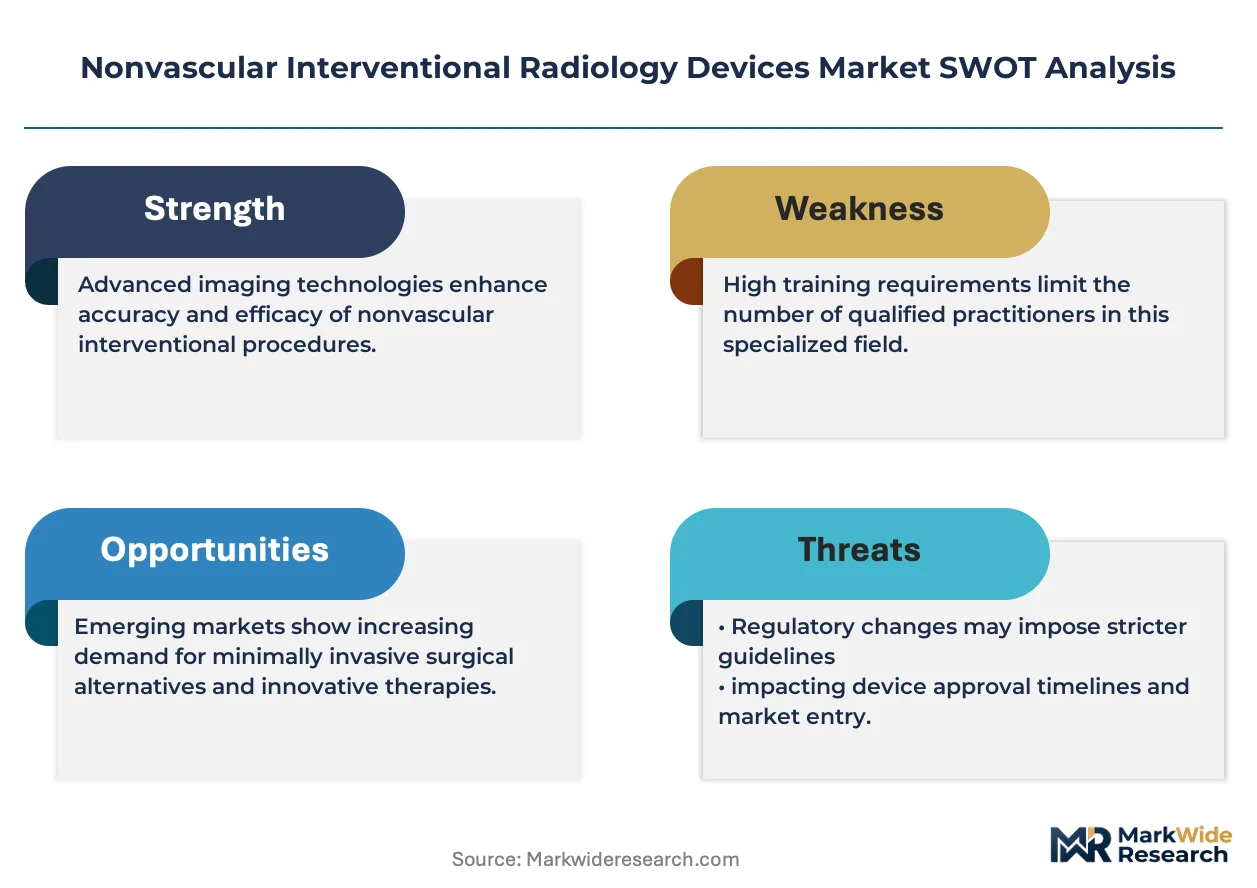
Interventional radiologist workforce density is bifurcating market access between mature urban hospital systems and underserved secondary markets. Boston Scientific Corporation leverages integrated catheter and guidewire portfolios to sustain dominance in drainage and biopsy workflows. Medtronic Plc anchors its position through deep fluoroscopy platform installations that lock in recurring device consumption. Stryker Corporation competes by specializing in navigation-enabled delivery systems that reduce procedure variability.
Nonvascular interventional radiology devices encompass percutaneous instruments designed for non-arterial access, typically constructed from nitinol, polyurethane, or polyethylene compositions and engineered to operate under real-time imaging guidance at sub-millimeter precision. These instruments enable tissue sampling, fluid evacuation, thermal destruction, and lumen restoration without open surgical exposure. Catheters and guidewires constitute the mature revenue base where pricing pressure is most acute, while MRI-guided technology represents the fastest-expanding margin pool as magnet-compatible instrumentation commands premium positioning. Ablation applications are displacing conventional surgery in hepatic and renal oncology, redirecting capital budgets toward integrated imaging-therapy platforms.
FDA 510(k) clearances govern U.S. market entry for most biopsy needles and drainage catheters, while EU MDR conformity assessments now demand expanded clinical evidence for Class IIa and IIb nonvascular devices. Japan's PMDA maintains distinct biological safety testing protocols that extend registration timelines for polymer-based ablation probes. Stakeholders must monitor reimbursement granularity for image-guided procedures as payors tighten prior-authorization criteria across hospital outpatient and ambulatory surgery settings.
Market Dynamics
CT-guided and ultrasound-guided system procurement is compressing procedure time requirements while expanding treatable patient populations, fundamentally altering capital allocation across hospital radiology departments.
Growth Catalysts
- Oncology Biopsy Volume Expansion:Rising incidence of hepatic and renal malignancies is expanding hospital investments in percutaneous sampling infrastructure across tertiary referral networks in the United States, Germany, and Japan.
- EU MDR Recertification Pathways:Expanded clinical evidence requirements for Class IIa and IIb devices are accelerating product portfolio rationalization among manufacturers with robust quality management systems.
- Nitinol Alloy Precision Engineering:Advances in shape-memory wire manufacturing are enabling sub-millimeter catheter tip articulation that reduces fluoroscopy exposure during complex drainage procedures.
Market Restraints
- Polymer Raw Material Concentration:Specialized polyurethane and polyethylene feedstocks for ablation probe insulation concentrate among Asian chemical suppliers, exposing manufacturers to input cost volatility.
- Japan PMDA Biological Safety Protocols:Distinct polymer biocompatibility testing requirements extend registration timelines by 12-18 months compared to FDA 510(k) pathways.
- Open Surgical Substitution:Conventional resection retains preference in certain pancreatic and biliary interventions where percutaneous access carries elevated complication risk profiles.
Strategic Opportunities
- Ambulatory Surgery Center Channel Development:Shifting site-of-service economics for image-guided tumor ablation is creating dedicated procurement contracts outside traditional hospital supply agreements.
- MRI-Guided Platform Convergence:Integration of magnet-compatible instrumentation with real-time thermometry is opening premium positioning for procedures previously confined to CT guidance.
- India CDSCO Registration Acceleration:Streamlined medical device import pathways under revised 2017 rules are reducing time-to-market for drainage catheter portfolios in secondary urban markets.
Industry Challenges
- Interventional Radiologist Workforce Density:Urban hospital systems capture disproportionate procedural volume while secondary markets face specialist recruitment constraints that limit device utilization rates.
- EU MDR Technical Documentation Burden:Expanded clinical evaluation report requirements for legacy product lines are consuming regulatory affairs capacity that would otherwise support new product development.
- Legacy Fluoroscopy System Integration:Navigation-enabled delivery systems require software interface compatibility with installed base imaging platforms, complicating interoperability certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonvascular Interventional Radiology Devices Market |
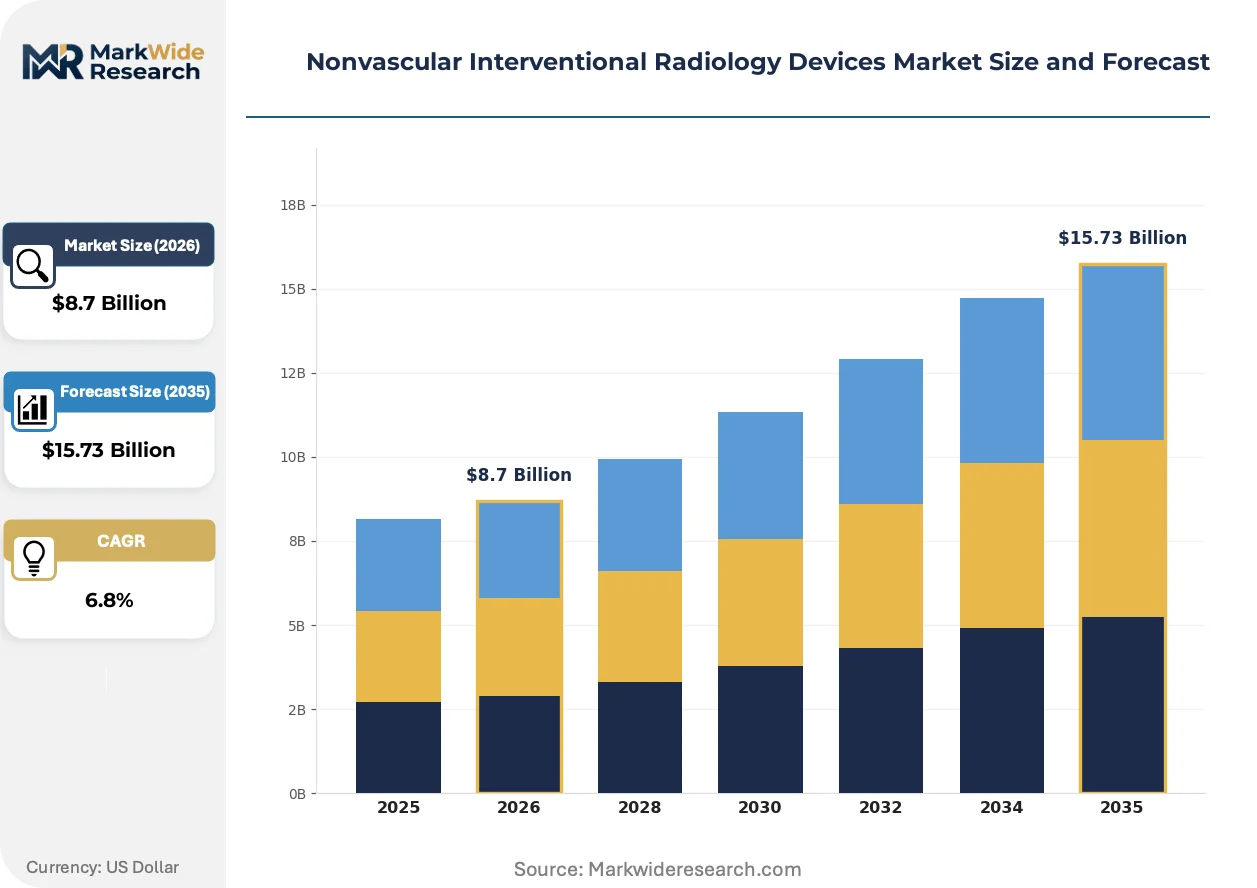
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Guidewires, Balloons End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Ambulatory Surgery Centers Technology: Fluoroscopy, Ultrasound, MRI-guided, CT-guided Application: Biopsy, Drainage, Ablation, Tumor Treatment |
| Companies Covered | Boston Scientific Corporation, Medtronic Plc, Stryker Corporation, Cook Medical, Teleflex Incorporated, Penumbra, Inc., AngioDynamics, Inc., Merit Medical Systems, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonvascular Interventional Radiology Devices Market Evolving Landscape
Real-time imaging fusion and disposable instrument miniaturization are compressing procedure variability while expanding treatable anatomical targets beyond traditional vascular access corridors.
Electromagnetic tracking technology for needle navigation is miniaturizing sensor arrays to sub-2mm diameters compatible with standard biopsy instruments. Academic medical centers in the United States and Germany are piloting these systems for thoracic and abdominal interventions where respiratory motion complicates freehand targeting. The technology is miniaturizing hardware requirements from cart-based platforms to handheld probe attachments, reducing capital barriers for mid-tier hospital adoption.
EU MDR conformity assessment timelines for Class IIb ablation devices now demand prospective clinical data that legacy predicate comparisons cannot satisfy. Manufacturers with pre-2021 CE certificates face portfolio pruning decisions as notified body capacity constrains recertification throughput. Electromagnetic navigation and thermometry-integrated probes encounter the most extended review cycles due to novel software classification under Rule 11.
Hospital procurement committees are unbundling capital equipment from disposable device contracts, forcing manufacturers to compete on instrument unit economics rather than system placement lock-in. Radiology department purchasing in Germany and Japan now separates imaging platform decisions from catheter and guidewire vendor selection. This pattern is most visible in university hospital networks where centralized value analysis committees override individual physician preference.
Nonvascular Interventional Radiology Devices Market Segmentation
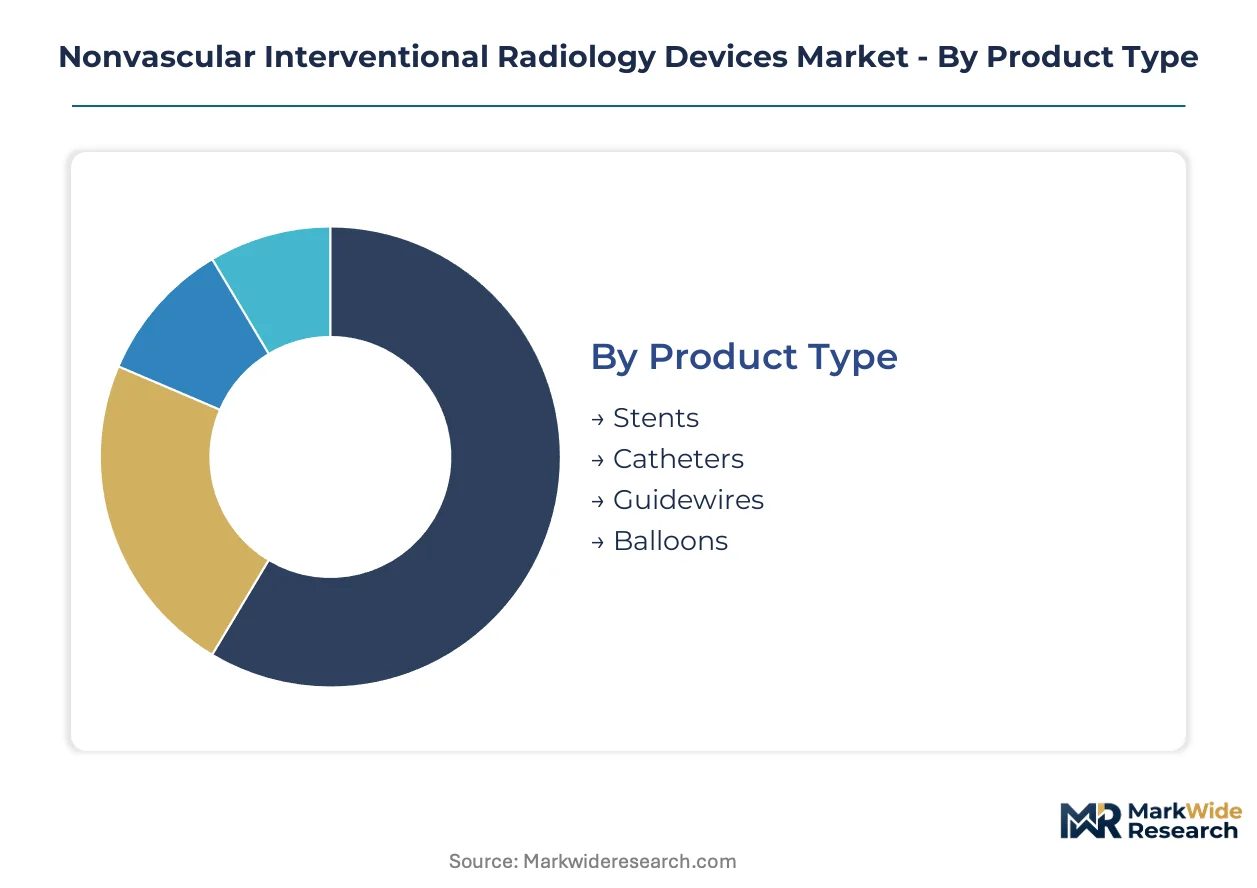
Segmentation in nonvascular interventional radiology reveals how regulatory pathways, imaging modality preferences, and site-of-service economics fragment procurement patterns across device categories. Manufacturers must align portfolio breadth with specific reimbursement and certification requirements rather than pursuing uniform market approaches.
Product Type:
FDA 510(k) clearances for Class II devices apply differential evidentiary standards across metallic and polymer-based instruments, shaping competitive entry barriers.
- Catheters:Polyurethane and polyethylene constructions dominate drainage and biopsy workflows. Hospital procurement committees in the United States and Germany unbundle these from capital equipment contracts, intensifying unit-price competition among suppliers.
- Guidewires:Nitinol alloy engineering enables sub-millimeter tip articulation for complex access. Japanese PMDA biocompatibility protocols extend registration timelines for polymer-coated variants, favoring established suppliers with regulatory affairs capacity.
- Stents:Self-expanding metallic designs address biliary and ureteral strictures.
- Balloons:Dilatation platforms restore luminal patency in benign strictures.
Established volume favors catheters; emerging adoption favors guidewires with navigation integration.
End User:
Reimbursement granularity for image-guided procedures varies sharply across inpatient, outpatient, and freestanding settings, redirecting capital investment flows.
- Hospitals:Tertiary referral networks concentrate complex oncology interventions requiring multimodal imaging integration. Germany's university hospital systems anchor European demand for CT-guided ablation platforms through centralized value analysis committees.
- Ambulatory Surgery Centers:Site-of-service economics for tumor ablation are expanding dedicated procurement contracts outside traditional hospital supply agreements. United States payor prior-authorization tightening favors ASCs with established utilization management protocols.
- Outpatient Clinics:Secondary urban markets in Japan face interventional radiologist recruitment constraints.
- Diagnostic Centers:Biopsy-only workflows limit device portfolio requirements.
Revenue concentration sits with hospitals; margin expansion concentrates in ambulatory surgery centers.
Technology:
EU MDR Rule 11 software classification creates divergent conformity assessment burdens across real-time imaging modalities.
- CT-guided:Established infrastructure dominates hepatic and renal tumor ablation. Procurement in the United States concentrates among academic medical centers with dedicated interventional radiology suites and research trial capacity.
- MRI-guided:Magnet-compatible instrumentation with integrated thermometry commands premium positioning for procedures previously confined to CT guidance. Extended EU MDR review cycles for novel software classification constrain notified body throughput for new entrants.
- Ultrasound:Point-of-care accessibility drives biopsy volume in secondary markets.
- Fluoroscopy:Deep platform installations lock in recurring device consumption through installed base effects.
CT-guided systems anchor current revenue; MRI-guided platforms are climbing the fastest on premium positioning.
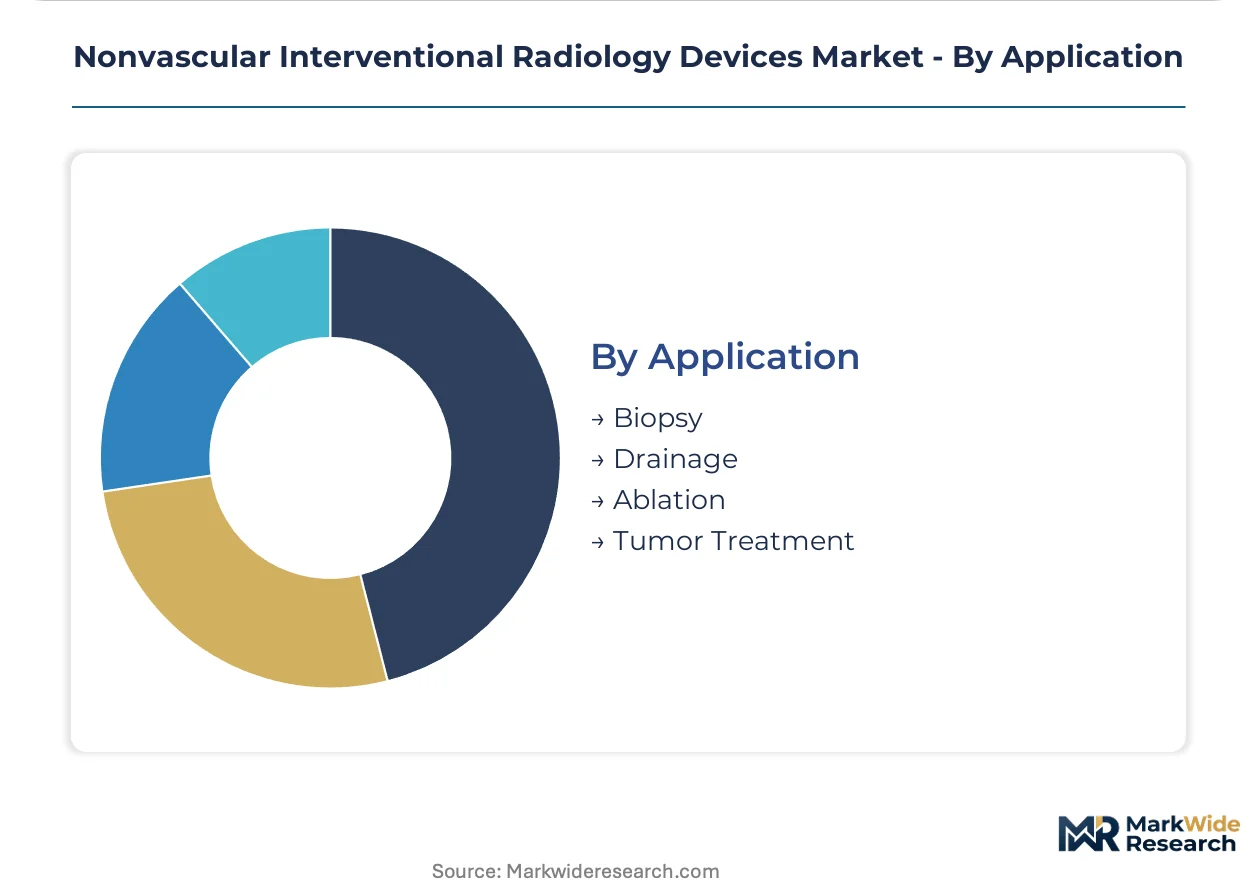
Application:
Clinical evidence requirements for Class IIb devices under EU MDR reshape competitive positioning across therapeutic versus diagnostic use cases.
- Ablation:Thermal destruction platforms displace conventional surgery in hepatic and renal oncology. Prospective clinical data demands for EU MDR recertification favor manufacturers with robust quality management systems and pre-2021 CE certificate continuity.
- Biopsy:Percutaneous sampling infrastructure expansion tracks rising malignancy incidence. United States tertiary networks drive CT-guided system procurement for thoracic and abdominal targets where respiratory motion complicates freehand techniques.
- Drainage:Fluid evacuation procedures concentrate in hospital-based workflows.
- Tumor Treatment:Combined modality approaches integrate ablation with adjuvant therapies.
Biopsy generates procedural volume; ablation captures capital intensity and premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearances anchor the United States as the procedural volume leader, while EU MDR recertification timelines and Japan's PMDA protocols create divergent market access conditions across developed economies.
United States
Tertiary referral networks concentrate CT-guided ablation procurement for hepatic and renal oncology. CMS reimbursement granularity for image-guided procedures tightens prior-authorization criteria across hospital outpatient and ambulatory surgery settings. Academic medical centers in Boston and Houston anchor multimodal imaging integration for complex interventions.
Germany
University hospital systems drive centralized value analysis committees that unbundle capital equipment from disposable device contracts. EU MDR conformity assessments for Class IIb ablation devices demand prospective clinical data that legacy predicate comparisons cannot satisfy. The Rhine-Ruhr corridor concentrates fluoroscopy platform installations that lock in recurring device consumption.
Japan
PMDA biological safety testing protocols for polymer-based ablation probes extend registration timelines by 12-18 months compared to FDA pathways. Secondary urban markets face interventional radiologist recruitment constraints that limit device utilization rates. Tokyo and Osaka metropolitan areas anchor demand for navigation-enabled delivery systems.
India
CDSCO registration acceleration under revised 2017 medical device rules reduces time-to-market for drainage catheter portfolios. Secondary urban markets in Maharashtra and Karnataka expand percutaneous sampling infrastructure as malignancy incidence rises. Mumbai and Bangalore clusters concentrate procurement committee formation for integrated imaging-therapy platforms.
United Kingdom
NHS England procurement frameworks separate imaging platform decisions from catheter and guidewire vendor selection. NICE technology appraisals for MRI-guided thermometry-integrated probes encounter extended review cycles. London and Manchester academic networks pilot electromagnetic tracking systems for thoracic interventions.
Nonvascular Interventional Radiology Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the nonvascular interventional radiology devices sector. The market structure consolidates around diversified medical technology conglomerates with deep fluoroscopy platform installations and specialized navigation-enabled delivery system manufacturers. Three archetypes dominate: integrated catheter-guidewire portfolio holders, magnet-compatible instrumentation developers, and disposable instrument miniaturization specialists. Competitive moves concentrate on strategic partnerships for software interface compatibility and portfolio diversification into MRI-guided platform convergence.
Among diversified technology conglomerates, Boston Scientific Corporation, Medtronic Plc, and Stryker Corporation occupy positions that exemplify distinct strategic archetypes. Boston Scientific represents the integrated portfolio holder with sustained dominance in drainage and biopsy workflows. Medtronic anchors its position through recurring device consumption tied to deep platform installations. Stryker exemplifies the navigation specialization vector with delivery systems that reduce procedure variability. These three entities collectively illustrate how market access bifurcates between mature urban hospital systems and underserved secondary markets based on workforce density and regulatory affairs capacity.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic Plc |
| Stryker Corporation |
| Cook Medical |
| Teleflex Incorporated |
| Penumbra, Inc. |
| AngioDynamics, Inc. |
| Merit Medical Systems, Inc. |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance tiers and EU MDR conformity classes simultaneously gate supplier qualification and stratify price positioning across catheter and guidewire portfolios. Manufacturers with pre-2021 CE certificate continuity command premium positioning for Class IIb ablation devices where prospective clinical data requirements exclude newer entrants from comparable pricing tiers.
Pricing Analysis
United States hospital procurement committees negotiate catheter unit costs 15-25% below German university hospital benchmarks, reflecting divergent value analysis committee structures. Three-tier pricing structure across premium navigation-enabled, standard fluoroscopy-compatible, and economy drainage tiers tracks certification grade and software integration depth. Cost compression in standard-tier guidewires is intensifying because procurement committees unbundle disposable contracts from capital equipment placements. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with research trial capacity demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for nitinol alloy feedstocks sourced from Japanese and South Korean specialty metals producers. Polyurethane insulation compounds for ablation probes concentrate among Chinese and Taiwanese chemical suppliers, while precision catheter extrusion capabilities anchor in Germany and the United States. Single-source vulnerability persists for magnet-compatible sensor arrays tethered to Japanese component manufacturers. Distribution runs through hospital value analysis committees in tertiary networks and GPO contracts for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across imaging modality preferences and site-of-service economics creates defendable niches for specialists. Shifting reimbursement granularity toward ambulatory settings splinters procurement authority away from centralized hospital committees.
For Market Incumbents: Secure EU MDR recertification priority for legacy Class IIb portfolios before notified body capacity constraints extend review cycles further. Deepen backward integration into nitinol alloy processing to offset Asian feedstock cost volatility. Navigation-enabled delivery systems face emerging competition from electromagnetic tracking miniaturization specialists. For New Entrants and Emerging Players: Anchor in ambulatory surgery center channel development where prior-authorization protocols favor new suppliers with dedicated utilization management support. India's CDSCO registration acceleration offers the most penetrable regulatory pathway for drainage catheter portfolios. Target procurement committee formation in Maharashtra and Karnataka secondary urban clusters. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape toward manufacturers with robust quality management systems and pre-2021 CE certificate continuity. Long-term viability over the next decade hinges on MRI-guided platform convergence capabilities. Watch electromagnetic navigation patent filings as inflection indicator for technology leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Notified body capacity constraints favor early filers with legacy CE certificate continuity. |
| Hospital System Partnership | Academic medical centers in Boston and Houston anchor multimodal imaging integration demand. |
| Software Companion Development | Real-time thermometry integration commands premium positioning for MRI-guided ablation platforms. |
| Reimbursement Strategy | CMS prior-authorization criteria tightening redirects volume toward ASCs with utilization protocols. |
| Geographic Expansion | CDSCO registration acceleration opens secondary urban markets in Maharashtra and Karnataka. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) clearance databases, EU MDR conformity assessment records, CMS reimbursement bulletins, and hospital procurement contract disclosures. Bottom-up instrumentation unit economics triangulated against top-down imaging platform installation data.
Across the analysis window, forecasts model product type segmentation by material composition and regulatory class, end user segmentation by site-of-service reimbursement tier, technology segmentation by imaging modality compatibility, and application segmentation by diagnostic versus therapeutic use case. CAGRs derive from procedural volume trajectories in oncology biopsy and tumor ablation, cross-referenced against capital equipment replacement cycles and workforce density projections.
Material uncertainties — regulatory timeline slippage at notified bodies, polymer biocompatibility testing protocol changes, interventional radiologist recruitment shortfalls — sit outside the modeled envelope. Forecasts reflect assumptions about EU MDR recertification throughput and PMDA registration timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Polysomnography Devices Market
Medical Devices
Germany Anesthesia Devices Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Ultrasonic Skin Care Devices Market