
 Dental X-Ray Market | 2026-2036
Dental X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Dental X-Ray Market Intelligence
Radiologist technician shortages across outpatient dentistry is collapsing patient throughput capacity at independent practices. Dentsply Sirona leverages its integrated CAD/CAM and imaging ecosystem to capture recurring software revenue streams. Planmeca OY anchors its competitive position through Finnish manufacturing scale and direct digital radiography specialization. Carestream Dental navigates channel complexity by sustaining independent dealer networks alongside direct hospital contracts.
Dental X-ray systems generate ionizing radiation images of oral structures using tube voltages typically ranging from 60–90 kVp, with digital sensors replacing film-based capture through scintillator-photodiode arrays or CMOS technology. The primary commercial purpose centers on caries detection, periodontal assessment, and pre-operative surgical planning. Intraoral X-ray equipment dominates replacement cycles due to shorter asset lifespans and lower capital barriers, while cone beam computed tomography systems command premium positioning in implantology and orthodontic practices. Digital X-ray technology is displacing film-based systems as regulatory pressure mounts on chemical waste disposal and reimbursement incentives favor electronic health record integration.
FDA 510(k) premarket notification requirements govern device safety and efficacy claims for all systems sold in the United States, while ISO 13485 quality management certification serves as a baseline for international market access. EPA hazardous waste rules under RCRA constrain silver halide film processing in remaining analog installations. Stakeholders must monitor how AI diagnostic adjuncts trigger new FDA software-as-medical-device classification determinations that could reshape competitive moats.
Market Dynamics
Orthodontic clear aligner protocols are compressing imaging replacement cycles as practices require cephalometric precision for treatment planning. Digital sensor technology is displacing film-based capture while EPA hazardous waste rules under RCRA accelerate obsolescence of chemical processing infrastructure.
Growth Catalysts
- Clear Aligner Therapy Expansion:Orthodontic practices are expanding imaging fleets to support precise cephalometric analysis required by aligner protocols.
- FDA 510(k) Compression:Accelerated premarket notification pathways for AI-enhanced radiographic software are reducing time-to-market for diagnostic adjuncts.
- EHR Integration Incentives:Reimbursement structures favoring electronic health record connectivity are pulling dental service organizations toward standardized digital workflows.
Market Restraints
- CMOS Sensor Supply Concentration:Scintillator-photodiode array manufacturing concentrates in East Asian foundries, creating single-source vulnerability for digital sensor components.
- RCRA Compliance Burden:EPA hazardous waste disposal rules impose ongoing operational costs on remaining analog film processors.
- Ionizing Radiation Liability:ALARA principle enforcement and malpractice exposure limit throughput expansion at independent practices.
Strategic Opportunities
- AI Diagnostic Adjuncts:Software-as-medical-device classification under FDA 510(k) is creating white space for algorithmic caries detection and periodontal assessment tools.
- Cone Beam CT Penetration:Implantology and oral surgery practices represent underpenetrated demand for three-dimensional volumetric imaging systems.
- Multi-Site Standardization:Dental service organization consolidation creates procurement scale for integrated CAD/CAM and imaging ecosystem vendors.
Industry Challenges
- Radiologist Technician Scarcity:Outpatient dentistry faces collapsing patient throughput capacity due to qualified operator shortages at independent practices.
- ISO 13485 Certification Timelines:Quality management system audits create extended market access delays for international entrants seeking CE marking pathways.
- Legacy System Integration:Digital sensor retrofit compatibility with existing tube head infrastructure requires custom mounting solutions and electrical interface adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental X-Ray Market |
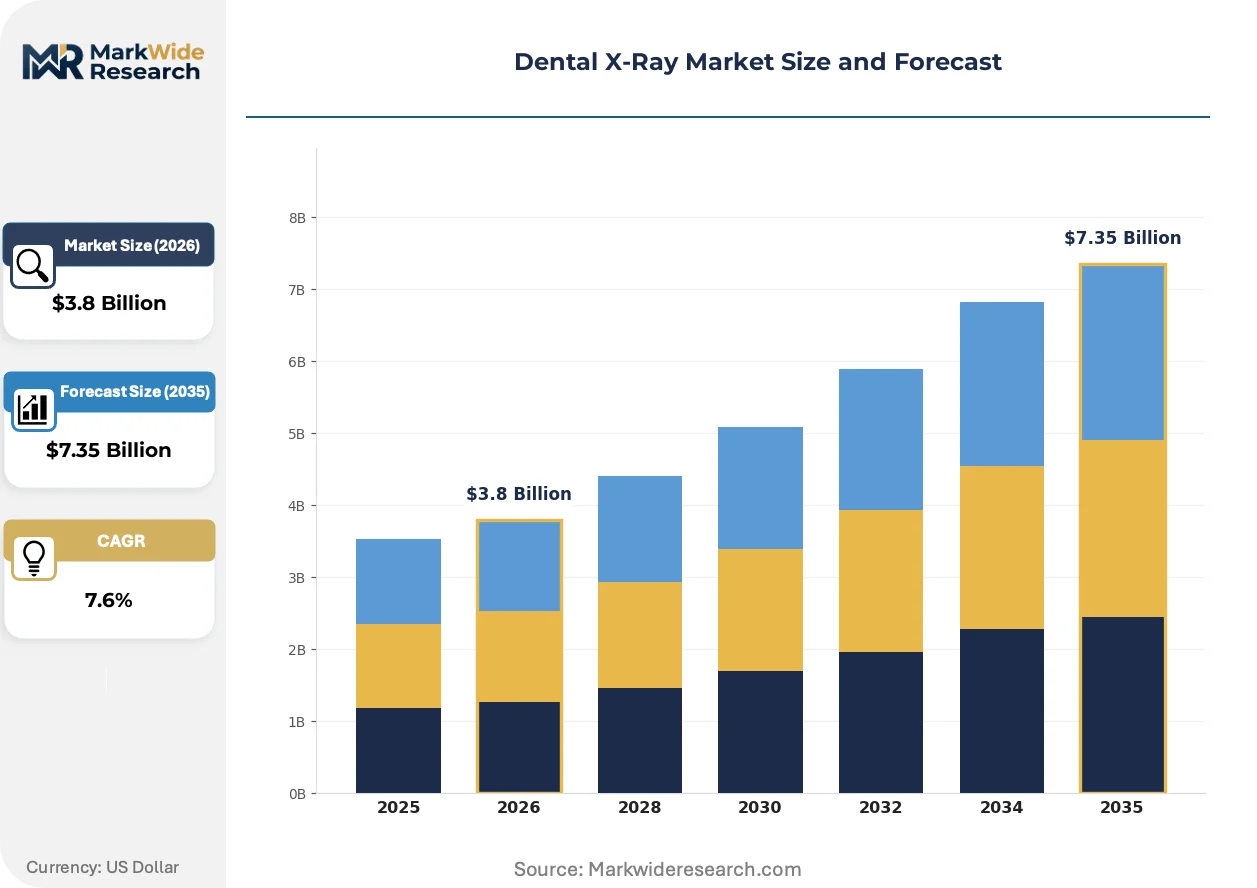
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
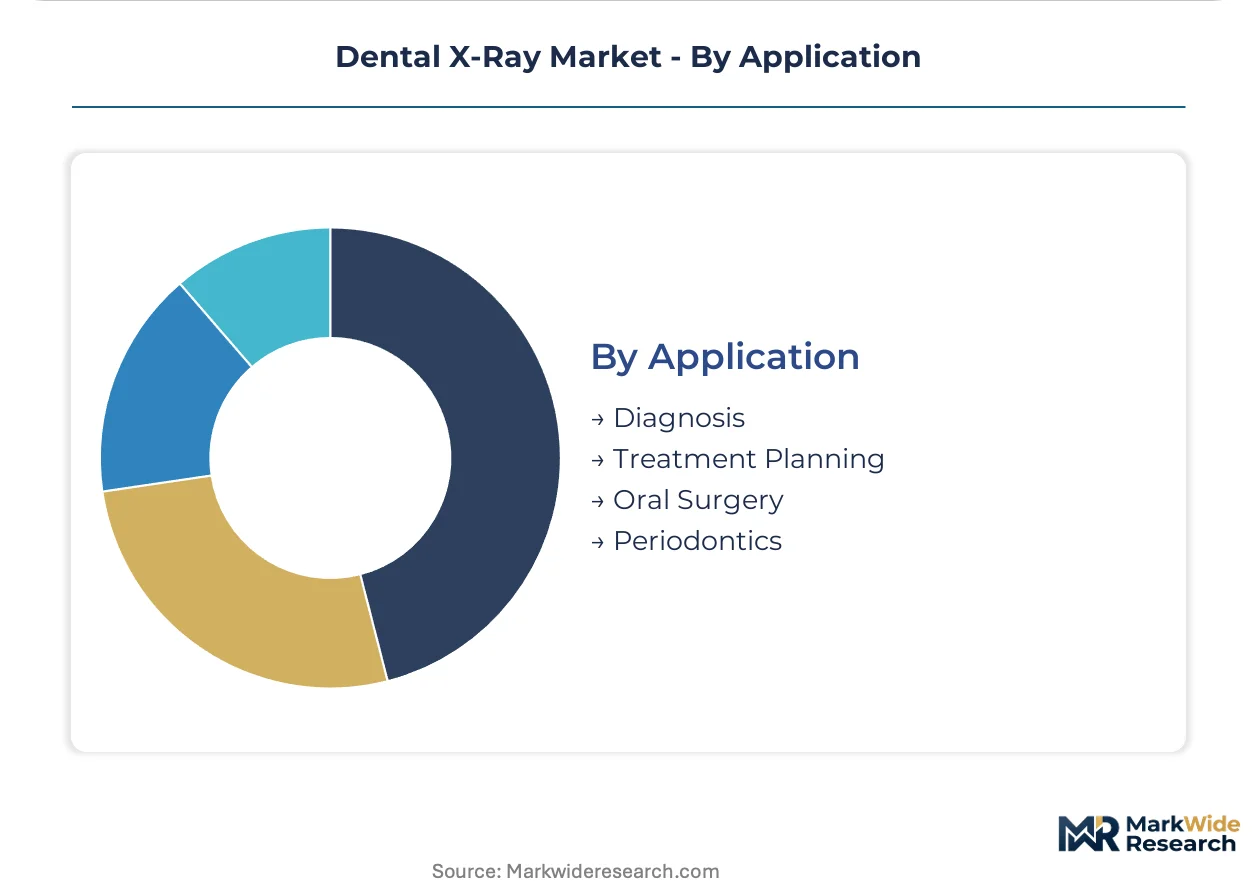
| Segmentation | Product Type: Intraoral X-Ray, Extraoral X-Ray, Cone Beam Computed Tomography, Digital X-Ray End User: Dental Clinics, Hospitals, Orthodontic Practices, Research Institutions Technology: Computed Radiography, Direct Digital Radiography, Film-Based Systems, 3D Imaging Application: Diagnosis, Treatment Planning, Oral Surgery, Periodontics |
| Companies Covered | Dentsply Sirona, Planmeca OY, Carestream Dental, Envista Holdings Corporation, VATECH, Danaher Corporation, Acteon Group, DÜRR DENTAL, Cefla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental X-Ray Market Strategic Shifts & Innovations
Three forces are restructuring competitive positioning: semiconductor-based detection is fragmenting hardware value chains, software classification rules are reshaping regulatory moats, and procurement consolidation is compressing vendor margins.
CMOS photodiode arrays are fragmenting the traditional film-to-digital transition pathway by enabling direct digital radiography without scintillator intermediate layers. Orthodontic and implantology practices are adopting these sensors at compressed replacement cycles compared to general dentistry. This technology is fragmenting vendor revenue models from capital equipment sales toward recurring software and sensor replacement streams.
FDA software-as-medical-device classification determinations for AI diagnostic adjuncts are creating new premarket notification requirements beyond traditional hardware 510(k) pathways. Algorithmic caries detection tools now face distinct efficacy validation standards separate from underlying sensor hardware. European orthodontic practices are responding through MDR technical documentation requirements for machine learning-enabled radiographic analysis.
After-sales service unbundling is disrupting traditional bundled maintenance contracts as dental service organizations negotiate direct parts procurement and third-party technical training. Independent dealer networks are losing exclusivity in multi-site network negotiations. This pattern concentrates in United States metropolitan markets where DSO consolidation has reached critical procurement scale.
Dental X-Ray Market Segmentation
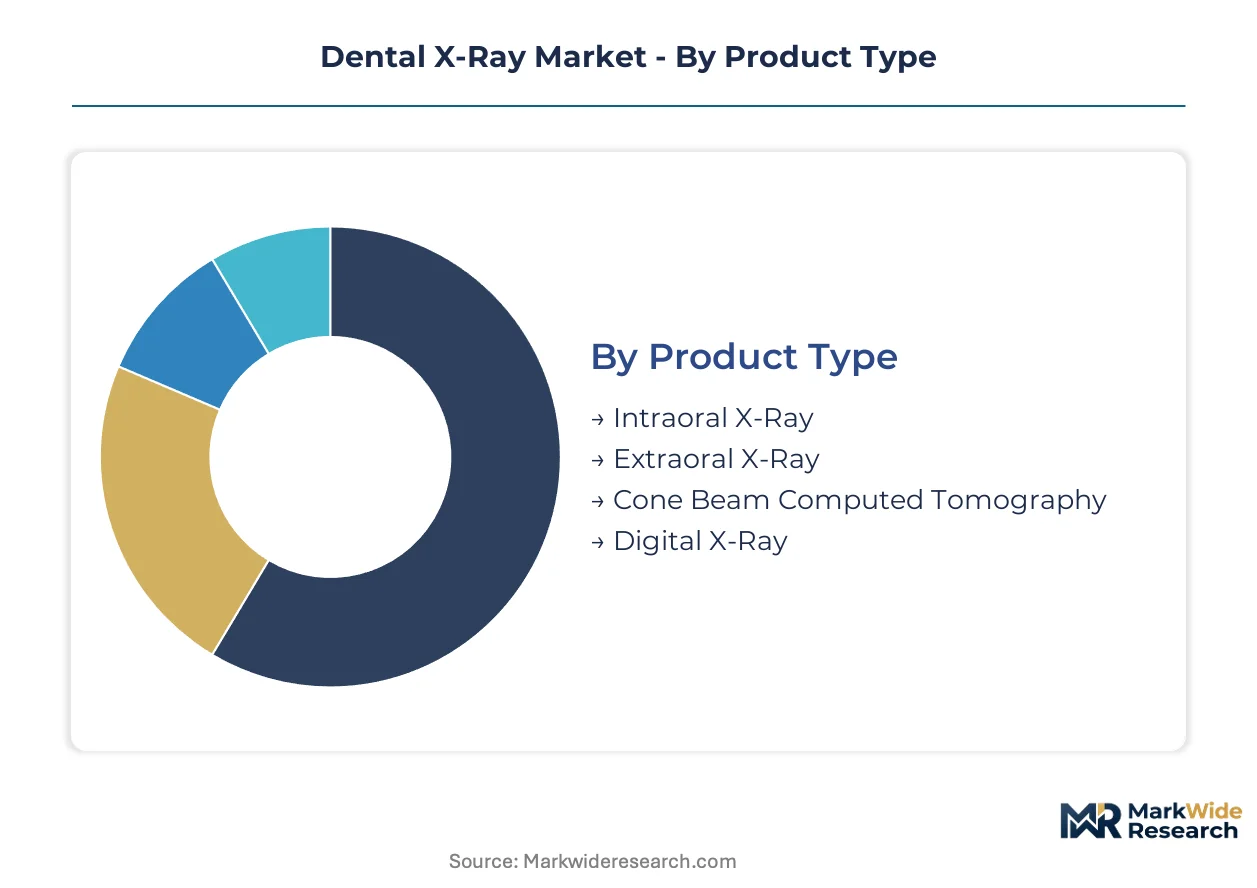
Segmentation in dental X-ray markets reveals distinct procurement patterns across clinical settings and technology tiers. Equipment replacement cycles, regulatory compliance burdens, and integration requirements vary sharply between high-volume hospital systems and independent orthodontic practices.
Product Type:
Domestic demand concentrates in intraoral and digital systems for general dentistry, while cone beam CT exports cluster in implantology-heavy markets across Germany, South Korea, and Brazil.
- Intraoral X-Ray:Tube heads operating at 60–70 kVp with rectangular collimation dominate caries detection workflows. Dental clinics in the United States and Japan drive replacement demand as film-based systems face EPA RCRA compliance deadlines.
- Cone Beam Computed Tomography:Volumetric scanners at 90–120 kVp capture 3D mandibular anatomy for implant surgical guides. Orthodontic practices in South Korea and Germany are expanding fleets to support clear aligner therapy protocols requiring precise cephalometric reconstruction.
- Extraoral X-Ray:Panoramic and cephalometric systems serve orthodontic assessment with broader field-of-view capture.
- Digital X-Ray:Scintillator-photodiode arrays and CMOS sensors displace silver halide film across all clinical settings.
Intraoral X-ray holds the largest share; momentum sits with cone beam CT as implantology penetration deepens.
End User:
Procurement scale separates institutional buyers from independent operators, with dental service organizations extracting volume discounts unavailable to solo practitioners.
- Dental Clinics:Independent and group practices generate the highest unit volume for intraoral sensor replacements. United States metropolitan markets show concentrated DSO procurement standardizing digital workflows across multi-site networks.
- Orthodontic Practices:Clear aligner therapy protocols demand precise cephalometric analysis, compressing imaging replacement cycles. Practices in Germany and South Korea are adopting direct digital radiography sensors at accelerated rates compared to general dentistry.
- Hospitals:Oral surgery departments and emergency dental services require integrated PACS connectivity and radiologist oversight.
- Research Institutions:Academic dental schools and craniofacial research centers drive validation studies for AI diagnostic adjuncts.
Dental clinics command volume leadership; orthodontic practices are climbing the fastest as aligner therapy expands.
Technology:
Cost tier stratification separates premium direct digital systems from legacy computed radiography serving price-sensitive installed bases.
- Direct Digital Radiography:CMOS photodiode arrays enable immediate image capture without scintillator intermediates. Japanese and German manufacturers anchor production scale for these sensors, supplying orthodontic practices seeking workflow compression.
- 3D Imaging:Cone beam reconstruction algorithms and volumetric rendering software command premium positioning. Implantology practices in Brazil and South Korea represent underpenetrated demand for three-dimensional surgical planning capabilities.
- Computed Radiography:Photostimulable phosphor plates bridge analog-to-digital transition for cost-constrained clinics.
- Film-Based Systems:Remaining silver halide installations face accelerating obsolescence from EPA hazardous waste enforcement.
Direct digital radiography holds installed base dominance; 3D imaging shows the steepest expansion trajectory.
Application:
Reimbursement intensity varies across diagnostic versus surgical applications, with oral surgery commanding higher per-procedure imaging allocation.
- Diagnosis:Caries detection and periodontal assessment drive routine intraoral capture volume. United States dental clinics prioritize AI-enhanced radiographic software for algorithmic lesion flagging under FDA 510(k) clearance pathways.
- Oral Surgery:Pre-operative planning for implant placement and third molar extraction requires three-dimensional anatomical mapping. German and South Korean surgical practices are standardizing cone beam CT protocols for mandibular nerve avoidance.
- Treatment Planning:Orthodontic and restorative workflows integrate imaging with CAD/CAM design systems.
- Periodontics:Bone loss quantification and furcation assessment utilize both 2D and 3D modalities.
Diagnosis captures the greatest procedure volume; oral surgery is gaining share fastest as implantology penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clear aligner therapy protocols drive cephalometric imaging demand in South Korea and Germany, while United States dental service organizations standardize digital workflows across multi-site networks at scale unmatched elsewhere.
United States
Dental service organizations in metropolitan markets extract volume discounts unavailable to independent practitioners. FDA 510(k) premarket notification pathways compress time-to-market for AI-enhanced radiographic software entrants. Greater Boston and Pacific Northwest clusters host validation studies for machine learning-enabled diagnostic adjuncts.
Germany
Implantology practices standardize cone beam CT protocols for mandibular nerve avoidance in pre-operative surgical planning. MDR technical documentation requirements govern machine learning-enabled radiographic analysis under European Union medical device regulation. Bavaria anchors manufacturing scale for direct digital radiography sensors serving orthodontic workflows.
South Korea
Orthodontic practices adopt direct digital radiography sensors at accelerated replacement cycles compared to general dentistry. MFDS regulates software-as-medical-device classification for algorithmic diagnostic tools separately from underlying hardware. Seoul Capital Area concentrates clear aligner therapy fleet expansion demanding precise cephalometric reconstruction.
Japan
Dental clinics drive replacement demand for intraoral systems as film-based installations face compliance deadlines. PMDA oversees device safety claims for digital sensor technology under pharmaceutical and medical device Act. Kanto region clusters manufacturing for CMOS photodiode arrays supplying orthodontic sensor demand.
Brazil
Oral surgery practices represent underpenetrated demand for three-dimensional volumetric imaging capabilities in implantology. ANVISA regulates premarket approval pathways for cone beam CT systems sold in the national market. São Paulo state concentrates procurement scale for integrated CAD/CAM and imaging ecosystem adoption.
Dental X-Ray Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in dental X-ray markets. The upper tier captures recurring software revenue through bundled CAD/CAM and imaging ecosystems, while specialists compete on direct digital radiography sensor performance and cone beam CT reconstruction algorithms. Two strategic archetypes dominate: full-platform vendors integrating hardware-software workflows, and component specialists supplying sensors and tube heads to third-party assemblers. Competitive moves concentrate on multi-site procurement consolidation and AI diagnostic adjunct certification.
Among integrated platform vendors, Dentsply Sirona and Planmeca OY occupy positions exemplifying contrasting geographic anchors. Dentsply Sirona represents the United States-based archetype leveraging ecosystem breadth, while Planmeca OY exemplifies Finnish manufacturing scale in direct digital radiography specialization. Carestream Dental sits within the channel-complexity tier, navigating independent dealer networks alongside direct hospital contracts.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca OY |
| Carestream Dental |
| Envista Holdings Corporation |
| VATECH |
| Danaher Corporation |
| Acteon Group |
| DÜRR DENTAL |
| Cefla |
| Others |
Cost & Logistics Intelligence
CMOS photodiode arrays substituting for scintillator-photodiode intermediates simultaneously concentrate sensor fabrication in East Asian foundries and compress hardware margins toward recurring software revenue models. This substitution dynamic reconfigures procurement economics as dental service organizations negotiate direct component sourcing while independent practices face elevated replacement costs for integrated digital sensors.
Pricing Analysis
Long-term service contracts dominate procurement between dental service organizations and integrated platform vendors, with per-unit transactional pricing persisting for independent clinic sensor replacements. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with premium tiers commanding extended warranty coverage. Cost compression in the independent clinic segment intensifies as CMOS sensor supply concentration limits vendor negotiation leverage. Dental service organizations exhibit lowest price sensitivity due to procurement scale, while solo practitioners face acute budget constraints.
Supply Chain Analysis
Japan and South Korea anchor CMOS photodiode array fabrication for direct digital radiography sensors, while Finland and Germany concentrate cone beam CT system assembly. Manufacturing draws from specialized scintillator crystals, precision tube head components, and semiconductor-grade silicon substrates. Single-source vulnerability in East Asian foundry capacity creates exposure to regional logistics disruption. Distribution runs through independent dealer networks alongside direct hospital contracts, with multi-site procurement increasingly bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental X-ray market is recovering from cyclical replacement compression as orthodontic clear aligner therapy protocols drive accelerated imaging fleet upgrades. Equipment replacement cycles shortened by cephalometric precision requirements justify near-term capacity positioning.
For Market Incumbents: Secure exclusive sensor supply agreements with East Asian foundries to preempt competitor access during capacity constraints. Deepen backward integration into CMOS photodiode design to reduce dependency on single-source semiconductor fabrication. Channel control through direct DSO contracting represents the critical defensive lever against independent dealer network erosion.
For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-tracks for AI diagnostic adjuncts open immediate white-space in algorithmic caries detection software. Target orthodontic practices in South Korea and Germany as the most penetrable segment given compressed replacement cycles and clear aligner protocol standardization. A software-as-medical-device certification-first go-to-market angle bypasses capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: FDA software-as-medical-device classification determinations reshapes the acquisition landscape toward algorithmic diagnostic capability rather than pure hardware scale. Long-term viability favors vendors with integrated CAD/CAM and imaging ecosystems capable of capturing recurring revenue streams. Watch for MFDS and PMDA regulatory harmonization on AI radiographic analysis as the signal indicating cross-border software licensing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Adjunct Certification | FDA 510(k) clearance for algorithmic caries detection creates new recurring revenue streams separate from hardware sales. |
| Direct Digital Radiography Sensor Development | CMOS photodiode arrays without scintillator intermediates compress workflow steps for orthodontic practices. |
| Cone Beam CT Reconstruction Algorithm Investment | Volumetric rendering software commands premium positioning in implantology practices across Brazil and South Korea. |
| Multi-Site Procurement Standardization | Dental service organization consolidation creates volume discounts unavailable to independent practitioners. |
| ISO 13485 Quality System Expansion | CE marking pathway acceleration enables faster European market access for international entrants. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement managers at dental service organizations, orthodontic practice administrators, and biomedical engineers at hospital oral surgery departments; and secondary validation against FDA 510(k) premarket notification databases, MFDS device registration filings, and ISO 13485 certification records. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across direct digital radiography, cone beam CT, and intraoral system categories.
Across the analysis window, the forecasting framework modeled demand by product type, end-user procurement scale, technology tier, and geographic regulatory cluster. CAGRs derived from replacement cycle compression analysis, clear aligner therapy penetration curves, and digital workflow adoption rates. Industry-specific inputs included orthodontic practice fleet expansion data and EPA RCRA compliance deadline impacts on analog system obsolescence.
Decision-makers should treat outputs as directional under base assumptions of sustained clear aligner therapy expansion and stable CMOS sensor supply; material deviation in semiconductor fabrication capacity or regulatory classification timelines would warrant model refresh. Recalibration cycles align with material shifts in FDA software-as-medical-device determinations and dental service organization consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
C-Arms Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Brazil Nuclear Imaging Market