
 Pediatric Imaging Market | 2026-2036
Pediatric Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Imaging Market Intelligence
High-field MRI specification tiers is collapsing the gap between adult and pediatric diagnostic capability, forcing equipment makers to redesign magnet architectures for smaller body habitus. Siemens Healthineers leverages its MAGNETOM platform to sustain pediatric-specific coil development, while GE Healthcare anchors its Edison ecosystem around AI-assisted scan-time reduction for uncooperative young patients. Canon Medical Systems differentiates through ultra-low-dose CT reconstruction algorithms that compete on radiation metrics against conventional adult protocols.
Pediatric imaging encompasses diagnostic modalities engineered for anatomical scales from neonates through adolescents, typically requiring reduced radiation exposure parameters, specialized receiver coils, and sedation-compatible throughput designs. The primary purpose is detection and monitoring of congenital anomalies, oncologic conditions, and traumatic injury in populations where tissue sensitivity and patient cooperation constrain standard adult protocols. Ultrasound maintains structural dominance in neonatal cranial and abdominal screening due to its non-ionizing profile and bedside accessibility, while 3D imaging advances fastest in pre-surgical orthopedic planning where complex skeletal deformities demand volumetric visualization. Digital radiography occupies the mature volume tier across outpatient facilities, though margin pools concentrate in contrast-enhanced MRI for pediatric oncology staging at specialized academic centers.
FDA ALARA guidance and EU MDR device classification for pediatric-specific indications shape product development roadmaps and market access timelines for manufacturers seeking dual-territory approval. EMA pediatric investigation plans further condition drug-device combination approvals where contrast agents accompany imaging procedures, creating parallel regulatory pathways that extend commercialization cycles. Stakeholders must monitor evolving AI-based image reconstruction standards from IEC working groups, as these will determine which vendors gain priority access to procurement frameworks at major pediatric hospital networks.
Market Dynamics
FDA ALARA guidance and EU MDR pediatric device classifications are forcing equipment redesign cycles toward low-dose architectures, compressing development timelines while expanding compliance costs across dual-territory approval pathways.
Growth Catalysts
- Neonatal neurology protocols:German university medical centers are integrating advanced MRI sequences for preterm brain development assessment, pulling high-field system upgrades into academic procurement cycles.
- ALARA principle adoption:US pediatric hospitals are expanding low-dose radiation system procurement following FDA guidance, prioritizing equipment with documented pediatric exposure reductions.
- AI reconstruction standards:IEC working groups are advancing image reconstruction benchmarks that favor vendors with validated pediatric algorithms, creating procurement preference hierarchies at major hospital networks.
Market Restraints
- Helium supply concentration:High-field MRI magnet production depends on helium sourced from concentrated geological deposits, exposing manufacturers to price volatility and allocation constraints.
- Pediatric coil specialization:Anatomically specific receiver coils require dedicated R&D investment with limited cross-application utilization, fragmenting production scale economics.
- EU MDR transition friction:Extended conformity assessment timelines for pediatric-specific indications are delaying market access for redesigned equipment platforms.
Strategic Opportunities
- Point-of-care ultrasound expansion:Neonatal intensive care units in India are adopting portable cranial ultrasound systems for bedside screening, bypassing radiology department bottlenecks.
- AI-assisted sedation reduction:Scan-time compression algorithms are enabling diagnostic completion without general anesthesia, opening pediatric oncology staging to outpatient settings.
- Orthopedic 3D planning:Pre-surgical volumetric visualization for complex skeletal deformities is penetrating pediatric surgery departments previously limited to 2D radiography.
Industry Challenges
- Pediatric radiologist scarcity:Fellowship-trained specialists capable of interpreting neonatal and adolescent imaging variants are concentrated at academic centers, constraining community hospital service expansion.
- Legacy PACS integration:New low-dose CT reconstruction algorithms require workflow reconfiguration within existing picture archiving systems, extending deployment timelines.
- Contrast agent compatibility:Drug-device combination approvals through EMA pediatric investigation plans demand parallel safety documentation, complicating contrast-enhanced MRI protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Imaging Market |
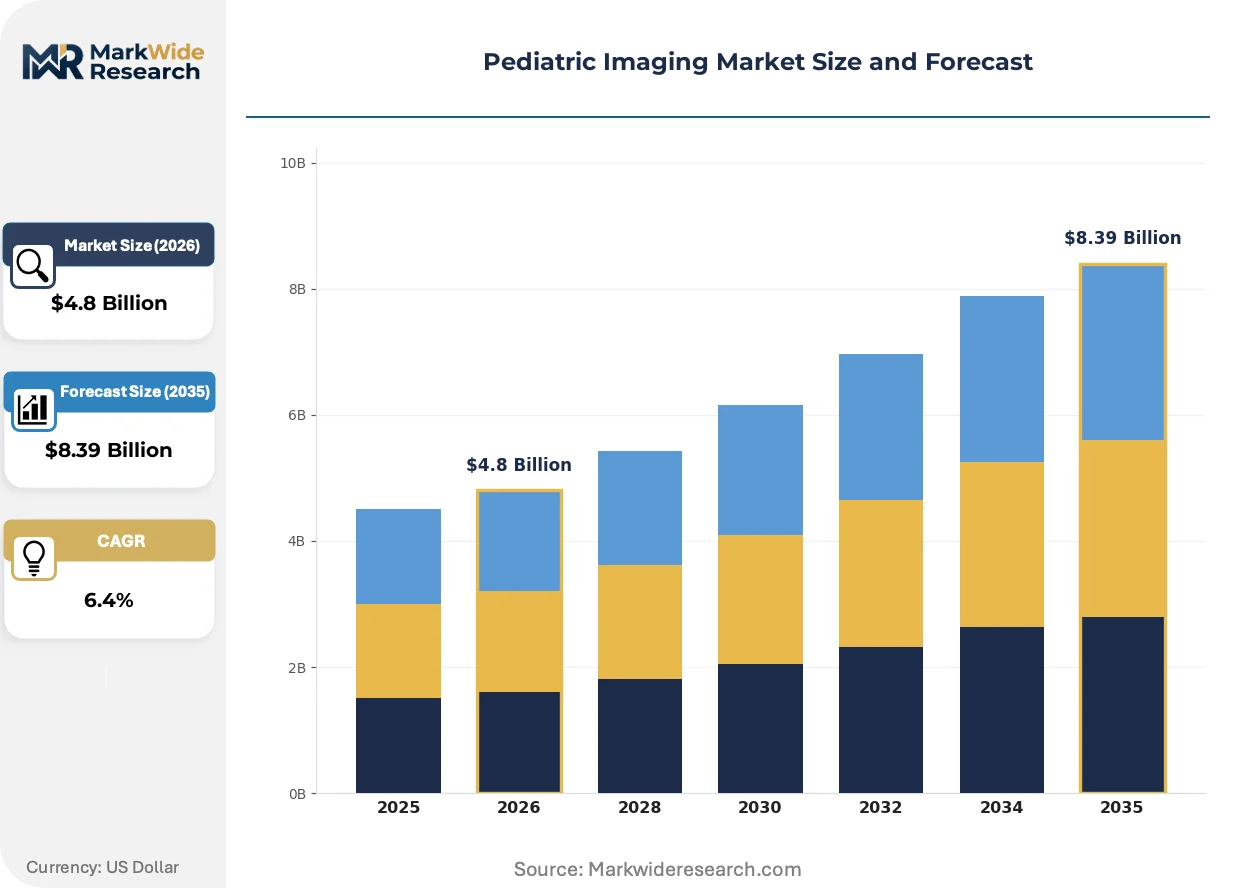
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, Ultrasound, CT Scan Technology: 3D Imaging, Contrast Agents, Digital Radiography, Fluoroscopy End User: Pediatric Hospitals, Diagnostic Centers, Outpatient Facilities, Research Institutions Application: Oncology, Neurology, Orthopedics, Cardiology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Samsung Electronics, Hitachi Ltd., Agfa-Gevaert Group, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Imaging Market Strategic Shifts & Innovations
Deep learning reconstruction and magnet miniaturization are collapsing the capability gap between adult and pediatric diagnostic platforms, while procurement frameworks increasingly weight radiation exposure metrics above throughput specifications.
Photon-counting CT detector technology is displacing energy-integrating architectures in pediatric protocols. Academic medical centers in Germany and the United States are prioritizing these systems for young patient cohorts. The shift is compressing acceptable dose thresholds and forcing incumbent vendors to accelerate detector platform refreshes or cede premium tier positioning.
EU MDR Article 52 pediatric-specific indication requirements are extending technical documentation obligations for imaging equipment. Manufacturers must now demonstrate clinical evidence across neonatal through adolescent age brackets prior to CE marking. This regulatory expansion most affects MRI and CT vendors seeking dual-territory approval alongside FDA 510(k) pathways, compressing parallel submission strategies.
Hospital procurement committees are unbundling equipment acquisition from multi-year service contracts, forcing vendors to compete on discrete maintenance pricing. Pediatric specialty networks in the United States are leading this disintermediation, separating capital expenditure approval from operational technology management. The pattern concentrates among consolidated health systems with dedicated biomedical engineering capabilities, particularly in the Northeast and Midwest regions.
Pediatric Imaging Market Segmentation
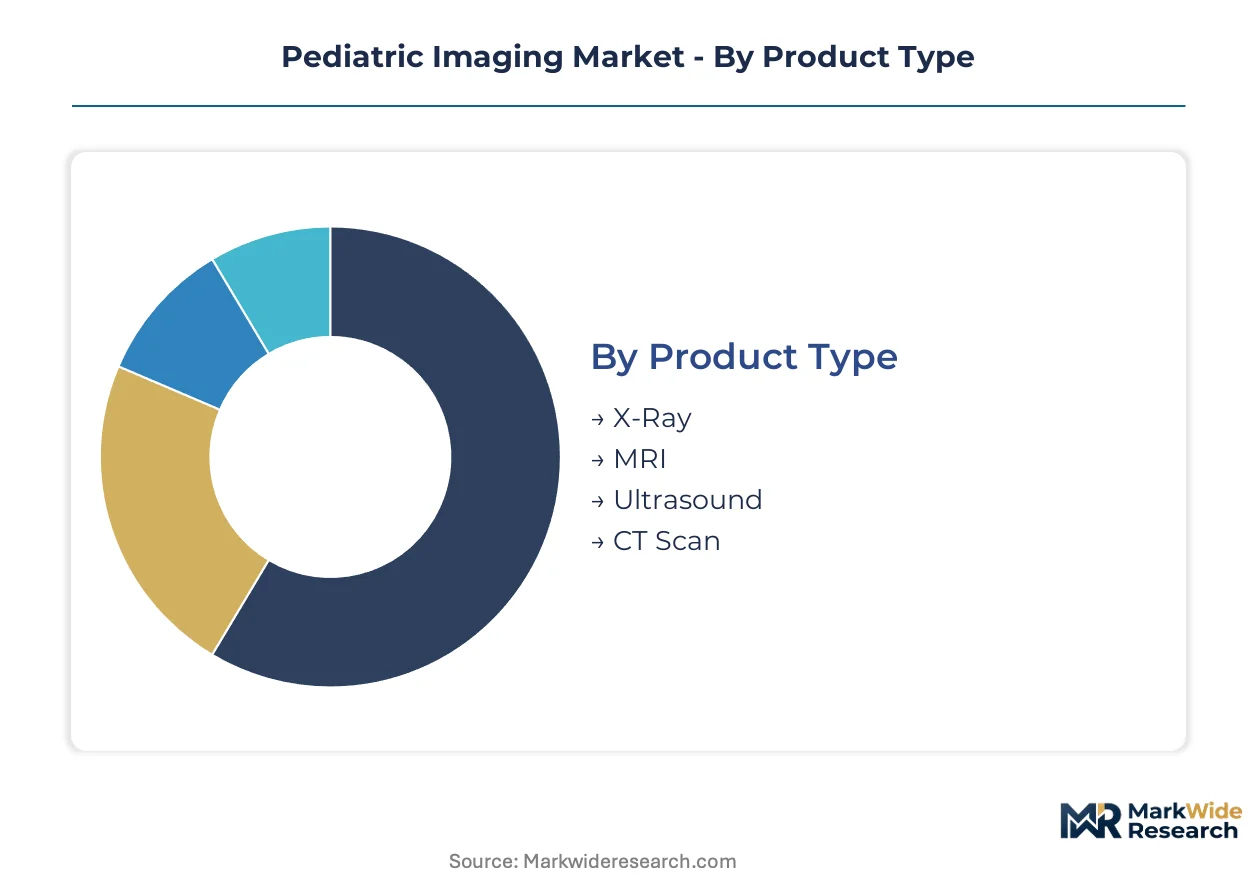
Pediatric imaging segmentation reflects divergent regulatory pathways and reimbursement frameworks across modalities. Equipment classification under FDA 510(k) versus EU MDR Article 52 creates tiered compliance burdens that reshape vendor portfolio priorities and hospital procurement hierarchies.
Product Type:
FDA ALARA guidance and EU MDR device classifications impose dose-limitation requirements that fragment equipment approval timelines across radiation-emitting and non-ionizing modalities.
- X-Ray:Digital radiography systems with pediatric-specific exposure protocols dominate outpatient screening volumes. Demand clusters at US pediatric hospitals prioritizing FDA-compliant low-dose architectures for skeletal surveys and chest imaging.
- MRI:High-field systems with specialized neonatal coils enable preterm brain development assessment without ionizing radiation. German university medical centers are pulling high-field upgrades into academic procurement cycles for neurology protocols.
- Ultrasound:Portable systems with cranial and abdominal transducers serve neonatal intensive care units at the point of care.
- CT Scan:Photon-counting detector technology is displacing energy-integrating architectures in pediatric protocols at academic centers.
Established volume favors X-Ray; emerging adoption favors MRI.
Technology:
Cost tier differentiation separates premium reconstruction algorithms from baseline acquisition systems, with AI-assisted platforms commanding procurement preference at consolidated health systems.
- 3D Imaging:Volumetric reconstruction platforms enable pre-surgical orthopedic planning for complex skeletal deformities. Penetration is climbing the fastest in pediatric surgery departments previously limited to 2D radiography.
- Contrast Agents:Gadolinium-based and iodinated formulations require EMA pediatric investigation plans for drug-device combination approvals. Documentation burdens complicate protocol standardization across EU territories.
- Digital Radiography:Flat-panel detectors with pediatric exposure indexing occupy the mature volume tier across outpatient facilities.
- Fluoroscopy:Pulsed acquisition modes with last-image-hold functionality reduce dose in interventional procedures.
Margin concentration sits with contrast-enhanced protocols; throughput scaling favors digital radiography deployment.
End User:
Customer type determines service intensity and capital deployment cycles, with academic centers driving technology adoption and community facilities optimizing asset utilization.
- Pediatric Hospitals:Comprehensive imaging departments with dedicated sedation protocols and fellowship-trained radiologists. US consolidated health systems in the Northeast and Midwest are unbundling equipment acquisition from service contracts.
- Diagnostic Centers:Focused outpatient facilities with high-throughput digital radiography and ultrasound capabilities.
- Outpatient Facilities:Limited modality portfolios serving routine screening and follow-up imaging.
- Research Institutions:Advanced MRI and CT platforms supporting clinical trials and protocol development.
Procurement sophistication concentrates at pediatric hospitals; volume scaling favors diagnostic center networks.
Application:
Clinical indication drives modality selection and reimbursement intensity, with oncology and neurology commanding premium equipment configurations.
- Oncology:Contrast-enhanced MRI protocols for staging and treatment monitoring require specialized pediatric coils and sedation-compatible throughput. Margin pools concentrate at specialized academic centers with fellowship-trained interpretation capacity.
- Neurology:Advanced MRI sequences for preterm brain development assessment are penetrating German university medical centers. Neonatal cranial ultrasound maintains structural dominance for bedside screening.
- Orthopedics:3D volumetric visualization is gaining share fastest for complex skeletal deformity surgical planning.
- Cardiology:Echocardiography and cardiac MRI protocols for congenital anomaly assessment.
Revenue intensity favors oncology; technology refresh cycles favor neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate lowest price elasticity for high-field MRI systems, while procurement committees in India prioritize portable ultrasound units that bypass capital-intensive radiology infrastructure.
United States
Pediatric hospitals in the Northeast and Midwest are unbundling equipment acquisition from multi-year service contracts. FDA ALARA guidance is compressing procurement timelines for low-dose radiation architectures. Boston and Philadelphia academic medical centers are pulling photon-counting CT systems into pediatric oncology staging protocols.
Germany
University medical centers in Bavaria and North Rhine-Westphalia are integrating advanced MRI sequences for preterm brain development assessment. EU MDR Article 52 pediatric-specific indication requirements are extending technical documentation obligations for imaging equipment manufacturers. Heidelberg and Munich clusters are driving high-field system upgrades for neonatal neurology protocols.
India
Neonatal intensive care units in Maharashtra and Karnataka are adopting portable cranial ultrasound systems for bedside screening. The country's national pharmaceutical regulator conditions drug-device combination approvals where contrast agents accompany imaging procedures. Mumbai and Bangalore medical device distributors are expanding point-of-care ultrasound networks to bypass radiology department bottlenecks.
Japan
Academic centers in the Kanto region are prioritizing AI-assisted scan-time reduction algorithms for uncooperative young patients. METI standards for medical device software are shaping AI-based image reconstruction validation requirements. Tokyo and Osaka pediatric specialty networks are consolidating procurement through dedicated biomedical engineering capabilities.
China
Provincial hospital networks in the Yangtze River Delta are expanding digital radiography deployment for routine pediatric screening. NMPA device classification for pediatric-specific indications is creating tiered compliance burdens that reshape vendor portfolio priorities. Shanghai and Hangzhou manufacturing clusters are localizing production of flat-panel detectors with pediatric exposure indexing.
Pediatric Imaging Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with consolidated health systems in developed markets favoring premium-tier vendors while emerging economy procurement gravitates toward scale-driven manufacturers. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with full-modality portfolios, specialized imaging equipment manufacturers with coil-level customization capabilities, and electronics conglomerates leveraging semiconductor expertise for detector innovation. Dominant competitive moves include strategic partnerships for AI algorithm validation and geographic expansion through localized manufacturing joint ventures.
Among diversified medical technology conglomerates, GE Healthcare and Siemens Healthineers exemplify archetypes anchored in magnet architecture development and ecosystem platform strategies respectively. Canon Medical Systems occupies a position within the specialized imaging equipment tier, representing vendors differentiating through reconstruction algorithm capabilities. These three companies collectively illustrate how procurement preference hierarchies at major pediatric hospital networks are concentrating around vendors with documented pediatric exposure reductions and validated AI-assisted protocols.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Samsung Electronics |
| Hitachi Ltd. |
| Agfa-Gevaert Group |
| Carestream Health |
| Others |
Cost & Logistics Intelligence
Ninety-day magnet fabrication lead times for high-field MRI systems concentrate pricing power with helium-secured manufacturers, while pediatric coil specialization fragments production scale economics across tiered equipment categories. Procurement committees at consolidated US health systems exploit this asymmetry by unbundling capital acquisition from multi-year service contracts.
Pricing Analysis
After-sales service revenue tiers—spanning parts replacement, preventive maintenance, and extended warranty contracts—generate lifetime value multiples exceeding initial equipment margins. Pricing stratifies across premium, standard, and economy tiers based on magnet field strength and AI reconstruction certification levels. Cost compression in the standard tier intensifies as Chinese flat-panel detector manufacturers expand pediatric exposure indexing capabilities. Academic medical centers in Germany and the United States demonstrate lowest price sensitivity, while diagnostic center networks in emerging economies prioritize capital expenditure minimization over feature depth.
Supply Chain Analysis
Strategic stockpiling of helium reserves distinguishes tier-one MRI manufacturers from competitors exposed to spot-market volatility. Magnet production concentrates in Germany, Japan, and the United States, drawing from concentrated geological helium deposits in Qatar, Algeria, and Russia. Superconducting wire and rare-earth permanent magnet materials anchor component dependencies. Single-source vulnerability in helium refining infrastructure poses structural risk. Distribution runs through authorized dealer networks with biomedical engineering certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric imaging constitutes a defensive-moat market where regulatory entrenchment—manifest in FDA 510(k) pediatric-specific indication requirements and EU MDR Article 52 technical documentation obligations—erects multi-year barriers to competitive replication.
For Market Incumbents: Consolidate coil-level customization capabilities through captive supply of anatomically specific receiver arrays, insulating against emerging specialized manufacturers from South Korea and China. Deepen hospital system partnerships in the Northeast and Midwest United States where procurement disintermediation separates capital from service decisions. Prioritize AI-assisted scan-time reduction R&D to defend against software-centric entrants targeting sedation reduction protocols. For New Entrants and Emerging Players: Differentiate on point-of-care ultrasound portability for neonatal intensive care units in India and Southeast Asia, where radiology department bottlenecks create addressable white space. Target portable cranial and abdominal transducer segments with bedside screening value propositions. Pursue distributor-led go-to-market models that bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking portfolio rationalization, particularly imaging divisions with pediatric-specific coil libraries but limited AI reconstruction validation. Long-term viability hinges on regulatory pathway execution rather than technological differentiation alone. Watch IEC working group publication timelines for AI-based image reconstruction standards as inflection indicators for procurement preference hierarchies.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Validation Partnership | IEC working group standards determine vendor access to major pediatric hospital network procurement frameworks. |
| Pediatric Coil Library Acquisition | Anatomically specific receiver arrays command premium positioning in neonatal neurology protocol competitions. |
| Helium Supply Security Agreement | Long-term offtake contracts with Qatari and Algerian refiners insulate against spot price volatility. |
| Point-of-Care Ultrasound Distribution Expansion | Maharashtra and Karnataka medical device distributors bypass radiology bottlenecks in neonatal intensive care. |
| Dual-Territory Regulatory Submission | Parallel FDA 510(k) and EU MDR Article 52 pathways compress commercialization cycles for redesigned platforms. |
Research Approach
A spread of perspectives from pediatric radiologists, hospital procurement committee chairs, biomedical engineering directors, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders were cross-validated against secondary sources including FDA 510(k) filings, EMA pediatric investigation plans, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up equipment shipment estimates and top-down healthcare expenditure allocations were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled span modality type, magnet field strength tier, end-user facility category, and regional regulatory cluster across the projection horizon. Compound annual growth rate derivation incorporated procedure volume elasticity to reimbursement rate changes, technology replacement cycle assumptions for digital radiography platforms, and penetration curve modeling for photon-counting CT detectors. Helium price trajectory scenarios and AI reconstruction algorithm adoption curves served as pediatric imaging-specific forecast inputs.
Forecasts assume regulatory continuity in FDA ALARA guidance and EU MDR pediatric device classification regimes; material policy shifts would require re-modeling of equipment approval timeline assumptions and compliance cost burdens. Revision becomes warranted when photon-counting CT detector cost curves cross thresholds enabling community hospital procurement penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market